GUD: delivering results in a tough environment

Despite the weird name, GUD Holdings (ASX:GUD) has been a stalwart of the ASX for almost 60 years. That sort of longevity implies it must be doing something right. It has undergone a lot of change over the years, buying and selling businesses. Revenue has almost doubled over the last two years as a result of acquisitions.
GUD is now primarily an automotive parts and accessories business with 89% of revenues in the most recent interim results coming from this segment. The balance comes from the water segment.
The water business consists of Davey Water Products which supplies water-related products for farming and irrigation, home and garden applications, pools and spas, commercial and water treatment purposes. Revenue declined a bit in this segment as export sales were severely impacted by destocking activities, especially in Europe. Margins are also quite low for this part of the business at sub 5%.
The automotive sector consists of a host of different brands and products. It includes APG Group which was acquired in January 2022 and accounted for 27% of total revenue in the most recent half.

Source: GUD, H1 FY23 Financial Results, 15/2/23
GUD manufactures a lot of its own products as well as being a distributor.
The fortunes of GUD are tied closely to those of the car industry. New car sales have rebounded since the depths of the pandemic, but are still 9% below their highs in 2017 and 7% below the 5 year pre-Covid average.
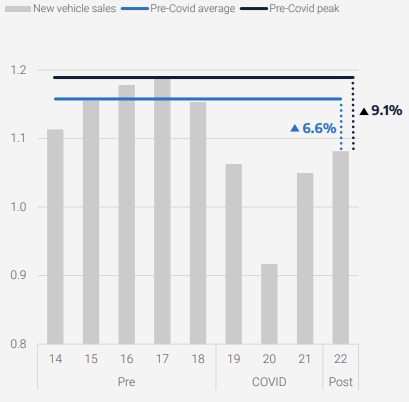
Source: GUD, H1 FY23 Financial Results, 15/2/23
In calendar year 2022, the overall market for new cars was up 3.0%, but the top 20 models for GUD sales rose by 4.7%. GUD’s products are more targeted at pickups (utes) and SUVs. Sales of particular vehicles have been very volatile as supply has fluctuated wildly. Wait times have pushed out to as much as 250 days. These trends have a flow on effect for GUD, as people often kit out their 4wds with a bunch of cool accessories when they pick them up from the showroom floor.
But GUD is not entirely at the mercy of new car sales. In fact, 80% of the automotive revenue (excluding APG) comes from non-discretionary spend, that is replacement parts for wear and tear. This side of the business benefits as the average age of cars on the road increases, which it has been and is forecasted to keep growing.

Source: GUD, H1 FY23 Financial Results, 15/2/23
Investors may be concerned that as cars steadily march away from internal combustion engines (ICE), that demand for GUD’s products will fall. That is certainly the case for some products, but according to the company, 69% of GUD’s automotive revenue profile is not dependent on ICE vehicles.

Source: GUD, H1 FY23 Financial Results, 15/2/23
GUD’s balance sheet has been impacted by these acquisitions. They are carrying a fair bit of debt although they are trying to manage it down with a target of getting net debt down to two times underlying EBITDA by June. At December it was 2.5 times.
This has led to the Bankruptcy risk (Z1 - score) being in the Distress zone although it has improved following the latest result and is getting close to the cautious zone. The debt maturity profile is reasonably balanced with maturities extending out twelve years, however there is $137 million in debt maturing in 2024 and that will need to be refinanced. That should not be a problem, however it is likely to be refinanced at a higher rate given the current interest rate environment.
The acquisitions have also been partially funded by equity capital. Shares on issue have increased from 90 million to 129 million over the last few years. This will often result in retail investors having their shareholding diluted.
The most recent interim results were reported on 15 February and were very well received by the market. The share price has jumped 23% since. EPS is now forecast to almost double to 81c in FY23 followed by further growth of 11% in FY24. EPS fell markedly in 2022.
Reviewing the StockRank we can see that it has improved from 81 to 84 since reporting. This has largely been driven by the Quality Rank which jumped from 67 to 90. A significant contributor to this was the Health Trend score which went from 3 to 5. Operating margins, return on capital employed and return on equity all also improved.

The other two components of the StockRank declined. Value fell from 72 to 68. This is largely on the back of the sharp share price rise making the value metrics look a bit less attractive. The Momentum rank also fell. Remember that rankings are a relative rank relative to all the other companies listed on the market. Therefore the movements in the rankings do not only reflect the fundamentals of the business in question, but also movements across other companies.
Trading in January and February has been quite strong across each area of the business. There are still capacity constraints due to ongoing tight supply of new vehicles, but the expectation is that this will gradually ease.
Overall the business seems to be well managed and continuing to grow despite a challenging external environment.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?