GWA: A high ranking income stock

You may not be familiar with the company GWA (ASX:GWA), but you probably make use of their products. They make toilets, sinks, showers, tubs and other water products for the bathroom, kitchen and laundry. They are behind such brands as Caroma, Methven, Clark and Dorf. They design their own products and sell them to both residential and commercial customers. The products are manufactured by suppliers in Asia and Europe.
Source: GWA, FY23 Results presentation, 14/8/23
Residential sales are largely driven by new builds and renovations and likewise for commercial. They generate approximately 60% of their sales revenue from the renovations and replacement segment in Australia. Sales are also impacted by the decisions of merchants to increase or decrease their stock of GWA products. About 60% of their revenue comes from their four largest customers, with the single largest customer accounting for 24% of revenue.
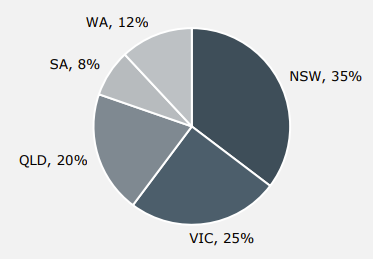
Revenue is predominantly derived from Australia at 82%. 10% comes from New Zealand and a further 8% from the UK. Within Australia, NSW is the largest market at 35%, followed by Victoria at 25% and Queensland at 20%.
Source: GWA, FY23 Results presentation, 14/8/23
In FY23 revenue declined by 1.6% impacted by the general economic slowdown with rising interest rates and inflation causing people to think twice when it comes to renovations and look for value options where possible. All three markets registered declines, with the largest declines coming from New Zealand due to the recession there. Some of the declines in volumes sold were able to be offset by increased prices charged.
You need to dig into the accounting a bit to understand what happened with profits. Reading the presentations from management, they state that FY23 normalised profits declined about 6%. However, statutory profit increased 23%. The reason was a 15m pre tax significant item in FY22. $10m related to a project to upgrade ERP/CRM software and $5m to the closure of the China sales operations. I am sceptical about companies treating software projects as an abnormal item. It is a normal part of doing business. In my view, it should either be capitalised as an asset or put through as a normal expense.
Importantly, the FY23 accounts had minimal significant items and therefore the healthy operating margin of 17% is a true reflection of the business performance. These solid margins have contributed to a Quality Score of 94. Return on equity is also consistently in the low to mid teens.
The net gearing ratio (including leases) is 55%. In FY23 they reduced their debt with improved cash flow. Cash conversion, operating cash compared to EBITDA, also improved, in part due to the reduction in working capital, ie. collecting more of the accounts receivable and lowering inventory levels. This reversed the FY22 situation where cash flow was low due to a build up of inventory. Over the long-term, cash generation has been strong. Free cash flow per share has grown at a CAGR of 22% over the last five years.
For investors who place a high value on deriving income from their investments, GWA is worthy of consideration. They are currently trading on a 12 month forecast rolling dividend yield of 6.9% and the dividends are fully franked. They reduced the dividend from 15c in FY22 to 13c in FY23. Analysts are forecasting 13.2c in FY24. They tend to pay out 75% - 85% of earnings as dividends. Importantly, the dividends are backed up by solid cash flow and earnings and a high Quality score, which provides a higher level of confidence that the dividends will be able to be maintained.
The high dividend yield is also contributing to the high Value Score of 87. The share price is trading at a forecast PE ratio of 11.3 and the other valuation metrics are trading at relatively cheap levels. Just prior to the start of the pandemic, shares were trading at $4 and the reported EPS has little changed since then. Since the announcement of the latest full year results in mid August, the share price has been very volatile, first spiking higher to $2.22 then sliding to $1.63 two months later, before rebounding to the current level just shy of $2.
Analysts have recently upgraded their earnings expectations, especially for FY25. This has led to a sharp rebound in the share price over the last three weeks, both of which have contributed to the Momentum Rank leaping 13 points to 94.

The outlook outlined at the results presentation in August was mixed, but with some positive signs. The residential renovations market was expected to remain subdued, with BIS Oxford Economics predicting the market would slide by 8 per cent over the year.
On the positive side, demand is expected to increase for new builds and repair and renovations for commercial health and aged care facilities. There is a solid pipeline of residential detached housing and increased activity in multi residential, social and affordable housing and build to rent categories. This outlook has improved modestly from the descriptions provided at the half year results in February.
Both state and federal governments have made it very clear that they wish to increase the stock of affordable housing. There is significant undersupply in the rental market, which is putting upward pressure on rents. Market forces should see this lead to more investment in housing, especially high-density residential, which could lead to another construction boom and demand for GWA’s products. GWA have also adjusted their product mix to include cheaper tapware and shower products which should have more appeal to the affordable housing market.
The strong scores for quality, value and momentum lead to an overall Stock Rank for GWA of 99, placing it in the upper echelons of stocks on the ASX. It has been a steady performer over time, riding the cycles and adjusting the business as required. It is not likely to be a high growth company, but if purchased at the right price, steady growth in earnings and dividends could lead to a profitable investment.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?