How does Alliance Aviation stack up without Qantas?

Alliance Aviation Services (ASX:AQZ) is an airline business with a very different business model to the other commercial carriers. They own and operate a fleet of aircraft, but only 3.4% of their revenue comes from operating regular public transport flights. Their largest source of revenue is contract revenue. This is typically in the form of contracts with mining companies where they fly mining staff from the major ports to remote mining locations. These are known as fly-in-fly-out (FIFO) workers. Their strategic goal is to be a wholesaler of aircraft capacity and therefore they are continuing to reduce their regular public transport flights.
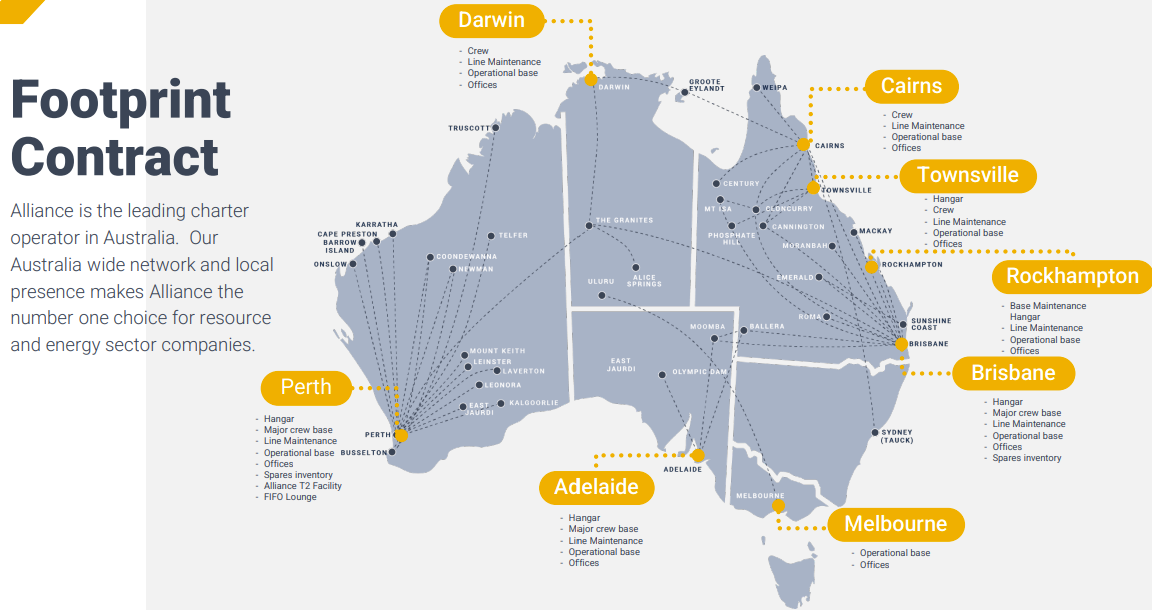
Source: Alliance Aviation Services Limited, “Results Presentation 1H FY2023”, 8/2/2023
Their second largest source of revenue is through wet lease agreements. This is where Alliance own the aircraft but lease them to Qantas Airways (ASX:QAN) and Virgin. In addition to providing aircraft capacity, they also provide the staff, and take care of all aspects of servicing the aircraft. Revenue from this segment increased by 316% in the most recent half with six new aircraft being deployed.
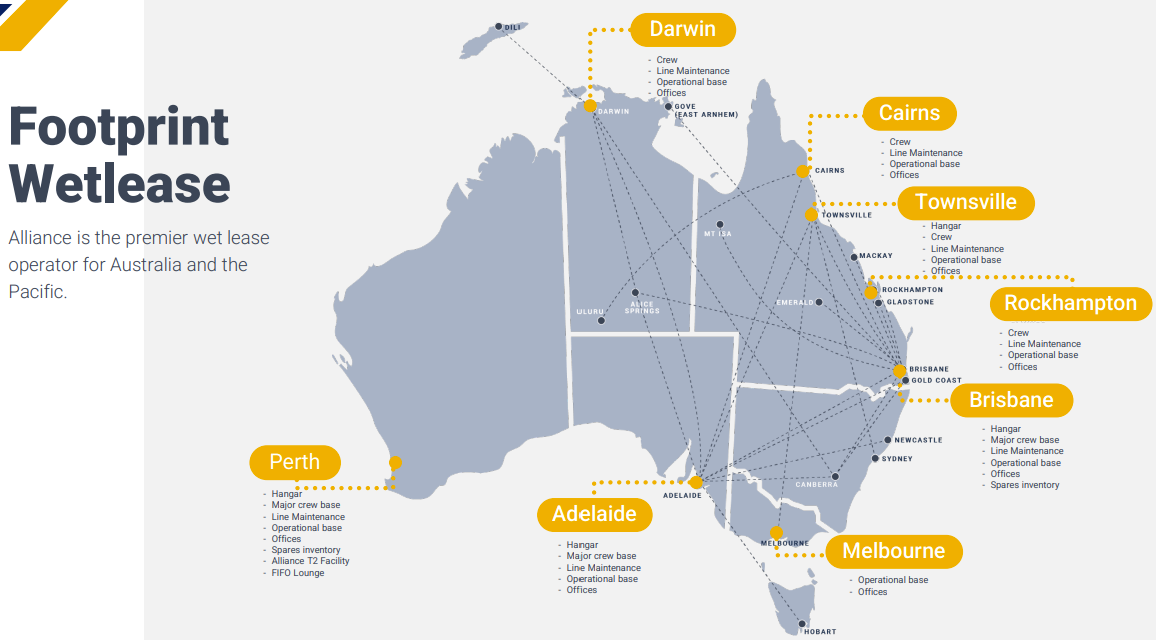
Source: Alliance Aviation Services Limited, “Results Presentation 1H FY2023”, 8/2/2023
In addition to regular public transport flights, they also derive a small amount of revenue from two other segments, but these are declining. They are charter flights and aviation services.
Total revenue for Alliance has been rising strongly since 2017 with a CAGR of 13.1%. This accelerated rapidly in the first half of 2023 with growth of 40% largely driven by the expansion of the wet leasing component of the business. Revenue for the whole of FY23 is forecasted to grow by 42% with further growth forecast for FY24. (Note: These forecasts are the average of the four market analysts who cover the stock.)
Profits have generally been rising but fell in 2022. Underlying profits fell due to the challenges associated with COVID. The statutory profit actually fell into a loss, driven down by a $12.1 million write down of the older Fokker 50 fleet which are being retired. Profits are forecast to rebound strongly in FY23.
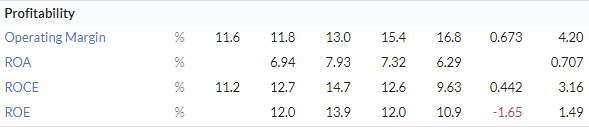
Alliance ranks highly in terms of Quality with a score of 89. This is supported by a good Health Trend score of 7/9 but dragged down a bit by lower Return on Capital and Return on Equity in the last year. However when looked at over a longer period, return rates have been quite good. The same is true of operating margins. (Note: the final column in the table below is TTM)
The Quality score is also hampered a bit by the fairly high level of debt which leads to an increase in the Bankruptcy Risk although certainly not to alarming levels. It is just in the Cautious zone.
The increasing debt levels have been due to the replacement and growth of their aircraft fleet. This has been driven by building a fleet of Embraer E190 jet aircraft.
An additional expansion of this fleet was announced in February. They are purchasing an additional 30 Embraer E190 aircraft that are currently operated by a US airline. The acquisition of the aircraft will take place gradually over two years starting in September.
This expanding fleet supports the extension of the wet leasing agreement with Qantas. In February they announced the number of aircraft on wet lease for use within the Qantas network would increase from 18 to 30.
They have also invested in building a hangar for a maintenance centre in Rockhampton.
Turning to the valuation, the Value score of 63 is being dragged down by the lack of any dividends for the last few years. The negative free cash flow, due to the expenditure on fleet expansion, is also hurting the Value score. However looking at the forward PE ratio it is quite reasonable at 9.8.
When looking at the operations of the business on a stand alone basis they appear to be solid. However an analysis of Alliance is not complete without considering the actions of Qantas.
Over three years ago Qantas acquired a 19.9% stake in Alliance. Then in May 2022 they announced that they had reached an agreement to acquire the remaining 80% of the business that they did not already own. Naturally this sparked the interest of competition watchdog the ACCC given the relatively small number of players in the Australian aviation industry and especially the FIFO charter segment. After 12 months of consideration the ACCC have decided to oppose the takeover.
The ACCC stated: “Combining such an important player with Australia’s largest airline, Qantas, would be likely to substantially lessen competition and is something we oppose,” Ms Cass-Gottlieb said. The ACCC carefully considered the level of competition provided by other airlines such as Virgin Australia and National Jet Express (which was recently purchased by Rex), and other smaller market participants. The ACCC found that it is unlikely a new or existing airline could expand quickly to a scale that would address the loss of competition resulting from the proposed acquisition. “Qantas will face limited competition if allowed to acquire Alliance because most other airlines lack the right aircraft, fleet size, or capabilities needed to compete effectively,” Ms Cass-Gottlieb said. (ACCC, Media Release: ACCC opposes Qantas’ acquisition of Alliance, 20/4/2023)
Qantas is now seeking further information and are yet to throw in the towel. This development has caused the share price to fall 15% in the last month. If they are ultimately unsuccessful the 20% stake they currently hold may create an overhang on the stock price as people wait to see if Qantas decide to sell. There will be some uncertainty surrounding the stock until this issue is fully resolved. Qantas is also Alliance’s largest customer, but that shouldn’t be impacted by the takeover outcome.
Additional commentary from the ACCC reinforces the view that Alliance is a strong business in its own right which is reflected in the high Quality score.
The ACCC also received considerable feedback that Alliance is strongly valued by customers as a particularly vigorous and effective competitor. “For many customers, Alliance is the preferred supplier due to its large fleet capacity, customer-centric approach and high-quality service offerings, including having the highest on-time-performance in the industry and demonstrated flexibility and willingness to meet customer needs,” Ms Cass-Gottlieb said. (ACCC, Media Release: ACCC opposes Qantas’ acquisition of Alliance, 20/4/2023)
Any decision regarding an investment in AQZ should be made based on the assumption that they are a stand alone company. As has been illustrated, they are a well run company with a firm foothold in their market. There are risks associated with their expansion plans, but if well executed they should lead to increased profitability. Whilst not a household name, given they do not sell seats to the general public, they are actually one of Australia’s most significant airlines with a fleet approaching 100 aircraft.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
Buffett says never buy an airline, then he buys them anyway.