How to combat low interest rates with high yield dividend shares

The UK’s decision to leave the EU has unsettled the UK economy and efforts to boost growth could be more bad news for the country’s weary savers. With interest rates at a record low of 0.5%, further cuts seemed out of the question just a few months ago. But a wave of uncertainty means that cuts could indeed be coming if the economy takes a tumble. It’s one reason why dividend shares - as an alternative to meagre returns on cash - could be worth a closer look.
Effective dividend strategies
We’ve been keeping a close eye on income strategies since the referendum, and it’s clear that some of them have held up well. That said, there have been concerns about low levels of dividend cover in some areas.
Of all the investing strategies tracked by Stockopedia, Dividend Dogs of the FTSE has been one of the best performers in 2016. It had a difficult time in 2015 because it was exposed to some badly performing sectors. But this year the same strategy of buying the 10 highest yielding stocks in the FTSE 100 has returned 30% - before dividends.
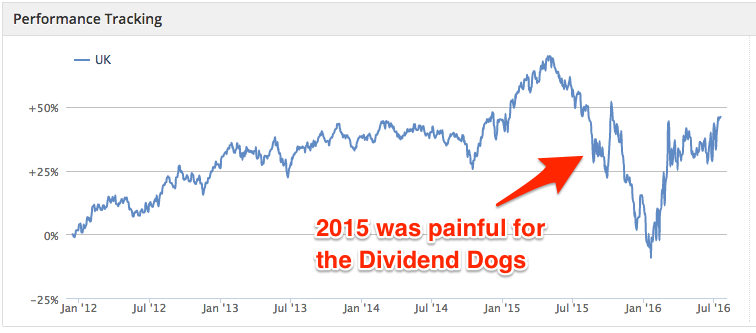
Part of the reason for that performance is that the sectors that dragged it down in 2015 have done well this year. Some of those include mining, oil & gas and financials. A handful of blue chips in those sectors have bounced back, and held up well through the Brexit mayhem.
Part of the philosophy behind Dividend Dogs is that high yield is a proxy for relative cheapness (yield is calculated by dividing the dividend per share by the share price, multiplied by 100). As a share price falls, its yield will rise, all other factors being equal. So this strategy does have an inbuilt bias towards firms that might be out of favour or are near the bottom of the business cycle.
Even so, given that FTSE 100 stocks are generally well financed businesses with a keen interest in maintaining their dividends, the strategy bets that the dividends will remain intact.
Improving a high yield dividend strategy
While it’s great to see the Dividend Dogs strategy recover this year, it’s clearly prone to sharp drawdowns. One criticism of the strategy is that it lacks safety nets that might protect it from this kind of volatility and, more crucially, potential dividend cuts.
In fact, when you look at a variation on the Dogs rules, with the Forecast Dividend Dogs strategy (which relies on forecast yields), you can see a similar problem. Some of the highest forecast yields this year have been found in housebuilders. Economic wobbles have dented prices in these stocks and the strategy has been pummelled by holding positions in companies like Taylor Wimpey and Barratt Developments.
So is there a safer approach to using a high yield strategy like this?
One option is to pair above-average yields with other safety measures that might point to stronger, safer dividends, such as these:
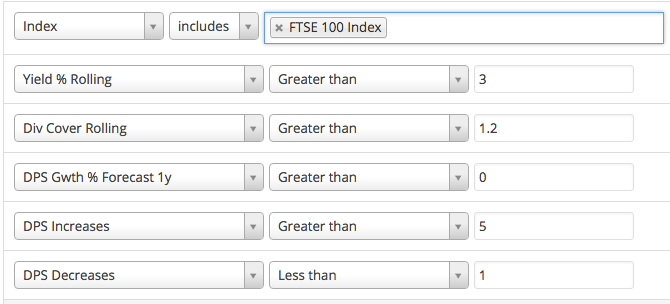
Key features of these rules are that they look for a reasonable track record of dividend growth. This can be a pointer to companies where the dividend policy is well managed. In other words, it’s looking for a consistently positive trend in dividend growth, with dividends that are covered by earnings and are forecast to grow in the coming year. (Stockopedia Members can see the screen here).
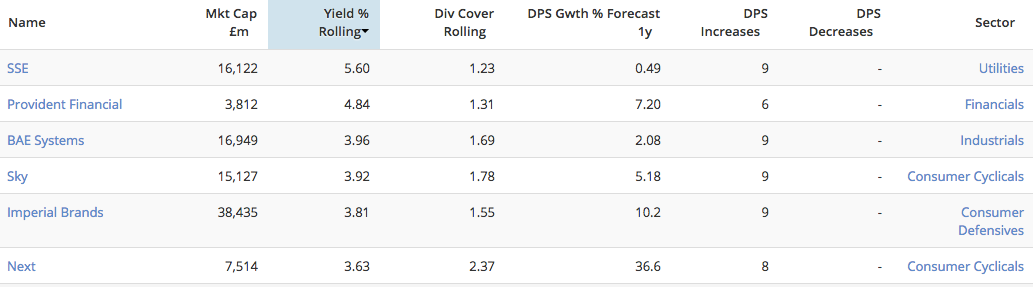
What this does is throw a new light on the high yield stocks of the FTSE 100. The current median yield of the 11 companies that pass these rules is 3.6%, but there’s more sector diversification in the list than the regular Dividend Dogs strategy. You can get an idea of that from this snapshot:
Dividend safety
So in a climate of low - and possibly falling - interest rates, those savers and investors looking for reasonable returns may well consider their options with dividend shares. The strong performance of defensive and commodity-focused sectors since the referendum has been a real boost to income strategies like Dividend Dogs. But it’s a strategy that is prone to too much sector concentration - and it has paid the price in the past. Introducing a few safety measures, particularly with some dividend growth rules, could be a useful way of giving a successful high yield strategy an extra level of safety.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
6 comments
To Ben
...Of all the investing strategies tracked by Stockopedia, Dividend Dogs of the FTSE has been one of the best performers in 2016. It had a difficult time in 2015 because it was exposed to some badly performing sectors. But this year the same strategy of buying the 10 highest yielding stocks in the FTSE 100 has returned 30% - before dividends...
This is the O'Higgins mech strat which can't be judged on one year as it is a much longer term approach and will inevitably have bum years as well as better ones. Although often misunderstood as such, it is not actually an income strat but uses yield only as the selection criterion. The idea though is to create gains over time via capital growth and reinvested dividends, not to withdraw dividends to derive an income.
Back in the earliest days of the UK Motley Fool in the late nineties, I wrote the regular weekly reviews of a five share UK market version of this, run officially by the Fool, which we named Beating the Footsie, (BTF).
Unfortunately for us, we had been fooled by backtesting, a process in which, since then, I have never had any faith as a method of demonstrating the efficacy of a strategy. Don't ever trust a scheme whose only proof is backtested results.
Mechs were all the rage then on the Fool, a fad which has since all but disappeared in popularity. Although I was the reviewer, I never really had much faith in the BTF scheme for certain lack of logic reasons, and during that period devised my own mech, the pyad26 (non backtested of course) which had much more investment logic though I haven't followed it for a very long time as mechs fell out of fashion.
After five years, which we felt adequately long to test the BTF, we gave up the whole lousy idea of BTF in disgust as a seriously losing proposition. Not only did it lose quite a bit over the five years but it was relatively volatile thoughout, thus adding higher risk to the losses. Wotaloadarubbish it was.
My final article on the subject in 2002 here:
http://news.fool.co.uk//workshop/2002/ws021009.htm?ref=mechanicalhome
How about preference shares, some of those pay high dividends?
Interesting. I changed Footsie to ASX, no giants however two ot of six have a score over 90
Hi stayhi that seems a very large holding in one stock even if your portfolio is huge! lol
I have held HSBA shares for years, (I currently hold just over 49,000), and have enjoyed good dividends. True, the unit price has nosedived over the last 2 years, but if you have no plans to sell, then this is a secondary issue. Now the price is rising, I may well purchase more.
I have held HSBA shares for years, (I currently hold just over 49,000), and have enjoyed good dividends. True, the unit price has nosedived over the last 2 years, but if you have no plans to sell, then this is a secondary issue. Now the price is rising, I may well purchase more.
Eh?
Without my making any comment on the merits of this share, but purely logically as a dividend player, shouldn't that be the other way round? That is, you should have purchased more when the price was falling.