How to invest like Jim Slater: Lessons from a shifting strategy

History is a funny thing. We tend to imagine that history books record facts and figures with scientific precision, as if the chronicles offer a photographic snapshot of the past. But the reality is quite different. Historians have to make do with archival scraps, odds and ends, and various leftovers from the years gone by. Some of the greatest thinkers—including Leo Tolstoy—have even argued that historical fiction is more truthful than non-fiction. Inevitably, historians miss important details.
Some characters are forgotten. Even if they shaped events, their names slip through the cracks and are lost to history. One of those names is Jim Slater. His obituary in the BBC said, ‘The name probably means nothing to anyone under the age of 50, but in the 1970s Jim Slater was a truly famous businessman.’ That line stuck with me. I remember my grandparents talking about the old days of Jim Slater, James Goldsmith and Tiny Rowland. When I became interested in investing, I asked my grandmother about Slater. Her face lit up, as if she was taken back in time. ‘Gosh’, she replied. ‘Now you’re talking!’ Her eyes gazed into the distance. ‘I wonder’, she said. ‘Is Jim Slater still alive?’
In 1977, Slater wrote his autobiography, Return to Go. The book is no longer in print and I bought it on Amazon for 1p. In 1992, Slater wrote an investment guide called The Zulu Principle. It was more successful than Return to Go, but it helps to read both books. One book can show you an investor’s style at a particular moment in time. Two books, written fifteen years apart, can reveal the lessons learned and the process behind developing a full investment philosophy…
Backtesting, the Old-Fashioned Way
Slater started investing around 1959, before the internet and before personal computers. The idea of backtesting an investment strategy was out of question, so Slater devised a clever workaround. He bought two years’ back issue of The Investors Chronicle and the Stock Exchange Gazette and reviewed the share recommendations. With the benefit of hindsight, Slater was able to identify traits that were present before periods of strong price performance. The process helped Slater separate genuinely good recommendations from tips that turned out to be duds.
Slater developed and refined his own investment philosophy. He described himself as an ‘earning situations’ specialist, but in many ways, he focused on turnarounds. In Return to Go, he said:
“I was looking for shares which, following a bad period, had a steadily rising earnings trend.”
Slater’s theory was that turnaround companies tended to stay undervalued because the market had become jaded after years of poor performance.
“Quite often after a period of losses it would take a long time for the stock market to forgive and forget, so the rating given to these companies was not high enough in relation to their recent earnings trend.”
Slater complemented this investment theory with a clear set of well-defined rules (see below). Slater listed these rules in 1963, writing an investment column in The Sunday Telegraph under the pseudonym of ‘Capitalist’. Rule 1 ensured the company was undervalued and generating enough cash to pay a dividend. Rules 2 and 3 focused on strong earnings growth, while Rules 5 and 7 ensured the company had a healthy balance sheet.
1. The dividend yield must be at least 4 per cent.
2. Equity earnings must have increased in at least four out of the last five years.
3. Equity earnings must have at least doubled over the last four years.
4. The latest Chairman’s statement must be optimistic.
5. The company must be in a reasonable liquid position.
6. The company must not be vulnerable to exceptional factors.
7. The shares must have a reasonable asset value.
8. The company should not be family controlled.
9. The shares should have votes.
Slater also applied criteria for the price-to-earnings (P/E) ratio. This was essentially a prototype GARP strategy (growth at a reasonable price).
“I was looking for shares with an above average earnings yield (the equivalent today would be a below-average price-earnings ratio) coupled with above-average growth prospects”
Slater ran a ‘ghost portfolio’ while writing his ‘Capitalist’ column. In Return to Go, he reflected on the results:
“The ‘Capitalist’ portfolio did appreciate in value by 68.9 per cent against a market average of only 3.6 per cent during the same period.”
Backtesting, the Modern Way
It’s been sixty-six years since Slater wrote his ‘Capitalist’ column. Today, we’re better equipped to simulate the performance, using data from 2015-25…
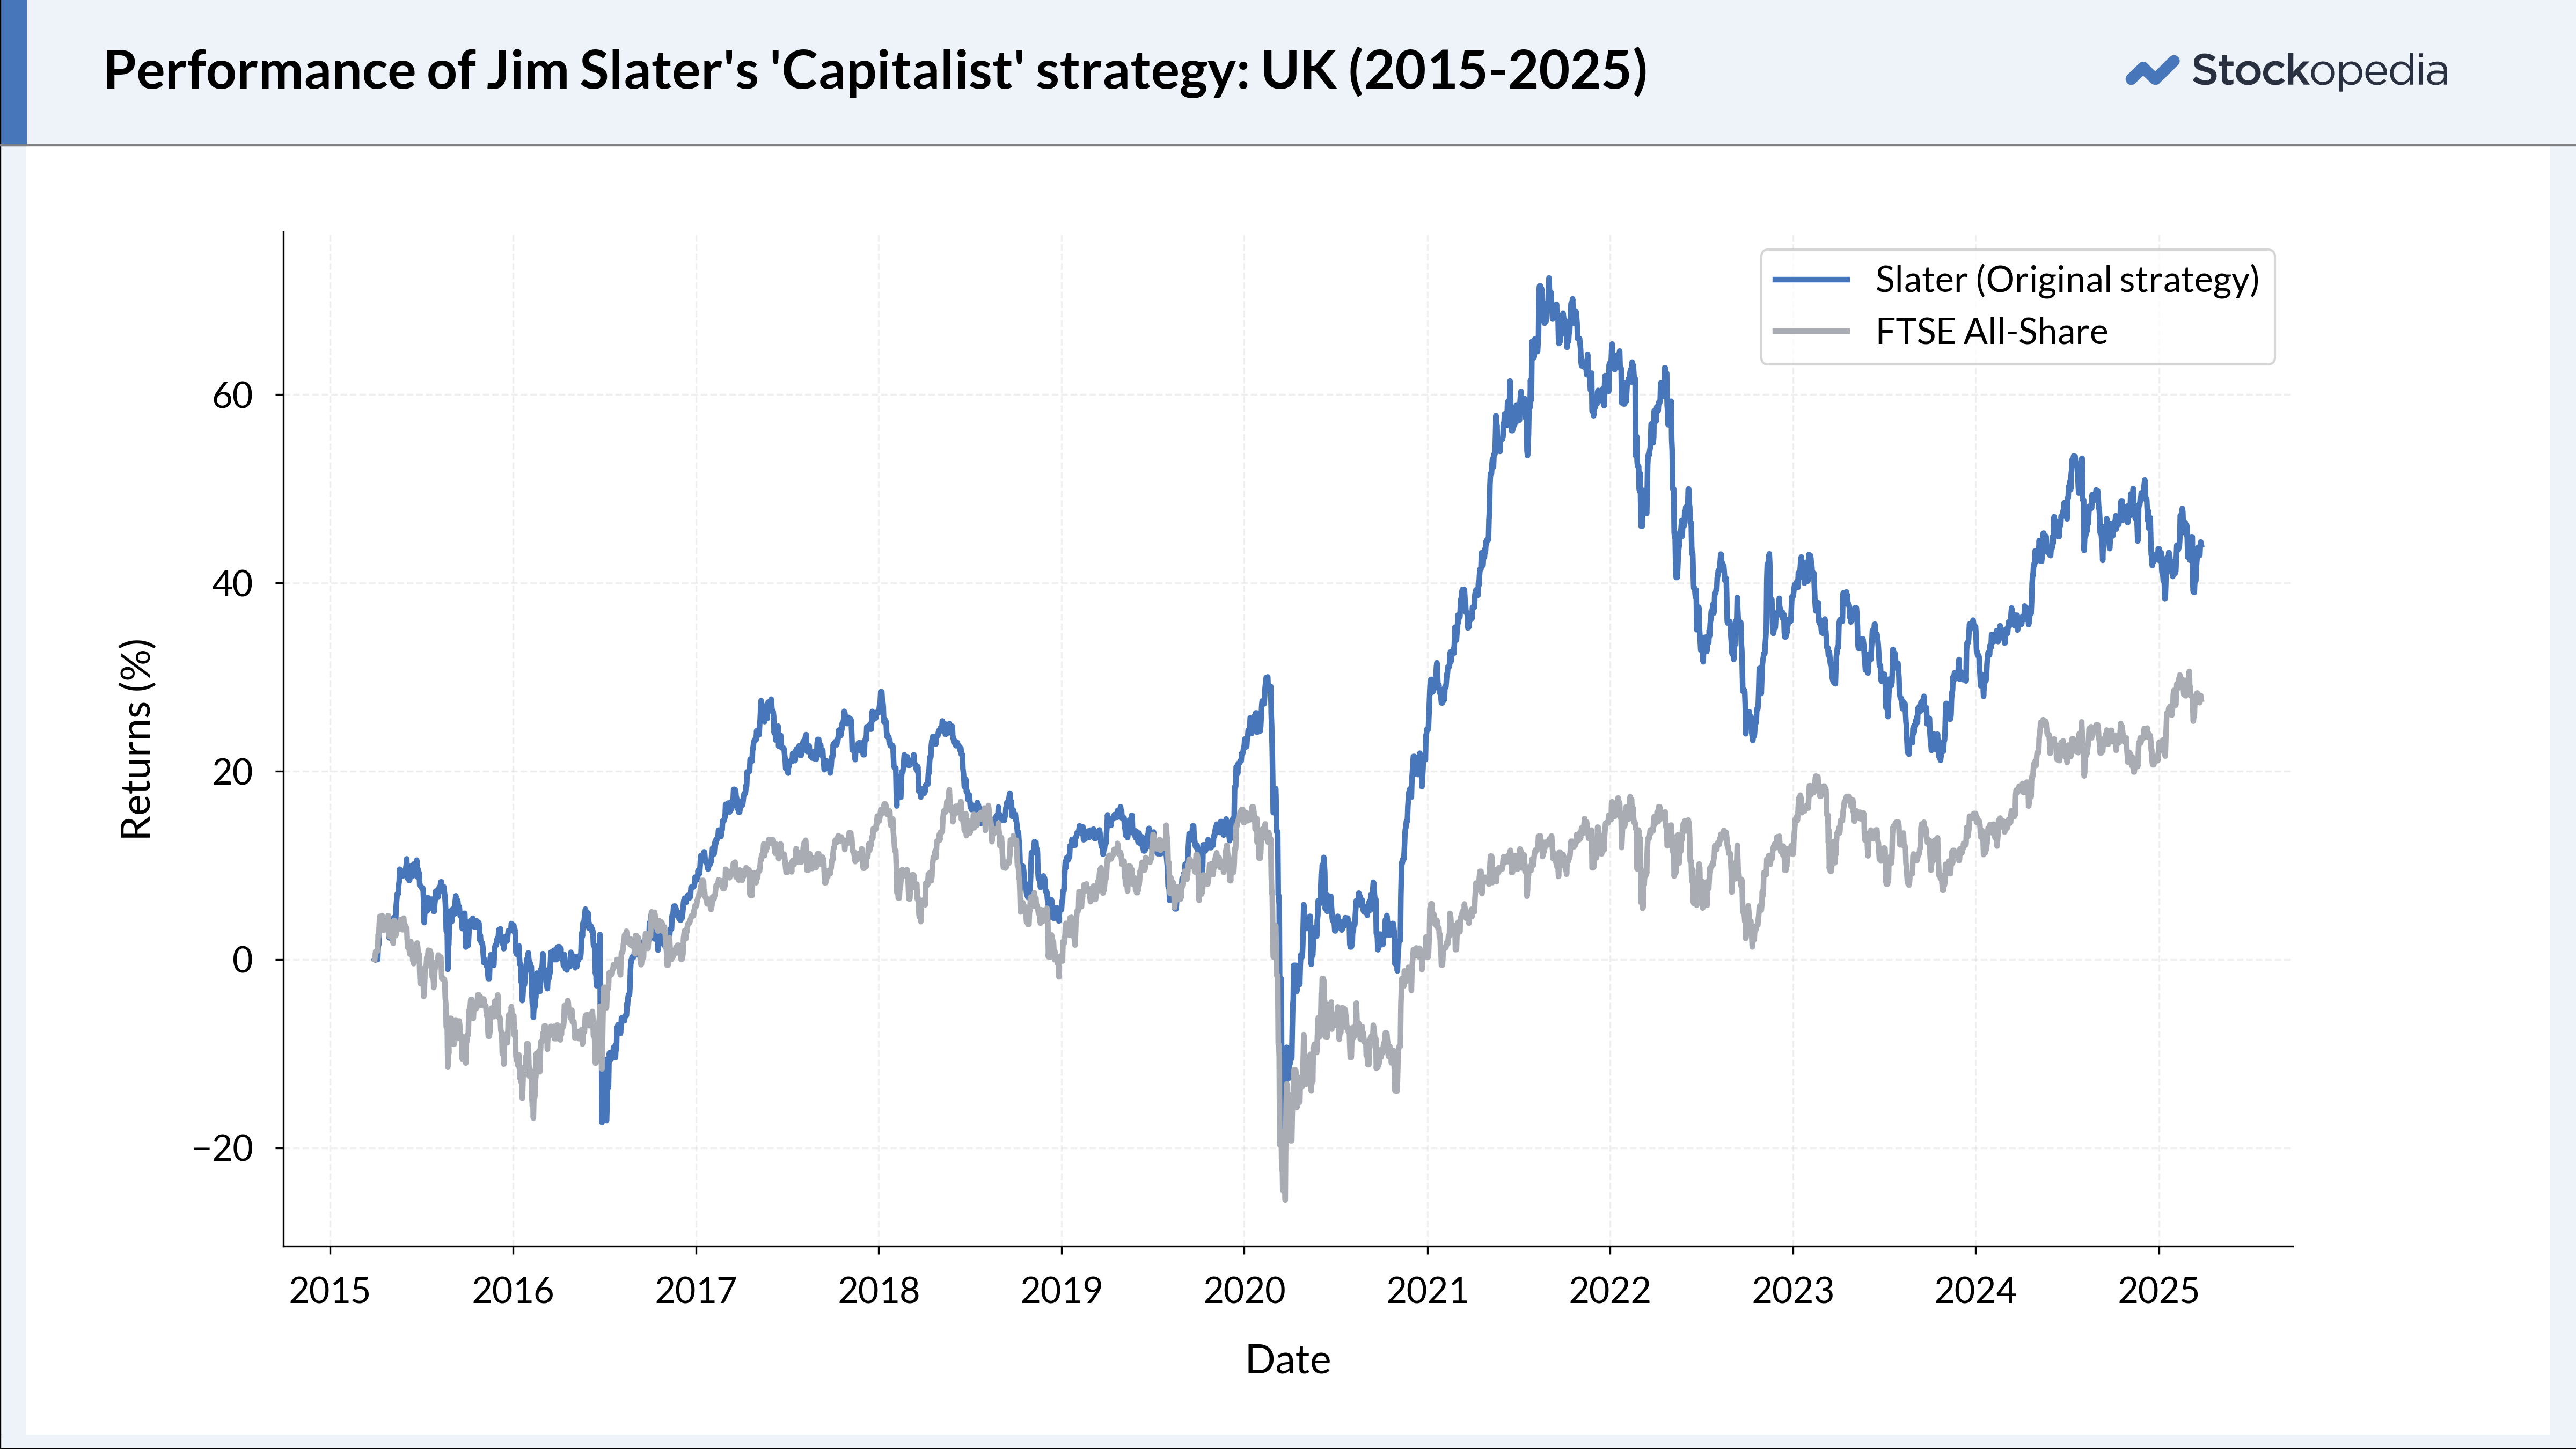
The strategy performed better in 1963-65, when Slater’s portfolio appreciated by nearly 70%. Back then, information was harder to access. Fewer investors used quantitative data. The market was less efficient, meaning it was easier to find mispriced stocks. An investment strategy which worked in the 1960s may not work in the 2020s. Slater managed this problem by reinventing himself, but before we get onto that… let’s go over the simulation in a bit more detail.
I adapted the criteria slightly: firstly, to make them consistent with the rules available in the Stockopedia screener; secondly, because the investment environment is different. Slater ran the ‘Capitalist’ portfolio at the tail-end of the post-war economic boom, when Prime Minister Harold Macmillan told voters, ‘You've never had it so good’. Slater later reflected, ‘The market was in quite a bullish phase… This obviously helped.’
Today’s economic climate is less favourable, what with pandemics, inflation and geopolitical crisis. I was less stringent when running the simulation, particularly around earnings growth. I honed in on the following cut-offs:
- The dividend yield is at least 2%; # My interpretation of Rule 1 above
- An EPS CAGR rate of at least 20% (over prior 3 years); # As per Rule 2
- EPS growth streak of at least 3 years; # As per Rule 3
- The current ratio is at least 1, indicating a reasonable liquid position; # As per Rule 5
- The assets-to-equity ratio is 350 or less; # As per Rule 7
- The P/E ratio must be below 15; # As per Slater’s criteria for the price-to-earnings
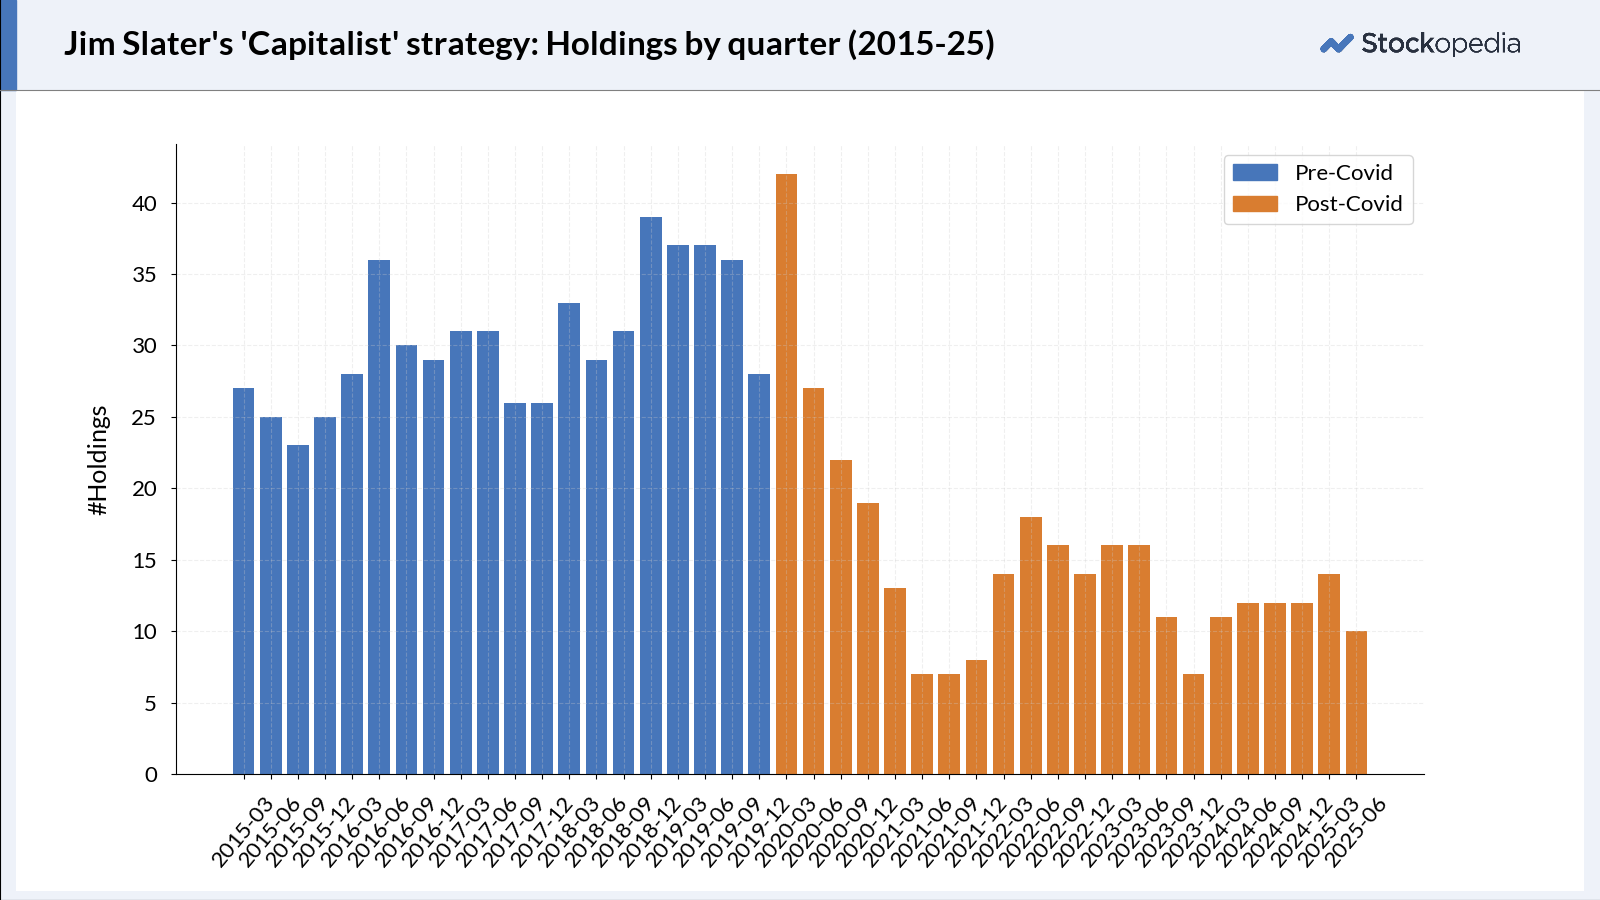
We can make a few observations. The number of holdings in our simulation dropped significantly after Covid. This was likely due to slower earnings growth during the pandemic and the Ukraine War. Higher interest rates also made it harder for companies to meet Slater’s strict liquidity and balance sheet requirements. The ‘Capitalist’ strategy also performed better after Covid, particularly in 2021. Some of the top performers were as follows:
- Stock Spirits (LON:STCK^K21) - 42% gain between 2021-06-30 and 2021-09-30. Stock Spirits was a UK-based company primarily involved in producing and distributing alcoholic beverages. The company performed well during the pandemic. In September 2020, Roland explained that, ‘lockdown restrictions have inevitably led to a big shift in alcohol sales from the on trade to the off trade. One company that may have benefited from this is drinks group Stock Spirits.’ The company was eventually acquired through a cash offer of 377p per share, representing a 41% premium.
- Morses Club (LON:MCL^B23) - 76% gain between 2021-03-31 and 2021-06-30. The company was a home collect credit business. Covid forced a rapid digitisation of financial services, and Morses Club had already been transitioning to a more digital model through its Shelby Finance division. Furthermore, during the pandemic, many people faced financial distress. With many mainstream banks tightening lending standards, Morses served a niche but growing market of people excluded from traditional finance due to poor credit. As recently as June 2021, the company satisfied Slater’s criterion that the Chairman’s statement should be optimistic. Paul Smith, Chief Executive Officer of Morses Club, said: “Despite the continued impact of the pandemic, trading performance across all of our lending products has been very strong in the first quarter of FY22”
- Steppe Cement (LON:STCM) - 44% gain between 2021-03-31 and 2021-06-30. Steppe Cement, headquartered in Malaysia, operates as an investment holding company focused mainly on cement production and sales. The company’s financial statements for 2020 (published in 2021) contained several bullish points. Net profit rose 14% to $11.1 million, while EBITDA edged up from $23.9 million to $24.2 million. Export volumes also grew by 20%, keeping pace with broader market trends.
The Superinvestor of Slaterville
Many will argue that Slater was just lucky. After all, in a large enough group, a handful of coin-flippers are bound to land ten heads in a row purely by chance. This was precisely the point Warren Buffett made in The Superinvestors of Graham-and-Doddsville. He imagined a national coin-flipping contest in which 225 million Americans each flipped a coin once a day. After ten days, probability dictates that about 215 people would have flipped ten consecutive heads — not due to skill, but to random luck.
But then Buffett introduced a key insight: what if all the successful coin-flippers — or investors — had attended the same school? In that case, he suggested, ‘you might want to see if you could identify concentrations of unusual characteristics that might be causal factors.’ In other words, if the winners all shared a common background or approach, it would be worth exploring whether something more than chance — a method or philosophy — was behind their success.
Jim Slater’s approach, like those of the ‘superinvestors’ from Graham-and-Doddsville, clearly does not rely on random selection. Instead, it focuses on stocks that meet specific, targeted criteria. We can clearly see Slaterville in the top-right corner of the charts.
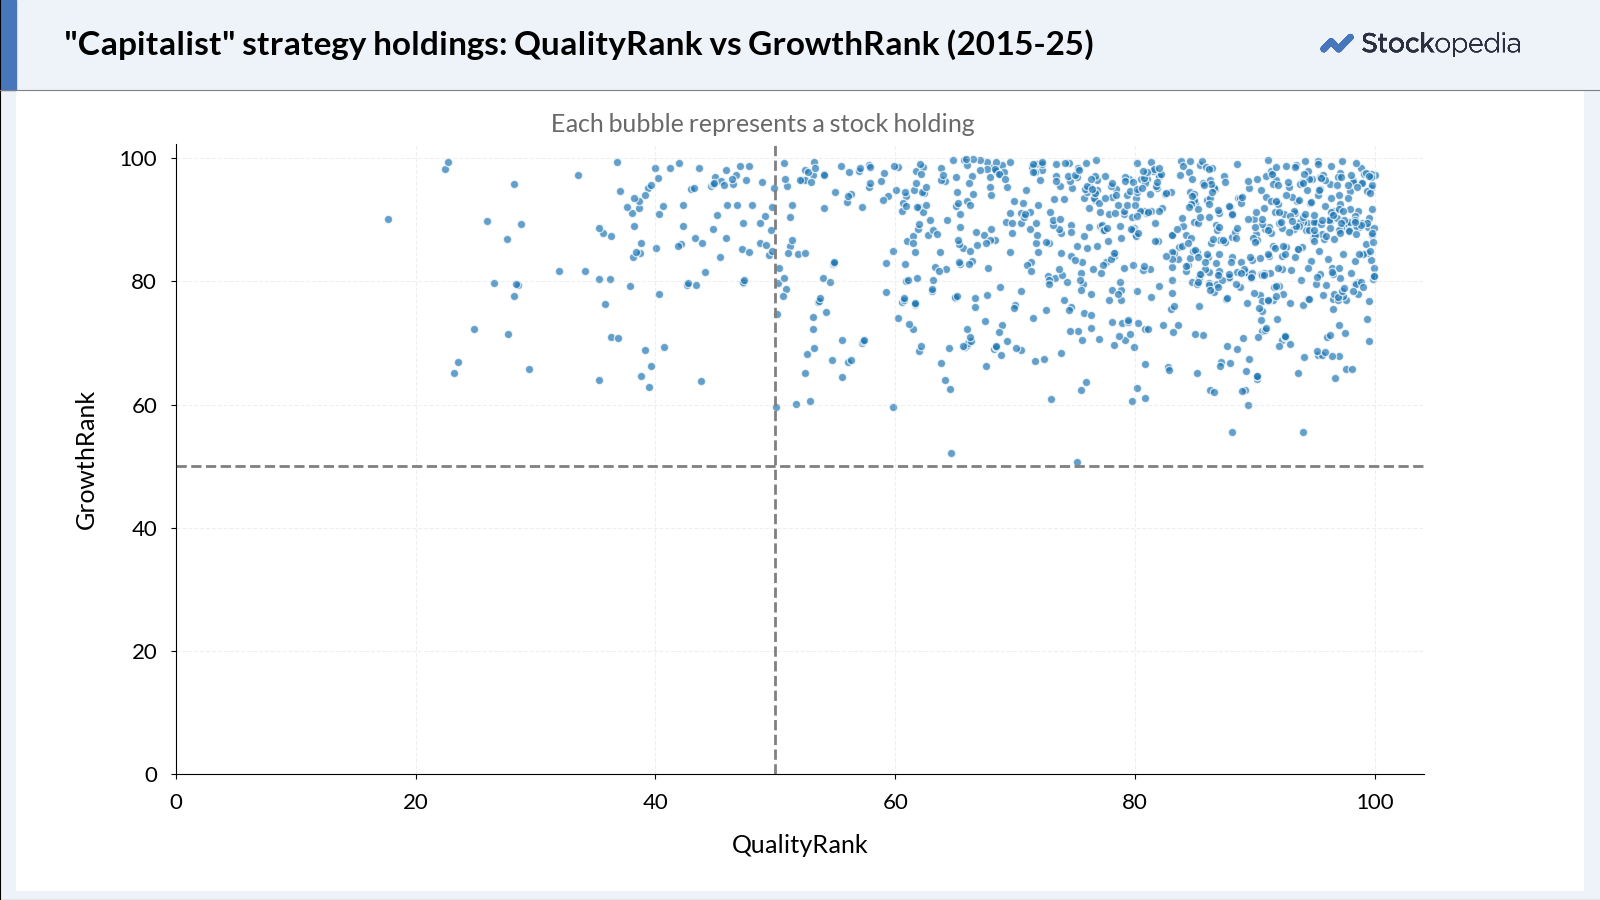
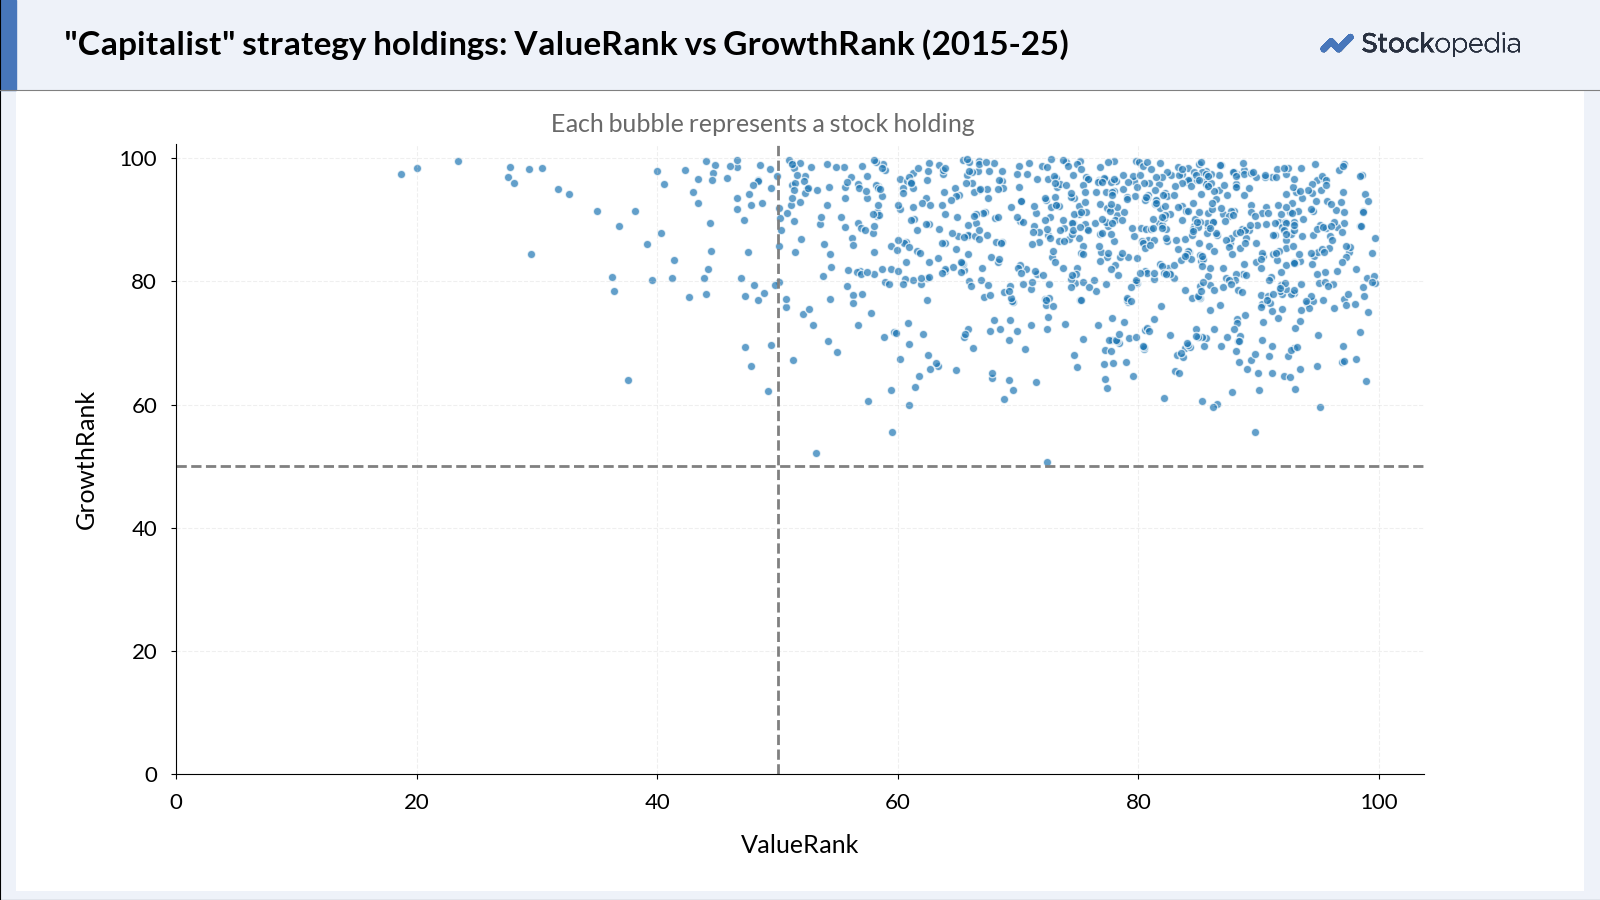
Investors applying the ‘Capitalist’ criteria would have gained exposure to distinct segments of the market — the growth segment, the quality segment, and the value segment. This approach would have ensured stocks were exposed to various factors that drive share price returns.
- One key factor is value — historically, stocks that are relatively inexpensive have outperformed those with high price tags. Slater gained exposure to value by hunting for companies with a low P/E and a high yield.
- Another factor is quality — firms that are consistently profitable, financially sound, and generate strong cash flows typically deliver better returns than companies that are unprofitable, heavily indebted, or struggling to maintain liquidity. Slater gained exposure to quality by hunting for stocks with a strong balance sheet.
Our algorithms generate rankings — ValueRanks, GrowthRanks, and QualityRanks — which are plotted on the chart. Each rank reflects how strongly a company is exposed to a specific factor, with higher scores being indicative of greater alignment with that particular factor.
The Times They Are A-Changin'
In 1992, Jim Slater introduced a new set of investment criteria in his book The Zulu Principle. Our Zulu GuruScreen, inspired by Slater’s approach, applies the following investment filters:
- PEG ratio below 0.75 — indicating growth at a reasonable price;
- Price-to-Earnings (P/E) ratio under 20 — avoids overvalued stocks;
- Earnings per Share (EPS) growth over the past year above 15% — selects companies with strong recent growth;
- 1-year relative strength greater than 0% — focuses on stocks outperforming the market;
- Return on Capital Employed (ROCE) above 12% — ensures efficient, profitable use of capital;
- Market capitalisation between £20m and £1b — targets small- to mid-cap growth opportunities.
We simulated the performance of the Zulu approach between 2011 and 2025. While it didn’t quite match the returns of Slater’s Capitalist portfolio (1963–65) it still delivered solid gains… over a much longer time period.
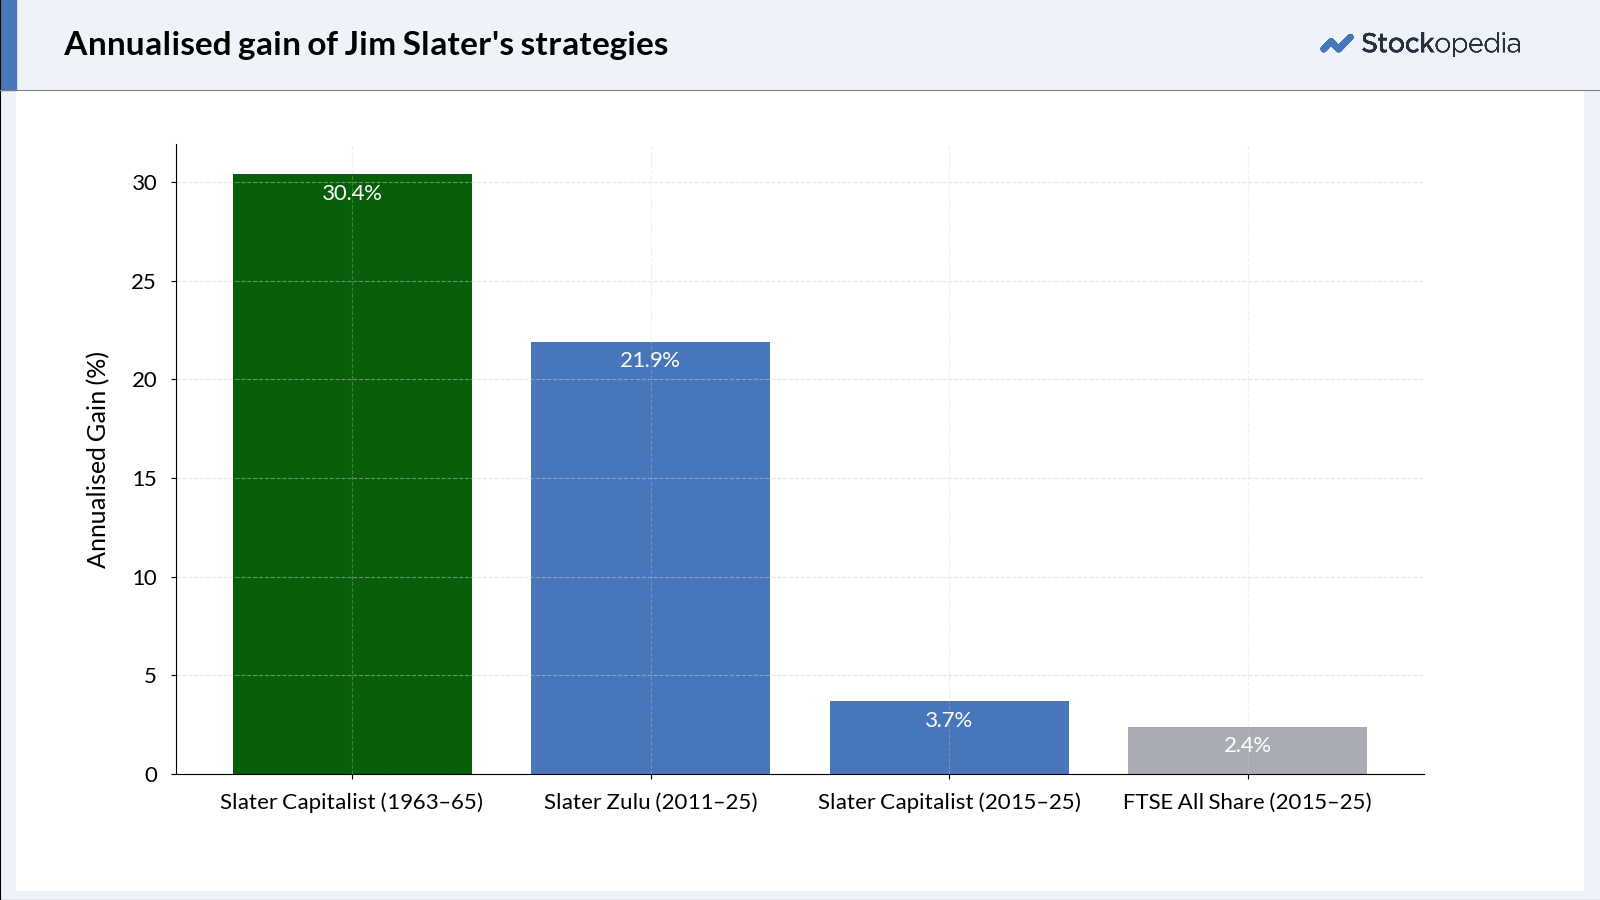
By adapting his approach, Slater was able to sustain a strong performance over time. But what exactly did he change? First, he used different metrics. In the early 1960s, Slater used a range of separate metrics to identify undervalued growth stocks — including the yield, the P/E ratio, and EPS growth. By 1992, he introduced a composite measure: the PEG ratio. This divides a company’s P/E ratio by its EPS growth rate. A lower PEG suggests that the stock could offer growth at a low price.
Slater also increased his exposure to two factors that drive returns: size and momentum. He started to focus on companies within a specific market cap range, deliberately targeting small, dynamic growth stocks. He summarised his thinking with a one-liner, ‘Elephants don’t gallop’ — i.e. bigger companies have less scope to deliver rapid earnings expansion. It’s also important to highlight that Slater introduced momentum into his strategy. Momentum is the idea that stocks with strong recent performance tend to continue rising. Slater started to target companies with positive relative strength — i.e. companies that were beating the market.
While Slater consistently targeted Quality-Growth shares, he increased his exposure to Quality-Momentum over time…
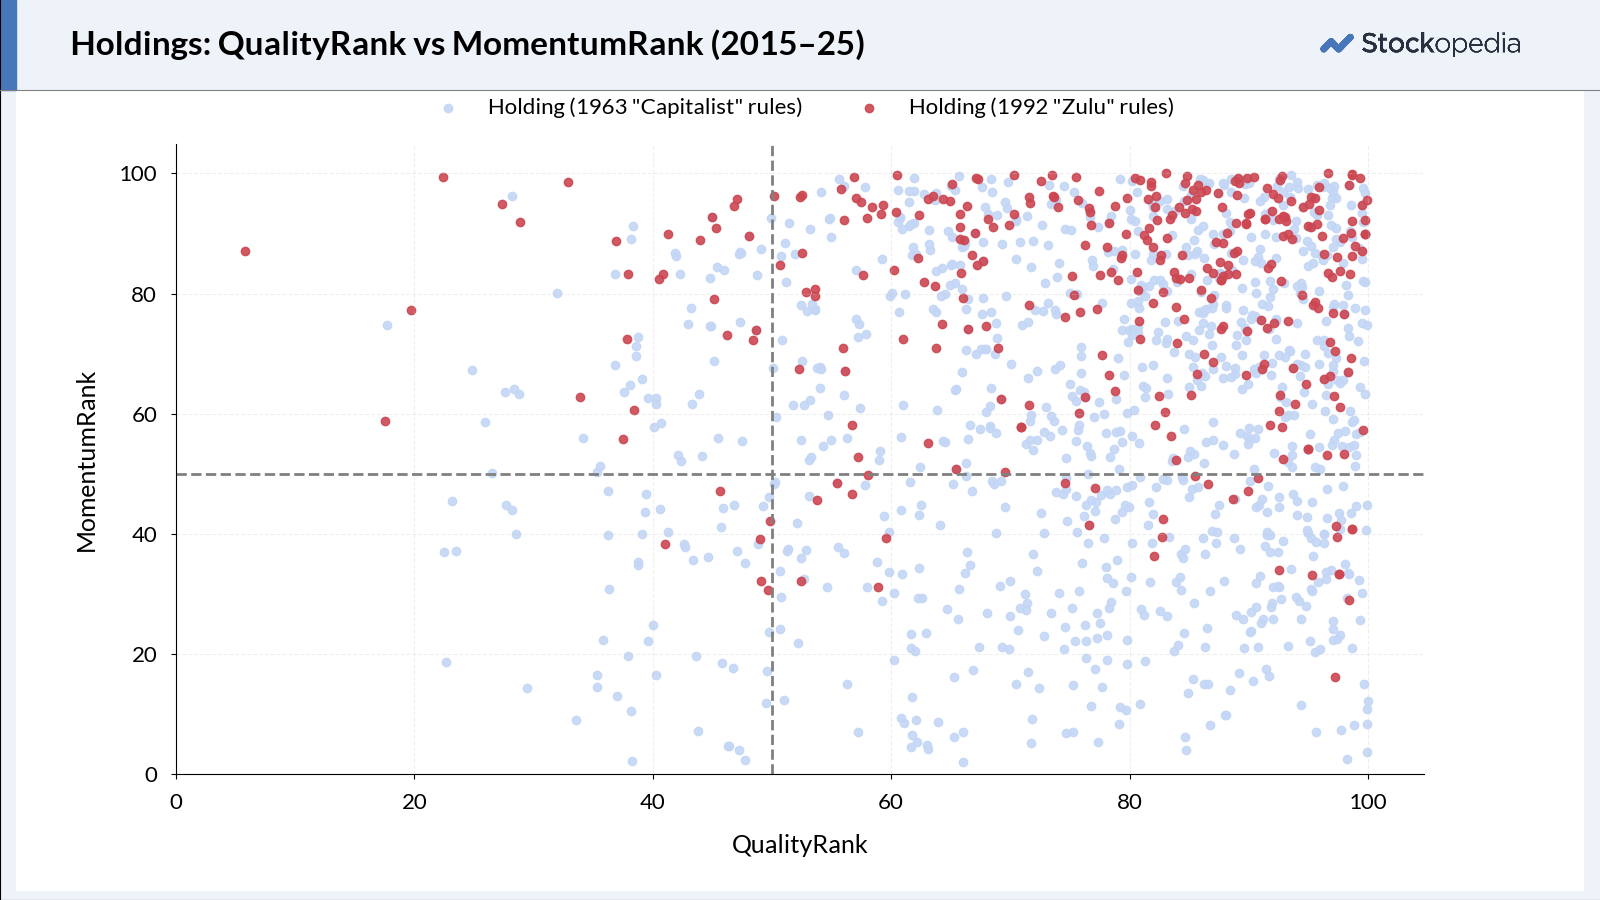
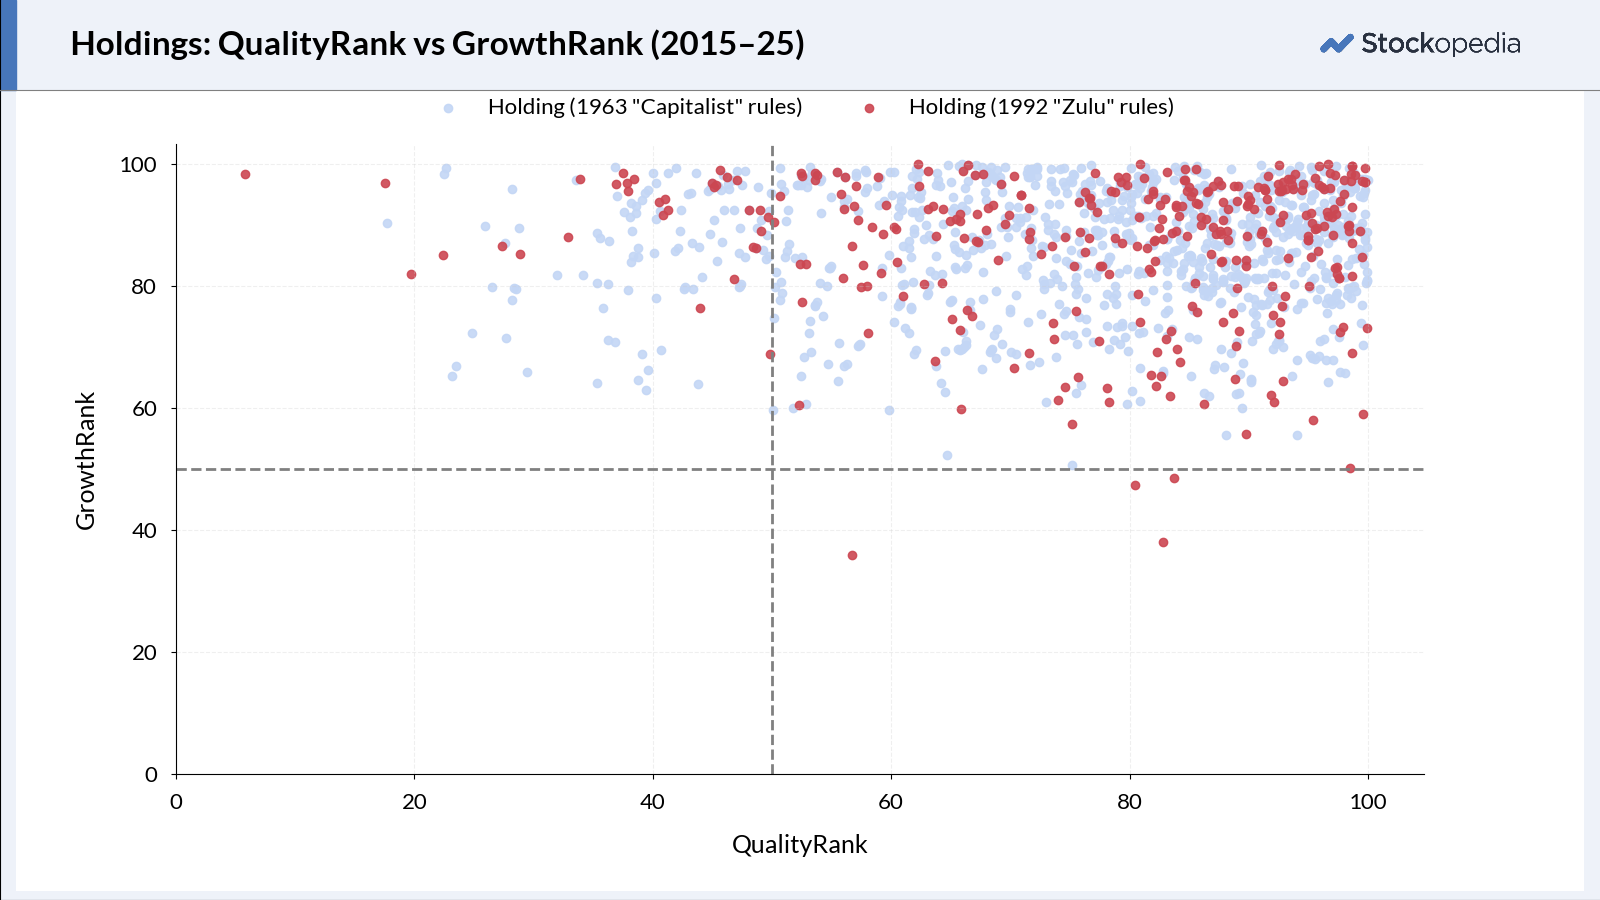
To pivot toward momentum, Slater had to overcome certain cognitive biases. He was a trained accountant and his early emphasis on liquidity and balance sheet strength was perhaps a reflection of the classic ‘man with a hammer’ syndrome. If to the man with a hammer, everything looks like a nail, then to the investor who is an accountant, every stock is a balance sheet. He initially sneered at the idea that future returns could be predicted by simply looking at historical share prices. In 1992, he wrote:
“About twenty years ago, I observed that chartists usually had dirty raincoats and large overdrafts… Even now I do not know many rich chartists.”
Over time, Slater’s view changed, apparently accepting the wisdom of crowds — i.e. the idea that the market’s collective judgment can be more accurate than that of an individual investor.
“I give technical analysis much more credence than before…Other investors may be selling after becoming aware of problems that you have not yet identified… If the shares are not keeping up with the market, you should be on red alert.”
Conclusions, key takeaways and next steps
I always wondered why Jim Slater was not more of a household name. He was hugely influential in financial and economic circles. The older generation mentioned him now and again. And yet, he seems to have slipped through the cracks of history, never quite getting the recognition he deserved. Then it occurred to me that history is supposedly written by the winners. For a while, Slater found history working against him. He was wiped out in the crash of 1973 and retired to write children’s books. The fates had been cruel. Slater was condemned to the status of a ruined financier… a harsh reminder that 'rags to riches' stories can play out in reverse.
But Slater proved himself as the comeback kid and eventually had the last laugh. He reestablished himself as an investment guru with The Zulu Principle and a series of other books. These books were my own introduction to investing. When he passed away in 2015, many investors reflected on the debt they owed to his work. Anyone interested in learning more about Slater’s career should check out Adam Curtis’ documentary, The Mayfair Set.
Perhaps most remarkable is how Jim Slater evolved his investment approach over several decades, adapting to changing market conditions and bouncing back from failures in the early 1970s.
Readers hoping to invest like Slater can follow these key steps...
- First, align with the factors that drive returns. Slater consistently exposed his portfolio to value, quality, and growth, and over time, he incorporated size and momentum into his strategy.
- Second, adapt with the times. Slater managed a successful portfolio from 1963 to 1965, achieving strong results that we were unable to replicate in the 2020s, using similar rules. Slater recognised the need to evolve, especially by revising his views on momentum, with the result that his 1992 approach generated solid returns (see below).
- This leads to the third requirement for long-term success: the willingness to question and overcome our own biases. As a trained accountant, Slater initially favoured balance sheet strength and was skeptical of price trends, but he ultimately overcame these biases and targeted shares beating the market.
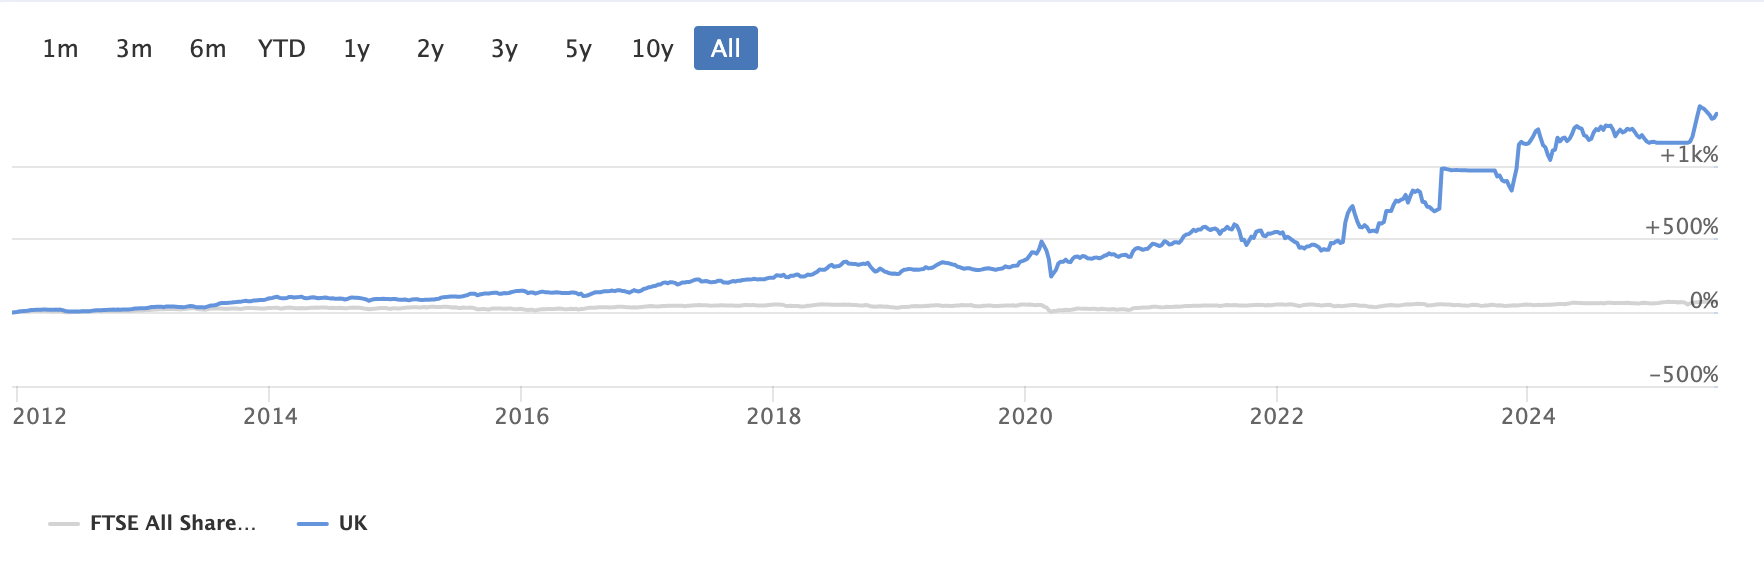
Feel free to explore our GuruScreen, designed to align with Jim Slater’s Zulu Principle strategy.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

35 comments
Read The Zulu Principle many years ago. Excellent book. Would like to listen to an audio version but unfortunately, it is not available in the Apple Store. If anyone knows how to download an audio version, please advise.
A lot of very interesting comments here on the Jim Slater ZULU Principle screen, where the performance is stated as being 1366% since inception, which looks to be about 2012. I too would be interested on seeing the nuts and bolts behind this stellar performance but probably more interested to see what it's performance would be going forward.
The first question which springs to mind is that a screen is (or should be) a filter identifying the stocks which currently meet the criteria for a portfolio. So it is not the screen which makes the return of 1366% but the underlying portfolio which it is screening for.
If I have understood this correctly, then the 1366% relates to a portfolio somewhere which Stockopedia are actively managing and rebalancing. If this is the case, why not provide a link to this portfolio? Apologies if this is already stated somewhere.
If someone is managing such a portfolio, then other questions come to mind. If the portfolio is fully invested in qualifying stocks then what happens to the stocks which are in the screen? It could mean that none of the stocks in the screen are selected?
I am not normally that interested in retrospective analysis based on what a guru might have bought as I think there are far too many variables over what is quite a long timescale. However the figure of 1366% has got my attention.
Having read the article I was interested enough to go back and scan through my copy of the Zulu Principle again. It is a well written book. One small correction to my earlier post - the section regarding Poly Peck was under creative accounting (not fraud).
Jim Slater via REFs and then CD REFS got me into investing, and in turn pointed me towards Stockopedia, so I am eternal grateful to the man for that. Wasn't one of his sell criteria if the PEG got above 1.2?
The first share we bought via REFS was Ashtead (LON:AHT) around £1, then sold at 1.20 for a nice profit, or so we thought at the time.
"I always wondered why Jim Slater was not more of a household name"
Well he was for a while - but for all the wrong reasons. The Slater Walker affair was quite prominent on the news and it was difficult to feel any sympathy for Slater's eventual situation. Obviously he reinvented himself as a writer and somewhat ironically as a Champion of the small investor.
No doubt that he was a good writer and managed to communicate his thoughts in a very readable way. The Zulu Principle had a very good section on frauds, in particular, Poly Peck and the boosting of profits through currency transactions, so not just a book on investment styles.
In the Zulu Principle, Slater did acknowledge the role of technical analysis and there was quite a long piece featuring Brian Marber discussing momentum. So its fairly clear that he bought into theses ideas in 1992 when the book was written and not part of an evolution some time afterwards.
Slater had many simultaneous ideas on all types of investing but these tend to be lost as his thoughts on PEG gained prominence. There was an excellent post on Stockopedia a few years ago, which like many other excellent posts here has been lost. In a discussion regarding Slater, the subject of his monthly news letter "Investing for Growth" came up.
The point was the selections in IFG bore little resemblance to stocks that you would expect to see using a quality screen. If anyone here remembers IFG, names like Surrey Free Inns (SFI) , Old English Pub and Luminar will be well remembered. Unfortunately, these were questionable selections and it would seem that Slater had a blind spot with the hospitality industry.
As regards when to sell, Slater I recall did give some guidance in the Zulu Principle. Straight away on bad news and ( I think) a 25% unexplained decline. I am not sure that the Stockopedia Slater screen would use these sell points so I am not that sure the screens contain stocks that the original guru would have chosen. Interesting to look at these screens but I don't think that they can be taken as definitive portfolios.
Slater was a crook who wrecked a number of businesses and the lives of many employees on borrowed money. He avoided prison solely because of his partner’s connections to the government of the day. In the process the activities of Slater Walker contributed to the evisceration of the stock market of the time. Not the sort of creature that I would wish to idolise.
Slater had an, ahem "Interesting" backstory. Although I believe his share picking strategy has merits, the man himself doesn't come across as someone I'd have wanted to spend time with. The red flag for me was that he was somekind of protégé of Lord Stokes; super salesman who became head of Leyland, then swallowed Triumph, then Rover, then got invited to acquire the failing BMH. Stokes built the dumpster fire that was British Leyland, so to me his judgement was doubtful and the fact he mentored someone who nearly got extradited to Malaysia for financial "Activities" doesn't surprise me.
Jim Slater was clearly no angel as his early days as an asset stripper in the city suggest.
However I think it is unfair to describe him as a crook, and that he only survived because his partner in Slater Walker was a member of the government.
Britain's constitution emphasises the separation of powers so the executive and judiciary are therefore independent of each other. In this case a magistrates court decided that there was no case to answer against the Singapore Government and the case was dismissed.
I think Jim Slater deserves a tremendous amount of credit for helping thousands of individuals (including myself) to understand the opaque mysteries of the stock market via his books, company refs and seminars. Also I think Stockopedia has in some ways expertly built on some of the foundations that he laid.
Thanks for the engagement. I’ve enjoyed the discussion.
I think the general consensus is that Slater was a hero, albeit a flawed hero. Slater was no angel, but deserves credit for helping private investors.
There are also lessons from Slater’s business career that apply to today. A familiar picture emerges if you examine the details of his asset-stripping ventures and how he gained influence beyond the business world—particularly through his ties with political and government circles. Slater began as a successful entrepreneur, but as he grew powerful and crossed into the political realm, he ultimately overreached and eventually, like Icarus, flew too close to the sun.
It’s a familiar character arc and I can see other business tycoons on the same trajectory. Consider a comparison between Elon Musk and Jim Slater. Both represented a partnership between government and business. Readers will be familiar with Musk’s ties to President Trump, so I’ll dedicate more space to Slater’s political connections. His business partner, Peter Walker, was a Cabinet minister and Slater was an informal advisor to the Conservative government, led by Ted Heath. It’s also worth noting that the Labour Party — Tony Benn of all people!! — went around backing Slater’s hostile takeovers.
This segues into another similarity between Slater and Musk. Both were seen as wizards, capable of delivering a silver bullet solution to deep-rooted economic troubles (hence the support they enjoyed from politicians). Slater’s formula was to buy up a company, sell off the inefficient assets and what remained automatically became more profitable. This was somehow regarded as a secret sauce that only Slater and tycoons like him could master. People spoke of Jim Slater’s ‘new way of doing things’. People who worked for Slater boasted that they has ‘solved’ the problem of Britain’s decline — i.e. Slater could make Britain great again.
The comparison with Musk should be obvious. Many political commentators contrast the old, stagnant Whitehall approach with a snappy, tech-driven start-up mentality. You often hear calls to inject this start-up mindset into government departments — as if the world’s problems could be solved simply by firing the suits and letting in the ‘tech bros’ with their hoodies and baseball caps. Let’s wait and see… but for now, it’s worth noting that Slater’s story didn’t end well. Many pundits who supported him later admitted they had been ‘willing dupes’. Politicians turned on the takeover tycoons and called them, ‘The unacceptable face of capitalism.’
I don’t have anything against Elon Musk; I’m just putting on my historian’s hat and making a comparison. If we don’t learn the mistakes of the past, we are bound to repeat them, etc etc. It matters, because the 2020s are in many ways like the 1960-70s — both decades were marred by political crises and economic stagnation. In times like these, people have a tendency to look out for some messiah figure to save us. I personally do not think that people will gravitate towards a nationalist strongman, e.g. a Hitler or a Mussolini. In a country with solid free market foundations, the greater risk is that we gravitate towards people who can perform economic miracles. It happened in the 1960-70s and it’s happening again today…
My views on this topic are greatly influenced by Adam Curtis BBC documentary, The Mayfair Set, which covers Jim Slater’s career in great depth. I’ll post it here, for anyone interested...
Politicians turned on the takeover tycoons and called them, ‘The unacceptable face of capitalism.’
This remark was directed against Tiny Rowland by Ted Heath. Rowland was in the habit of bribing African leaders in order to take over their companies, which was never Slater's habit. Slater engaged heavily in insider trading, but it's important to realise that insider trading was legal in the UK at the time.
Thanks for clarifying. I guess the general point is that the takeover tycoons rose to power and were held in high regard, then they later fell from grace. That speech by Ted Heath was directed at Tiny Rowland, as you point out, but the speech arguably exemplifies how 'The Mayfair Set' as a group had collectively fallen from favour.
Fascinating documentary
Many thanks for this article as I learnt a few things I didnt know about Jim Slater. However my question is in relation to the Jim Slater Zulu Principle Guru Screen you have in Stockopedia. It has achieved over 1300% since inception, which seems an incredible result. But how has it done this? Currently only 4 shares qualify for the screen. Yet when I read the rules for the guru screens it says you can have up to 25 shares tracked, yet if I read it correctly you only buy shares at the start of the quarter. Also when do you sell the shares. From the guru rules it seems you would sell any share which doesnt qualify at the end of the quarter, so you would probably only end up with about 4 shares at the end of the quarter if that is how many qualify. Also over the last 3 years the screen has delivered around 150% return. Generally how has this been achieved. Have certain shares continually qualified, so the performance has been achieved due to a few exceptional shares. Or do shares tend to be sold after 3 months, so there`s quite a bit of trading to get these results. I think it would be interesting if someone could dissect the results of either this screen or the CANSLIM one, which also has excellent results, but few qualifying candidates, so we can see exactly how these returns were achieved.
Hi,
Thanks for the question.
We can unpack it thoroughly in a full article, as you suggest, but just briefly... your understanding of the rebalancing process is correct - i..e we rebalance quarterly, buying all stocks that meet the criteria, selling stock which don't make the grade, repeat once every 3 months.
I don't have the numbers to hand right now, but I suspect that over the last few years the number of qualifying stocks has been quite small. I say this because you can see the chart flatlining at times, suggesting no shares qualified. And as you say, a small number of shares qualify right now.
Why is this? The Slater screen targets companies with dynamic earnings growth. It may be harder to achieve said growth against the current macroeconomic backdrop of pandemics, political crises, high interest rates... and so on. Interestingly, stocks which do make the cut seem to perform very well indeed, suggesting they have some sort of secret sauce, perhaps?
It's quite a deep topic, beyond the scope of a comment thread... perhaps we can do a deep dive at a later date, into the Slater screen and also CAN SLIM.
Best,
Alex
Alex, look forward to that article.
Selecting no or few candidates demonstrates the strength of a screen, not a weakness. Loosening requirements to select in more candidates makes a mockery of any screen. The literal capacity to produce alpha is the singular measure of success. At the same time one has to acknowledge that any screen will filter out the vast majority of candidates that will go on to have big price rises.
Has there been a period when no stocks qualified?
It would be useful if Stockopedia, showed the actual stocks selected, at the moment you can only see the ones that currently qualify.
So did slater really sell stocks as they related due to their peg rising. No I think the screen is focused on entry and not exits.
The fact that it dropped stocks like this every quarter and still made 1300% is pretty good.
If we ran a model where the exit criteria of Slater were modelled that would be awesome, but can't we theorise a set of non negotiable criteria in the screen that would result in being kicked? Or can you stay in if you meet some fraction.
There is no silver bullet. I like sectors so Mr Slaters selection are not in the current zeitgeist imo.
At some point yes - and the AI algos will know it before we do.
Travelzoo (NSQ:TZOO) is worth a look imo.
Q: "how can we beat the bots" - the investment world is changing and we need to be aware.
Don't let the tail. I agree with this. For some reason the GURU screens have been ignored over the last few years.
The rules are not entirely clear to me either. A follow up article by Alex on how the Slater screen has achieved its results would be very useful. Is it just a few lucky picks or is it consistent?
The background bio on Slater was very interesting. Although Buffett gets all the attention, putting his principles into practice is difficult. But Slater's ideas can be used by a small investor.
Thanks for this article Alex, it brings back a few memories as, like Jim Slater, I lost money in the crash of 1973 and it took a couple of years before I started investing again. I also went to the same school as Jim Slater (Preston Manor County Grammar in Wembley) but our periods at the school did not quite overlap. There is a school of thought which says that investors using a particular method should stick to their guns and not change the method in response to market conditions but I guess you have to apply a bit of common sense to this, as Jim Slater appears to have done.
A mate of mine lent me his copy of The Zulu Principle around 95/96 and it is what got me into investing. Jim Slater also set up Company REFS using data from Hemscott. These were data sheets (a forerunner to StockReports) that you could use to look for share ideas discussed in The Zulu Principle. In the days before CD-ROM, these were like telephone directories in size.
A few years ago, I was curious to know if Company REFS was still going and my internet search led me to Stockopedia, where I watched a video of Ed announcing they had recently bought Company REFS. I often think of Jim Slater when I look at StockReports, and how having so much information available as a one-pager, was just like good ol' REFS.
Having just remembered about Hemscott, there was a poster called Anakin, championing a share called Videologic. Any Stocko subscribers here from the Hemscott bulletin board of 30 years ago?
"Any Stocko subscribers here from the Hemscott bulletin board of 30 years ago?" Not quite but close from 1998! *when Russian ruble crisis ( & Asian crisis) sent the UK market down - days of early google " it will never catch on!" - remember posters like freddy or ydderF after he lost a bet - 28Kbit dial-up modems, driving after work to post share certificate sales and the national press saying there is a new group of on-line amateur investors!! used so much had to buy a second landline to allow us to receive calls! Was doing very well until the dot com bubble burst. Learnt a hell of a lot (dare I say more than a great book) especially when starting from scratch in 2001! Believe Morningstar bought Hemscott data?
Was it Kirk999 who used to push Northgate Information Solutions have a feeling he lost a fortune in the end must be late 90's early noughties.
I was also brought here by Jim Slater, I inherited my Dad's shares and that led to a nice lump sum when Morrisons went private, I decided to actively manage my holdings rather than just let them drift and bought a copy of "Investigating for dummies"*. One of the recommended further reading books was "Beyond the zulu principle", the author sounded vaguely familiar, one of those whiff of sulphur names from before my time, like John Stonehouse or Jeremy Thorpe, which piqued my interest. Reading about REFS then led me here.
*Or similar complete beginners guide
Jim also wrote "Beyond the Zulu Principle" subtitled "extraordinary profits from growth shares", in 1996. I still have my copy which he signed and sent me with a Magnum of Champagne for winning a competition about investing. He also showed great generosity to a muckshift foreman friend of mine on the Esher bypass after help with a noise problem. A true gentleman I believe.
Thank you Alex, I enjoyed reading the history lesson. We hold Steppe Cement and will add a few more even though it doesn't meet the filters mentioned. We failed to take profits when we should have done so I'm hoping there's another decent rally to reward patient holders when cement sales grow again.
The big money investments went through SlaterWalker and what he is mostly remembered for no mention of that ?
Hey,
Thanks for the reply.
Yes, Jim Slater and Peter Walker did make a lot of enemies. This is well covered in The Mayfair Set documentary, by Adam Curtis. It covers his asset stripping career and documents Slater's rise and fall.
At the same time, Slater is generally well respected in the private investor space, in large part because of The Zulu Principle and his other books. These are a very accessible introduction to equity research and investment more generally.
If you'll excuse the movie reference, the cynic in me says that life isn't like Star Wars, where the baddies have red lightsabers and goodies have blue ones. I guess some people are a complex mix of good and bad...
Alex
Thanks Alex. I really enjoyed reading this and I'm going to read it again from time to time in the future to help keep me grounded and focused on the rules. A great interpretation of golden advice from a true legend.
“I was looking for shares which, following a bad period, had a steadily rising earnings trend.”
Great stuff hadnt realised Slater had seen this as key sign that things may be changing for the better.
I have long thought myself that this is a good simple point for choosing starting position - thats the beauty of stocky too - the trend in expectations is flagged up nicely (if we could have them further out too as early as possible that would be uber useful - i am aware that not many have forecasts past next year but some companies do and if data is avaialable would be great for it to be uploaded - even if perhaps its in hidden tab if it would make things messy and more confusing if its kinda niche number)
One thing i have noticed that can put a spanner in the works is that the shareprice often turns before the forecasts take an uptick so you can pay materially more by waiting - i have had a couple of dabbles where it appears trend in downgrades is bottoming out and has perhaps steadied - i am not convinced by my gambles in that regard. So i suspect slater is spot on that you dont need to take the risk and you are taking the downside away by paying more if its clearer that the trend is upover rather than temporary pause on downward path.
When companies have been downgrading i think they will probably be right cautious before upgrading as they will look fairly stupid later if that turns out to be a false dawn - much better to say notalot and keep it as it is until you are confident you wont need to flip back - so its logical that uptick is decent sign - albeit befroe one can buy after that sign the shares wil be marked up recently.
There is probably enough companies it there that have shown uptick that there is perhaps no ned to try and find the bottom - unles perhaps you have good confidence in long term plans for said company - too me if i know a company is fundamentally good and just going through bad patch due to stuff beyond their control i tend to take different stance.
Hey,
Thanks for the reply.
I got that snippet from Return to Go, not The Zulu Principle. Slater was writing in 1977 about his investment strategy in the 1950-60s.
The Zulu Principle covers the classic PEG-centric strategy, in addition to other approaches, including turnarounds. In fact, he dedicates a chapter to turnarounds.
I get the impression he was not a one-trick-pony. He had many arrows in his quiver, many approaches to use, depending on the circumstance.
Alex
A shame that the funds run by the Slater family - Slater Growth and Slater Recovery have performed so badly recently - only Slater Income fund has actually made a profit in the last 12 months.
An excellent article. Coincidentally there is a write up on their Jim Slater screen in the IC today along with this additional background....
If nothing else, Jim Slater’s investing classic The Zulu Principle was a canny bit of marketing. That’s because while its title hints at some hidden anthropological discovery, the book has nothing to do with the Zulu people or their customs. Instead, the ‘principle’ was coined by Slater after watching his wife read a 4-page article on the topic. He surmised that had she then “borrowed all the available books on the subject from the local library and read them carefully, she would have known more about Zulus than most people in Surrey”.
If she had gone further, by visiting South Africa, living there for “6 months in a Zulu kraal” and studying everything she could find on Zulus at a South African university, Slater hypothesised that “she would have become one of the leading authorities in Great Britain and possibly the world”.
Slater’s point was that focus matters. By immersing yourself in a subject – be it academic, or potentially highly profitable – you too can fast attain expertise that separates you from the crowd. For the humble retail investor focused on the smaller companies all too often overlooked by the establishment, this was a call to arms.
A smashing account, thanks Alex.
An excellent article. The zulu principle was the first book I read on equity investment, way back in 1999, it remains on my bookshelf today as a guide.