How Warren Buffett achieved extraordinary results without being extraordinary

If you had invested $1 in Berkshire Hathaway in 1976, that investment would have grown to more than $1500 by the end of 2011. That’s an extraordinary result. At the same time, this performance presents an interesting irony. Achieving these results is not rocket science. Buffett once said:
‘In investing it is not necessary to do extraordinary things to get extraordinary results’.
It’s a great line, but some people misread it. They attribute Buffett’s returns to luck. Warren made this point in The Superinvestors of Graham-and-Doddsville. He imagined a coin-flipping contest where 225 million people each flipped a coin once per day. After ten days, roughly 215 people would have gotten ten heads in a row — not because of skill, but simply due to luck.
Buffett then introduced a key point: if winners all used the same approach, their success might be due to a specific strategy, rather than just chance. Buffett noted that:
‘A disproportionate number of successful coin-flippers in the investment world came from a very small intellectual village that could be called Graham-and-Doddsville.’
Benjamin Graham and David Dodd were the founding fathers of value investing. They emphasised buying securities at a ‘cheap’ price (i.e. for less than their intrinsic value).
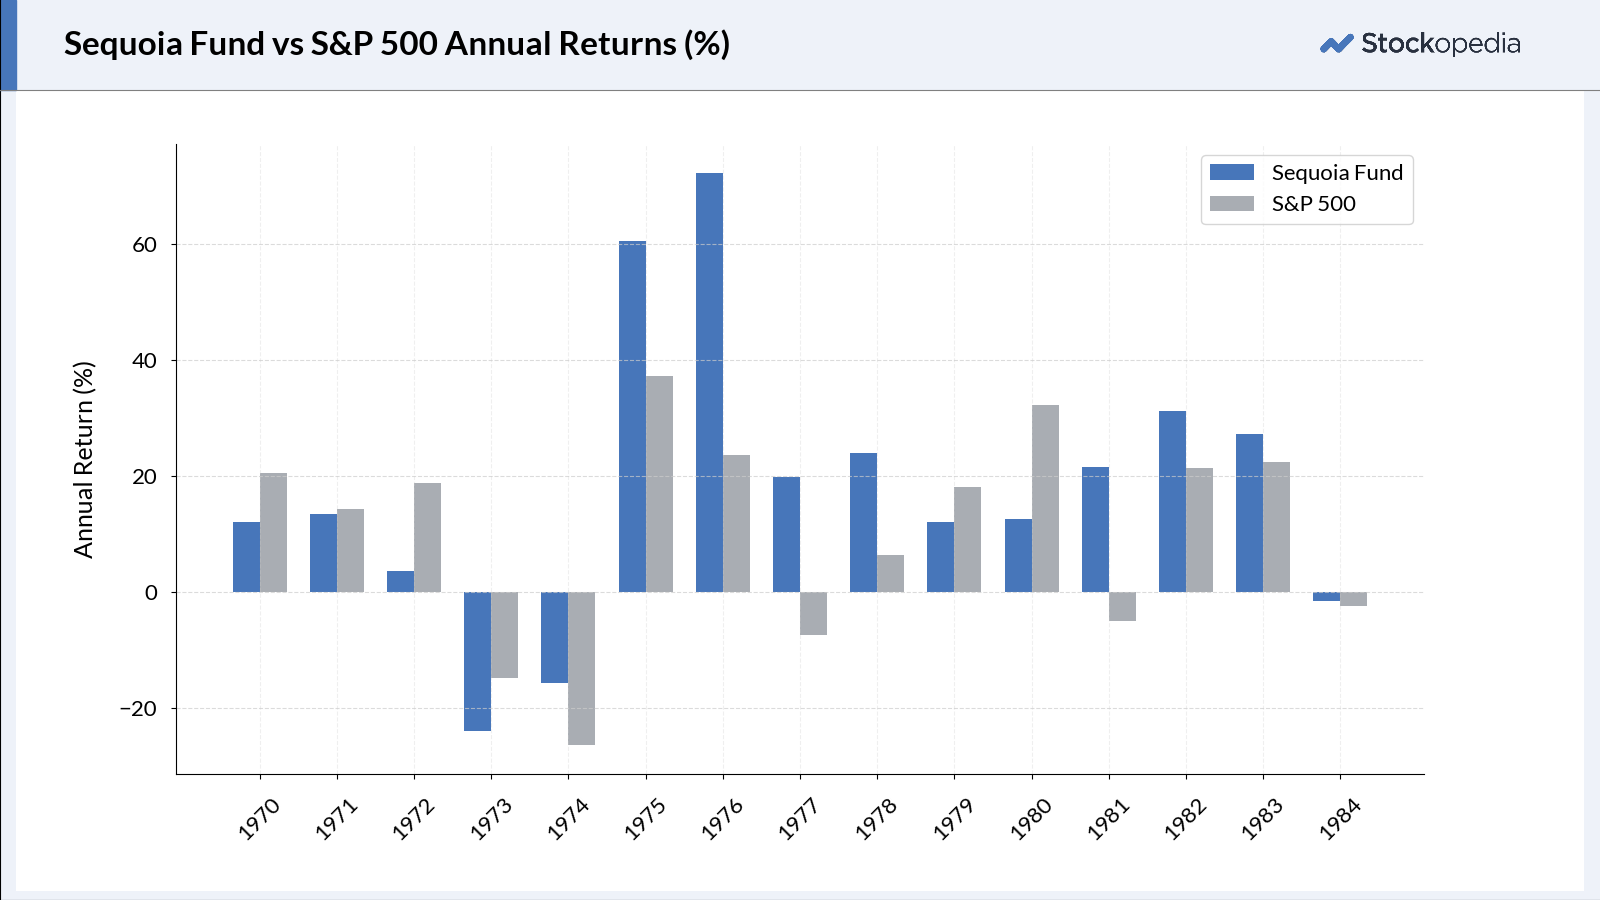
Buffett highlighted a selection of friends and acquaintances he considered true Graham-and-Doddsville-style investors. Each of them had outperformed the market over the long-run. For instance, the following chart shows the record of the Sequoia Fund, which was managed by Bill Ruane, whom Buffett met in 1951 in an investment class taught by Ben Graham.
Reverse engineering Buffett’s Alpha
At the same time, it’s easy to cherry-pick a few success stories, while overlooking other investors who followed the strategies of Graham and Dodd, but nevertheless failed. There must be a better way to explain Buffett's success…
In 2013, three quantitative researchers —Frazzini, Kabiller, and Pedersen— set out to understand Warren Buffett’s performance using a more data-driven approach. They applied regression analysis, a statistical method that examines how Buffett’s portfolio returns moved in relation to well-known factors such as quality, value, and momentum.
Their method was as follows: for each factor, they calculated a ‘factor premium’:
- For the value factor, the factor premium was the extent to which ‘cheap’ stocks (those with low price-to-book ratios) outperformed ‘expensive’ stocks (with a high price-to-book ratio). If Buffett’s returns moved in sync with the factor premium, it could suggest he preferred undervalued, cheaper stocks.
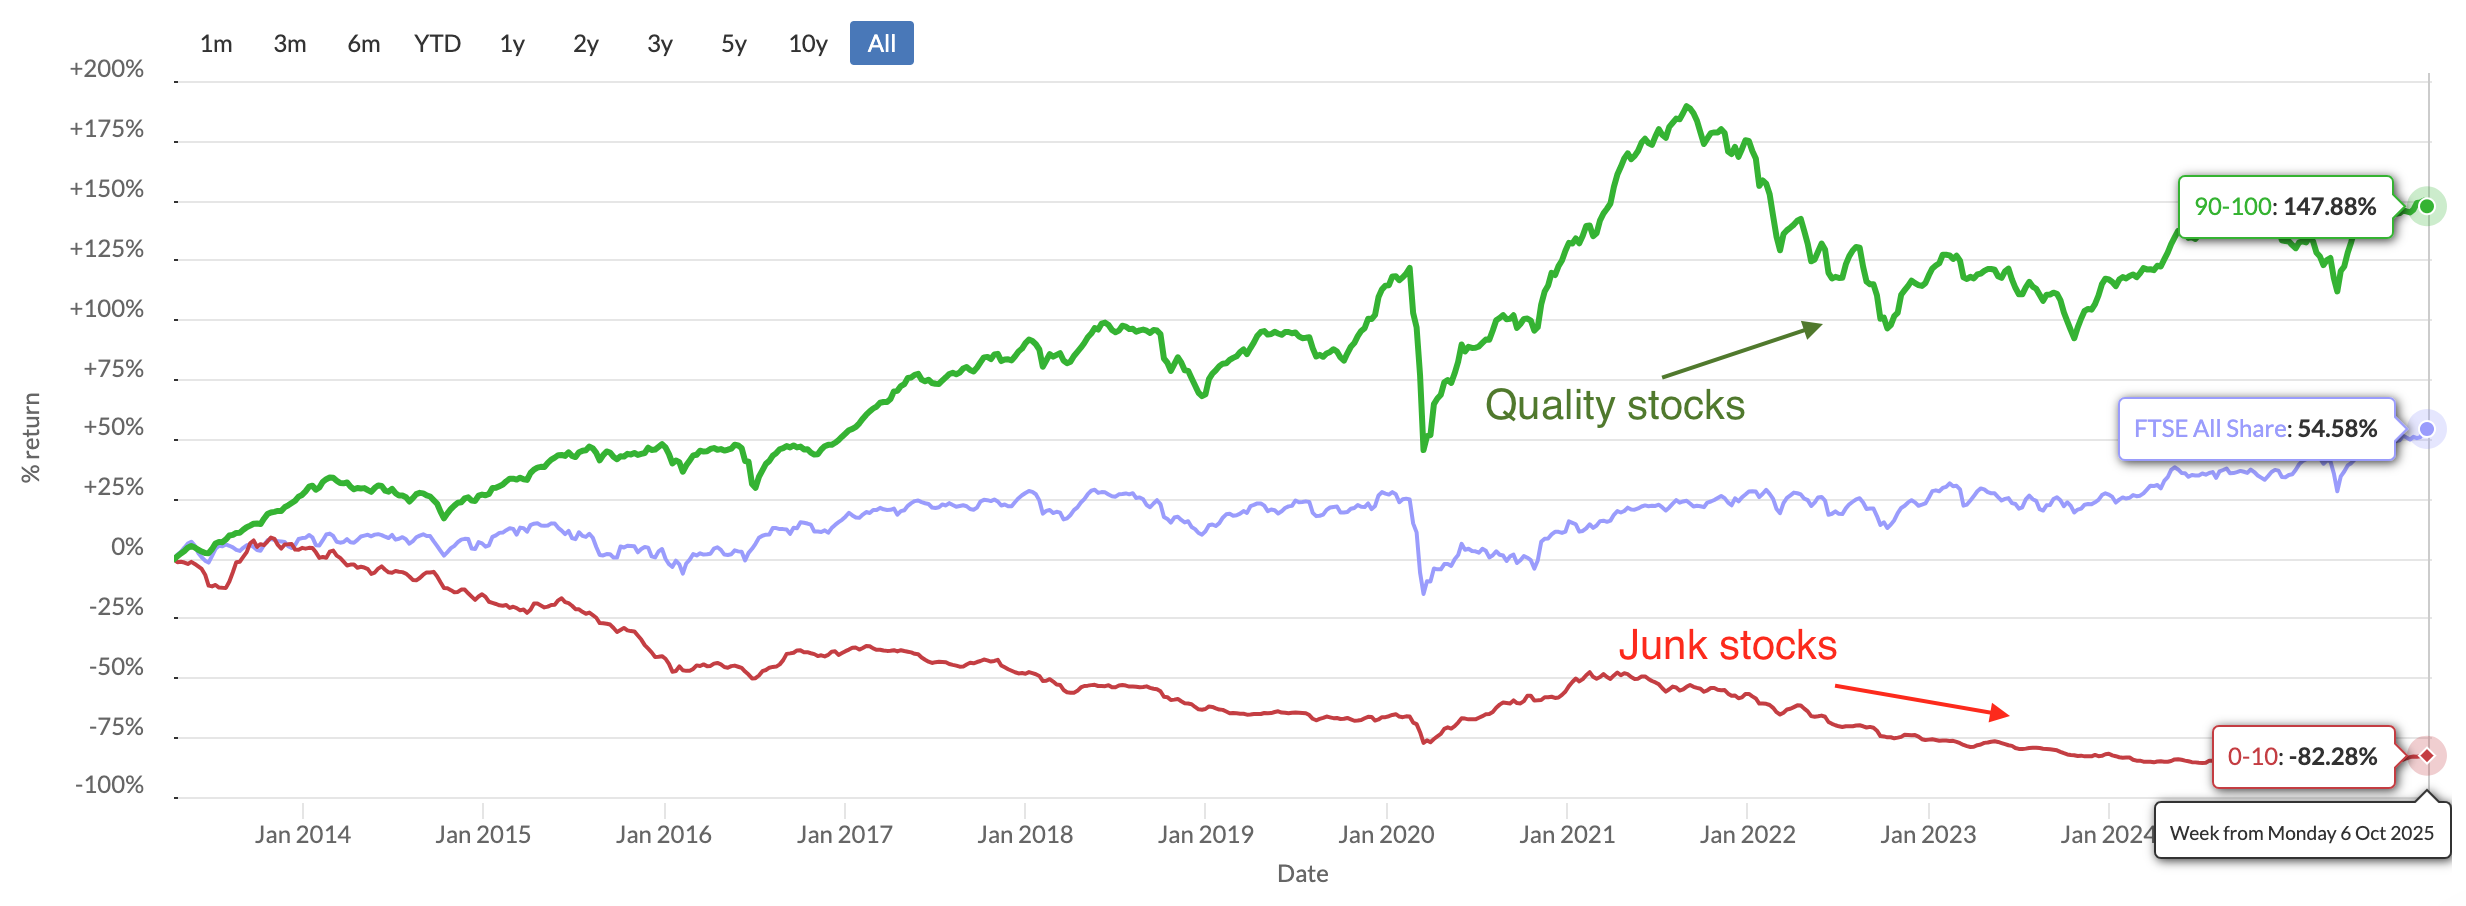
- For the quality factor, the factor premium was the extent to which ‘quality’ stocks (profitable, cash generative) outperformed ‘junk’ stocks (unprofitable etc). If Buffett’s returns moved in sync with the factor premium, it could imply he was invested in strong, financially sound businesses.
Frazzini, Kabiller, and Pedersen looked at six factors in total, analysing whether Buffett’s portfolio returns moved in tandem with each respective factor premium. The regression coefficients are shown below. A positive coefficient indicates that Buffett’s portfolio tended to move in the same direction as that factor. In technical terms, we would say that a positive coefficient corresponds to a positive ‘tilt’ — e.g. a positive tilt towards investing in quality stocks.
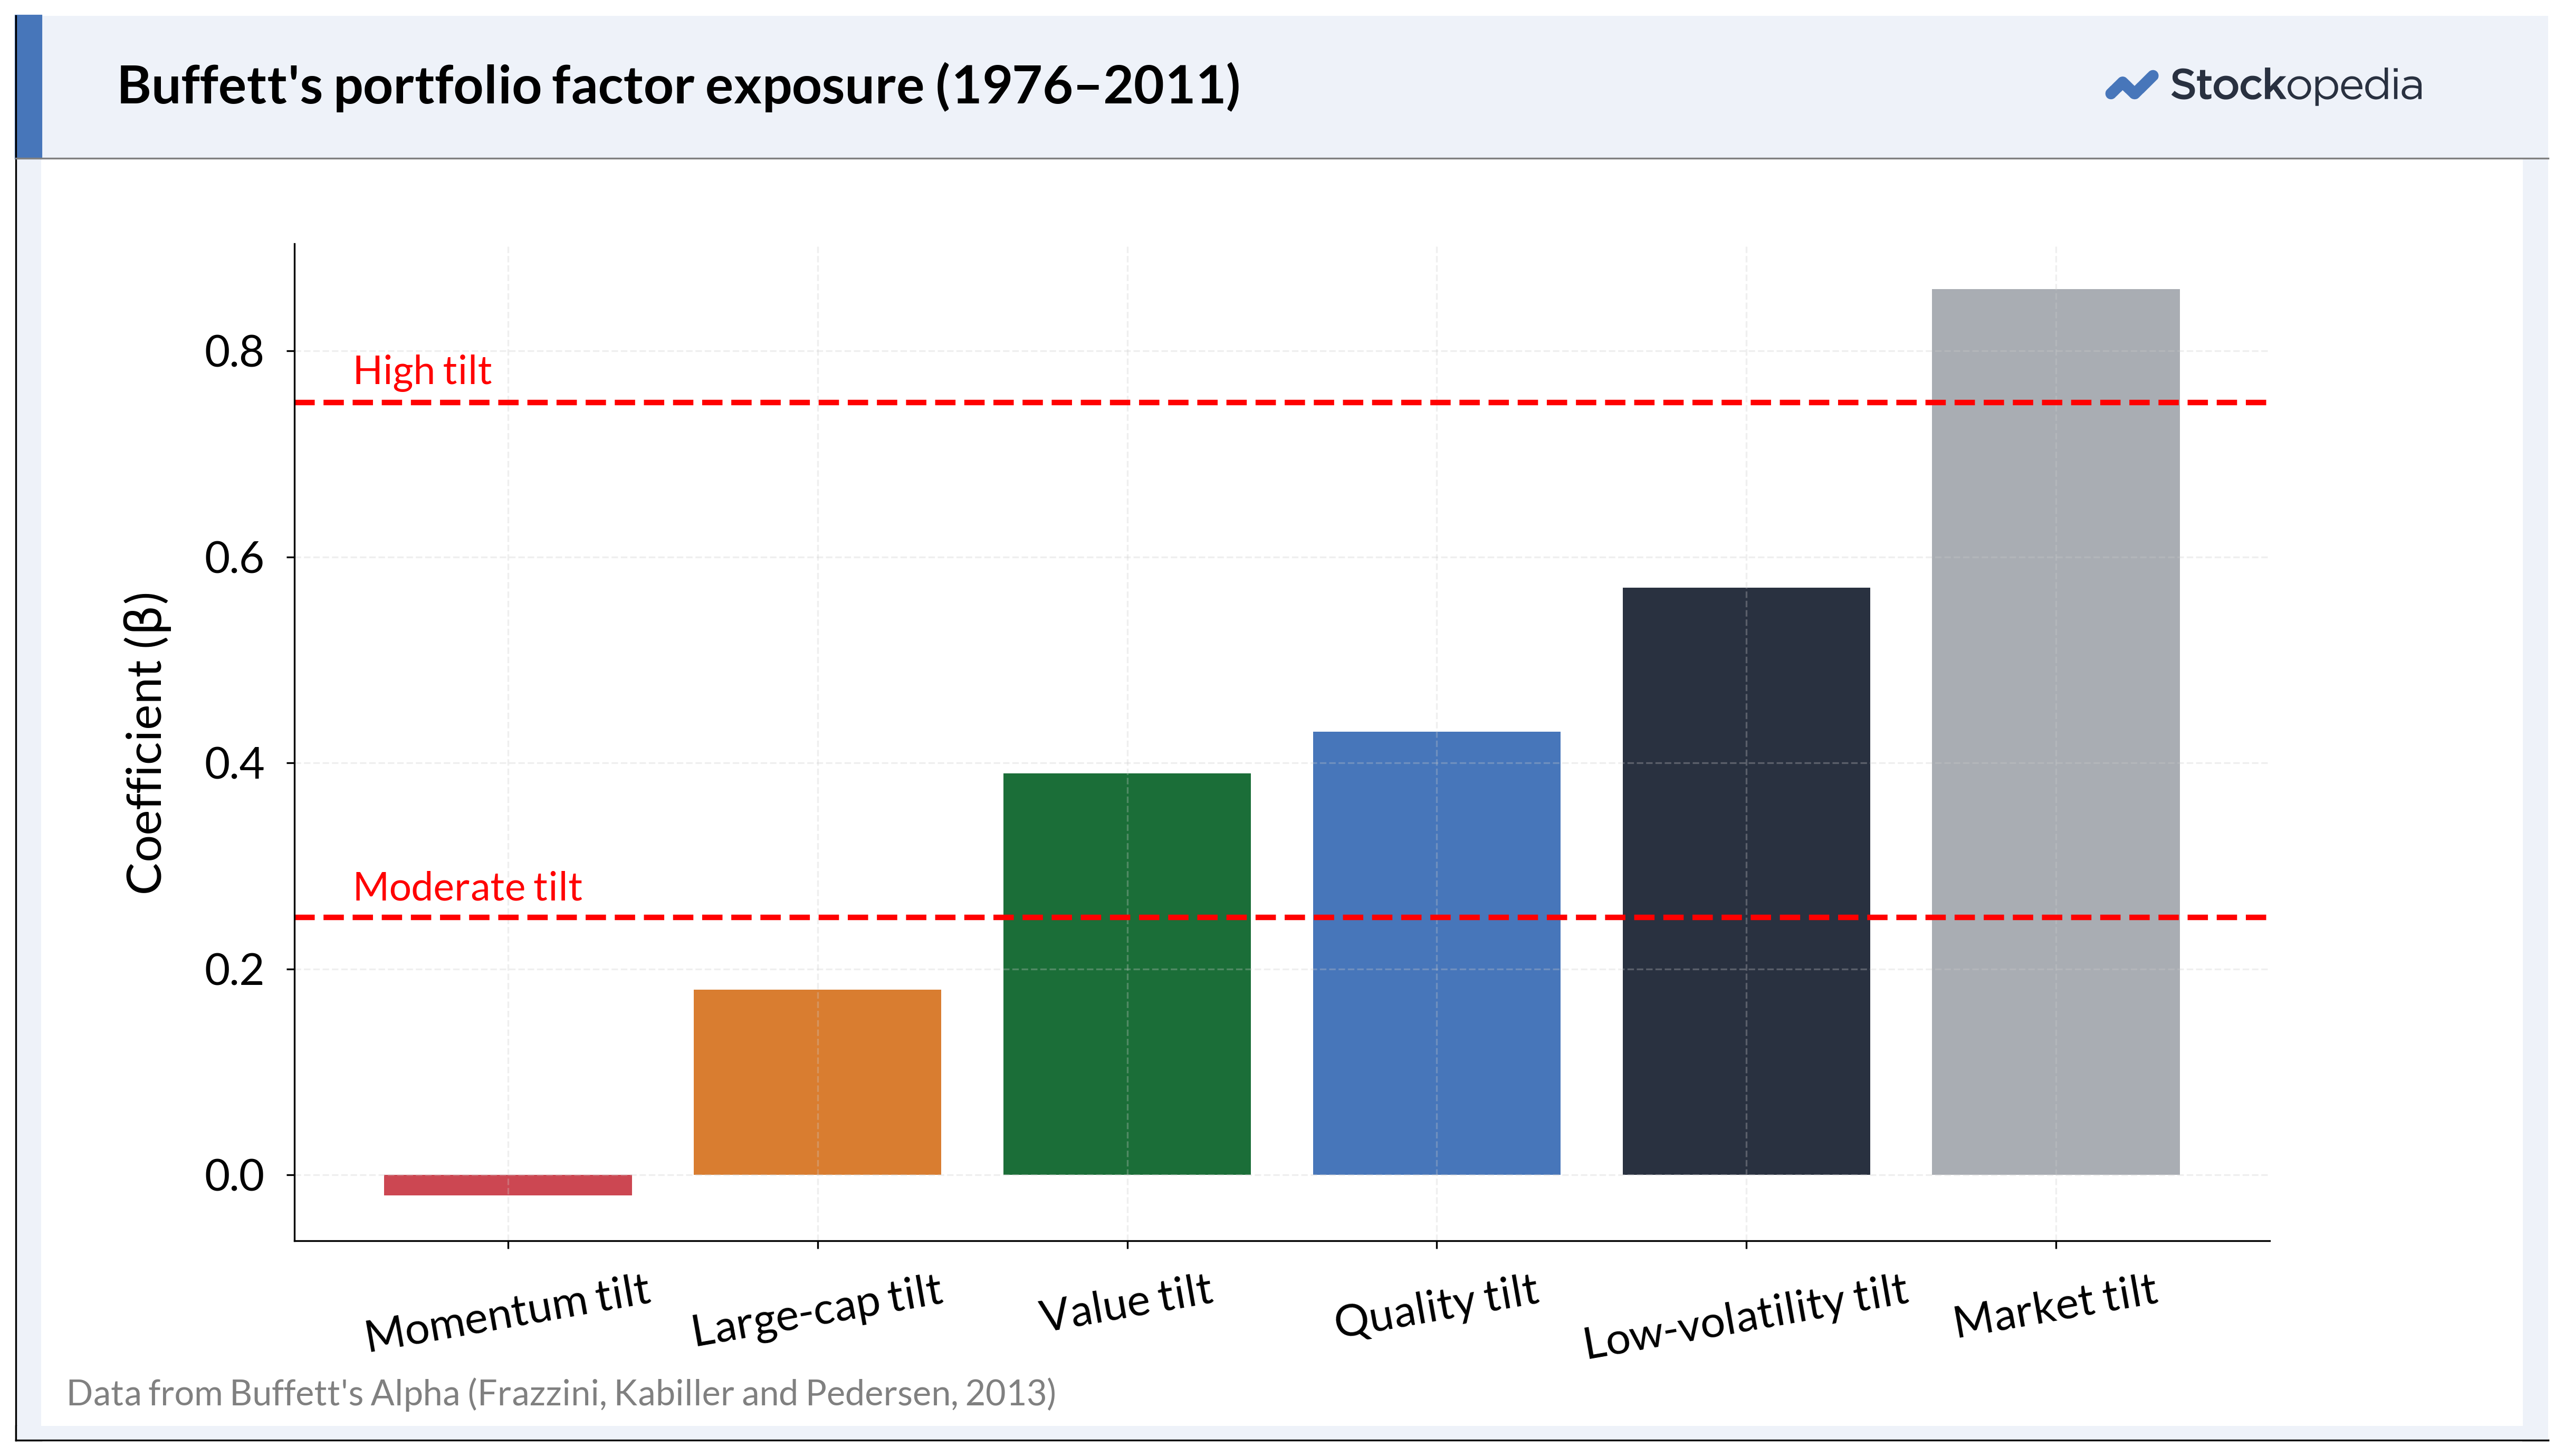
We can make several observations:
- Buffett was significantly exposed to the ‘low-volatility’ factor, suggesting a preference for stable stocks with low price volatility. Buffett’s portfolio also had a large-cap tilt, indicating a preference for large-cap, blue-chip companies (e.g. Coca Cola). Note that these are often stable, low-volatility companies.
- His portfolio was exposed to the ‘value’ factor, but it showed even greater exposure to ‘quality’. This is consistent with Buffett’s preference for high-quality businesses that are not necessarily cheap, but are reasonably priced. This principle is summed up by Buffett’s quote: ‘It’s far better to buy a wonderful company at a fair price than a fair company at a wonderful price.’
- Buffett had a strong ‘market-tilt.’ This does not mean he was tracking the market; it means his portfolio tended to move in the same direction as the overall market, suggesting high correlation or exposure to market risk. Frazzini, Kabiller, and Pedersen also observed that Buffett enhanced his returns through leverage, for example from insurance float. They estimated that Buffett applies a leverage of about 1.6-to-1.
Buffett’s investment approach can be crudely summed-up as follows: leverage-up on good, cheap, stable stocks. The researchers said:
‘Buffett’s performance can be largely explained by exposures to value, low-risk, and quality factors… Accounting for the general tendency of high-quality, safe, and cheap stocks to outperform can explain much of Buffett’s performance.’
Of course, Buffett’s genius lies in the fact that he figured out the stock market’s 'secret code' decades ago—long before big data and quantitative research existed. Frazzini, Kabiller, and Pedersen said:
‘Buffett’s genius thus appears to be at least partly in recognising early on, implicitly or explicitly, that these factors work, applying leverage without ever having to fire sale, and sticking to his principles.’
A closer look the Buffett portfolio
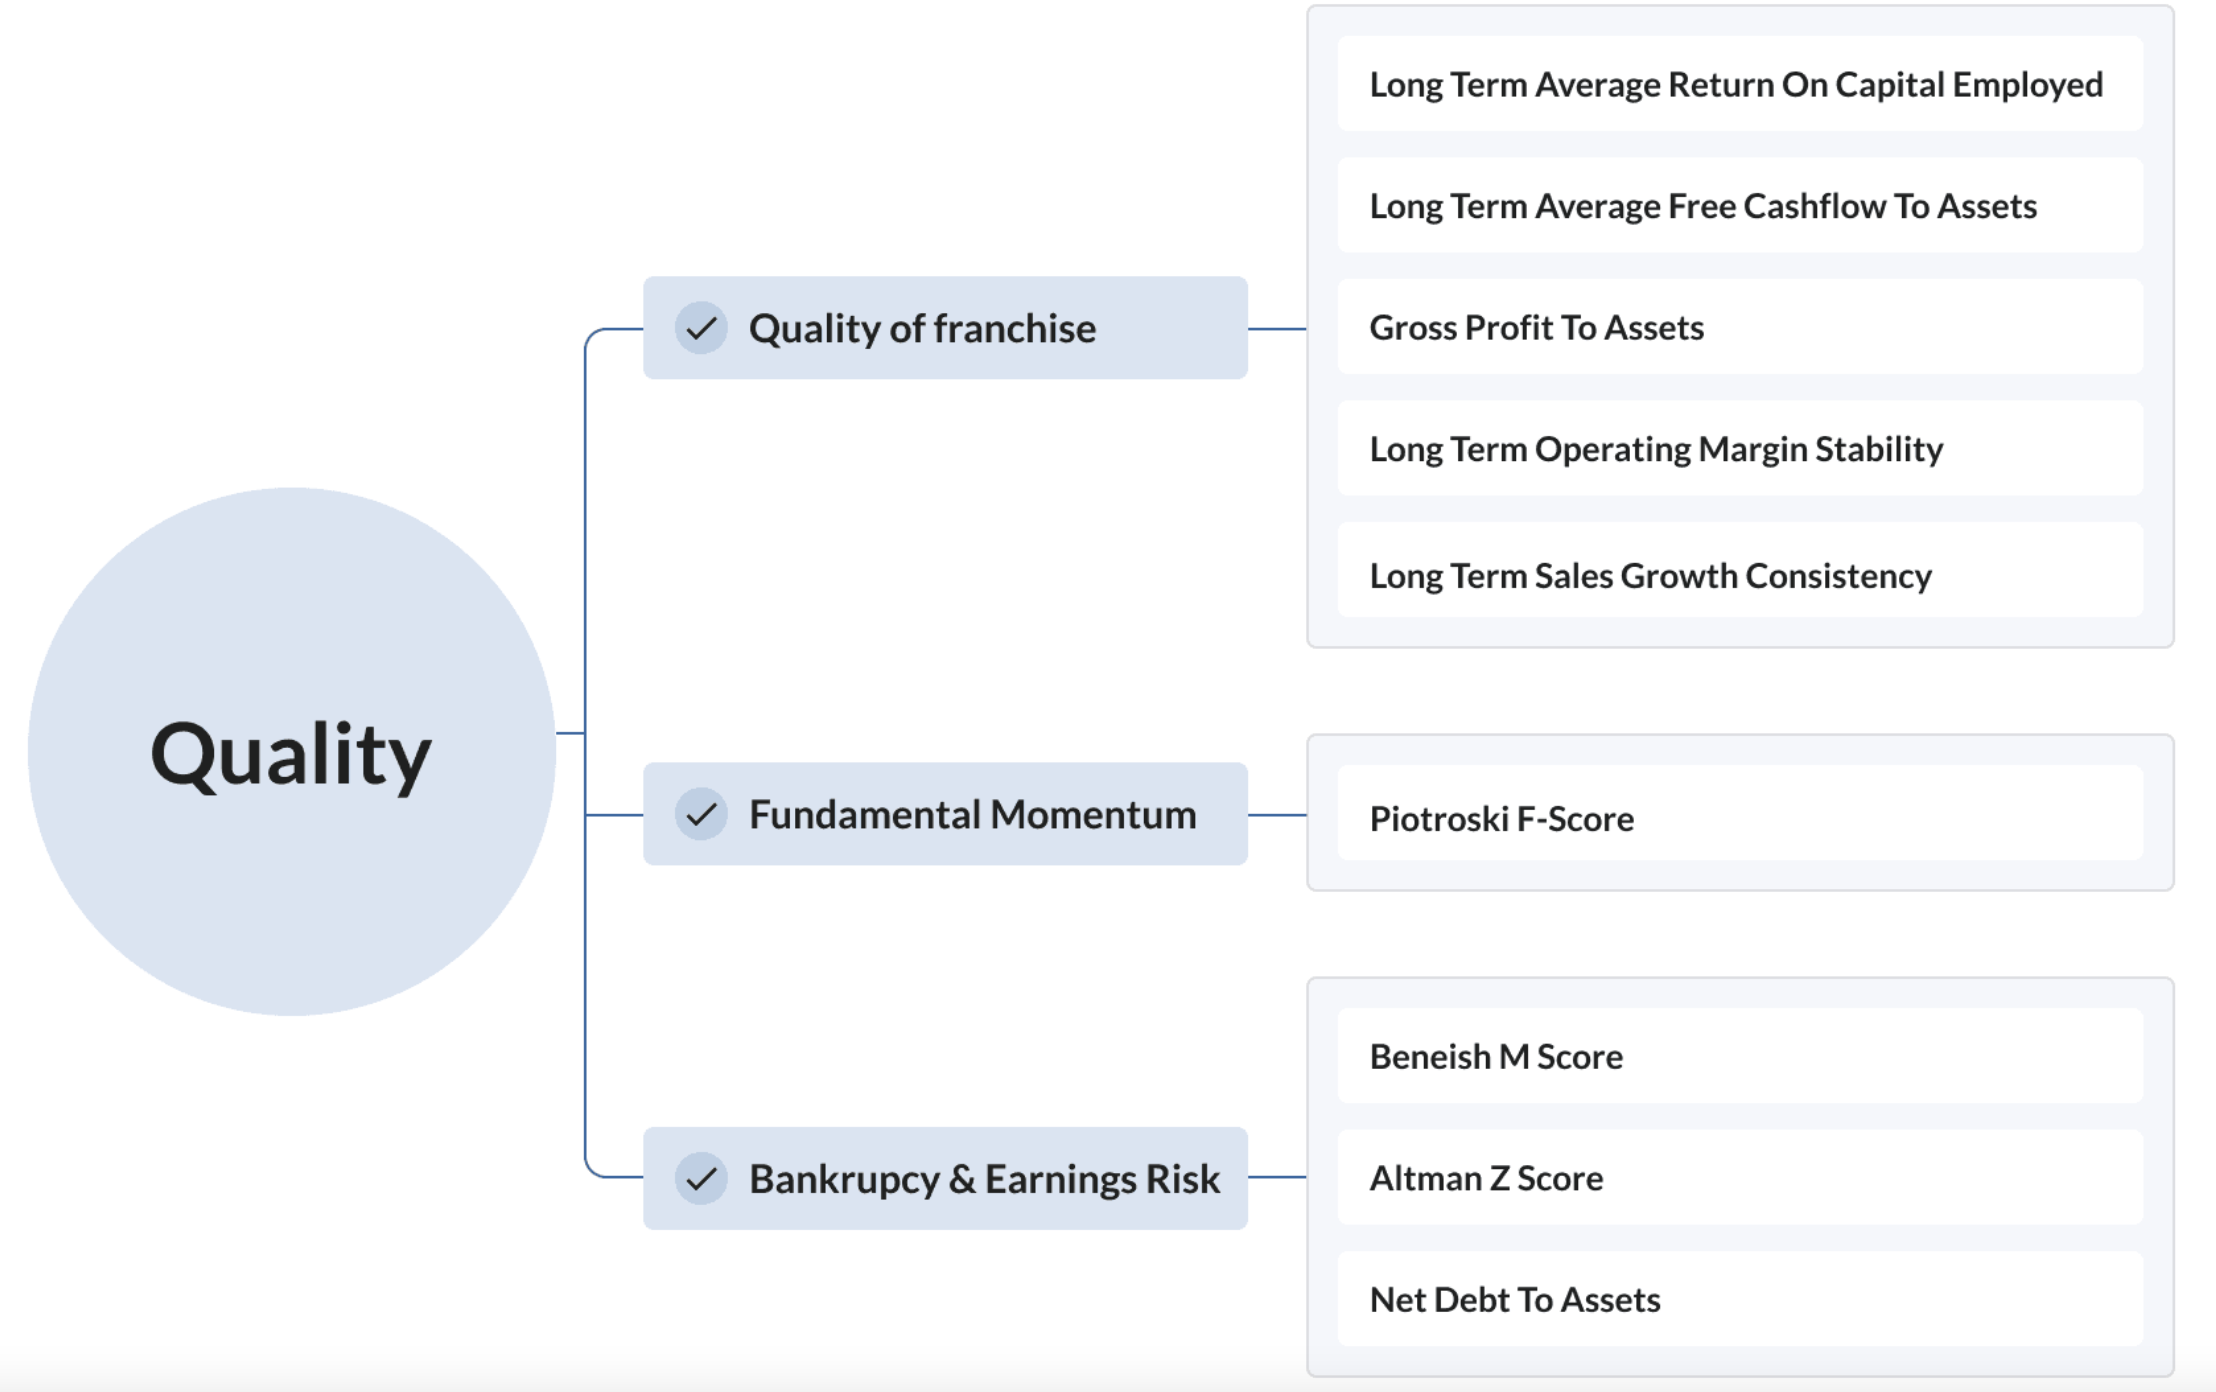
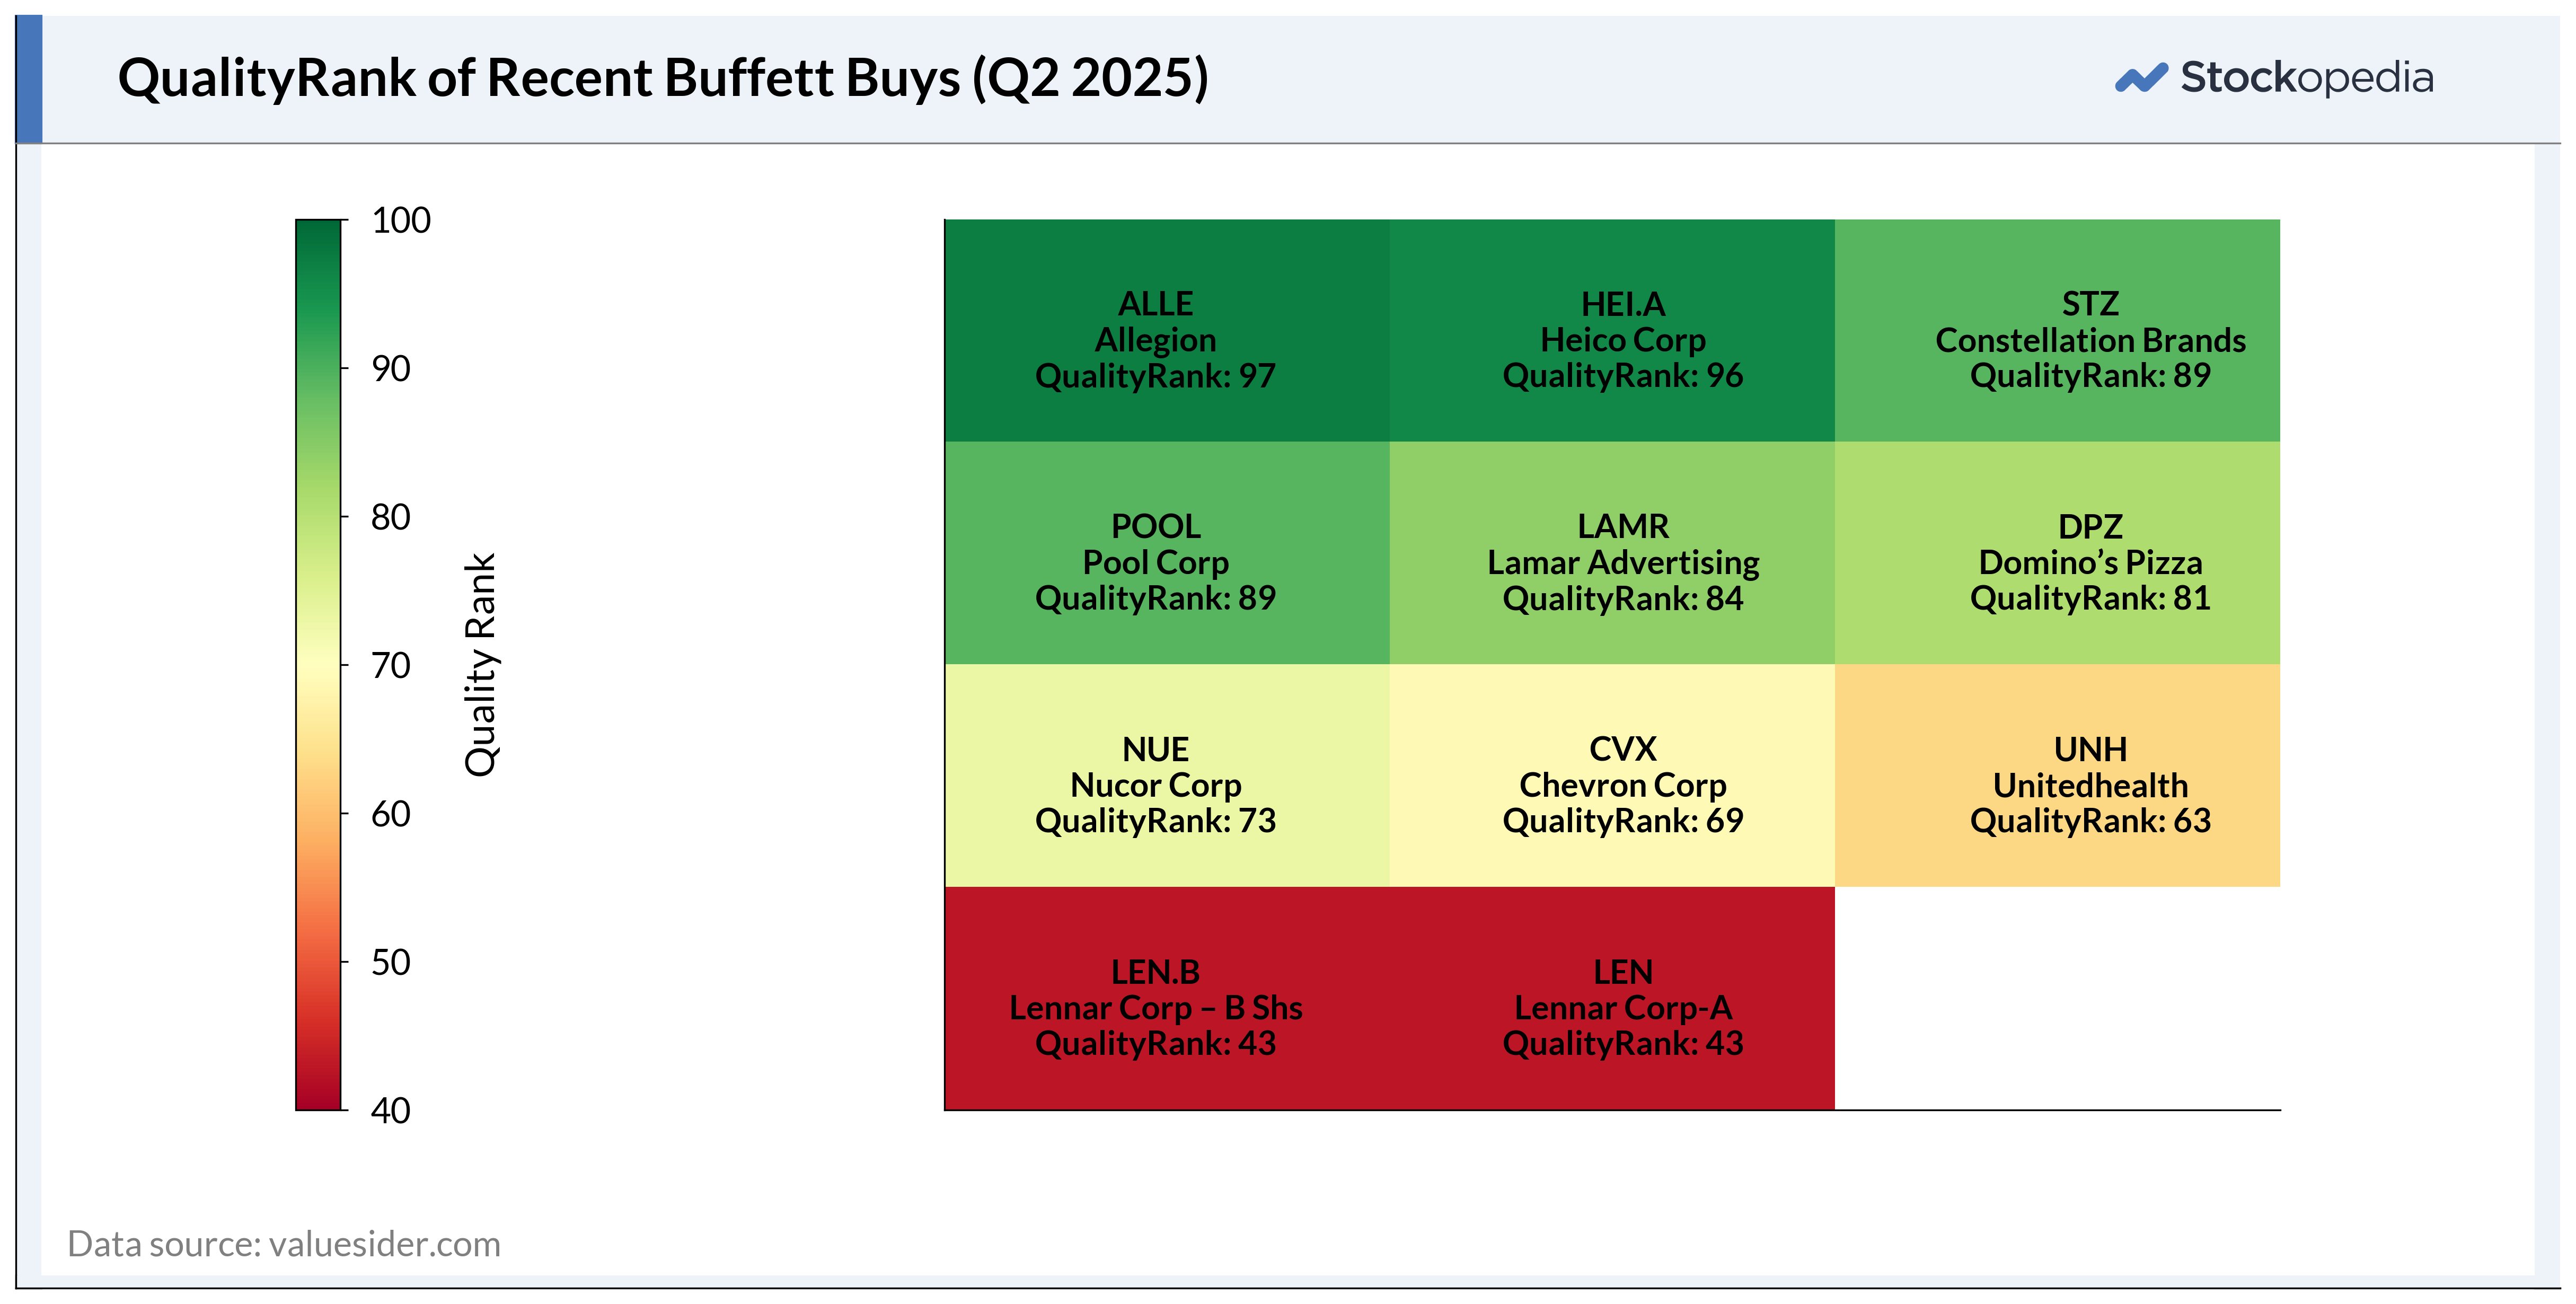
Warren’s recent stock purchases also reflect a tilt towards quality. We have our own method for assessing a company's exposure to the quality factor. Specifically, we calculate a QualityRank — a score from 0 to 100 — that rewards companies with strong profitability, healthy cash flow, and solid financial statements (see below). Buffett bought and/or increased his position in 11 companies in 2025 Q2. Only two of those currently have a low QualityRank (below 50).
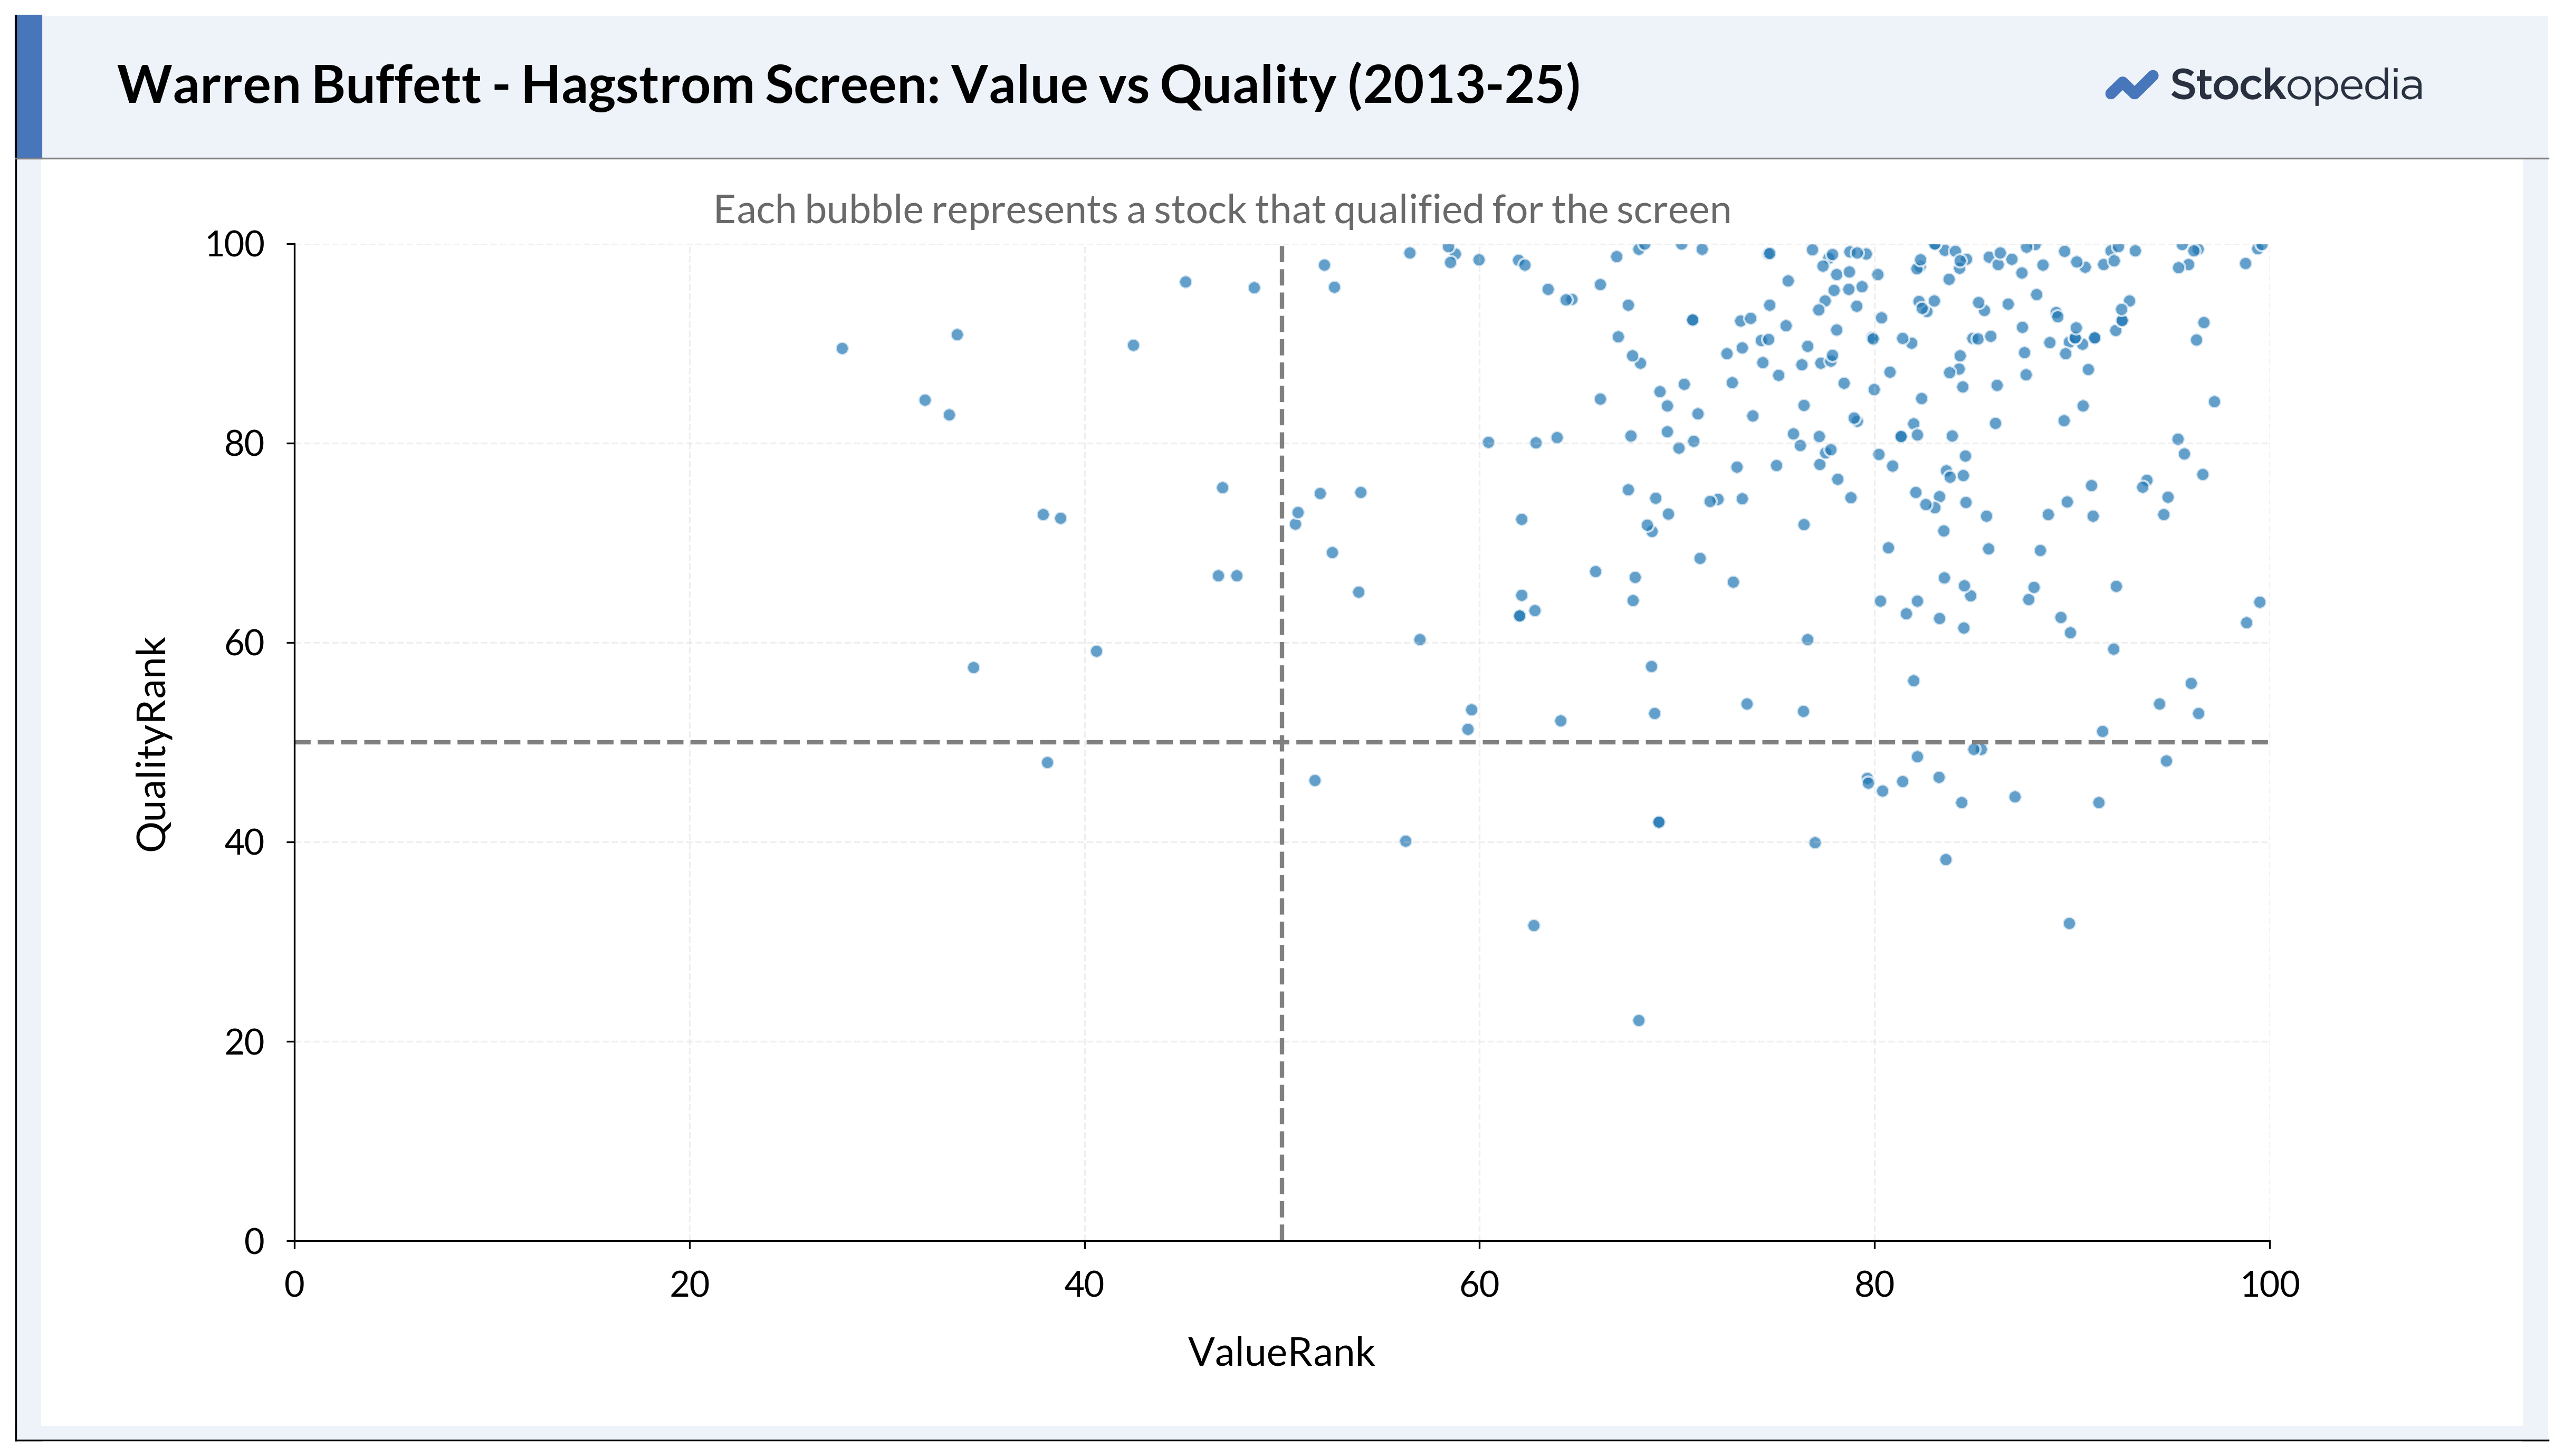
We also run a Buffett-esque GuruScreen. It based on Robert Hagstrom’s books, The Warren Buffett Way. Stocks which have qualified for the screen have had a tilt towards value and quality factors. We can see that the Buffett-style strategy is not random, like a coin-flipping contest. The screening process clearly hones in on stocks within a specific segment of the market.
The Courage to be Greedy when Others are Fearful
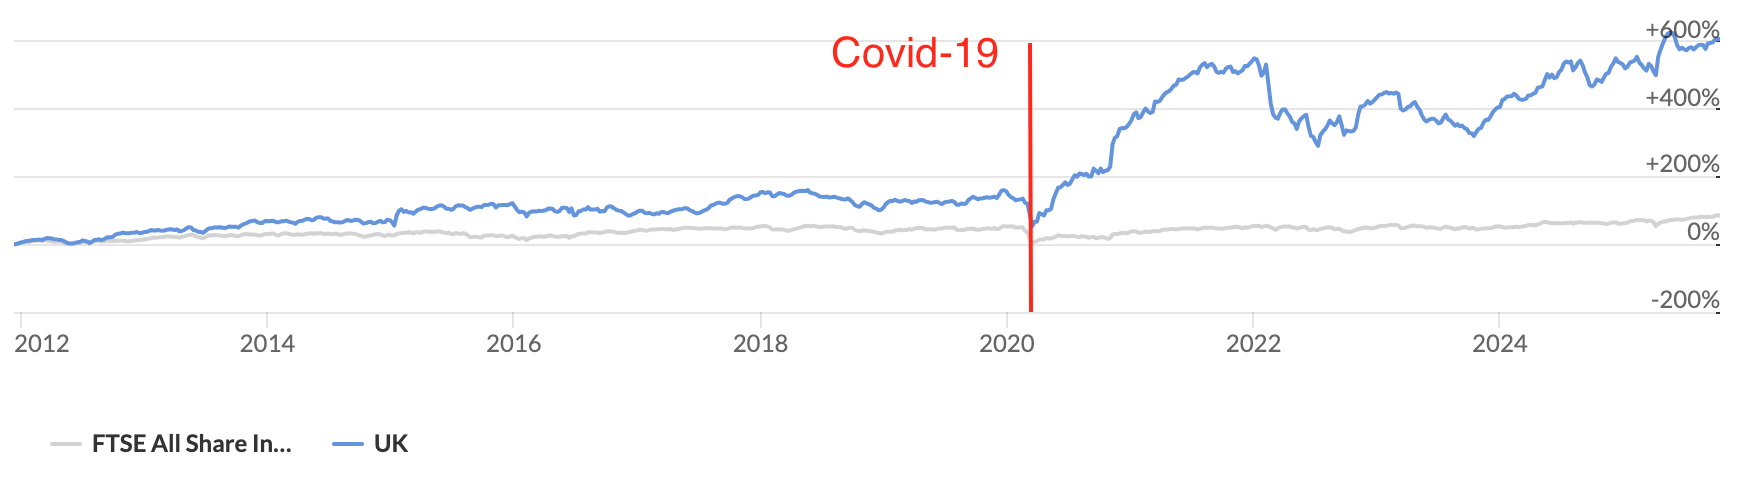
The Buffett-esque GuruScreen had a particularly strong period of outperformance during the pandemic. I can vividly remember those months, when it seemed like the market would keep going down and the world would end. I didn’t actually think it would end… but I acted as if it would. That is to say, I couldn’t bring myself to follow Buffett’s advice to be fearful when others are greedy and greedy when others are fearful.
I can remember looking at Go-Ahead (LON:GOG), the public transport provider. It was trading around ~570p, having dropped from ~2000p. It would eventually bounce back towards ~1300p. Somewhere in the back of my mind, I knew that transport companies would recover when everyone stopped self-isolating and started moving about again. But there was that voice in my head, whispering that the price might go down further. Of course, I let the opportunity slip…
This anecdote reminds me of something Mark Slater once said. He made his best investments when he felt scared and unsure. He made his worst investments when he was fully confident. This implies that the best time to get into stocks is, well, when the world is about to end.
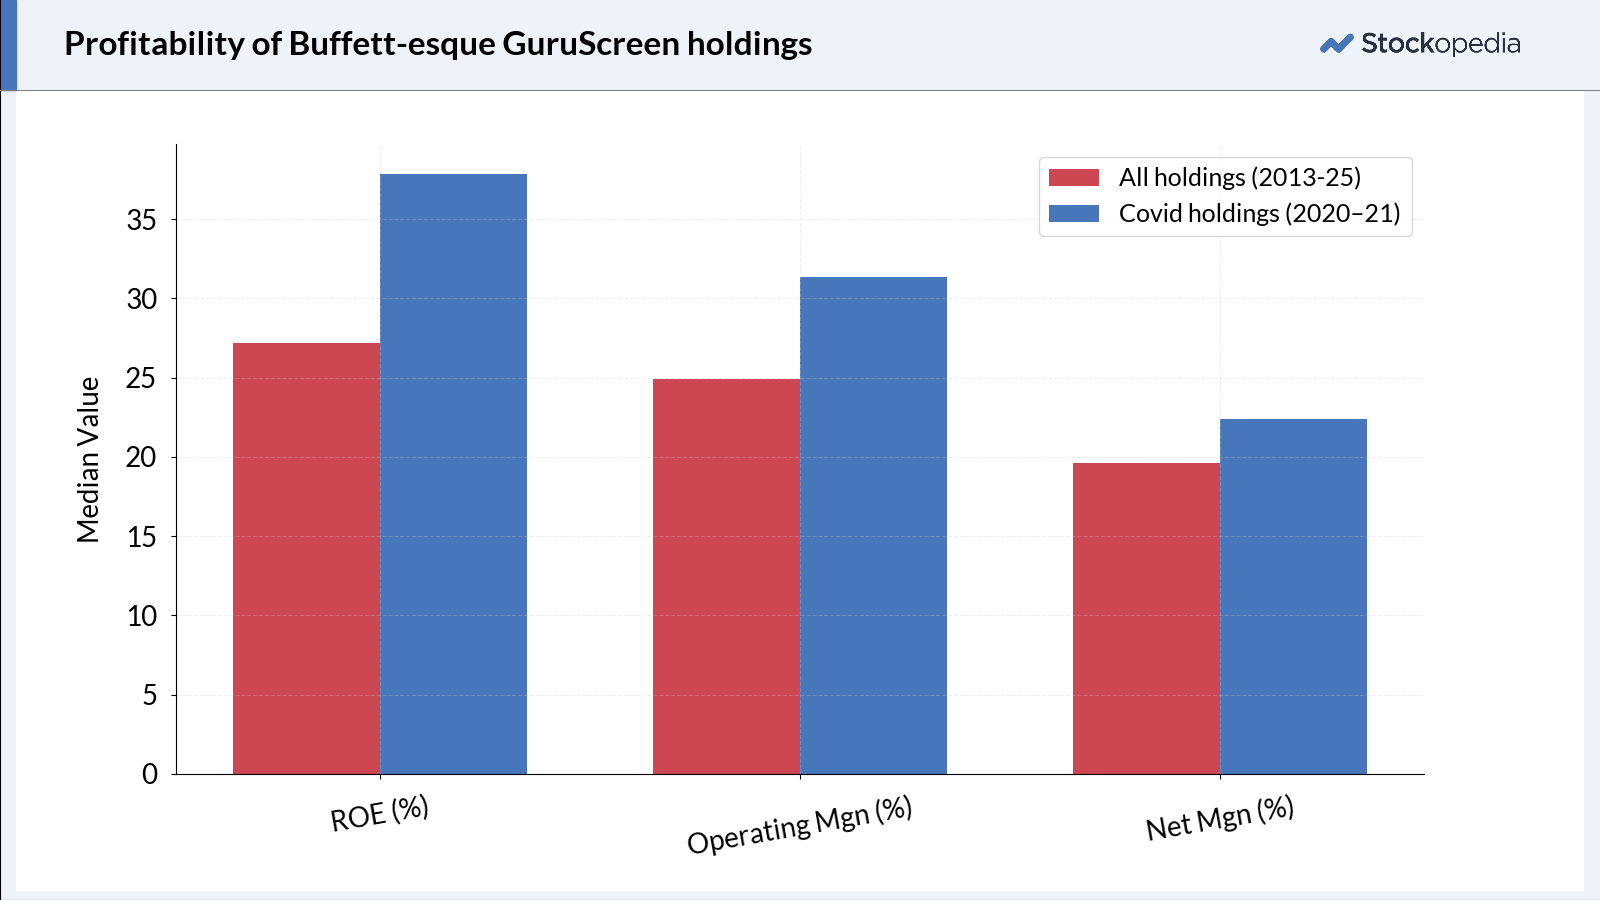
During the pandemic, stocks which qualified for the Buffett-esque GuruScreen tended to be more profitable. The screen selects for companies with a low price-to-free cash flow ratio. High-quality companies would have been marked down during Covid, enabling them to meet the screening criteria. For instance, the screen picked up Imperial Brands (LON:IMB). The company owns various tobacco brands, like Rizla, and has consistently commanded a solid return-on-equity. In January 2021, it had a P/E ratio of just ~8 and a P/FCF ratio of ~4, well below the market average. Back then, it traded around ~1500p. It now trades over ~3000p!
Conclusions and next steps
We often look at success stories and assume there's some complex magic behind their performance. In reality, their methods are conceptually simple, they're just difficult to implement in practice. Warren Buffett is a prime example. If you asked him what stocks he’s bought over the years, his answer wouldn’t be particularly ‘interesting.’ He’s invested in fairly mundane companies, like Coca-Cola and The Washington Post. These were cash generative, profitable, high-quality companies. But there’s nothing groundbreaking about what they do, and that’s exactly why they’re hard to buy in practice. Investors have to tell themselves that they’ll get rich by choosing boring blue-chips over companies that tell exciting stories about changing the world. And yet, it is these boring, profitable, high-quality businesses that tend to outperform the market.
In the final analysis, a few core principles can explain Buffett’s success. First, view a crisis as an opportunity. Buffett tended to be fearful when others are greedy and greedy when others are fearful. That is conceptually easy. We can imagine ourselves being that one person in the room, holding firm while Rome burns. In practice, that requires us to behave like the dog in the cartoon below. Most people jump ship when the best investment opportunity stares them in the face.
Secondly, research suggests that Buffett’s success can be largely explained by the principles of factor investing. Frazzini, Kabiller, and Pedersen found that Buffett achieved annual returns of 19%, with only about 6% being attributable to individual stock selection. The rest was explained by his exposure to well-known factors, like quality and value. Of course, Buffett still deserves credit for implementing a factor-based strategy long before factor investing was actually a thing. But at the end of the day, Warren ‘simply’ bought good companies at a good price.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Warren Buffett has also been consistent in his mantra to never bet against America. That is a part of his success.
Also when you consider the companies he has put together as a successful conglomerate (on top of the investment record), he might not look or act it but I would argue Mr Buffett and Mr Munger were highly extraordinary!
The article concentrates on stock selection which is only part of the equation behind the investment returns...
BH owns a well managed Insurance business which generates a significant free float which can be used for investment and lending. Using the float it is able to keep large cash reserves which enable BH to avoid fire sales and keep a long term investment horizon.
With significant cash reserves BH can also lend in times of stress - its track record of low risk profitable lending is a good one.
Also worth noting is that BH own a number of businesses outright which the individual investor would not be able to follow by stock selection.
These are just a few key factors which contribute to the BH success - it would be difficult/impossible for a private investor to replicate what BH has achieved purely by stock selection. Arguably, the best way for an individual investor to benefit from BH is to buy BRK.B
Arguably, the best way for an individual investor to benefit from BH is to buy BRK.B
i did look at buying the stock a few months back - the problem is if we have to pay a 25-50% premium above book value -then we arent getting the same good deal that the company is getting when its investing. As ever with quality company long term thats probbaly a complete red herring if that same premium now will exist in 25 years time- the returns should still be decent
as you highlight if he has access to close unlimited cash on tap when needed at low net cost - then that in itself is a very powerful tool - if one isnt silly with money one has.
probably nothing not to like here and apple excepted he has probably been very underweight on the big 5/6/7 tech companies that have probably generated a large % of stockmarket gains over the 15-20 years?. ok the big 5/6/7 as a group have probably out returned the BH - but i think we would all agree we knew BH would be doing fine now 15 years ago - ref the big tech companies that have done well we would probably have had less confidence soem might not have gone the way of blackberry and nokia for example ?
As far as I am aware you will always have paid a premium to hold BRK>B stock. Probably because it is so difficult to reproduce exactly the BH investment strategy. Its quite a unique company.
BRK.B has proved to be a very useful as an essential for the long term investor. It does not try to follow market trends such as AI,Dot.com etc. If you wanted a full exposure to these you might wish to use direct holdings or selective etfs.
If I was starting investing today on a lifetime buy and hold strategy ( 40 years) I would use etfs, BRK.B and gold as the basis for the portfolio. Would also probably incorporate a couple of general investment trusts and that would be it.
In my view the focus of these articles should be on BH as an investment vehicle rather than Buffett as a stockpicker. Far easier and more reliable outcome.
its very much common sense here - aided by the fact he has been able to do some great deals over the years.
must admit his comments about it being better to pay more for quality stocks should be ignored at ones peril - i look at one of my investments today Brickability (LON:BRCK) - its very much cheap for sure with p/e of under 6. but its perhaps not what i would call a quality business - its very much unproven as its added profits via acquisitions that need to prove themselves over the medium term. Hey ho only myself to blame if i go down the route of investing in less quality entities. Note perhaps i am being slightly harsh on myself here - brickability does have stock rank of 83 with great quality and value numbers - so its not flagging up as a sucker stock (at present).
As one who stays fully invested I was unable to do much more than invest small change on the 21st of March 2020, a date which is unforgettable being also the anniversary of my father's birthday and the first day of Spring. When opportunity knocks one cannot always get to the door in time.
Edit: Thinking about it, I reckon Buffett borrowed money whereas I've never borrowed to buy shares. I stood by last April and watched he Trump Slump which was a quick mini-Covid. Next time, I'll be ready to borrow money!