Hunting for compounders - Sigmaroc

Some high quality companies are admirably run but they’re not going anywhere fast. Then you have outfits like Sigmaroc (LON:SRC) .
It lacks a consistent track record, its accounts are littered with adjustments, and its Quality score is non-existent - but dig deeper and you’ll find an experienced management team with a clear vision assembling a construction materials company of substantial scale.
Five years ago SRC was a pitch, and then a cash shell. Today it is a £100m+ company expanding quickly into a c£500bn market, with a clear buy and build strategy and a strong pipeline of potential acquisitions.
It has some multi-billion pound large-cap incumbents in its crosshairs and there is a real sense of momentum here. The group is backed by solid institutional investors and has every chance of growing significantly in time.
I first looked at SRC here and saw enough to want to come back due to the sense of momentum about this company. The obvious red flag is a very poor Quality Rank but, if you believe in what this management team is doing, then what looks low-quality today might gloss over attractive underlying progress. Therein lies the risk and the reward.
Understanding Sigmaroc’s strategy and the competitive gap it has identified in the heavy construction materials market is key to grasping the opportunity here. It’s a market made up of concrete, asphalt blocks, cement, quarry aggregates, and related service companies.
The materials are cheap, heavy, and abundantly available. Importantly, transport cost is a key part of the overall price mix. This means proximity to market is an important driver of margin defence, so high-quality, well located assets have resilient margins. That’s point one.
Point two is that over the past 10 years there has been a period of consolidation in this sector, which is now reversing (per SRC management). Large businesses are not always good at running smaller, local operations.
This leads to a lack of ‘local-ness’. Think of the big network provider whose customer support function is on the other side of the world to its customers. This can develop into a fundamental weakness and allows nimble, smart, and ambitious new entrants to differentiate themselves on service.
That’s the opportunity for SRC. It can use this cycle of divestment to pick up attractive but mismanaged assets and improve them. These assets are well-located with resilient margins. Such a company could grow to be big quickly with the right management and investors.
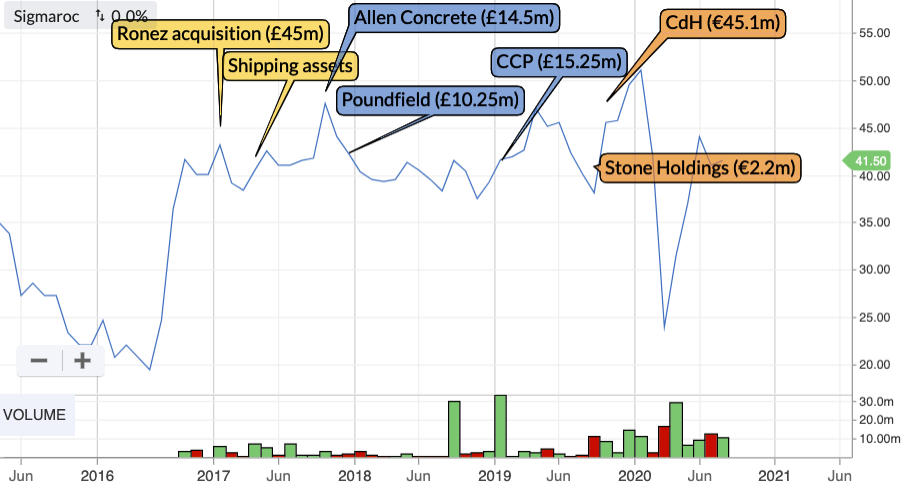
SRC acquisitions so far
That’s why I think this one is worth considering a little more deeply - there are obvious execution and shareholder dilution risks but the market is big and the potential upside is material.
Just compare SigmaRoc’s £102m market cap to listed competitors Breedon (£1,370m) and CRH (£23,900m) and you can see there is plenty of scope for growth...
A collection of asset-backed construction platforms
SRC seeks to create value by purchasing assets in fragmented construction materials markets. It assembles these assets into ‘platforms’ of 2-4 complimentary local businesses and then focuses on realising operational improvements and economies of scale across these platforms.
The ‘Buy and build’ strategy label is applied to a range of acquisitive businesses. Some work and some don’t. With SRC, at least, it does seem as though management is buying assets that become more valuable as part of its existing platforms.
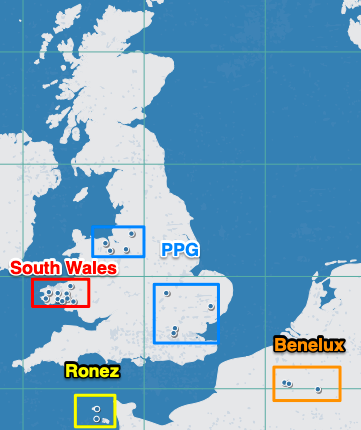
Since 2017, SRC has assembled four such platforms across the UK and Benelux.
- Ronez platform - SRC’s first key acquisition, completed on 5th January 2017, supplies the Channel Islands with aggregates, ready-mixed concrete, asphalt and precast concrete products. There is one quarry in Jersey and another in Guernsey, as well as SigmaGSY, which ships materials internally and to third parties.
- PPG platform - PPG manufactures precast concrete products. It includes Allen Concrete, which manufactures precast concrete products for the fencing and building industries, Poundfield Products, a leading manufacturer of precast concrete products with a portfolio of patents, and Cheshire Concrete Products (CCP), a supplier of concrete blocks and aggregates.
- South Wales platform - SRC’s 40% stake in GDH (with the option to purchase the remainder) is the cornerstone for SigmaRoc’s third Platform. There is also the high PSV Quarry, FoelFach. GDH is one of Wales’s largest independent suppliers of aggregates operating out of six quarries. Foelfach produces aggregates and supplies material internally to GDH as well as to outside customers.
- Benelux platform - Carrières du Hainaut (CDH) is the jewel in the crown of SRC’s Benelux platform, which also includes Stone Holdings. CDH produces aggregates and high quality Belgian blue stone - a high-grade dimension stone produced exclusively in Belgium under European protected status.
CEO Max Vermorken has suggested these platforms might max out at around £10-15m of EBITDA. One individual runs a platform, so this leads to a pretty flat business model with all autonomous platforms in direct contact with head office.
That suggests that SRC could become a £40-£60m EBITDA business by just maximising its existing platforms. Multiply that by CRH’s EV/EBITDA multiple of 8.24x and that suggests SRC should be aiming for an enterprise value of £330-£494m (compared to today’s c£150m). Keeping a constant mix of debt and equity implies a potential market cap of £218-£326m.
It is likely that additional platforms will be added to the company, so the potential future value is actually higher than this, assuming acquisitions are funded with a sensible mix of debt and equity.
Benelux: a statement of intent
SRC’s Benelux platform is its most recent platform and is an exciting case study in terms of how the company might generate value from acquisitions.
In Q3 of 2019 SRC expanded into Belgium ‘following many months of planning’ with the additions of Stone Holdings and Carrieres du Hainaut (CDH). CDH is the leading supplier of Belgian Blue Stone, which is a highly sought-after decorative stone used in infrastructure, housing and public spaces.
It recorded sales of €51.4m and an underlying EBITDA of €13.6m in 2019. Combined, CDH has approximately 200 million tonnes of aggregate and over 27 million cubic metres of dimension stone - enough for over 100 years of production at the current rate. Belgian Blue Stone remains undiscovered in many markets including the UK, but SRC has the commercial teams in place within its PPG Platform to change this.
This is just one example of how SRC can drive future growth across its platforms but there are other instances of potential cross-selling, operational gains, and scale benefits.
The pipeline
Here’s a recap of SRC’s key acquisitions so far:
Date | Asset | Acquisition cost | Underlying EBITDA multiple (company estimate) | Funding |
05/01/2017 | £45m | 9.0 | £40m new shares, £10m convertible loan | |
15/04/2017 | 2.5 | |||
19/10/2017 | £14.5m | 6.25 | Santander facility | |
13/12/2017 | £10.25m | 6.8 | New shares (41p) | |
25/01/2019 | £15.2m | 5.85 | New shares (41p), cash | |
11/09/2019 | €2.2m | 4.4 | New shares (50p), cash | |
15/10/2019 | €45.1m (enterprise value of €81.3m) | 6.8 | New shares (41p) |
That’s seven major acquisitions in around three years. There are clear risks in an aggressive buy and build strategy, but SRC is steered by an experienced management team and there is plenty of scope for further additions (as well as organic growth potential).
SRC’s pipeline of future deals comes from two sources: divestment programmes from major producers and private sales from independent suppliers. Both require significant expertise and due diligence in order to correctly identify value.
Independents and family businesses
There are about 15,000 of these in the UK and Europe, of which 500 or so fit the group’s investment and geographic criteria (of being maximum one hours’ flight from London). According to management, this equates to c£300m of EBITDA in the UK alone.
SRC adds value here through operational improvements and by refocusing on maximising shareholder value.
Major producers
According to Vermorken, there are four global players: Cemex, CRH, Heidelberg, and LafargeHolcim. All have expressed intentions to divest assets, generally in order to restructure balance sheets, as a result of competition, or because the operations are deemed non-core.
In these instances, SRC can add value to acquisitions by bringing a more entrepreneurial approach to what was formerly a highly centralised and bureaucratic process. Talented managers take ownership of their local businesses and a switch away from global branding to a more tailored, localised offering also drives results.
Board and culture
Directors have been consistently buying company stock as high as 50p, which is a promising sign.
The board and management team here are experienced and have worked together for many years. If SRC proves to be a success, a lot of that will be down to this team successfully executing its strategy so it’s worth covering their backgrounds in a little more detail.
Two of the three founders are still there.
CEO Mark Vermorken
From what I can tell, Max Vermorken is the driving force at SRC and has been the chief executive since 2016. Before SRC he was a strategic advisor to the CEO of LafargeHolcim and also has a private equity background, and so presumably has a solid handle on company valuation and capital profiles.
Executive chairman David Barrett
David co-founded SigmaRoc plc together with Max Vermorken and Charles Trigg. He is an expert in the industry, having previously co-founded London Concrete in 1997, which he expanded from one concrete plant in London to over a dozen.
Together, the board owns around 1% of the company. I’d like to see this a little higher, but directors have at least been actively participating in equity placings. Meanwhile the group has some solid institutional backers.
Still, the increase in share count is something to keep an eye on.
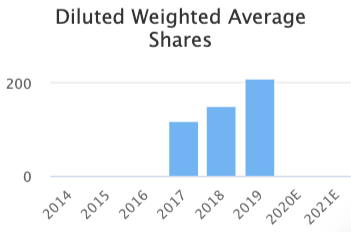
I expect further share placings to come but the hope is that all future acquisitions will be EPS-accretive on a diluted basis. How future deals are structured, and their valuations, will play an important part in creating or destroying shareholder value.
Risks
On that note, there are some clear risks for this fast-growing small cap that I’ll bullet point for brevity.
- Net debt position (that has since come down slightly over the lockdown period)
- An apparent lack of free cash flow generation
- Lack of comparability - rapid growth makes it harder to get a feel for underlying trade. Accounts are adjusted. The past is not necessarily reflective of SRC’s future.
- Poor Quality Rank, F-Score, Z-Score
- Further share dilution to come (probably)
- General macroeconomic risks (lockdowns, recessions, disrupted supply chains, etc.)
- Buy and build acquisition and integration risk
Conclusion
So SRC is not without risk and as always, DYOR. The company has yet to build up the type of consistent profitability that I usually look for but it could prove this in time.
Ultimately it comes down to whether or not you believe Vermorken et al have the nous and experience to assemble a large collection of quality, complimentary construction assets in the years ahead. From what I’ve seen, I think that’s possible.
Construction materials are consumed and produced locally, and, due to their high mass to price ratio, they tend to travel shorter distances to end customers than other commodities. This brings a particular dynamic to the sector, focussed on local and fragmented markets.
SRC understands that and is taking advantage of this important insight. It buys local businesses and lets local management run them. Product innovation, customer engagement and capex decisions are all driven by the local teams.
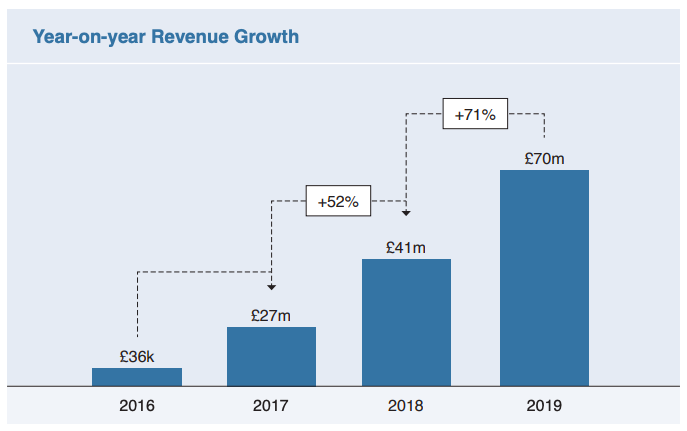
There’s a real sense of urgency here, too. In about three years, the management team has assembled a £100m asset-backed construction business with unique properties and strong market positions. It disclosed a net asset value of £102.0m at December 2019 - 40.2p per share - underpinned by property, plant and equipment worth £78.7m.
Some brokers are setting a 60p target price. I’d take that with a pinch of salt but it seems sensible to me in the short term, and I suspect management might be hoping for more in time.
With a large market to aim for and ample institutional backing, the upside is material. There are risks of course, but this is one stock with a clear strategy on how to become a significantly larger enterprise in the medium term.
I think SRC’s prospects seem healthy so I’ll continue to look into this stock and may take a small position if I can become comfortable with the red areas flagged up in its StockReport. Any views on this one are welcome.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
SRC rocks! Sorry couldn't help it
Thanks for your rigorous analysis Jack
Hi Jack,
Thanks for the article. I like this company too.
One further point to add is regarding the shareholders. Hermco Property Ltd is a 6.5% shareholder and this is backed by the former Exec Chairman of Breedon Aggregates (one of the biggest listed aggregates business on LSE). So "people in the know" are involved from an equity perspective.
I'd like to see them now start to deliver financially on some of their early investments such as Ronez etc. Am waiting to see this before adding personally.
The latest update indicated their like for like sales had not grown. "Comparing these results on a like-for-like basis adjusting for subsequent acquisitions, revenues recorded for the period were approximately 100% of revenues for the same period in 2019." https://www.stockopedia.com/share-prices/sigmaroc-LON:SRC/news/sigma-roc-plc-trading-update-urn:newsml:reuters.com:20200730:nRSd5376Ua
Very good article as always Jack. I'm a holder from 42p as I took some in the overhang. However a trade only for me so I'd be happy to lift around 50p!
On a safer level I have Travis Perkins Travis Perkins (LON:TPK) on watchlist. Great synopsis on Basic Materials (of the heavy kind). Infrastructure I think uses lots of this stuff as experienced by those companies 'bounce' after the Boris election. Why we did not keep 'safe distance' building in outside environments I will never know - and start putting roadworks up as soon as its 'get back to business'. Clown Town.
I can't afford to keep capital in 'long term growth' so a sector for another day. Maybe next week ......
Hi Jack
I invested early in Sigmaroc (LON:SRC) but exited and have not invested since. I was however, very taken with the business model and the company in general.
This Nov 2018 PiWorld/Mellor nid is an excellent introduction to the company as it was developing some 20 months ago.
Those interested might like to take a look, the CEO seemed to be well clued up.
https://www.piworld.co.uk/2018/12/06/sigmaroc-src-presentation-at-mello-london-november-2018/
Regards
Howard
Hi Howard, thanks for the Mello link.
I agree that Vermorken seems to be pretty switched on. PE background plus industry experience, with some long time sector specialists around him. I can see that team doing well in this space.
Was there any particular reason to do with Sigmaroc (LON:SRC) as to why you sold?
Hi Jack
I first bought 12/12/18 at 39.73p.
Sold out 12/07/19 at 44.00p.
But did several buys after my first buy following the price up. But a classic mistake, I was eroding my earlier gains by buying more expensively. I eroded myself back to break even and as the price was also falling so decided to step aside and watch Sigmaroc (LON:SRC) develop.
I did feel certain £SRC would develop into a good company though, so I am pleased to read your review of it.
I missed seeing its April rise so I will watch out to see if further momentum and volume begin to occur.
Regards
Howard