IG Group - Betting on the Underdog
At the time of publication, Graham has a long position in IG group (LON:IGG).
The Pitch
IG recently announced the acquisition of Underdog, a major US sports trading platform.
The news was met with dismay by the market:
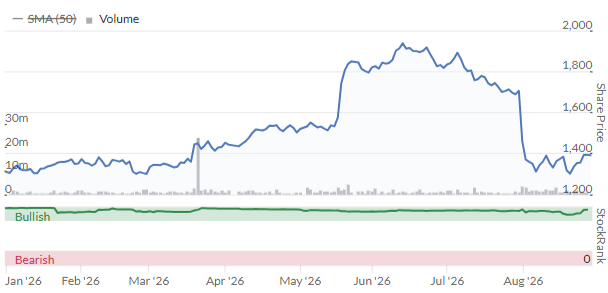
The company has 330 million shares outstanding; with the share price having fallen by over £3 since the news, that’s a fall in value of over £1 billion. Pretty impressive for an acquisition whose upfront consideration is only $1.1 billion (£810m).
In this stock pitch, I’m going to look at this acquisition and argue that while it is fraught with risk - especially the risk that IG is overpaying - the fall in IG’s share price more than fully reflects this risk.
The Big Picture
In the conference call on the day of the announcement, IG CEO Breon Corcoran said that during IG’s strategic review, they “looked at very many opportunities prioritising growth and innovation, and Underdog stood out”.
It is perhaps a coincidence - but perhaps not - that Breon Corcoran happens to be personally interested in Underdog via preferred shares and options, described as “approximately 0.4% of Underdog’s share capital”. With a max payment for Underdog shareholders, including earnout, of up to $1.3 billion, he could be in line to receive c. $5m from this transaction, which is more than his total earnings from IG in 2025.
It’s also worth highlighting that he has bought from Underdog’s co-founder and CEO Jeremy Levine before: when he was running Paddy Power Betfair, he acquired Levine’s fantasy sports business DRAFT for up to $48m, including earnouts.
This looks like DRAFT Mark 2: another acquisition of a Levine fantasy sports business, but on a much bigger scale.
The Rationale
IG is using its strong balance sheet - and its ability to print shares, with 60% of the $1.1 billion upfront consideration to be settled by new IGG shares - to aggressively advance into the US.
Not only will it massively increase IG’s US exposure - approximately doubling its revenue there - but it will also provide access to a younger demographic. According to IG’s presentation, it will lower their average customer age from 42 to 34.
This demographic is mobile-first, increasingly open to new forms of trading and betting, and is often keen to trade crypto and other financial assets. Underdog has about 1 million monthly active users. These accounts are primarily engaged in daily fantasy sports, which is considered to be skill-based and is therefore not a regulated gambling activity.
I think these survey results are important:
46% of Underdog customers have traded crypto previously
58% of Underdog customers have traded individual stocks
42% of Underdog customers said they like to fund their Underdog wallets with crypto.
While Underdog is very much sports-first, it’s easy to see why the customer base might be amenable to trading other products.
It has recently entered prediction markets, becoming the third-largest US operator. In a US context, prediction markets are typically structured as derivatives, and can be licensed and approved by the Commodity Futures Trading Commission. These markets involve traders buying and selling bets between themselves, rather than through a bookmaker.
Are IG overpaying?
Underdog generated $271m of net revenue in 2024, then $441m in 2025, and then $250m in the first six months of 2026.
EBITDA was negative until H1 2026, when it jumped to $59.6m. $46m of this was earned in Q2 alone.
With this sort of growth, a P/E or even an EV/EBITDA multiple doesn’t make a whole lot of sense.
For what it’s worth, if I annualise the EBITDA figure and use an enterprise value of $1,260m (the upfront consideration plus Underdog’s own debt, that IG will have to repay), I get an EV/EBITDA multiple of only around 7x (as Roland did). For such a rapidly growing business, this might not be excessive.
Note that IG may also pay a $200m earnout for 2026, depending on revenues achieved. There is no meaningful EBITDA requirement for this, so it is very unlikely to be self-funding.
On top of that, IG may pay an enormous management incentive plan to Underdog’s management team of up to $850m. This will require EBITDA of >$400m in 2028 and >$700m in 2029, and this one is said to be “self funded by Underdog’s earnings”.
I think there is considerable risk that IG are overpaying, especially considering that Underdog’s earnings until 2029 may be mostly headed in the direction of Underdog’s existing shareholders and management team. But it’s too soon to say that for sure.
The Bear Case
The explosion in prediction markets in the US has been driven by numerous factors but easily one of the biggest ones has been the deregulation trend spearheaded by the Trump administration.
Instead of being banned, prediction markets are being legitimised by the CFTC, bringing them into the mainstream and sparking an enormous boom in activity.
IG’s acquisition of Underdog assumes that Underdog will be able to expand into this new market, cooperating with IG’s other controversial US acquisition tastytrade to bring new products to millions of users.
However, there is no guarantee that this favourable regulatory environment will last forever. A new US president could change the leadership at the CFTC, which might then take a harsher line against the likes of Kalshi (and perhaps some day, Underdog).
The Bottom Line
This is a risky acquisition, and as an IG shareholder, I wish that it wasn’t happening.
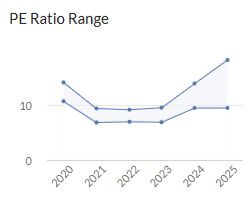
However, despite this, I think that IG’s current share price reflects the risks. Note that the P/E has fallen to only 10x:
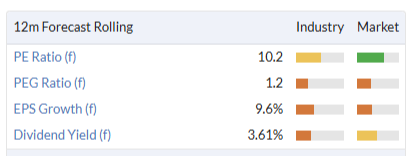
This is quite a normal multiple for IG. It has sometimes traded higher, and sometimes lower.
Paying for Underdog will require the creation of new IG shares worth over £400m, and the company will have to borrow to fund the 2026 earnout.
So there will be some dilution suffered by shareholders (less than 10%), and IG itself has become a riskier holding.
However, there is something to be said for increasing the company’s US exposure. Gaining access to a million US sports traders, and entering the US prediction markets through a well-known brand, is a gamble that could pay off.
As part of its strategic review, IG recently changed its corporate domicile to Jersey. My suggestion? A dual listing. I’d love to know how US investors would value this business. Interactive Brokers trades at over 30x earnings. Robinhood trades at over 40x. Would US investors think that a rating of only 10x makes sense for IG?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Excellent write up. While I know it was intended as a stock pitch it actually encouraged me to sell. I had bought a couple of weeks earlier on the basis the fall looked overdone. However, the more I look into this acquisition the more uncomfortable I am - the regulatory risk, the huge earnout, the conflict of interest with regards the CEO, and the fact this is still a very early stage market that might not be a big thing in a few years (and they are not even the main player in this market).
I can easily see this causing ongoing problems and distraction for IG - it is very different to what they currently do and don't see any obvious synergies. Also just anecdotlly I've been hearing a lot of complaints about the IG platform recently with a lot of disgruntled users - not looked into this and not sure which part of their business it effects or how bad it is, but something to keep in mind.
I am a holder in $IGG
I do worry that something will trip up the market for what is arguably a betting platform. Regulation is one serious factor. The other is a scandal possibly involving 'fixes' that undermines the rationale behind the randomness of prediction fundamentals.
Certainly the momentum behind the Trump era may be on the fade sooner rather than later after the US mid-terms, so could be a shift as referenced by Graham in the approval in principal of such platforms.
I must admit they don't appeal to me, though my 'betting' is constrained to Company investing through a regulated exchange.
I don’t think IG are in the same league as IBKR. They’re just not seriously operating as a tech business. Their platform is clunky, outdated and still doesn’t have half the breadth of IBKR.
At the risk of being a bit glib, the internet is consistently winner takes all: barely any point being the 5th best broker.
As a follow up not entirely sure if this is totally connected in terms of Underdog but here is the text of the Nevada outcome. The Robinhood share price tumbled 5% on the news. No idea if Nevada is an outlier in terms of Las Vegas etc but not positive for Underdog if there is a read across
Cheers
Martin
The Ninth Circuit Court of Appeals delivered a win for Nevada’s regulated sports betting industry Friday when a three-judge panel ruled that sports bets accepted by Kalshi are likely not swaps as determined by the Commodity Exchange Act.
The court rejected the arguments of prediction markets Kalshi, Crypto.com, and Robinhood, which asserted that federal law preempts state law.
Judge Ryan Nelson wrote that given “its broadest reading, the definition of a ‘swap’… might cover the sports event contracts here and thus preempt Nevada law. But that broad reading is not the best textual reading in context, does not square with the statutory scheme, does not have a limiting principle, and would raise concerns under the major-questions doctrine.”
The Major Questions Doctrine says that a federal agency must have explicit direction from Congress to decide an issue that is of major economic or political importance.
In April, the Third Circuit Court of Appeals ruled that New Jersey could not prohibit prediction markets from taking bets in that state. The conflicting rulings now set up a legal battle that is likely to land before the U.S. Supreme Court.
“We are pleased with the Ninth Circuit’s ruling today in favor of Nevada. This completely vindicates what we have been saying all along,” Nevada Gaming Control Board Chairman Mike Dreitzer said in a news release. “This is sports betting and needs to be properly regulated by the state.”
Gov. Joe Lombardo commended Dreitzer and the GCB “for their diligent work to uphold Nevada’s longstanding regulatory standards, safeguard the integrity of our gaming industry, and ensure the public can continue to have confidence in its oversight.”
In recent months, the GCB has attempted to enforce injunctions that prohibit Kalshi and other platforms from accepting bets.
The GCB was joined in the litigation by the Nevada Resort Association, which represents the state’s casinos. The NRA did not immediately respond to a request for comment
I am a US investor who holds IG shares.
For me, this acquisition raises a lot of questions.
The US tends to skew towards a dominant winner-take-all market. One only needs to look at how top-heavy the S&P 500 is or the relative outperformance of the S&P 500 vs. the Russell 2000. My concern here is that although Underdog is the third largest daily fantasy sports platform, what isn’t captured here is the chasm between the leaders in this space and everyone else.
FanDuel has 44% of the US market share and $6.9 billion in revenue, DraftKings has 34% of the market and $6.2 billion in revenue. Together, these two dominate the US market and have over 75% of the market share. There is another rapidly growing daily fantasy sports business here called PrizePicks with an estimated $1 billion in revenue. PrizePicks is private so it is harder to gauge, but it is growing rapidly. In the context of FanDuel, DraftKings, and PrizePicks, Underdog’s ~$500 million in revenue does not look quite as robust as other competitors in the market. It is anecdotal evidence, but in sports advertising, tv advertising, etc. the sports leagues have all been partnered with the larger players for a long time. As a US sports fan in the 25-44 demographic who receives an endless barrage of targeted sports bet-related advertising, I have never even heard of Underdog until this acquisition. That worries me.
Additionally, I can’t help but shake off the “coincidence” of how nice this deal works out for Corcoran. Shareholders are facing dilution while Corcoran can pocket a cool $5 million on the deal? It seems more to me like a nice way for Corcoran and an old colleague to profit off the time-honored tradition of over-paying for M&A.
Overall, I’ve been displeased with the strategic review. Although I certainly borrowed the idea from the Stockopedia team and it wasn’t my original thought - I was hoping for a dual US listing. This would have brought more visibility to US investors about the platform and services IG offers. I believe there was real low-hanging fruit here for multiple arbitrage - list in the US and suddenly your P/E can go from 10 to 20 to put you in the same orbit as IBKR. It’s hard not to feel the sting when a move that simple could have doubled the multiple with very little capital and is not fraught with nearly the same risk and uncertainty before IG now.
Thanks Graham ( I am long term holder of IG) and I share your concern about the amount of the earn out and if IG management is to close to Underdog to grasp the potential fall out. I commented at the time that such activities were more akin to gambling than investment. I accept I am hardly from Generation Z so maybe underestimating the ' meme' type psyschology at work here. To me it is OK whilst Trump and his cohorts are ruling the roost as this type of risk scenario is them all over. A more sober administration may take an entirely different view. I seem to think this market is one Plus 500 are looking at.
I agree and am surprised that IG has not listed in the US as to me this is becoming an entirely logical step. Maybe some from across the Pond will see value in all of this..........
On balance the risk given the share price fall looks to be on the upside so I am a HOLD
I
Great article, Graham, as ever.
Worth noting IG has been here before. When the tastytrade deal was announced in January 2021, the market took a couple of sessions to digest it properly, IG shares slid 13.3% over two days as investors ran the multiples and balked at the price (roughly 9x revenue versus IG's own 3.5x).
The market wasn't sure about that deal at the time, but four years on, the US division built around tastytrade now accounts for over a fifth of IG's revenue, and is set to reach 40% once Underdog completes.
This one definitely carries more risk, no argument there, but I wouldn't bet against this team's ability to integrate Underdog and monetise the new demographic over time. You go where the capital and growth is, and the US remains one of the deepest, and fastest-growing pools of both.
Great point on the peer comparisons too, IBKR and Robinhood are on vastly higher multiples in the US. Closer to home, flatexDEGIRO SE (ETR:FTK), the German-listed pan-European online broker of similar size, still trades on a 16.3x forward P/E versus IG's c.10x. IG definitely has room to catch up.
As an aside, it's nice to see a UK firm acquiring and making inroads into the US market rather than the other way around for once!