IG Group: Is the trend still our friend?

IG group (LON:IGG) is a stock that I’ve been involved with for quite a long time: over a decade.
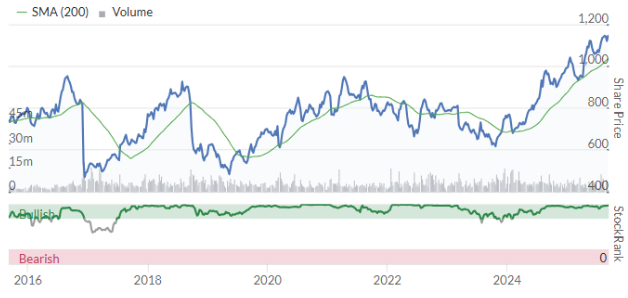
It has faced various challenges over this time, but the chart suggests that the company has been broadly successful:
It has paid a regular, and usually growing, stream of dividends for the past twenty years, which has been an important part of total return.
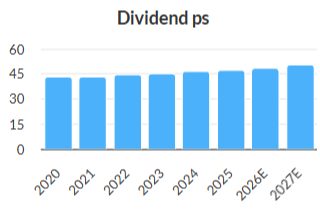
At today’s valuation, the yield is slightly over 4%, and the P/E ratio is 10x. Not bad for a stock trading at its all-time highs!
In this article, I'm going to explore why I remain a fan of this FTSE-250 stock.
History
IG has its origins in the 1970s and the exchange controls that prevented individuals from speculating on the price of gold.
In that environment, businessman Stuart Wheeler created Investors Gold Index, later shortened to IG Index. Customers could now trade on the price of gold using the innovation of spread betting, and of course it wasn’t long before the company expanded to offer spreads on a wide range of instruments.
The company continued to be called IG Index until 2012, when it dropped the “Index”.
Throughout its history, IG has been the main platform used by traders in the UK for spread betting and CFDs.
Modern profile
These days, IG is not just at home in the UK. It’s truly international, earning almost as much revenue in the APAC/Middle East region as it does in the UK. Here is the revenue breakdown for FY May 2025:
UK and Ireland: £297m
APAC/Middle East £259m
US: £166m
Europe: £134m
Institutional and Emerging Markets: £87m
Core to the business is what it refers to as “OTC” (over-the-counter). This refers to trading in instruments away from exchanges and in the case of IG means the products that it has designed itself, i.e. the various instruments on its spread betting platforms.
The beauty of this business is that IG charges customers a spread, but it often doesn’t have to pay a spread of its own. The reason for this is (in the words of its most recent Annual Report), "the vast majority of trades offset as customers take opposing positions”.
This results in something called “Internalisation”: there are long customers and short customers, their exposures offset each other, and IG doesn’t even need to make a trade on a real exchange in order to hedge its risk. It only needs to hedge its net exposure, which is far smaller than the gross exposures taken on by traders.
The risk management policy is important to quote here, as it’s key to how the business operates (emphasis added by me):
External hedging – once trades have been offset, we are left with residual market risk, which we manage within Board-approved tolerance levels. If exposure approaches our limit, we begin hedging passively to reduce our risk. In the event that we reach this limit, we hedge aggressively to eliminate additional exposure. Our market risk management model aligns IG with our customers. Our revenue is driven by spread, commission and overnight funding charges, it is not driven by client losses. We want our customers to trade successfully and we invest in content, education and tools to help them do so.
I should add that even if IG does want its customers to trade profitably, most of them do not. According to its latest legally-mandated disclosure, 74% of retail investor accounts lose money on spread bets and CFDs with IG.
While acknowledging that most retail traders lose money, I feel obliged to mention that this statistic makes no allowance for retail traders who might be using IG for hedging purposes, e.g. taking on a currency position to offset a real-world exposure, or shorting equities to hedge a real-world position that is uncomfortably large but cannot be immediately sold.
While the number of people who do that as a percentage of the customer base might be small, their loss-making trades would still have been financially useful for them, from a risk point of view!
Beyond “OTC”, IG’s major product categories are:
Futures and options, particularly in the US where IG owns the retail option trading platform tastytrade (more on this later).
Stock trading and investments, which has grown recently thanks to an acquisition (Freetrade) although IG already had its own share dealing platform.
Crypto is a recent development but IG does offer crypto trading in both the UK and US across a range of cryptocurrencies.
Content and education is also classified as a product. tastytrade has had TV-like channels for years, and UK customers can watch IG Live.
OTC is a highly profitable business by its nature, due to the spreads, commissions and financing charges that customers generate, often accompanied by frequent trading activity.
Stock trading and investments is a more stable type of business, but also much less profitable per customer.
In the UK and Ireland, for example, the average share dealing customer generated only £389 of revenue in FY 2025 (excluding Freetrade).
The corresponding average revenue figure for OTC was £5,194.
Former Management and a large US acquisition
For five important years, IG was managed by CEO June Felix, an American who oversaw the $1 billion acquisition of tastytrade in 2021.
This acquisition concerned me, as IG had grown successfully through organic means until this point.
Also, 2021 was the height of post-Covid trading hysteria, and I feared that IG was overpaying at the height of a boom. How long until US retail traders realised that option trading was harder and less profitable than it looked?
The deal valued tastytrade at 20x trailing PBT.
On top of that, it resulted in substantial share issuance. 61 million new shares were printed, giving tastytrade shareholders 14% of the group.
I’m still a little sceptical about whether IG got value from this takeover. Total US revenue has been on a pleasant upward trend (£166m in FY25 vs. £143m in FY24), but considering the amount that was invested in this division, I remain to be convinced that it has been a highly profitable transaction.
Overall, however, I was happy being a shareholder in IG during June Felix’s tenure, and I was sad to see her leave the company for health reasons in 2023.
New management and a more modest acquisition
I’m always going to be a little biased in favour of someone who received the exact same degree, in the same university, as I did.
With that disclaimer out of the way, I can say that I have been extremely impressed by the hire of Breon Corcoran.
His CV struck me as highly appropriate from day one, seeing as he was the mastermind behind the merger of Paddy Power and Betfair (having been the COO of the former and the CEO of the latter). He then became CEO of the combined entity, which is today known as Flutter Entertainment (LON:FLTR) - a highly successful company for its investors.
In some ways, this appointment struck me as a return to the company’s roots.
Prior to June Felix, IG had been managed by individuals who had served IG for many years and were steeped in the culture of British spread betting.
Felix was different: she was an American with fintech expertise.
But now with Breon Corcoran, IG is managed again by someone with a very deep understanding of gambling and speculation. He has managed both a large-scale bookmaker and a large-scale betting exchange, operations that are clearly adjacent to IG.
My only concern with Mr. Corcoran is the possibility that he might seek to engineer another large merger, and the potential that such a mega-deal could go wrong. But so far at least, he has shown no signs of seeking to do that.
Instead, he has overseen a reassuringly small acquisition: Freetrade, purchased for “only” £160m.
At its most recent full-year results, IG reported a cash balance of nearly £1.1 billion. After-tax profits were £380m (up from £308m the prior year). So that is the context in which I say that Freetrade “only” cost £160m: it was easily affordable from IG’s existing cash balances and from its ongoing profitability.
Freetrade signals IG’s intent to grow its UK presence further and to improve its share dealing proposition. With this acquisition, IG picked up 457,000 customers very cheaply: the challenge will be to motivate these individuals to step up their activity levels.
Despite having nearly half a million customers, Freetrade only generated £29m of revenue in FY25 (£64 of revenue per customer). So this is not a very impressive business currently, in my view. But at a £160m price tag, IG does not need to suddenly perform miracles, to make this deal a success.
What are the risks?
I think there are two main risks at IG.
1. Regulation
The first risk is one with which investors in this sector will be very familiar: regulatory risk. This one will never go away.
However, my view is that the regulatory situation in the UK is settled for the foreseeable future. I cannot speak with confidence about other jurisdictions, although I would be very surprised if anything were to happen in the US that would prevent retail investors from punting money on options!
In the UK, the industry came under EU rules on leverage and protections for retail traders back in 2018.
That might seem a long time ago, but these were seismic changes that put very strict caps on leverage and also introduced negative balance protection for the first time, so that traders couldn’t owe more than they had deposited with their trading platform.
Even after Brexit, these rules have been replicated and kept in force by the FCA.
My view is that with these rules and restrictions in place, spread betting is not going to be a priority for the FCA for the foreseeable future. I believe that, if left to its own devices, the UK would not have introduced these regulations in the first place.
And so personally I doubt that there will be any push for additional regulations: the existing rules already do a fine job of protecting retail investors from themselves. Negative balance protection means that a trader’s liability is firmly limited to the actual cash they are willing to put at risk in their trading account, and not a penny more.
2. Decline in activity
The other major risk faced by IG’s shareholders is less exciting and is actually inevitable: the risk that customer trading activity declines.
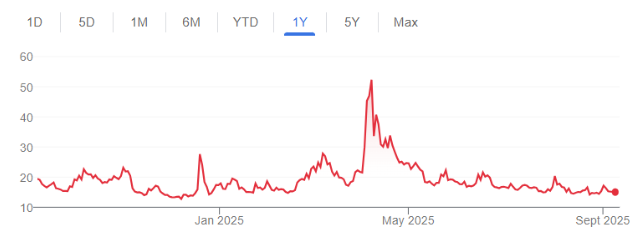
The main indicator to check here is the VIX (Volatility Index), as it’s the best way to check the propensity for traders to be active. A high VIX means that markets are expected to be volatile, according to option pricing.
A high VIX typically means that markets are moving fast, and nothing gets traders active more than fast-moving markets!
Trump has been a positive influence for those who love volatility:
Zooming out to a 5-year view shows how unusual the recent spike was (though the spikes in 2008 and 2020 were higher again):
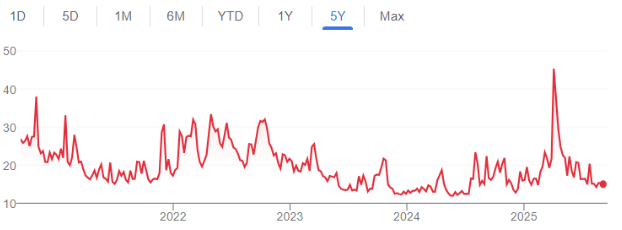
Of course there is no way of knowing what the next “Black Swan” event might be, and when it might occur.
IG’s most recent financial year ran to the end of May 2025, so it included the peak volatility period relating to Trump’s tariff announcements.
Therefore there is every possibility that FY May 2026 will be a quieter year, and revenues and profits might decline to a more “normal” level.
For context, IG’s FY 2024 revenue was £852m, and PBT was £401m, compared to revenues of £949m and PBT of £499m in FY 2025.
Estimates in the market currently suggest that the company is on track for revenues of £1.1 billion and PBT of £506m in FY 2026.
So I can accept that there is a little bit of downside risk to these forecasts, if volatility stays at lower levels for most of the year.
However, for now - to answer the question in the title - I would say that the trend is still our friend at IG. It has been a great performer for its investors and its StockRank today is 97, including a MomentumRank of 79. So it qualifies as a Super Stock.
There is competition from CMC Markets (LON:CMCX) and Plus500 (LON:PLUS), but these haven’t prevented IG from being highly profitable and enjoying the benefits of heightened trading activity. While Plus500 has increasingly targeted high-value customers such as those who use IG, I expect that IG will remain the default choice for high-value customers in the UK. Outside of the UK, the competition between the two companies is less direct (e.g. they have very different US operations).
To summarise my view: I view IG as a company of the highest quality, with a commanding market position, credible management, a healthy financial position, and a high degree of shareholder orientation as evidenced by its track record of dividends and buybacks. At a P/E multiple of 10x and a 4% yield, I do not yet have any concerns that it has overheated.
As my first boss said to me: The trend is your friend… until it ends!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

15 comments
Surprised that no mention of a possible budget gambling tax.
CMC Markets ... 70% of retail investor accounts lose money when spread betting and/or trading CFDs with this provider
IG ... 69% of retail investor accounts lose money when trading spread bets and CFDs with this provider.
PLUS 500 ... 80% of retail investor accounts lose money when trading CFDs with this provider.
Thank you Graham for an excellent nd vertpy clear articulation on IG This has also been one of my long term holdings I first bought the stock in a bit of a slump with a dividend yield that year of 19 or 11% div yield and have topped up several times whenever the divi looked appealing Thank you for giving a vote of confidence to my choice of investment
Probably a bit disingenuous of IG group (LON:IGG) CEO to say they "want their customers to trade successfully". If all their customers made money on their trades, IG group (LON:IGG) would haven to cover all the successful trades instead of offsetting them against each other. Then they would quickly go bust.
IG group (LON:IGG) With 43% operating margins, I am surprised that IG is so cheap. Money literally grows on trees for them. I would expect a stock like that to trade on a PE of around 20.
It doesn't
IG group (LON:IGG) Be careful shorting with IG group.
If the short suspends its listing because it has gone bust (which is what you want) IG will just keep the short at the suspension price. I had one that was stuck like that for 4 years. IG wouldn't close the bet.
Hi Graham, thanks for this excellent insight, you've increased my knowledge significantly.
Given the lower levels of profitability from share trading what do you think of IG group (LON:IGG) expanding in this area? Why are they, is it a sprat to catch a mackerel or risk diversification for example?
I bought shares in IG in Feb 2018 at 766p. They have spent many a year going sideways, although they have come good of late. It just goes to show that sometimes you need a lot of patience.
Worth noting that over 5 years revenues and EPS have been growing at 10% pa. I'd say that that was impressive. Longer-term its revenues and EPS has more than doubled over 10 years. This is something I look for when assessing growth.
Its ROCE is 23%, operating margins 45%; it's a good business. Stocko's Q score is 99. It looks cheap, with a fwd PE of 10, EV/EBITDA less than 6 and P/FCF of 8.3.
It fits my criteria for QGARP. I still hold.
Over 20 years, the share price has been increasing at around 10.4%pa. It's difficult to gauge dividend yield over that period, but it seems generally in excess of 4%. So shareholders were getting something like a 15% total return pa over than 20 year period. Not bad. Not bad at all.
Interactive Brokers (NSQ:IBKR) doing well atm.
Well US market on fire. Can sit and watch the fireworks or be involved.
The choice is yours.
Thanks for the write up of IG group (LON:IGG). I originally bought in 2017 and it's now my oldest stock pick that I still own. I topped up in March 2020 at Covid lows when I was only buying quality stocks that I really, really believed would still be there after the pandemic (eg Shell). I believe it's a quality company, also shown by it's quality rank, paying decent divis and acts a hedge in volatile times, as business picks up with the VIX up.
Having read your article, I checked the Stock Report and I can see that it's been on a good run recently. Just two years ago it was on a PE of 6 and Yielded 7%. I’m no chartist, but over the last ten years it has tested the 1000p ceiling four times, finally breaking through at the start of this year. Maybe a nice round 1000p will act as a floor from now on? When it does pull back, as all stocks inevitably do, I would be tempted to top up if it's not caused by a specific company issue.
My original holding has also seen a 378p per share divi which helps keep me happy. Over my investment time I have tended to move from story stocks to divi paying quality (most of the time!). It must be the Stockopedia Effect ;)
Thanks Graham - very helpful article. I hold and was wondering whether to top slice as the share price has done very well lately so will chew it over.
I'm in the process of moving my Mum's ISA from Lloyds Banking (LON:LLOY) to IG group (LON:IGG) as the IG ISA is cheaper to run and more flexible:
- It's a flexi ISA which Lloyds isn't
- Dealing commission £0 at IG and £8 at Lloyds
- Cash holdings get BOE bank rate interest at IG, zero at Lloyds
I did warn my 86 year old Mum not to be tempted to open a Spread Betting account with them!
IG group (LON:IGG) l have used for about 5 years now, they are ok generally, until something goes wrong, then they are completely useless. Took me months to get my money back with a ETF delisting, there have been similar reports. But they have free trading on UK shares and pay interest now.
Very funny. Every evening I say to my 88 year old mother "Let's see how our investments have done, do you think we'll have made any money?", to which her deadpan and certain reply is always "I doubt it".
I might mention spread betting to her as a way she might get rich quick.
At her age I should think she needs to get rich quick, although the same might go for myself!