Income portfolios revisited: the good, the bad and the ugly

It is coming up to a year since I wrote about income strategies. It is a good time to review their performance. In the first article in the series, I examined the evidence for income investing. I concluded that the historical data suggests a pure income strategy might be a sub-optimal investment method. However, creating an earnings-based value strategy and then investing in the subset of stocks with a high dividend yield will likely generate high performance and deliver an above-average yield over the long term. I suggested that the income investor would be better off screening for value picks and then choosing the highest-yielding of those.
The Income Portfolio
In the second article, I created a screen and an example portfolio. In order to build some diversification into the portfolio (and avoid what would have been a very concentrated bet on the UK housebuilders), I chose a few stocks from each industry sector from the screen results. This gave a 40-stock portfolio.
So, how has it performed? Not that great, if I am being honest:

After a decent start over the first few months, the portfolio never really bounced with the general UK market in April this year. This leaves the income portfolio clinging to a profit while the general market delivered an 8% return. One takeover, Civitas, was not included in the above results, but given that this is a 40-stock portfolio and the premium was relatively modest, this didn’t change the outcome.
However, it is worth noting that this hasn’t been a great period for value investors, with the Top Value Rank Stocks losing 13% over the same period:

So, a comparison with other similar value portfolios may show this income portfolio in a slightly better light. As others have pointed out in the past, the underperformance of a high Value Rank stock portfolio is primarily a function of their weighting to smaller stocks. It may be tempting to think one must only build an income portfolio from the largest stocks, but I believe this would be a mistake. Extended periods where large cap stocks beat small caps are rare, and if the scenario were reversed, we would be saying it was wise to choose smaller stocks. In reality, I believe a mix of different-sized companies makes sense. What larger caps may give is a more internally diversified business. It is worth considering this, but the beauty of being an equity investor is that you don't need to own conglomerates to gain diversification. Investors can simply build diversification in at the portfolio level.
Given that this was an income portfolio that started with a 9.1% forecast dividend yield, you’d also expect the bulk of the returns to come from that yield. In light of this, the biggest disappointment is that the TTM yield of the portfolio is now 5.9%. It’s not terrible, even in current markets, but low compared to the starting point.
Four companies cancelled their dividend altogether:
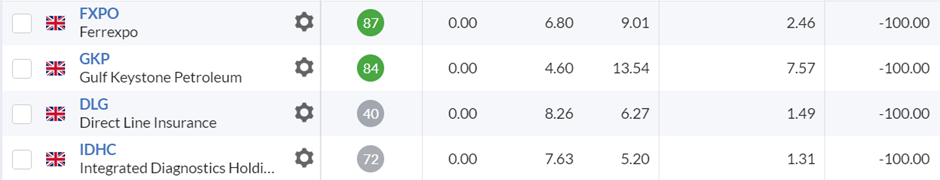
Notably, three of these four stocks suffer from high political risk. Gulf Keystone Petroleum (LON:GKP) is subject to the vagaries of Iraqi/Kurdistan politics, Ferrexpo (LON:FXPO) operates in a country at war, and Integrated Diagnostics Holdings (LON:IDHC) operates in the Middle East and Africa with operations in Egypt, Jordan, Sudan and Nigeria.
Unsurprisingly, these companies have been among the weakest performers in the portfolio:
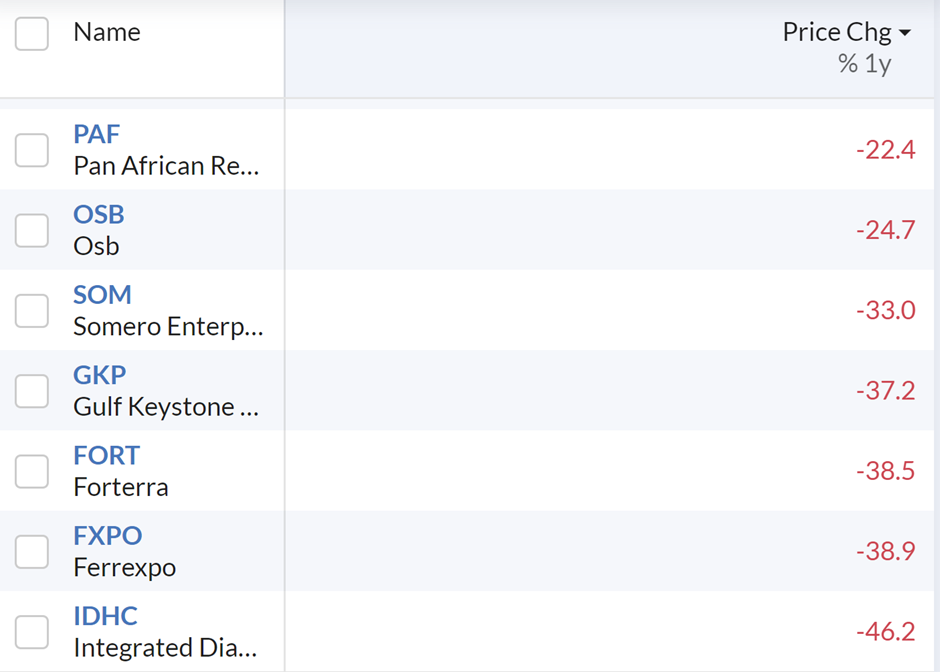
On top of this, nine companies appear to have cut their dividends or are forecast to do so:
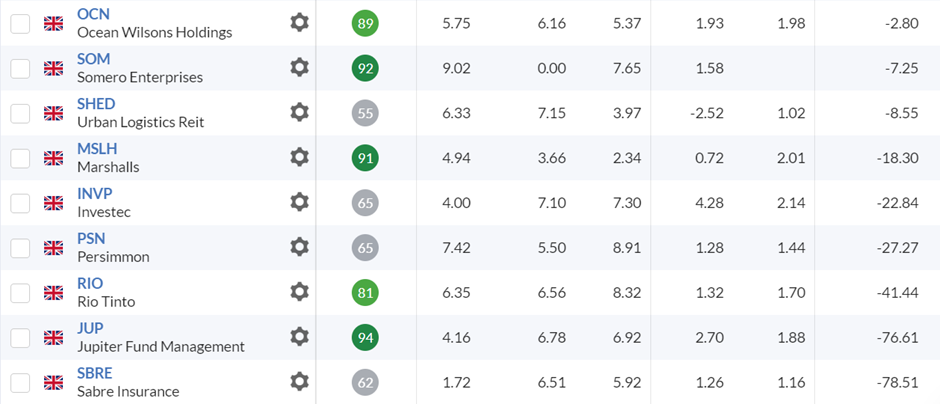
So overall, dividends have not made up for the poor capital return.
Although I haven’t done detailed calculations of volatility or Sharpe ratios, looking at the graph, I see little evidence that the income portfolio is less volatile than the general market and, therefore, should be favoured for this reason.
The Safer Income Portfolio
I knew the high-yield portfolio was risky when I wrote this article series. So, in a third article, I suggested that income investors would be better off sacrificing some initial yield for a safer income portfolio. Here is the performance of this portfolio over the last year:
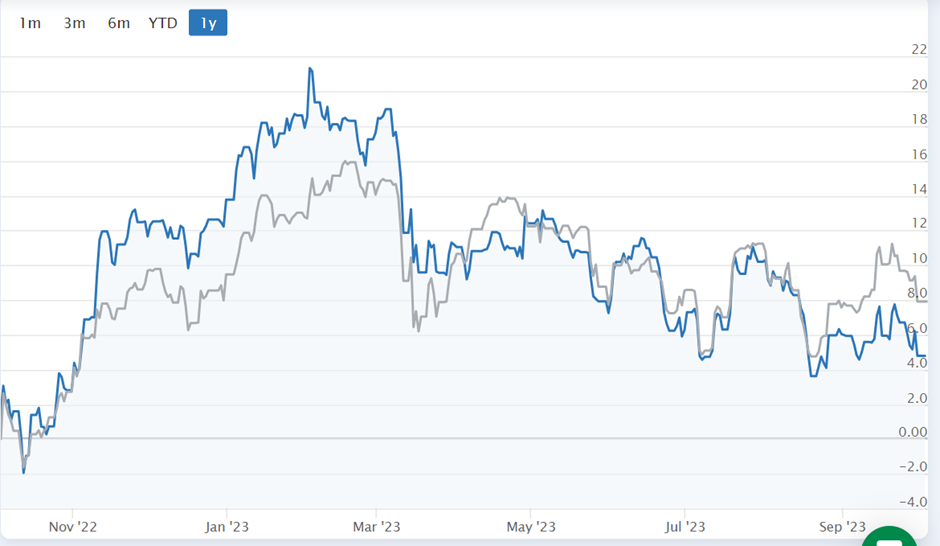
Again, this portfolio got off to a good start before tracking the market and finally underperforming over the last month. However, the difference here is smaller, with this portfolio generating around a 5% capital return versus the 8% of the FTSE All Share.
However, this portfolio also contained the same four dividend cutters, and these risky shares appeared amongst the biggest losers:
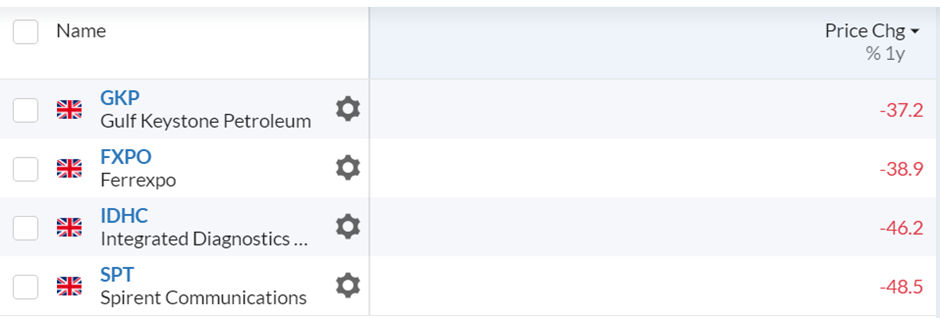
The most significant loss came from Spirent Communications (LON:SPT) , which has suffered from several profit warnings during the year, including one today. The figure above doesn’t even include today's fall. Spirent doesn’t appear to have cut its dividend, but it started as a share that was quite highly rated. It shows the risk of investing in highly-rated shares when things go wrong.
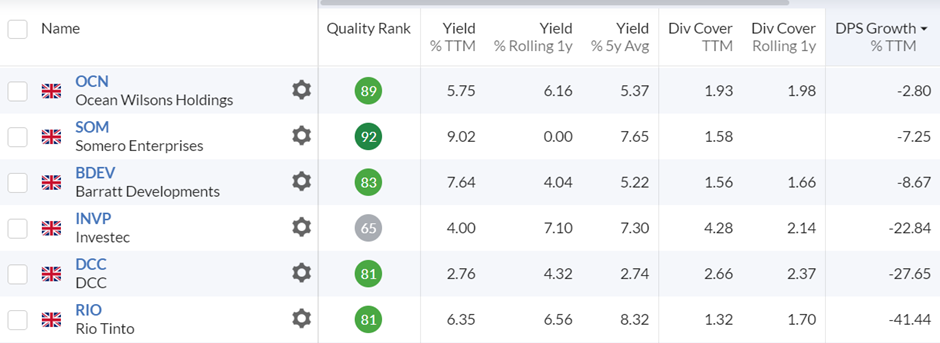
This portfolio also contained a few shares that reduced their dividend payout:
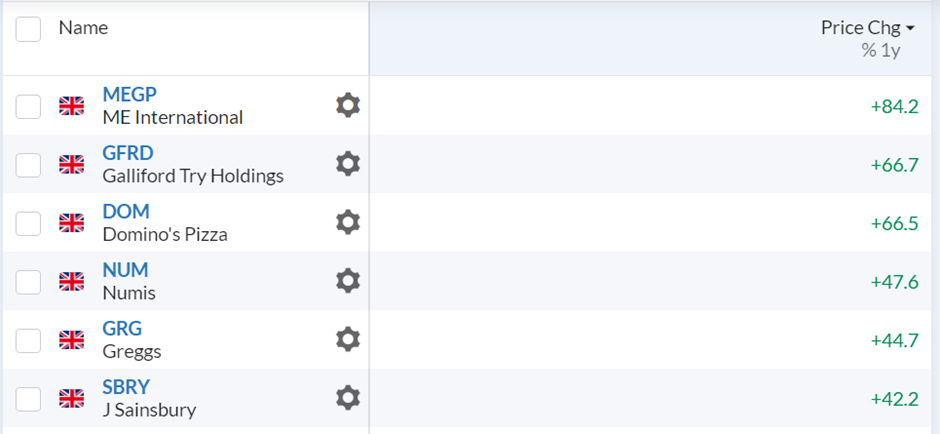
However, this portfolio contained more strong performers on price:
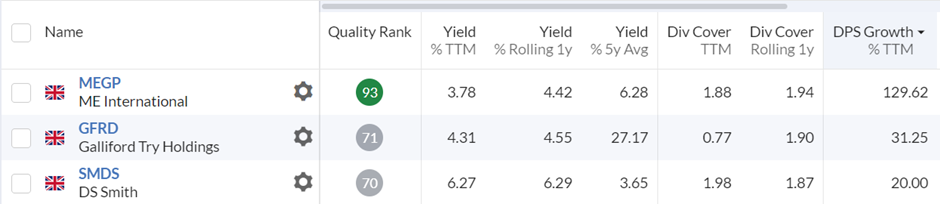
Interestingly, the two top performers in terms of price were also the best in terms of dividend growth:
In addition to greater industry diversification, my other attempt to add safety to the portfolio was to prefer stocks with active share buybacks. The theory was that a company was unlikely to buy back shares one day and cut their dividends the next. Here are the buyback stocks from the portfolio (excluding Civitas, which was taken over):
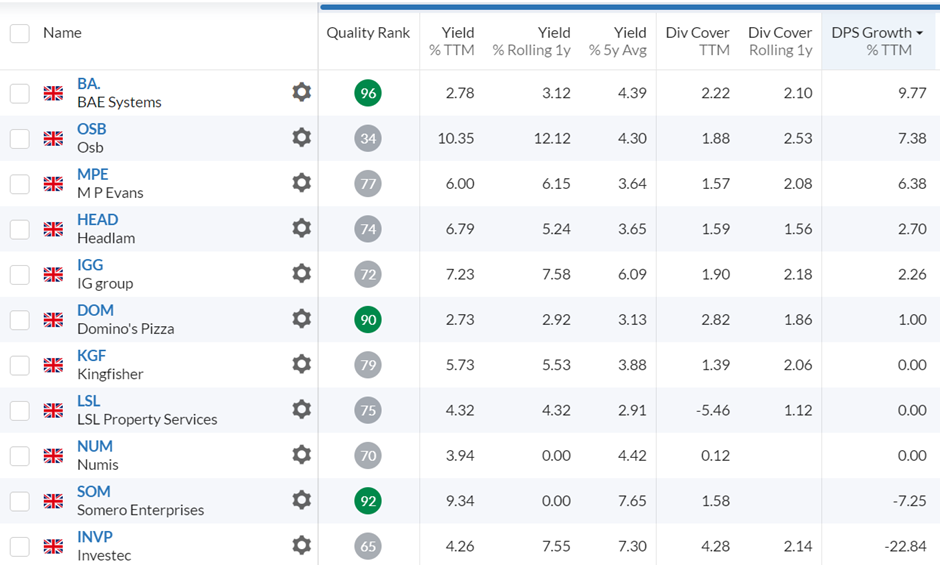
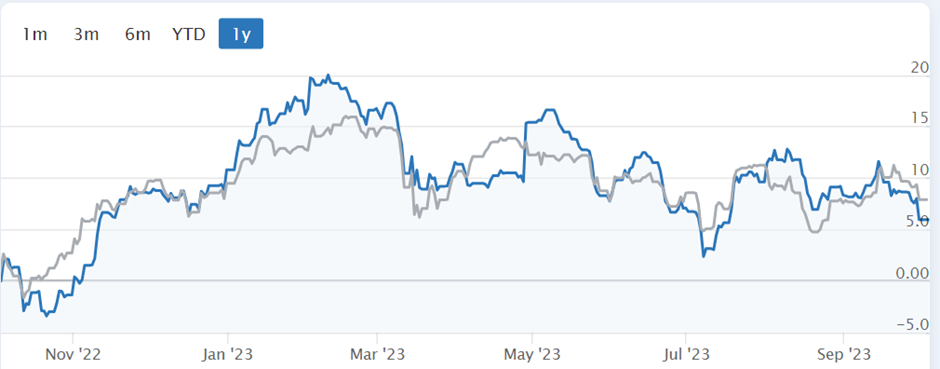
This seems to have largely succeeded, with only Investec (LON:INVP) significantly reducing their dividends. So, this may have added an element of stability for investors reliant on the income. However, it doesn’t seem to have made a difference to the yield; with some lower yielders in there, the average TTM yield of these stocks is 5.8%. In terms of capital gains, the buyback stocks have only performed in line with the rest of the portfolio, and hence underperformed the FTSE All Share:
Mea Culpa
So, what have I learned from this exercise?
The first thing is that the riskiest holdings have done the real damage. These stocks clearly had significant political risks when the portfolio was formed. I currently hold Gulf Keystone Petroleum (LON:GKP) and a small amount of Ferrexpo (LON:FXPO) because I believe the market has overreacted to the events here. However, this won’t be any consolation for an income investor who bought much higher and has seen their dividend income cancelled. This is made worse by Gulf Keystone Petroleum (LON:GKP) being an oil producer. More diversified oil producers, such as BP (LON:BP.), have done okay in contrast. It can be tempting to “juice” the income portfolio with high-yielding but risky or under-diversified stocks. With the benefit of hindsight, I would have picked much more stable businesses from these industry sectors.
Secondly, there has been a significant dispersion between the returns of individual stocks in the portfolios, both in terms of dividend growth and capital gains. I don’t think the winners or losers were predictable using simple screening metrics. (Although hindsight bias sometimes makes us think they were.) A 40-stock portfolio sounds well diversified. However, the inclusion, or not, of a few big winners made a big difference to the outcome. So, I think the income investor has a choice. They need to be more diversified than this if their main criteria for selecting stocks is purely dividend yield. Or they need to do a more detailed analysis of the prospects of individual stocks if they want to remain concentrated. There are pros and cons to both approaches. Owning a greater number of stocks may increase costs and the overhead of maintaining a portfolio but may still prove a more straightforward option than doing a more detailed stock analysis on many possible investment candidates.
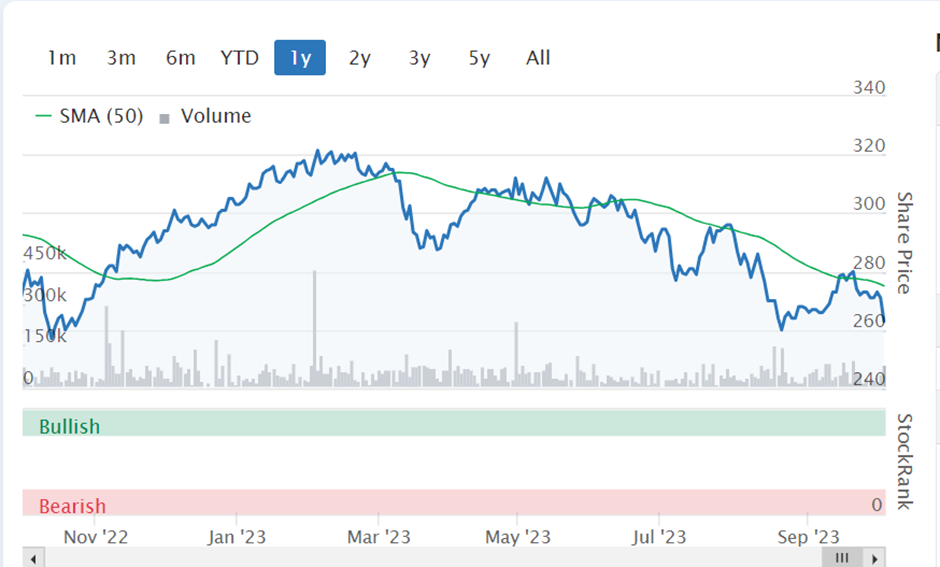
Finally, with the above tweaks in mind, these results shouldn’t put investors off building their own income portfolio. Even though the performance of these portfolios isn’t amazing, the safer income portfolio may have still outperformed the professionals. For example, here is Schroder Income Growth Fund (LON:SCF) over the last year:
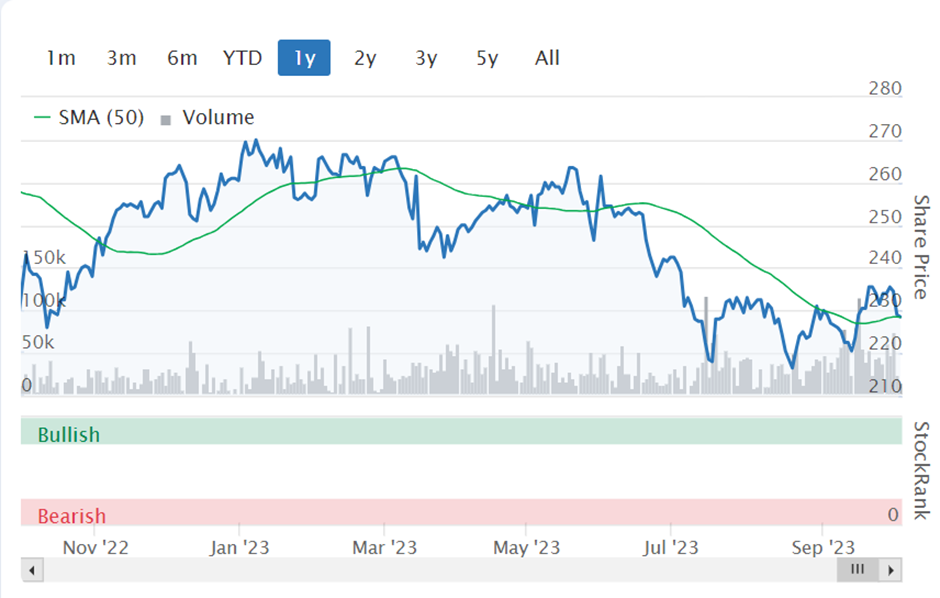
And this is Shires Income (LON:SHRS) :
[Disclosure: Mark owns shares in Gulf Keystone Petroleum (LON:GKP) Ferrexpo (LON:FXPO) Somero Enterprises (LON:SOM) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

10 comments
Great article Mark thank you. I've been interested in this strategy ever since you published last year. I'd been building an income portfolio for some time and after your article I've been using the screen and methodology to choose additional stocks. A lot of income portfolio articles mention changes in capital value and I suppose if you had no capital you couldn't generate an income, but the way I look at it, is that one could have purchased an annuity, and the capital value would gone to zero anyway. So for me, the interesting metric is how the income compared with other income strategies. I agree with Monty Carlo that Stockopedia is not ideal in this regard. I'd love to be able to generate stats on both accumulation and income units.
Hi 1MCF,
That is an interesting way of looking at it. However, I think capital value still matters. It is a bit like the investor who says, "my yield on my purchase price is 30%". It may give a warm feeling, but the market doesn't care about the purchase price, and neither should investors, IMO. If the current yield is, say, 2%, then an investor could sell their shares and invest in a 6% yielder and have three times the income. So capital value is important since this is the money that is invested to generate the income. Ideally, the income investor wants the capital value to grow at least with inflation while they reap a growing dividend income. However, I agree that Stockopedia isn't currently ideal for tracking income portfolio performance and, hence, making these sorts of switching ideas.
Mark
I'm afraid it is futile to even attempt to measure the performance of an income portfolio within Stockopedia.
Even over shorter time periods Stockopedia can be quite misleading for some stocks because it omits special dividends and the charts are not total return. Over longer periods the compounding of dividends is ignored. There is no total return FT Allshare index in Stockopedia - just the price performance.
Any higher-yielding portfolio will always look like a laggard on a Stockopedia chart over any longer time horizon.
A portfolio yielding 7% will double in value over a decade (1.07^10 = 1.97), just from dividend compounding. If we say the FT Allshare yields 3.5% then over a decade it would return 41% from dividend compounding. That's a difference of over 50% you will never see represented in a Stocko chart.
Good article.
I sadly hold Gulf Keystone Petroleum (LON:GKP) Ferrexpo (LON:FXPO) and even more sadly Evraz (LON:EVR) . All previously top StockRankers.
Evraz (LON:EVR) frustrates me as it is an International Business and the "Russian Oligarchs", particularly Abramovich are no more supportive of Putin's war than anyone else with some morality. Abram holds an Israeli passport and applied for a British Passport. Our Government turned him down. Our Government took my shares off me effectively: Nice: Hit British shareholders and US / Czech workers, not The Kremlin.
Ferrexpo (LON:FXPO) is a play on Ukraine winning the war. Hopefully they will, but this has gone on for too long whilst we've pussy footed about delaying giving them common sense tools like naval support, air superiority and HIMARS / Long Range missiles. They've done better than we expected. There are some Ukraine legal and corruption issues in the background. When this war ends.
Gulf Keystone Petroleum (LON:GKP) . There is some excitement as to whether the Turkey Kurdistan pipeline reopens. There is also some rumors about when this happens, whether GKP is a takeover target. If the pipeline reopens, the business looks good.
I am generally the worst investor trader ever and have massively increased my GKP holding on the rumour / play of the pipe knob being turned.
I might mention International Personal Finance (LON:IPF) . This is my best investment ever currently +110% over 5 years and yielding me something in excess of 15% on my holding. This was turbulent and soul destroying for the first 3 years.
I bailed out of IG group (LON:IGG) at 700p. If it ever gets cheap, I'll take a close look. Its a shame the Management wanted to destroy shareholder capital.
Good luck. I am not enjoying investing right now. Hope you are doing better than I.
Hi Mark
Thank you for doing the follow up article on your work from last year, it is always good to look back and think about what went well (try to do more of that) and what could have been a bit better (try to do less of that).
Yes this year has been tough, both on growth and income focused portfolios alike, as I run various family members investments for them.
The I have two main variations within the income fund (mum's ISA = her pension):
Firstly I have two manual "sell" signals, one is stopping the dividend, for example Gemfields (LON:GEM) the other is a 20% fall in capital value from purchase, for example IG group (LON:IGG). These companies go back on the watch list, so typically the sell's will bounce (FOMO) but it is more about trying to incorporate avoiding "Stage 4" stocks or do not fight the market if the price is drifting downwards relentlessly.
Secondly, is again a manual sell this is loosely on P/E, dividend % and total gain (number of years income), typically all three align, for example I sold Warehouse Reit (LON:WHR) which had risen from £1.10 to £1.50, the PE felt too high (everyone getting too excited on Amazon driven warehouse demand), the % dividend had fallen below my target (on price not purchase) and this was 4 years income booked. This is also partly about booking capital gain so not watching things go up and up, and then down, down and down, so this off sets some of the sells under the first section it is also about enabling lump sum withdrawals for my mum, gifts to the grandkids or a fabulous holiday.
I wonder if you take your basics of a diversified income fund, but then apply some form of sell rules, e.g. you are buying for income so a cut or stopped dividend = sell, would that improve the overall return, as well as the yield?
Thank you
Tommy
Hi Tommy,
What you have is effectively a stop loss. This can be a great strategy, although it doesn't always work for value portfolios, mainly due to the mismatch in mindset - if something cheap drops 20% is it not cheaper and a bigger buy not a sell? My aim here was to set up a Value portfolio that also paid a decent income. But if it works for you, that is great - it is far more important to find a strategy that works with your unique mindset.
In terms of selling when a dividend is cut, I also have mixed feelings. The problem is that the market has often anticipated the cut, so the price is weak beforehand and then gets hit hard when they cut, as everyone else who was buying the stock for income bails. This can include some income funds. My experience tells me that the actual cut often marks the low point for the share price and not the point to bail. It may be better to wait and sell later. I even think a strategy of buying stocks that cut their dividends may generate alpha! However, I haven't done an exhaustive analysis. Ed did a lot of research on how to react to profit warnings: https://www.stockopedia.com/bo... Something similar for dividend cuts may make an interesting research topic for the future.
I agree with selling when value is outed, particularly if momentum is fading too.
Mark
Hi Mark thank you for your article i hold a number of stocks mentioned in my SIPP which is Dividend focussed, overall perservance has been my approach on basis they are good businesses albeit some are unloved by the market
I dont allways understand the ratings for example why is the rating for Jupiter Fund compared to say the Phoenix group are so different?
hi mark your wright i only invest for divis and hold 65 companies about equal weighting so like 3 you have mentioned dont hurt they either come back or you have to wipe your mouth. long live the divis when were all stuck in reverse gear
I am definitely with Modigliani and Miller over the long term. But in the short term, having companies that pay dividends that can be re-invested, or ones that buy back shares and do this internally, gives a lot of comfort in these incredibly difficult short-term markets.
Thanks for the article, Mark. I agree, re-investment of high divs eases the pain. I too have suffered some capital loss this year, but reinvesting £18,500 of recent ISA divs to increase holdings in GCP Infrastructure Investments (LON:GCP) and Gore Street Energy Storage Fund (LON:GSF) and thereby add £2,000 of annual income from heavily discounted ITs helps sleep patterns. And GCP Infrastructure Investments (LON:GCP) as a disappointed suitor to GCP Asset Backed Income Fund (LON:GABI) has been buying back shares as well.