Infomedia: time for the rubber to hit the road

This article was written by regular contributor Anton Crabbe. You can read his bio here
Infomedia (ASX:IFM) is a company I have admired for some time now as fundamentally, they are a fantastic company.
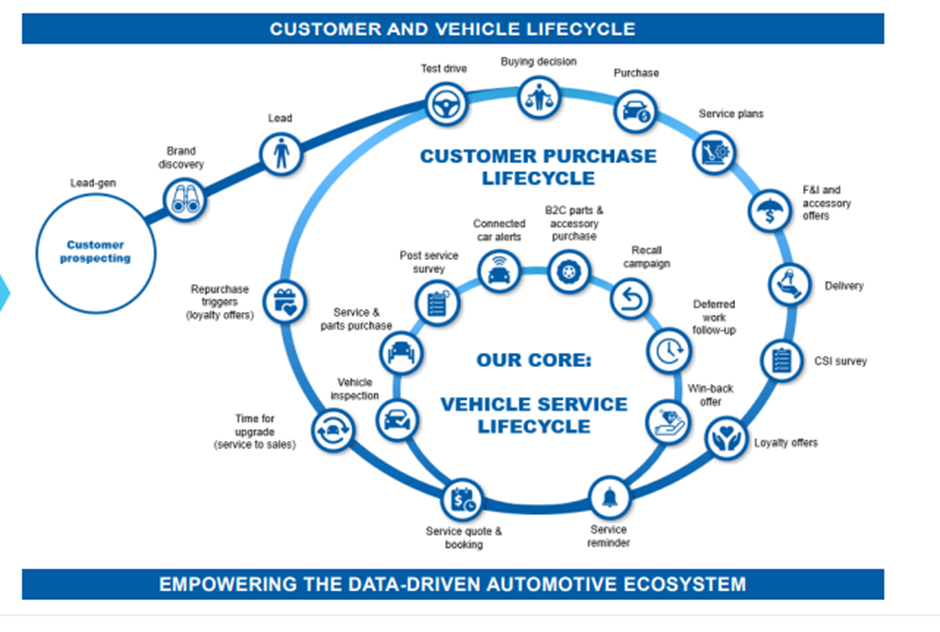
They are a global player in the automotive industry providing SaaS (Software as a service) and DaaS (Data as a service) products to car manufacturers, dealers, and OEM’s. Over the years their business has evolved from mainly a parts and inventory software provider to offering a full suite of SaaS and DaaS products that provide analytical, marketing, predictive servicing, parts inventory, and maintenance solutions. All this is aimed at capturing the global trend in connected cars and allowing car manufactures and dealers to own the lifecycle of a customer/car relationship by providing pre-emptive servicing, repair/maintenance and resale solutions and recommendations. A large part of the connected vehicle market is expected to come from the growth in EV sales, as the push to decarbonisation marches on.
https://www.infomedia.com.au/files/investors/230224-IFM-1HFY23-Investor-Presentation-Slides.pdf
To date this transition has not been a smooth ride for IFM. They raised capital back in 2020 to fund acquisitions and software development costs associated with the new strategic direction. There have been changes at board level, namely the appointment of a new CEO at the start of 2022, and there was a small thing called COVID which threw a spanner into the entire car supply chain.
As a result, sales flatlined and earnings and profits declined. But now they are starting to increase and pleasingly as a result of the new business strategy, the majority of IFM’s revenue is contracted annual recurring revenue (ARR). It’s looking like the worst is behind IFM and now they are focused on reducing costs, growing sales, market share and profits.
Stockrank/Quality Value:
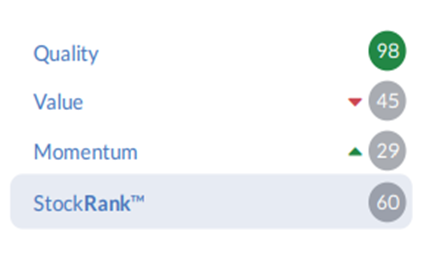
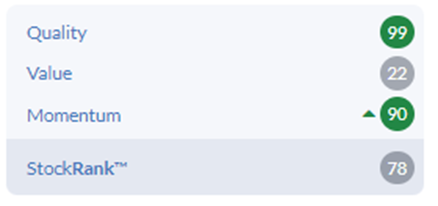
The numbers tell the story here, IFM is a quality company which is reflected in a quality score of 99 but this is no secret to the market or investors with a valuation score of 22 and momentum at 90. Momentum does seem to be on IFM’s side currently, which does help explain the 20 cents a share price increase since the start of 2023. If we go back to the start of February before the release of their half-yearly report on the 24th of February. IFM’s momentum score was 29 and their value score was 45, fare to say the market and investors liked the report.
Before report
After report
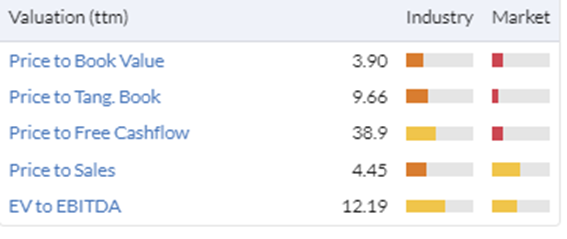
IFM have been recognised as a fundamentally strong company for some time now and trade on a high PE (currently 66). A quick look at their valuation multiples backs this up, as you are paying 4 times sales for a single share at $1.46. You have to pay to play here and is why for a company of such quality, their overall StockRank only 78.
Financial Health:
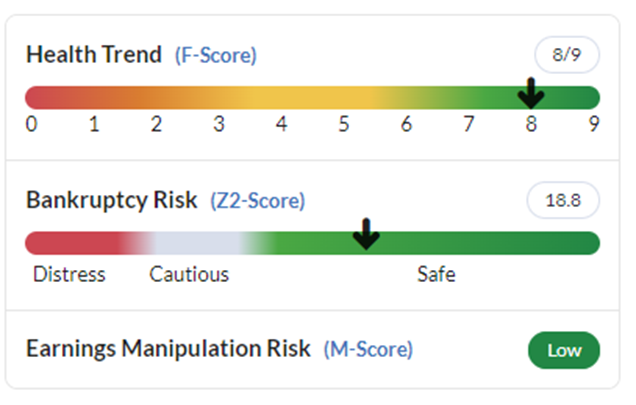
As is to be expected with a quality score of 99, IFM are in strong financial health with an F-score of 8 and a Z2-Score of 18.8. This is what happens when a company has no debt, positive cash flows, and produces profits.
They have also been prudent in issuing shares, as since 2013 they have only issued 73m new shares with the bulk of those coming in the 2020 capital raise.
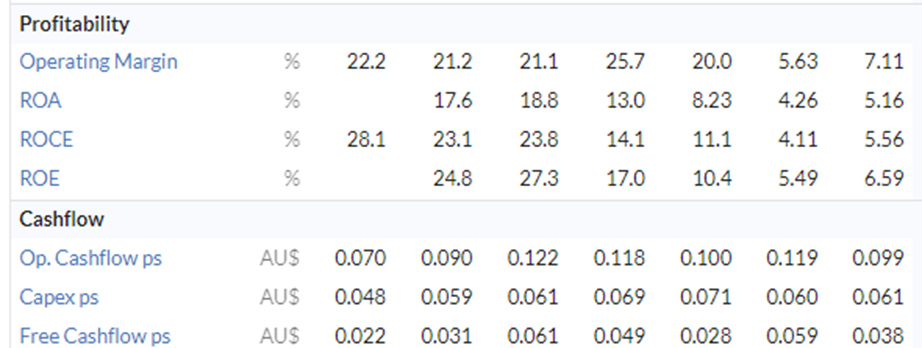
That said, despite the solid positioning, there is still room for improvement, as IFM’s operating margin, cash flow per share and profits all declined over the past three years as they have implemented their new strategic business direction and been impacted by COVID. This saw their share price fall from circa $2.00 back in 2019 to $1.46 at the time of writing.
IFM in their 2023 half year report noted they have started reducing IT infrastructure costs and reduced headcount as they enter the next phase of their strategic plan and ideally as revenue has started to increase again and is forecasted to keep increasing, earnings and profit margins should follow. For me, from here we want to see earnings and profit margins, ROE, ROA and ROCE return back to levels before the strategic plan was implemented and acquisitions made, as this will indicate the company is as profitable now as it was previously, and the new strategic direction is starting to create value for shareholders.
Liquidity Ownership:
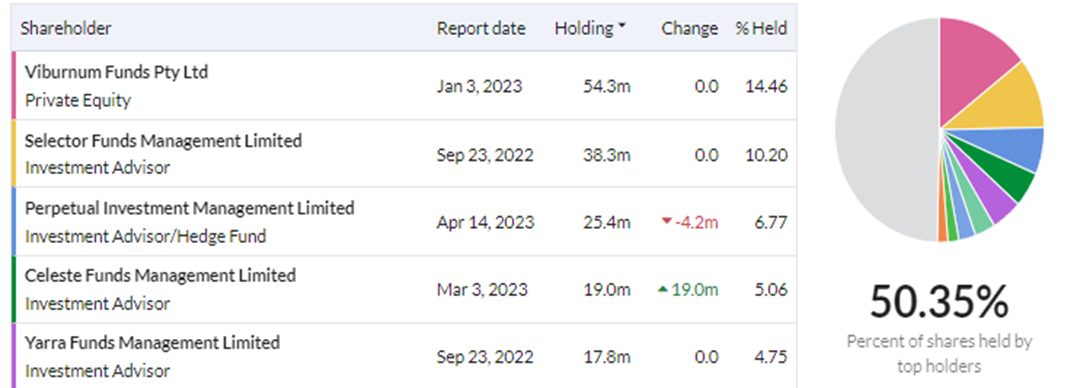
For a small retail investor there are plenty of shares to go round as of the 375m shares on issue 97.1% are classified as free float and can be traded. There largest shareholder is Viburnum Funds Pty Ltd with 14.4% and 50.3% is held by the top 9 shareholders.
Outlook:
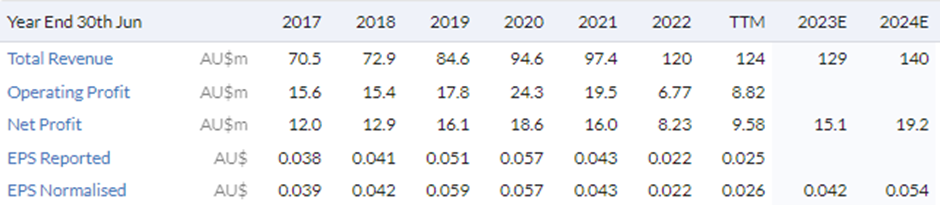
IFM reaffirmed forward sales guidance of $127m to $131m in their 2023 half year report and consensus estimates has net profit after tax increasing to $15.5m and $19.2m in FY23 and FY24 respectively. Also, encouragingly to see for shareholders, EPS and DPS are expected to return to previous levels too.
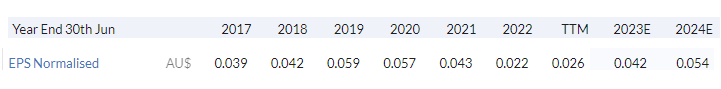
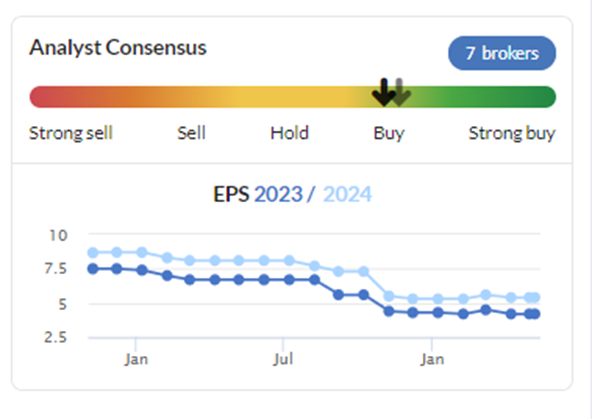
Investors will note that EPS estimates have fallen over the past 12 months. An acknowledgement that the company U-Turn is taking a little longer than initially anticipated.
Conclusion:
For me, it’s time for the rubber to hit the road for IFM. They have positioned themselves to capitalise on a global and industry wide tread and given the strong fundamentals of the company this should result in long-term value for shareholders. However, an investor should consider their risk appetite here, as IFM are priced to perfection given their stretched valuation multiples, with some of the future upside already baked into the share price, and any bumps in the road will hurt their share price. But if they keep meeting forward guidance and consensus targets the share price will look after itself and investors will be in for a good ride.
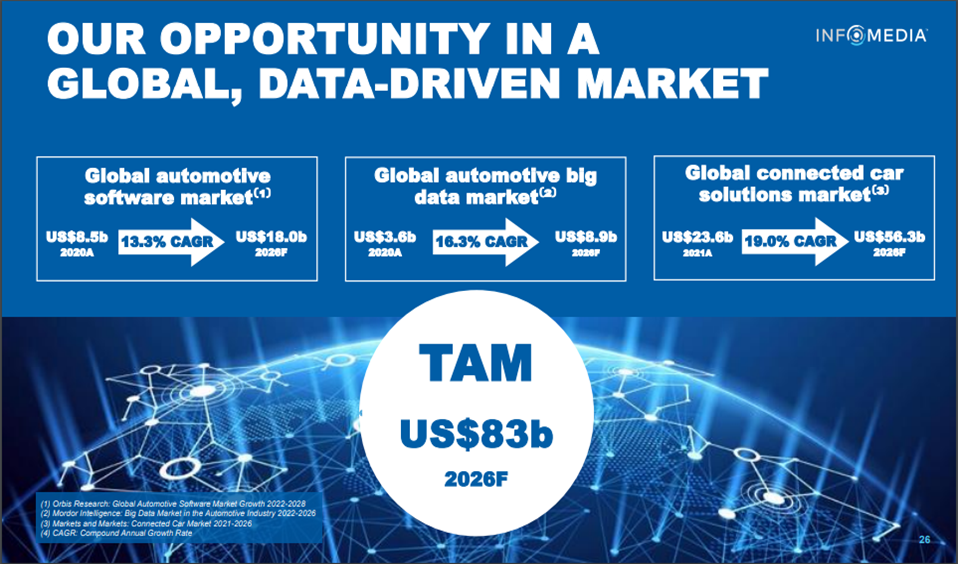
TAM = Total addressable market
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?