Is Morrison's recovery already in the share price?

Summary:
- Morrisons is a supermarket and along with the other major UK supermarkets, it’s had a tough few years competing against the German discounters Aldi and Lidl.
- Revenues, earnings and dividends fell, but are now starting to recover and grow.
- Morrisons’ dividend yield is low, suggesting high future dividend growth, but I think the market is probably overoptimistic.
10-Year growth rate: Below average
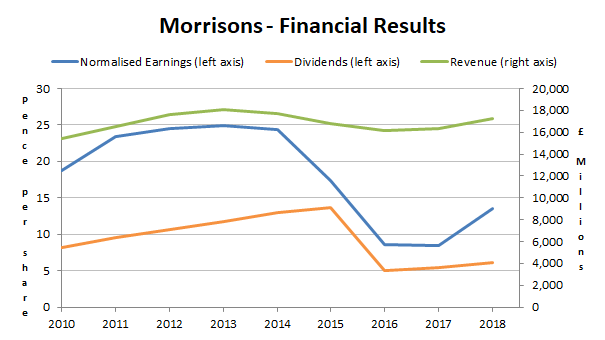
Morrisons is not a high growth company. Over the last decade its revenues, earnings and dividends have grown by an average of minus 7% per year, although that figure is slightly misleading.
It’s misleading because the period it covers happens to start at a high point for supermarkets and end at a low point.
If you look at periods longer than ten years then there is an underlying growth trend. It’s around a few percent per year and is likely driven by a combination of inflation and UK population growth.
Either way, Morrisons’ growth is below average, where the average growth rate of consistent dividend-payers is currently about 6% per year.
To be honest, this isn’t a massive surprise. Morrisons is a very mature business operating in an extremely competitive market. It’s also currently geographically constrained to the UK.
Going forwards, I would expect Morrisons’ growth to be no better than its long-term historic average of perhaps a few percent each year.
10-Year growth quality: Below average
Unsurprisingly, Morrisons’ below average growth rate leaves it with below average growth quality as well (where growth quality is basically a measure of growth consistency).
Over the last decade it has grown revenues, earnings and dividends approximately 67% of the time, while the average for consistent dividend-paying stocks is 73%.
This highlights the difficult time Morrisons has had as it struggles to cope with super-low prices from Aldi and Lidl.
This 67% growth quality score is also slightly misleading as Morrisons longer track-record is more consistent, as you might reasonably expect from a supermarket.
After all, it does operate in the defensive Food & Drug Retailers sector, so it should be relatively immune to the ups and downs of the economy.
And it is, but it isn’t immune to an attack from aggressive low-cost competitors whose business models perfectly fit the environment of post-crisis austerity Britain.
10-Year profitability: Below average
Here’s one of the key reasons why Aldi and Lidl were able to send shock waves through the supermarket sector in recent years:
None of the major UK supermarkets has any kind of enduring competitive advantage (possibly with the exception of Tesco, but even that is far from certain).
Yes, lots of people prefer one supermarket over another, but it’s usually a weak preference so location and price are still the dominant factors.
Since most towns have more than one supermarket these days, pretty much the only way to attract customers away from nearby rival supermarkets is with ever lower prices. But low prices mean low profitability, and that’s partly why profitability is a good indicator of competitive strength.
Companies with strong competitive advantages tend to be more profitable than average, while companies with little or no competitive advantages tend to be less profitable than average.
So how does Morrisons stack up in terms of its profitability?
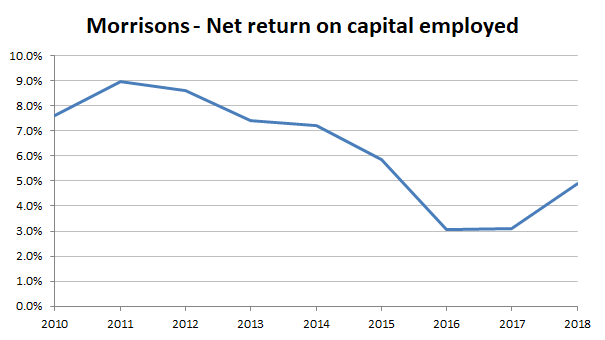
As you can see from the chart, I use return on capital employed (ROCE) as my measure of profitability; or ten-year average post-tax return on capital employed, to be precise.
The average profitability for consistent dividend-paying UK stocks is about 11%. In other words, an average dividend-paying company produces a return of about 11% per year from its fixed and working capital.
Unfortunately for Morrisons, it hasn’t reached that level of profitability even once in the last decade. Its profitability score is just 7.2%, which is very weak indeed.
This weak profitability suggests that Morrisons has little or no competitive advantage, which is not good news for shareholders.
A company without competitive advantages is likely to be buffeted by the winds of capitalistic creative destruction, and Morrisons wobbly track record is evidence of that.
Debt levels: High but acceptable
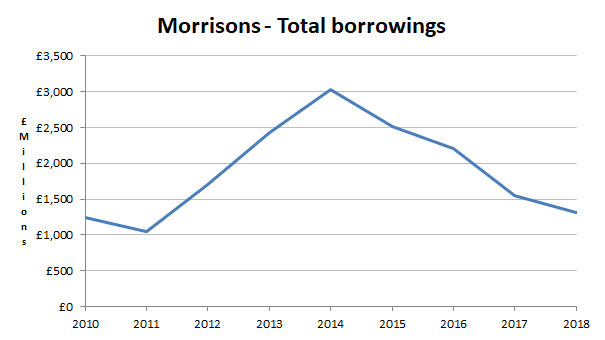
Just before Aldi and Lidl changed the UK supermarket landscape forever, Morrisons went on a debt-fuelled spending spree, opening new stores and building out its infrastructure like there was no tomorrow.
The end result was a collection of capital assets which are unlikely to ever produce a decent return on the original investment. On top of that, the company was saddled with debts of more than £3 billion, which I think is too much for a company earnings around £0.5 billion per year.
£3 billion was too high (in my opinion) because it took the company’s debt to profit ratio above five, and that’s my limit for defensive companies.
Eventually management agreed with me and in recent years Morrisons’ debt pile has decreased substantially. Today its debts are less than half their peak level, at £1.3 billion.
That gives Morrisons a debt to profit ratio of 3.9, which is still quite high but should be manageable for what is supposed to be a defensive business.
Pension liability: Very large, but in surplus
Pension liabilities are finally getting the respect they deserve from investors, largely due to high profile events such as the collapse of Carillion.
Personally I look at a company’s total pension liabilities, rather than just the deficit or surplus.
That’s because a 10% surplus today can easily become a 10% deficit five years down the line, and a 10% deficit on a big total pension liability is much more dangerous than a 10% deficit on a small total pension liability.
If the total pension liabilities are more than ten-times the company’s recent average profits, that’s usually a red flag for me. A 10% deficit in such a large pension scheme would be equal to an entire year’s profits, and that could be a serious drag on a company’s financial flexibility.
In Morrisons’ case, it has total pension liabilities of £4.3 billion, which gives it a pension to profit ratio of 12.6.
That’s above my 10x pension ratio limit, so in my opinion Morrisons’ defined benefit pension scheme is a potentially serious risk to the company’s health.
Having said that, the fund currently has quite a large surplus of assets over liabilities, to the tune of £600 million. That’s a 13% surplus, so it would take some very bad investment decisions for the scheme to turn from such a big surplus to a dangerous deficit.
But stranger things have happened.
Capital intensity and expansion: High, but coming down
Supermarkets are a relatively capital intensive business. You have to:
- build a store that has several hundred parking spaces,
- equip the store with expensive items like ovens, freezers and tills, and then
- invest in logistical infrastructure like trucks, warehouses and distribution hubs in order to supply your store with goods
And you have to pay for all that before you can start generating a penny of revenue or profit.
Capital intensity is a double edged sword though: It makes growth expensive because you have to build more stores and warehouses before you can grow, but it reduces the number of start-up competitors because they have a hard time raising enough capital.
Personally I don’t mind capital intensive companies as long as they’re not aggressively expanding their capital base. When capital intensive companies increase their capital assets rapidly, they’re often sowing the seeds of oversupply in the near future.
This happened to Morrisons and the other major supermarkets a few years ago when they were all building new stores as quickly as they could raise the necessary debt.
The result was a country oversupplied with out-of-town mega-stores, just when people were beginning to switch to small, more frequent shopping trips in order to more tightly control their budgets.
You can see this in the chart below, which shows Morrisons’ capex over the last decade or so:
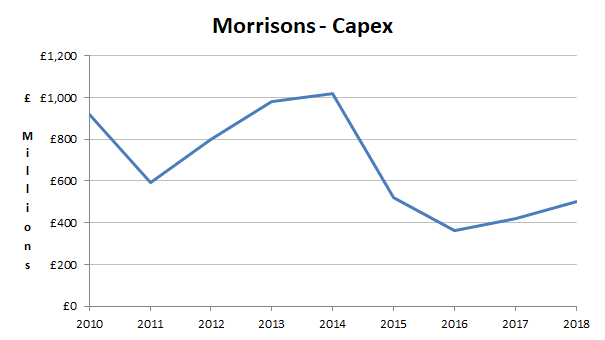
Peak capex occurred in 2014, the same year as company’s peak borrowings of £3 billion, and that is no mere coincidence. The dividend was cut shortly after and, quite sensibly, capex was cut aggressively at the same time.
The next chart shows Morrisons’ high capex to profit ratio (a measure of capital intensity) and capex to depreciation ratio (a measure of capital expansion):
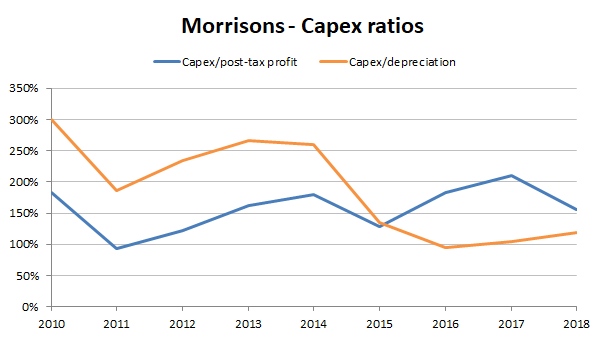
I consider a capex to profit ratio (i.e. capital intensity) of more than 100% as high, and Morrisons has averaged 150% over the last decade. As I said before, this isn’t usually a problem as long as the company isn’t expanding too quickly and possibly building up too much supply capacity (which is then difficult to remove as you can’t exactly make a supermarket disappear).
As for the capex to depreciation ratio (i.e. capital expansion), anything over 200% is too high for me if the company also has high capital intensity.
In Morrisons’ case its capex to deprecation ratio is currently 184%, so it’s very close to my upper limit, and that includes the period of relatively lower capex in the last four years. In 2015 this ratio was about 250%, so these two ratios were clearly suggesting that Morrisons was at risk from over-expansion, and that eventually turned out to be true.
Today I would say Morrisons’ capital intensity and capital expansion rates are high but acceptable, although they’re still a potential risk.
One final point on capital intensity:
The company is currently pursuing a capital light growth model, which I think is probably a good idea. What this means is that it is moving into wholesale, supplying other customer-facing outlets with baked beans, bread and so on.
For example, Morrisons now sells goods through Amazonso Amazon effectively acts as the store, saving Morrisons from that particular piece of capital expense.
Another example is Morrisons’ agreement to supply McColls, which is a chain of more than 1,300 convenience stores. Again, someone else runs the stores, saving Morrisons from making that capital investment.
In some ways this is a bit like a franchise business such as Domino’s Pizza (disclosure: I own a slice of Domino’s Pizza). Domino’s franchisees pay up the £100,000 or so of capital required to fit out the restaurant and then Domino’s simply supplies them with ingredients (and other things as well, such as national advertising).
It’s a very capital light way to grow as somebody else is paying for the capital assets. Hopefully it will work out well for Morrisons, but I’m not holding my breath.
Acquisition rate: Virtually zero
Something else I don’t like is highly acquisitive companies. It’s usually a case of a little bit is good, but a lot is not.
In this case there isn’t a problem as Morrisons has made almost no acquisitions of any meaningful size over the last decade.
Fair value price: 150p
As things stand today, I wouldn’t invest in Morrisons. That’s because its:
- Growth rate is too low
- Profitability is too low
- Pension liabilities are too large
And to a lesser extent, it’s still a very capital intensive company and its debts are towards the upper end of my preferred range.
However, perhaps you’re made of sterner stuff, or you have some special insight which makes you think Morrisons could be a good investment, at the right price. If that’s the case, here are my thoughts on Morrisons’ fair value:
At today’s share price of 250p, Morrisons has a below average combination of growth, profitability and value*.
* I measure value using the price to ten-year average earnings and dividend ratios, i.e. the PE10 and PD10 ratios.
On that basis, Morrisons is currently trading above fair value.
To reach fair value, i.e. to have an average combination of growth, profitability and value, Morrisons’ share price would have to fall to about 150p.
That’s a decline of more than 35% from today’s share price, which would be a large but not exceptional decline.
At 150p Morrisons would have a dividend yield of 4.1%, which is much more attractive than its current relatively slim 2.6% yield.
Potential purchase price: 100p
Because Morrisons’ ten-year growth rate is so low (minus 7% per year) it’s impossible to come up with a sensible potential purchase price using my normal method of combining growth, profitability and valuation.
So in this instance I’ll go by feel.
If I was looking to invest in Morrisons (which I’m not) it would have to be at a price comfortably below that fair value price of 150p. “Comfortably below” probably means a margin of safety of 30% or more, which gives me a ballpark potential purchase price of 100p.
If Morrisons fell to 100p it would give the stock a dividend yield of 6.1%, which sounds about right for such a weakly profitable, low growth company.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
1 comment
make of this what you will but there seems to be problems with a shortage of stock on the shelves at two stores fifty miles apart that my family and friends have commented on unprompted by me .