Keller Group - An Undervalued Play on US Infrastructure Spending?
Welcome back to our Stock Pitch Series. Today, I’m going to focus on a FTSE 250 industrial stock with a StockRank of 98 and a ‘Super Stock’ rating. The company is Keller Group (LON:KLR). Here’s why it has caught my eye.
- At the time of publication, Ed Sheldon had no position in KLR.
- Share price at the time of publication: 2,256p
- Market cap: £1.6bn
The Pitch
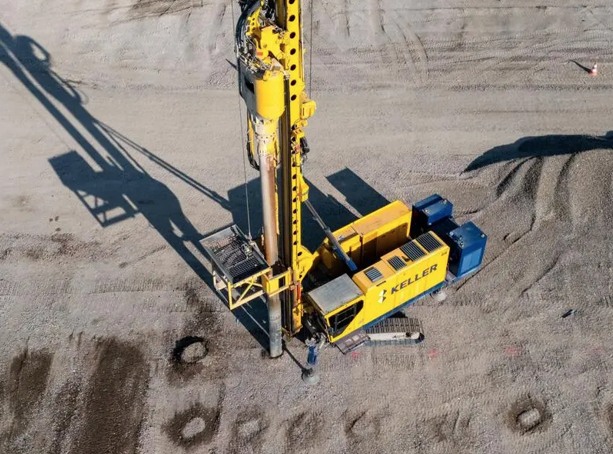
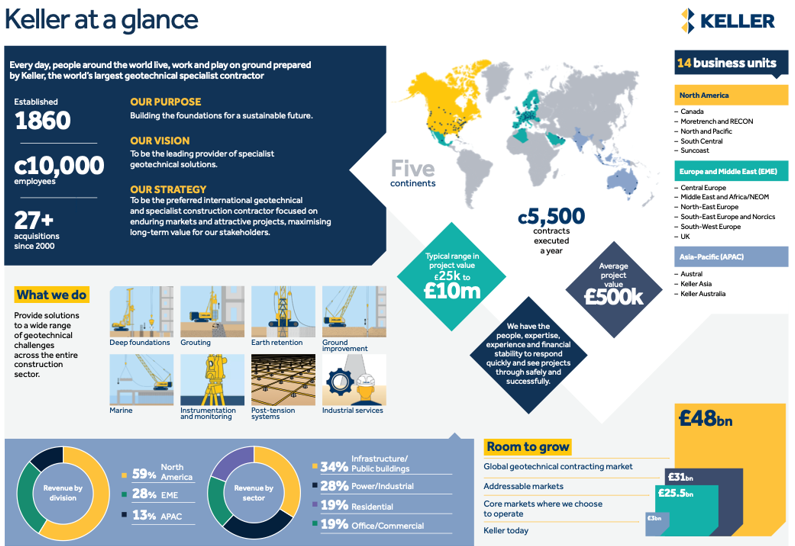
Keller Group is the world's largest geotechnical specialist contractor. Providing a wide range of advanced foundation and ground improvement solutions, it operates across five continents, taking on more than 5,000 projects every year.
Areas of construction in which the company operates include commercial (e.g. data centres, distribution centres, hotels), residential, infrastructure, power, industrial, and institutional. Last year, around 59% of revenue came from North America while EME and Asia generated 28% and 13% of revenue respectively.
The Big Picture
Keller looks set to enjoy some powerful tailwinds in the years ahead. Right now, the US is in the midst of a ‘mega project’ construction boom, fuelled by the digital revolution, the energy transition, reshoring of critical industries, and federal legislation such as Donald Trump’s ‘One Big Beautiful Bill’ Act. Across the country, companies are building data centres, semiconductor manufacturing plants, energy infrastructure, and much more. Given that Keller effectively specialises in getting ground ready to build on – and generates a large proportion of its revenues in the US – it could be a major beneficiary of this construction boom.
The current US administration is prioritising ‘sovereign’ infrastructure: There is a focus on projects that ensure US dominance in technology (AI) and defence such as data centres, chip plants, and nuclear energy facilities.
The One Big Beautiful Bill Act (OBBBA) is supportive: The OBBBA provides broad financial incentives for US construction and clears the regulatory path for massive industrial builds.
Going Deeper
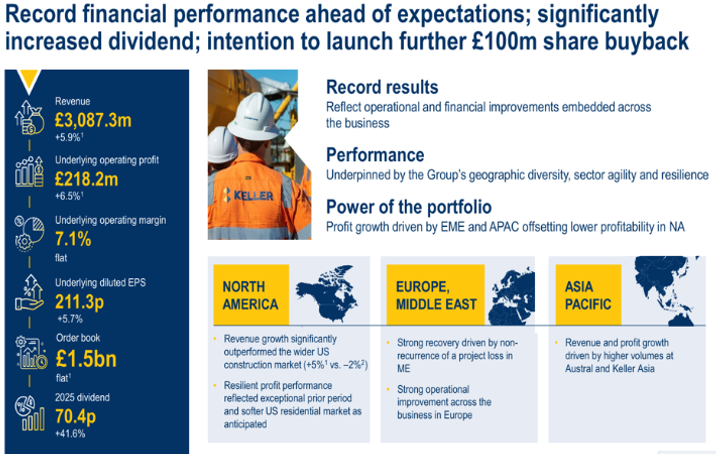
Looking at Keller’s 2025 results, the company is already benefitting from the supportive backdrop in the US. In North America, revenue growth outperformed the wider US construction market last year, driven by infrastructure spend.
Overall, group revenue for the year was £3.1 billion, up 5.9% at constant currency, while underlying diluted earnings per share (EPS) came in at 211.3p, up 5.7%. On the back of this performance, the company hiked its dividend significantly and also announced a share buyback.
It’s worth pointing out that management commentary in the 2025 results was very encouraging. Here are some notable quotes from CEO James Wroath:
“With the demand for our services supported by favourable long-term structural growth drivers including infrastructure investment, population growth, energy transition, climate resilience and technology adoption, we remain confident that the group is well placed to build on its momentum and deliver further progress in 2026 and in the years ahead."
“The group enters the new financial year with a high-quality order book, healthy tendering activity, strong balance sheet and a clear strategic direction.”
“The group has a compelling proposition for all our stakeholders and I am optimistic about the scale of opportunity ahead on which Keller is uniquely positioned to capitalise.”
Now, Keller is a cyclical company, so you wouldn’t really call it a ‘quality’ stock. However, looking at the company’s financials, it does have a lot of quality. Attractions include:
A high return on capital employed (ROCE): In 2025 underlying ROCE was 30.7% (2024: 28.2%), the highest level for 17 years.
A strong balance sheet: At the end of 2025, the company had a net cash position of £59.7m (the first time in more than 25 years it had a net cash position).
Dividend growth: Keller increased its 2025 dividend by 42% to 70.4p per share (a yield of approximately 3.1% today).
Reliable dividends: Keller has maintained an unbroken record of increasing or maintaining its annual dividend for 31 consecutive years, ever since its flotation in 1994.
High dividend coverage: Last year, dividend coverage was about 3x (its target cover range is 2.5x - 3.5x).
Buybacks – In its 2025 results, Keller announced a £100 million buyback as part of its multi-year share buyback programme.
One other thing worth mentioning here is that it’s an AI-proof ‘HALO’ stock (heavy assets, low chance of obsolescence). You can’t ask Anthropic to prepare ground for the construction of a data centre!
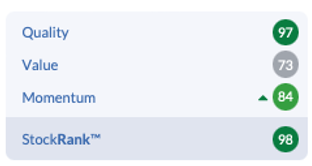
Overall, I see the quality factor as high. And Stockopedia does too, giving the stock a Quality rating of 97.
Turning to the valuation, it remains undemanding:
Low P/E ratio: With analysts expecting EPS to rise 7% to 226p in 2026, we have a forward-looking price-to-earnings (P/E) ratio of 10.
Low PEG ratio: Taking the 7% earnings growth forecast and comparing it to the P/E ratio, we get a PEG ratio of 1.4.
High free-cash-flow yield: A trailing free cash flow yield of around 11% also suggests that there is some value on offer.
Technically, the set-up looks favourable:
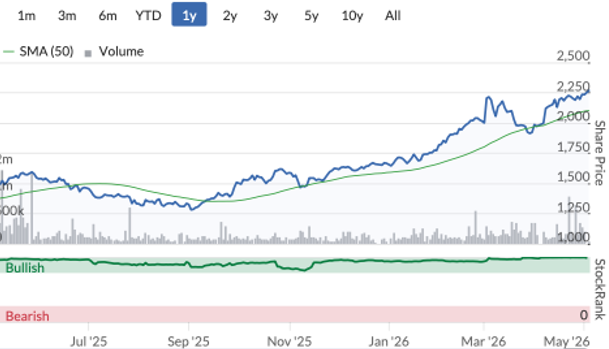
Upward trend: The share price is currently in a strong upward trend.
Breaking out: The stock recently hit new all-time highs (meaning that there will be no disgruntled long-term holders sitting on losses and looking to sell when they breakeven).
Not overbought: The RSI is below 70.
Healthy quant rating: The Stockopedia Momentum rating is 84.
What the Brokers Say
As for broker sentiment, it’s bullish at present:
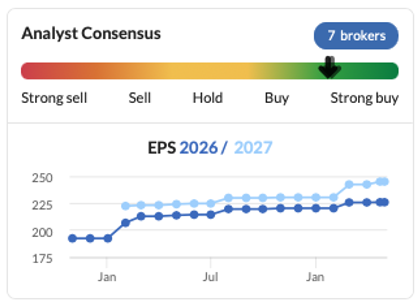
Multiple Buy ratings: Of the seven brokers covering Keller, four rate it as a Strong Buy, one rates it as a Buy, and two see it as a hold (given these Holds, there is scope for more Buy ratings).
Earnings estimates are rising: In recent months, analysts have increased their earnings forecasts for this year and next.
The average price target is 2,460p: That is only around 8.5% above the current share price but dividends are likely to boost returns.
The Bear Case
Risks to consider include:
Cyclicality: This is the main risk to be aware of. If we saw a major global economic contraction, Keller shares could underperform badly. Note that in the Global Financial Crisis, the stock fell from over 1,100p in 2007 to below 300p in 2011.
Industry weakness: While mega project spending is likely to be a tailwind in the years ahead, a weak residential construction market could hamper growth, especially if interest rates remain high.
A new CEO: The company has a relatively new CEO, which adds some uncertainty (sadly, former CEO Michael Speakman passed away in April).
Profit taking: The stock has experienced a material move higher over the last two years, more than doubling in price. After that kind of move, there is always the chance of a pullback.
The Bottom Line
Overall, I see the set-up here as attractive. In Keller, we have a company with growth potential, a low valuation, a rising dividend, share buybacks, bullish analyst sentiment, a strong upward share price trend, and a high StockRank.
Cyclicality is a risk – I would not want to be in this stock during a major global economic meltdown. Right now though, the backdrop looks supportive.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Thanks for the detailed analysis :-)
Keller (LON:KLR) has been popping up on my screen for a few weeks now as a good long term buy ;-)
Excellent detailed convincing pitch, great stuff Ed, thank you.
"At the end of 2025, the company had a net cash position of £59.7m (the first time in more than 25 years it had a net cash position)." -- under-appreciated balance sheet too
Really great read, Ed. A favourite stock of mine too -- although for some reason I don't hold it. Definitely room for a re-rating too.
Thanks for the deep dive and the effort you have put into it.
The most undervalued stock listed in the UK, in relation to AI, is Gooch & Housego (LON:GHH).
About 1.5x 2028 sales!
I don’t even understand why they are still listed here and not over the pond?
All the best
It's a terrific company on many counts. Growth, income and probably still represents a contrarian nature based on enterprise value to sales. Reminds me a lot of hill and smith a decade ago.
Hugely attractive from a dividend perspective as well
A good commentary on an excellent company that I identified through this site nearly a year ago when it had just moved through its 200 day SMA. Since then it's delivered a 56pc return and looks well set to go on delivering,,, wish I'd bought more!
Tell us about your other finds m2m, sounds like you know your stuff!
Truly excellent in terms of content , presentation and format from a deep dive in good hands Thank you
Thanks, Ed. This is a useful write-up, and the stock's been strong since last autumn, mostly staying above it's 50-day moving average, despite everything that's been going on in the world.