Keystone Law: A Tech Platform Dressed as a Law Firm?
In this week’s Stock Pitch, I’m going to put the spotlight on a small-cap stock with a ‘High Flyer’ rating and a StockRank of 88. The stock is Keystone Law (LON:KEYS). With the company recently telling investors that profits for FY2027 would be materially above expectations, and its share price rising, could it be worth a closer look?
[Disclosure: At the time of publication, Ed Sheldon had no position in KEYS.]
- Share price at the time of publication: 787p
- Market cap: £243m
The Pitch
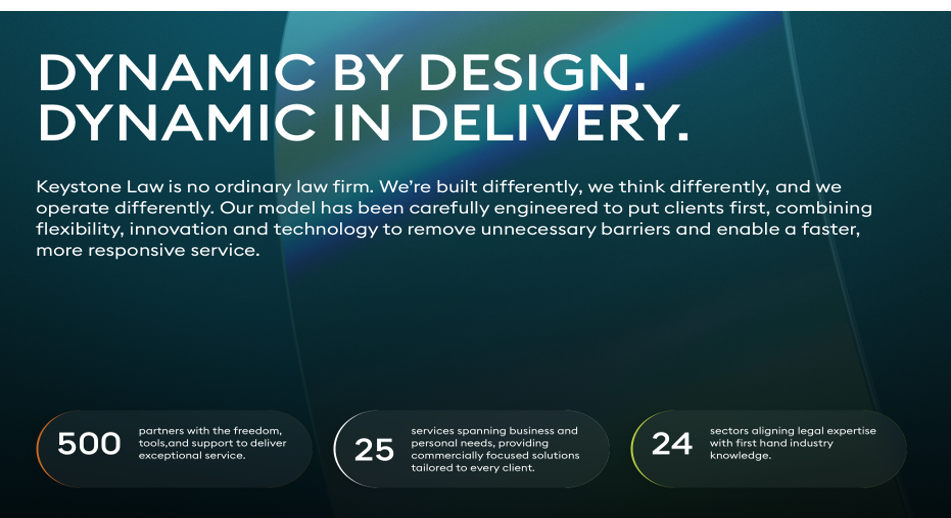
Keystone Law is a UK law firm that operates a unique ‘platform’ model. Its lawyers determine how, when, and where they work – pocketing up to 75% of what they bill – while the company provides them with full infrastructure and support via its central office and IT platform.
Founded in 2002, Keystone has more than 500 self-employed Principal lawyers today along with over 180 other fee earners. Its clients range from multinational corporations to fast-growing start-ups and high-net-worth individuals.
The Big Picture
The core investment case for Keystone Law centres on its platform business model. Rather than operating as a conventional law firm, it acts as a tech-enabled aggregator for senior lawyers.
Benefits of this strategy include:
- Scalability: Keystone’s platform model is highly scalable. This is illustrated by the fact that it now has over 500 Principal lawyers versus 398 in early 2023.
- Minimal property overheads: Because its lawyers work remotely, Keystone avoids the long-term, multi-million-pound lease commitments that burden traditional law firms.
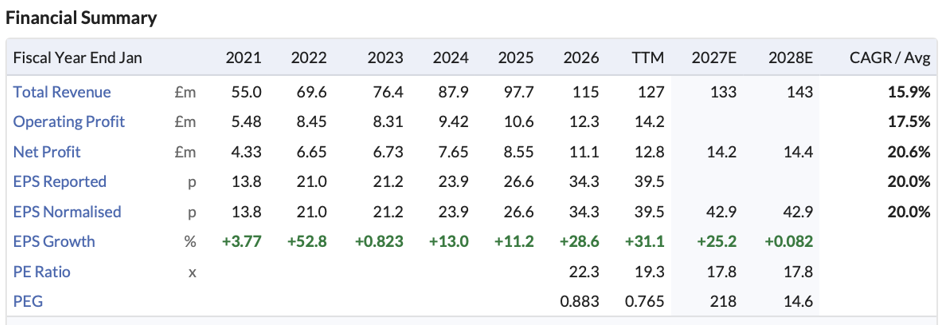
- Operational gearing: Central overheads (IT, compliance, billing) scale slowly relative to its revenue growth so incremental revenue from new lawyer additions flows efficiently to operating profit. Note that over the last five years, revenue has risen 109% while operating profit has climbed 124%.
Going Deeper
Keystone Law’s most recent results, for the six months ended 31 July 2026, showed that the company has momentum at the moment. For the period:
- Revenue was £66.3 million, up 22.5% year on year.
- Adjusted profit before tax (PBT) was £9.6 million, up 31.3%.
- Adjusted PBT margin was 14.5% (H1 2026: 13.6%).
- Adjusted basic EPS was 23.1p (H1 2026: 17.8p).
On the back of this performance, management declared an interim ordinary dividend of 9.6p per share (H1 2026 interim ordinary dividend: 7.5p) along with a special dividend of 15p per share.
In terms of the outlook, the company said that it had made a positive start to H2 FY2027. It also advised that it was expecting to deliver FY2027 revenue comfortably ahead and profits materially ahead of market expectations at the time.
“With a strong first half and an encouraging start to H2, we remain confident in Keystone's ability to deliver sustainable long-term growth."
Looking beyond the operational momentum, what stands out about Keystone Law is the high level of quality. This is a business with:
- A strong track record of top-line growth: Over the last five years, revenue has grown at a CAGR of 16%.
- A high ROCE: Return on capital employed has averaged 47% over the last five years.
- A robust balance sheet: Net cash was £10.5 million at 31 July.
- Rising ordinary dividends plus special dividends: Between FY2020 and FY2025, the ordinary dividend climbed from 6.5p per share to 20.2p per share.
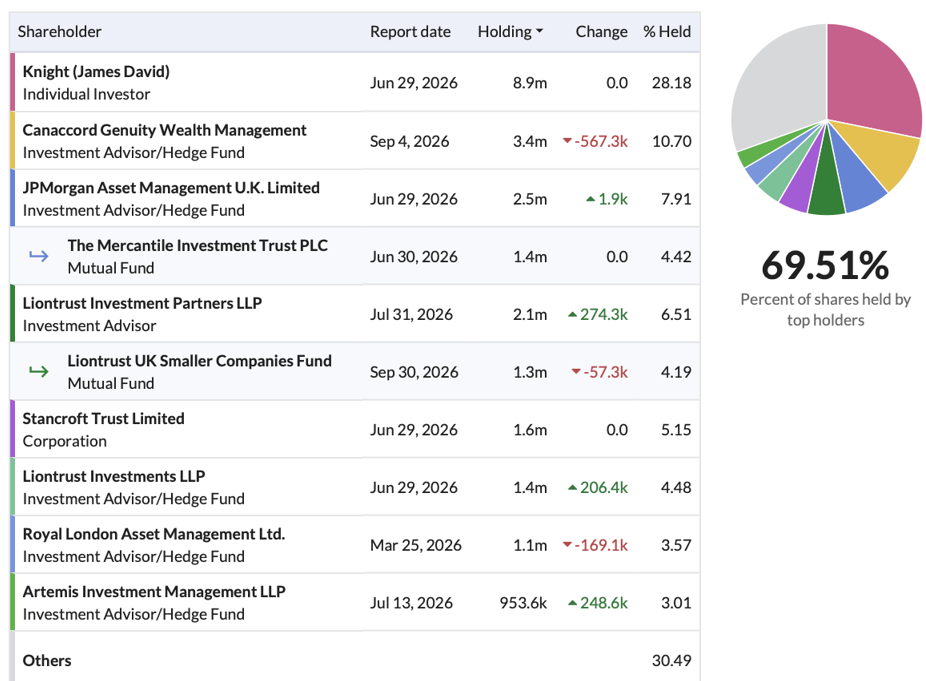
- Founder led: The company is led by founder James Knight who owns around 28% of its shares.
Turning to the chart, the share price is in an upward trend at present, sitting above its 50-day and 200-day moving averages. Recently, it broke out above highs of 2024 and 2025.
On the downside, the RSI is around 90. So, it could be a little ‘overbought’ at present.
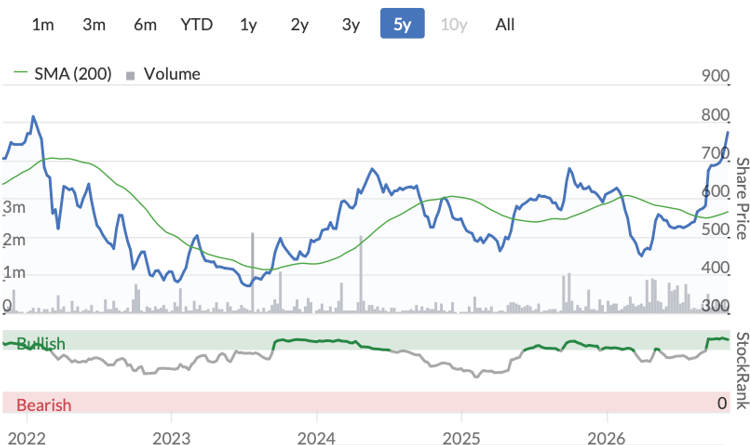
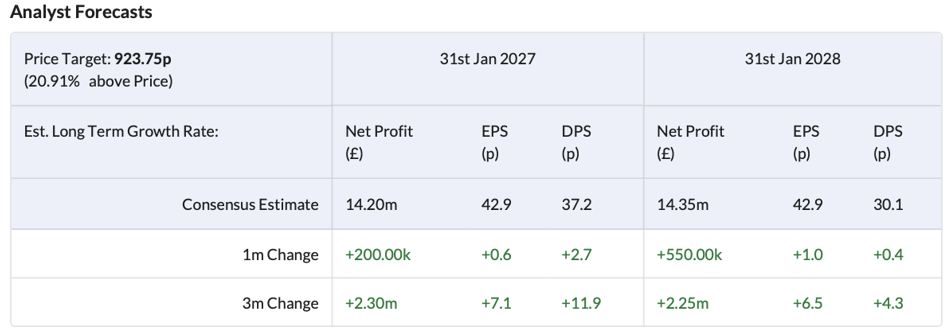
As for the valuation, the P/E ratio is about 18x, taking the consensus earnings forecast for FY2027 (42.9p). I think that’s quite reasonable given the quality here, even if the StockRank system gives KEYS a 30 for Value.
What the Brokers Say
Brokers appear to be quite bullish on Keystone Law:
- Multiple Buy ratings: All four firms covering KEYS rate it a Buy or Strong Buy.
- Upside potential: The average price target is 924p – about 17% above the current share price.
- Rising earnings forecasts: Earnings estimates are trending up.
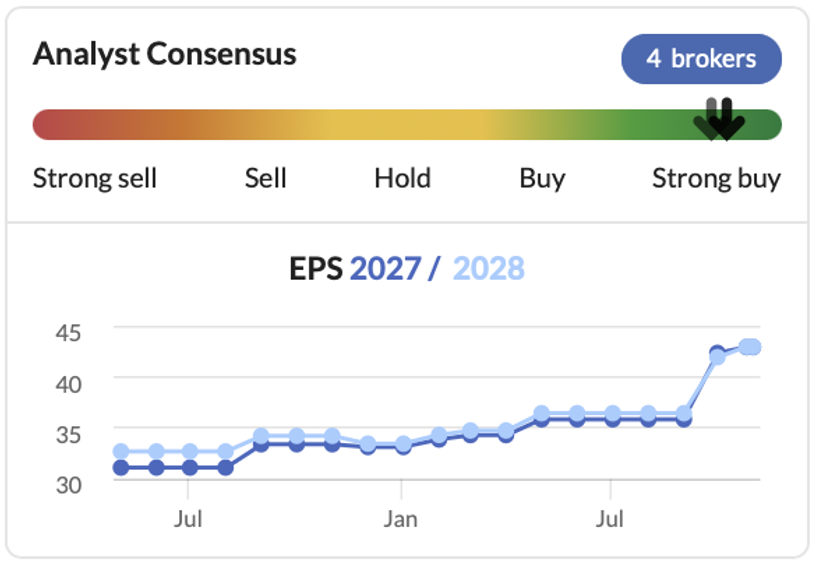
One thing to note here is that the EPS forecast for FY2028 is the same as the forecast for FY2027. So, there is scope for FY2028 EPS upgrades if Keystone can continue to perform.
The Bear Case
Risks with Keystone Law include:
- Economic weakness: A slowdown in the UK economy could result in less demand for legal services.
- Interest rates: High interest rates could squeeze capital markets deal volumes.
- Principal acquisition rates: During periods of economic uncertainty, senior partners can become risk-averse, delaying decisions to leave stable equity partnerships.
- AI disruption: There haven’t been any signs of AI disruption here yet, but we can’t rule out disruption from Claude and other generative AI models.
The Bottom Line
Keystone Law is essentially a technology platform dressed as a law firm. With its asset-light, aggregator business model, it is a very scalable company.
The bull case centres on its ability to continue attracting senior lawyers from traditional firms without incurring heavy office-related fixed costs. If it can continue to grow, it should be able to generate attractive returns for investors.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
With 500 principal lawyers turnover seems low. My other concern is liability insurance, how do they cover this given the cost of professional indemnity in the legal profession?
surely with insurance it becomes easier with scale ? - so surely its easier to get decent price (per) with pool of 500 plus workers