Large cap loonies: big companies that look too cheap
Large cap Loonies
Last week, as a follow-up to my Midcap Madness screen, I looked for Small Cap Silliness – companies between £30 and £300m market cap that look simply too cheap. Here are the criteria I used to identify cheapness:
Price-Earnings Ratio Forecast 1y < 10
I want companies that are forecast to remain cheap rather than one-off inflation beneficiaries.
Dividend Yield Rolling 1yr > 5%
While this isn't designed to be an income screen, a large dividend yield is a sign of companies where the price has declined, but the company retains its dividend payout. This may indicate that company management believes that the company's future is not as bad as the market has priced.
Stockopedia QV Rank > 70
This is a sense check that I am getting stocks with reasonable Quality and Value.
Industry Group excludes "Collective Investments"
I want to look for trading businesses, so I exclude funds and fund-like stocks.
In this article, I wanted to apply these same criteria to the large caps:
Market Cap: > £3b
One of the challenges with investing in large cap companies is that it is very difficult to get an informational edge. Whereas with a small cap, investors may be among the few who speak with management or model a company's finances, large caps will be covered by multiple brokers who are experts in their sector. Gaining an edge by more accurately predicting next quarter's earnings is unlikely to be a game the individual investor can win. Instead, investors need to lean on behavioural advantages. In reality, sentiment toward a stock often changes far more rapidly than the underlying business. Take, for example, perhaps the most boring stock in the FTSE100: United Utilities (LON:UU.) This is a highly diversified regulated utility. Despite being a very stable operating business, the share price of this company has ranged from just over £8 to £11 in the last year:

The individual investor can do well buying large cap stocks when they are unloved and selling when they are in vogue (or at least less widely hated). This Screen is suitable for identifying these candidates since very few large caps get to a sub-10 P/E and 5%+ dividend yield without the prevailing opinion being that there is something wrong with them. And there often is. Just that these issues are rarely terminal, and the market tends to overreact to these challenges. In my last article, a reader suggested that we would be better off looking for stocks that don't pay dividends, with the idea that these would be under-followed. While I am not averse to taking advantage of a lack of interest, investors need to look at microcaps without broker coverage to play this game effectively. This is unlikely to be an effective strategy for large and mid-caps, where instead, the value investor is looking for companies that are known to other investors but have been rejected due to superficial or short-term issues. This is what this Screen aims to identify.
The Results
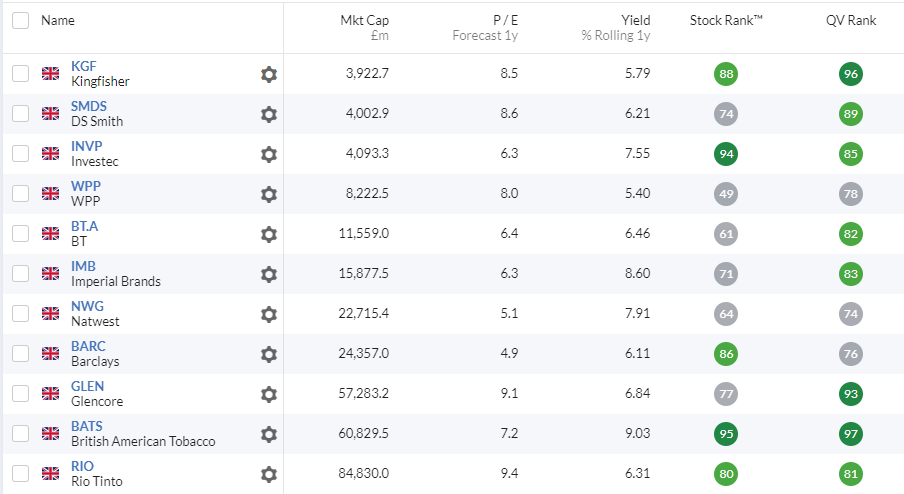
The Screen currently generates 11 results:
The Companies
DS Smith (LON:SMDS)
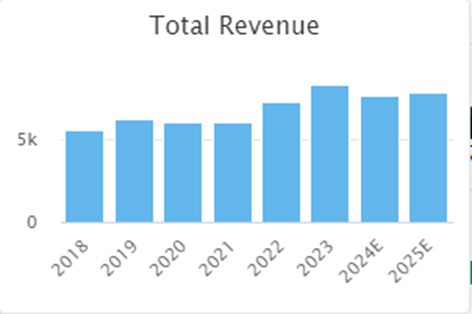
Cardboard packaging manufacturer has a record of consistent but fairly pedestrian revenue growth:
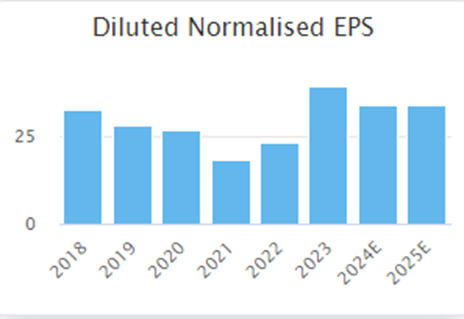
EPS is less consistent:
But operating cash flow is growing nicely:
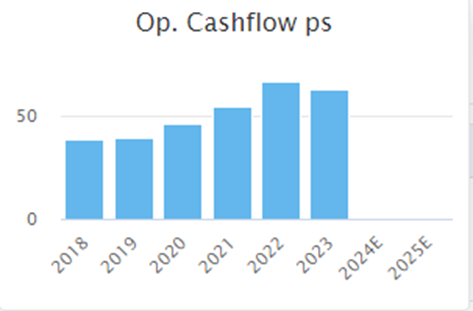
As is free cash flow, although increased capex in 2023 sees this drop slightly:
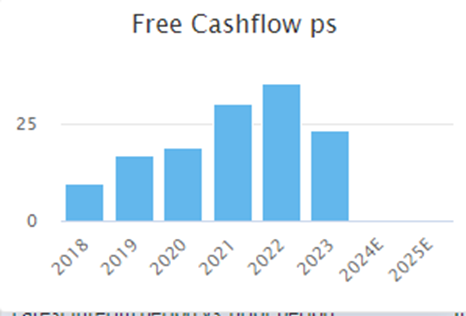
With a share price of 292p, this is a P/FCF. This is marked as red by the Stockopedia algorithms, but this simply reflects how cheap the industry sector has become.

This is more than enough to cover a dividend yield of over 6%.
One downside is that the Altman Z-score flags the company as in distress:
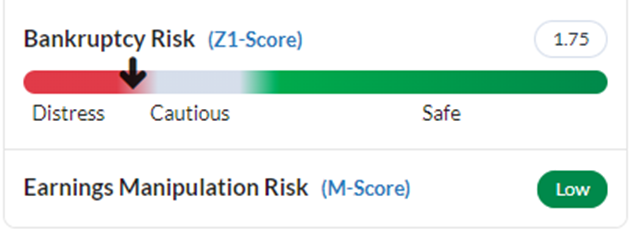
However, this is largely due to negative working capital:
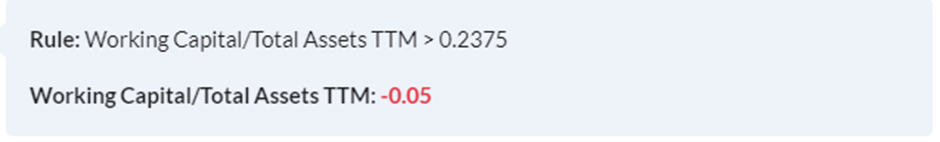
While investors may want to watch this carefully, the company always trades with this sort of working capital profile:
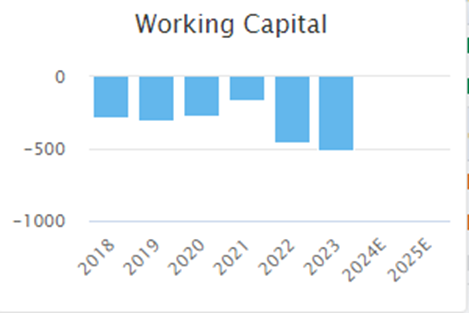
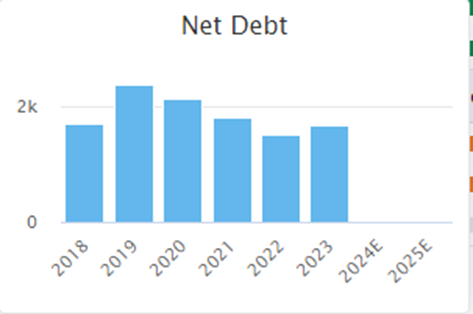
This shouldn't be a problem as long as revenue doesn't decline significantly. Particularly as net debt has reduced since a peak in 2019:
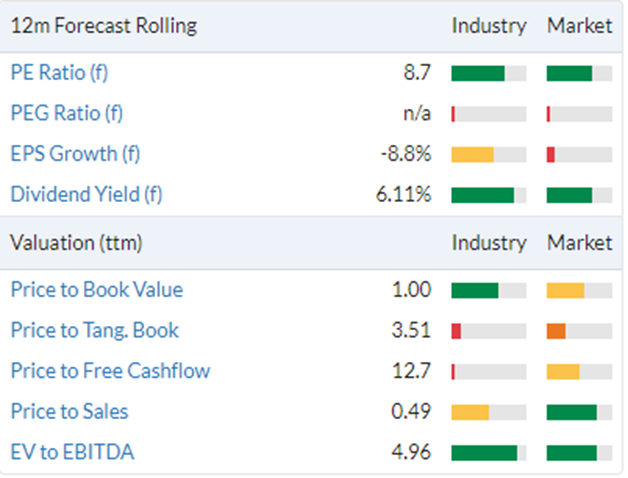
Overall, then, this makes the company look good value on a forward P/E of less than 9:
With the company confirming that they are trading in line with expectations at the AGM earlier this month:
Overall trading is in line with our expectations, driven by continued resilient pricing and strong cost control measures, despite end markets remaining challenging.
Investec (LON:INVP)
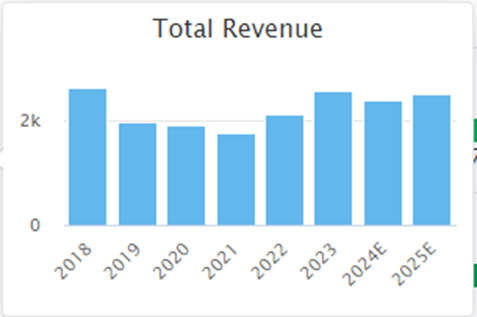
Investec is an Anglo-South African banking and wealth management group that is listed on both the UK market and the Johannesburg Stock Exchange. Investors may have come across the company acting as a broker for some of their holdings (although, sadly, this is a broker where individual investors can't see their research). Revenue here has largely been flat:
EPS was trending down until 2021, but a strong 2022 and 2023 reversed that trend:
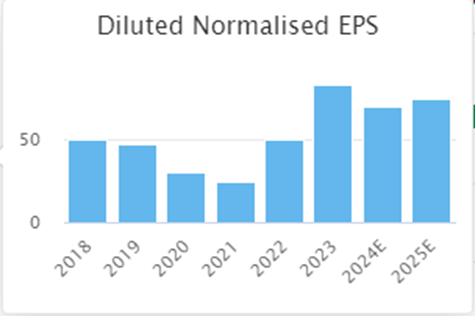
Given the weakness in IPOs, equity raises, and wealth management, this is an admirable performance driven by the banking side of their operations. As such, investors may want to focus on the P/B ratio, which doesn't show as good value as some other UK banks:
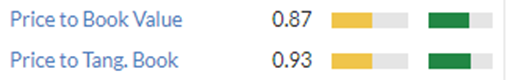
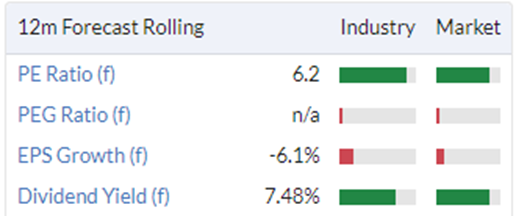
However, given that this is more diversified than the average UK-only bank with wealth management and investment banking arms, the low P/E and high dividend yield looks compelling:
WPP (LON:WPP)
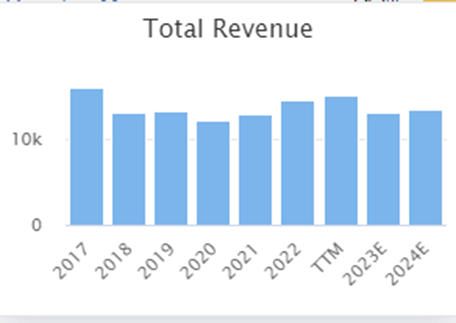
Revenue at this marketing agency has been flat for years:
As has EPS, apart from the COVID hit and bounce back:
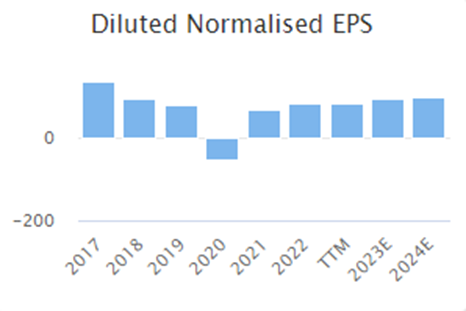
However, net debt has been increasing:
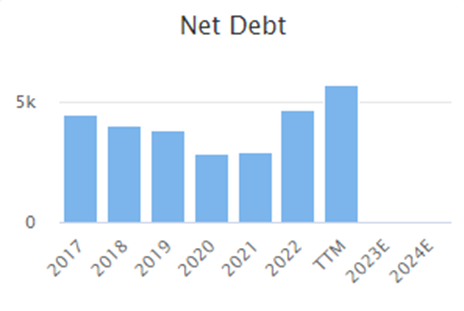
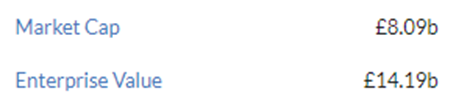
And makes up a significant part of the capital structure:
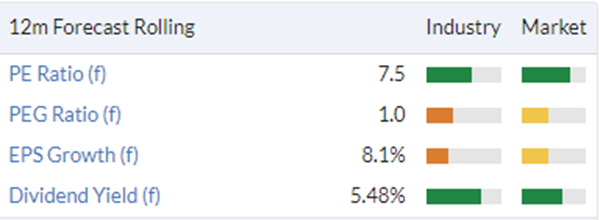
As such, the low P/E here probably represents fair value:
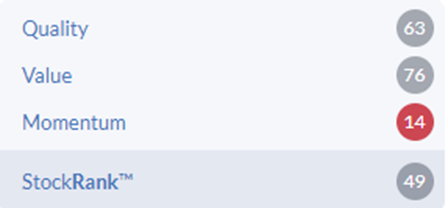
So, unfortunately, this doesn't look like a good investment proposition. Especially with a momentum rank of just 14:
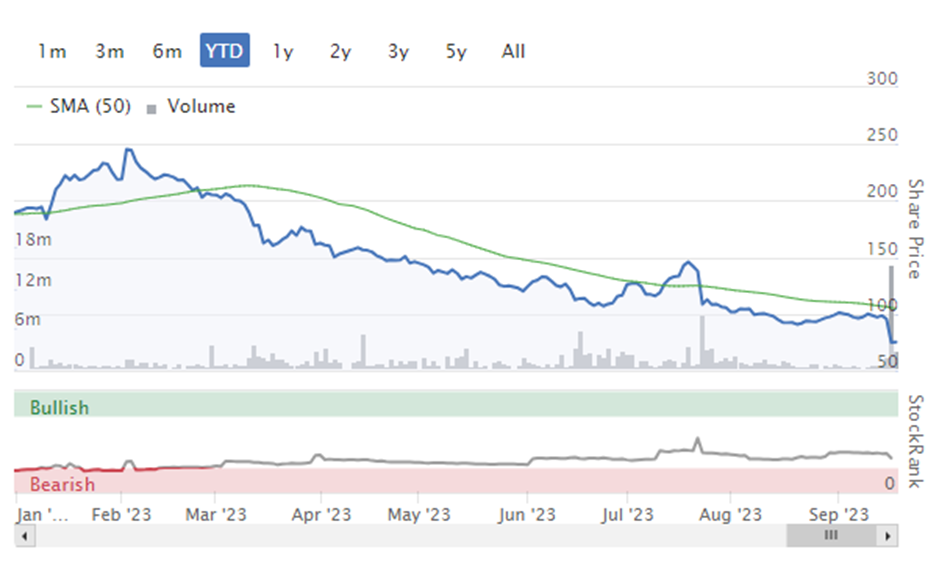
And with Sir Martin Sorrel's new venture S4 Capital (LON:SFOR) issuing a profits warning this week, there are further risks here:
BT (LON:BT.A)
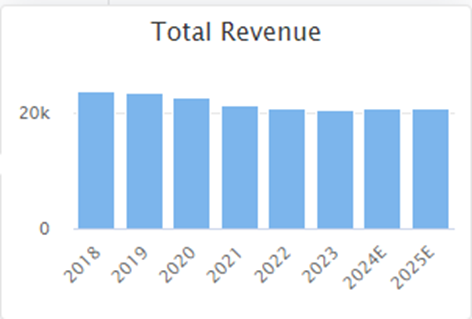
Revenue has been in slow decline here for years:
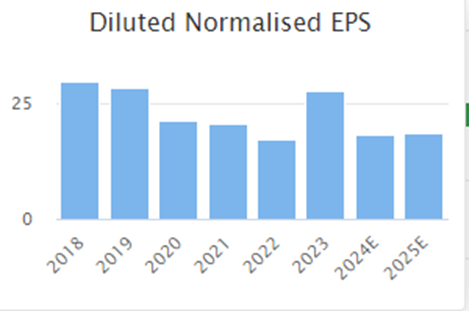
Which ends up being reflected in EPS:
However, operating cash flow is much better:
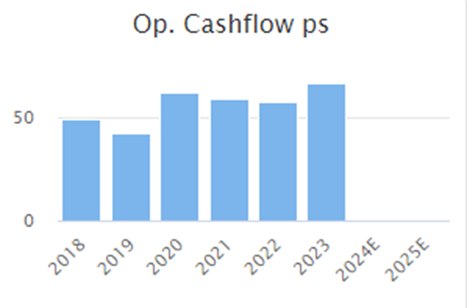
Leading to reasonable free cash flow:
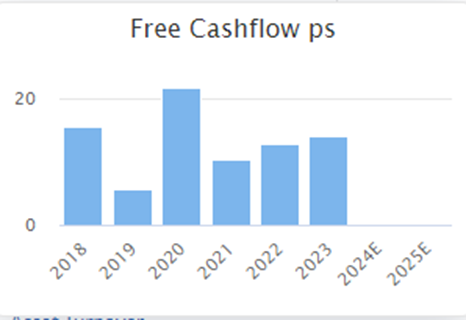
Which can be used to pay out a dividend yield of over 6%:
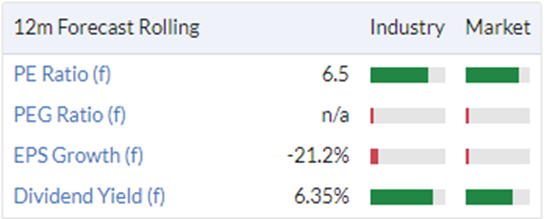
Unfortunately, there are two elephants in the room. This first is substantial net debt:
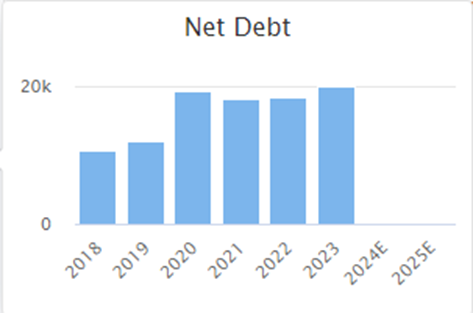
This will be taking increasing interest payments to service and leaving less for shareholder returns. The other place that cash needs to go is to service an £8b pension deficit at the last triennial valuation date:
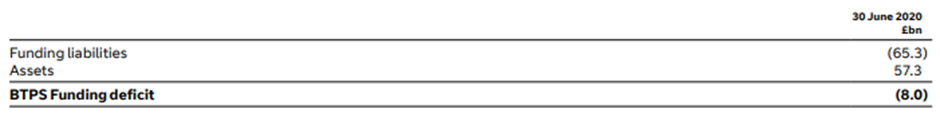
Given the moves in discount rates, this may be more favourable when the 2023 triennial valuation is complete. However, the risk is that their recent actions to employ a large amount of LDIs in the scheme assets may leave the scheme unable to benefit from the drop in discount rates. From the 2023 Annual Report:
At the triennial valuation date, the EEPS had a diversified investment strategy, investing scheme assets in: global equities (25%), property & illiquid alternatives (20%), an absolute return portfolio (24%) and a liability-driven investment portfolio (31%). The asset allocation at 31 March 2023 was: global equities (1%), property & illiquid alternatives (36%), an absolute return portfolio (7%) and a liability-driven investment portfolio (56%).
As such, this doesn't look cheap enough to overcome the apparent risks.
Imperial Brands (LON:IMB)
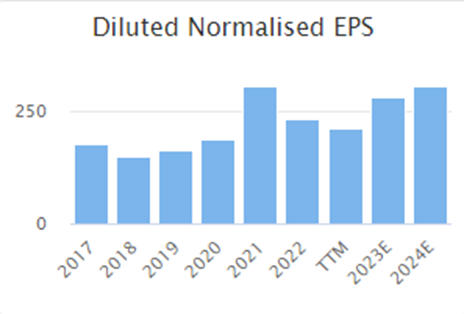
Investors need to make their own minds up on the ethics of investing in tobacco companies. Those who are comfortable with the ethics and regulatory risks of investing in Imperial Brands get a company with growing EPS:
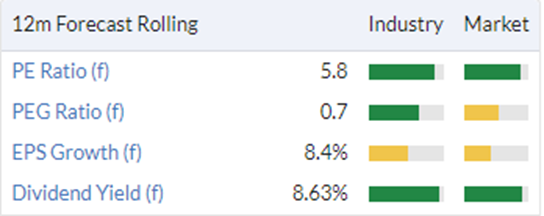
On very compelling multiples:
Natwest (LON:NWG)
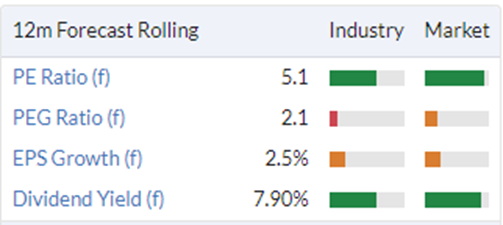
On a P/E and dividend yield basis, this UK-focused bank is one of the cheapest large cap companies:
Not only this, but they have an ongoing large buyback in place:
We are pleased to announce an interim dividend of 5.5 pence per share and intend to commence an on-market buyback programme of up to £500 million in the second half of 2023 in addition to the £1.3 billion directed buyback completed in Q2 2023 bringing total distributions deducted from capital to £2.5 billion for H1 2023.
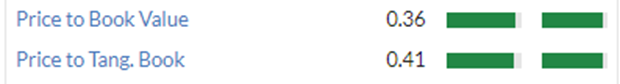
One thing the Great Financial Crisis taught investors was to be wary of investing in banks based on earnings metrics, as earnings can quickly evaporate. However, unlike the GFC, the company trades at a significant discount to book value:
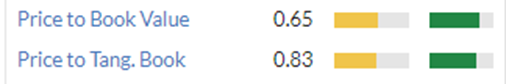
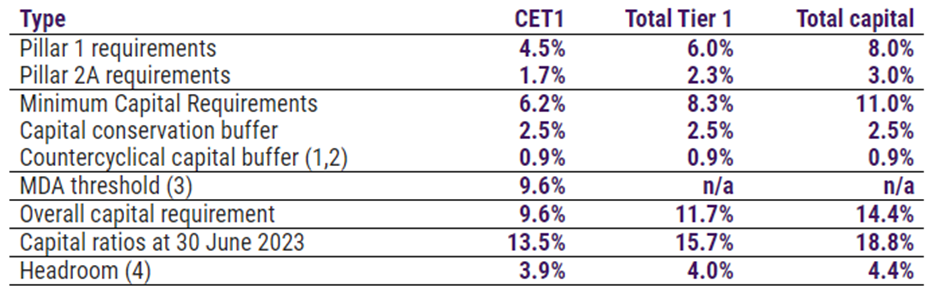
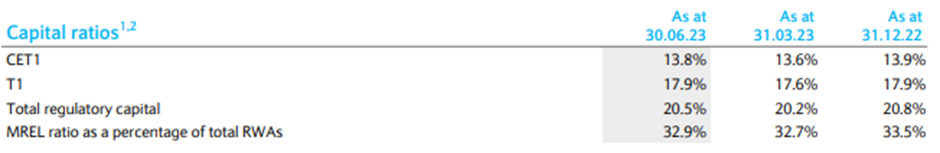
The bank is also in a completely different place financially, with capital ratios showing significant headroom to the MDA threshold, where they would have to stop dividends and buybacks:
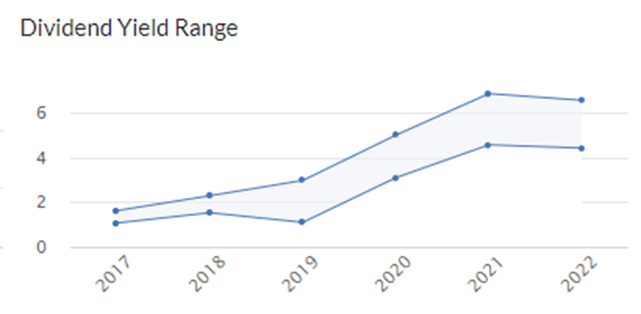
Given its exposure to UK housing and the economy, both of which are struggling in the wake of higher interest rates, investors may want to be cautious here. I am not a banking analyst, so I will not attempt to model these impacts. However, with higher rates, the bank also earns a much higher net interest margin. As such, it seems investors may have been overly cautious, leaving the valuation at a recent low:
Barclays (LON:BARC)
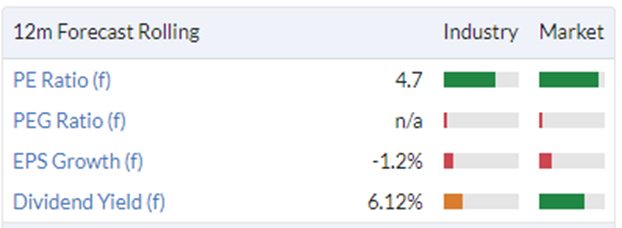
Barclays faces much the same risks as Natwest but appears even cheaper on everything but yield. Even here, a forecast dividend above 6% is not bad:
Barclays has very similar capital ratios, suggesting that it is similarly robust:
Glencore (LON:GLEN)
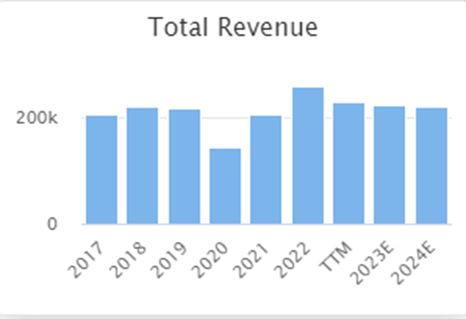
Commodity producer and trader Glencore's revenue largely follows the trend in global natural resource prices:
Their EPS trend is an exaggerated version of this due to operational gearing:
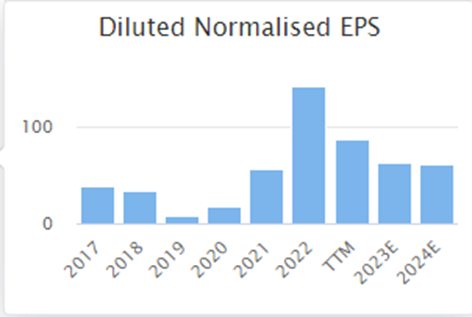
The peak earnings in 2022 are not forecast to be repeated any time soon, but the free cash flow looks more promising:
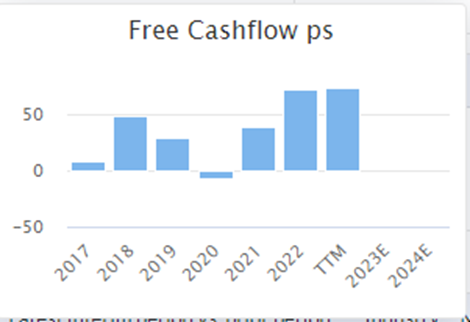
Which more than covers the expected 8% dividend yield in 2023:
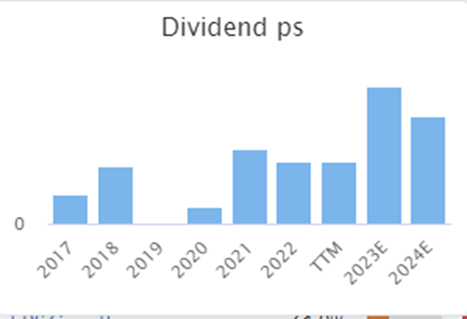
The dividend is not forecast to be at the same level in 2024 but still gives a dividend yield above 6%. This doesn't look like the cheapest stock on P/E but will appeal to income investors who want diversified commodity exposure:
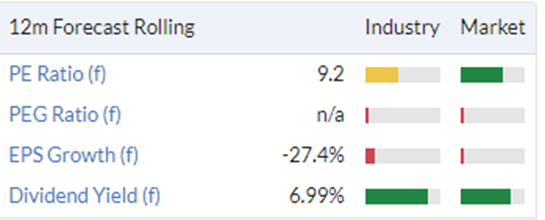
British American Tobacco (LON:BATS)
Compared to Imperial Brands, British American Tobacco is on a higher forecast P/E but pays a higher dividend:
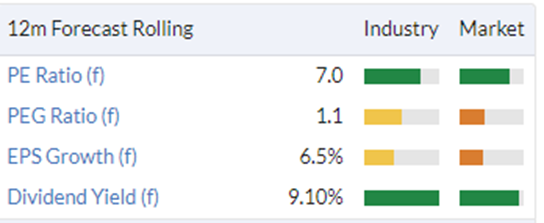
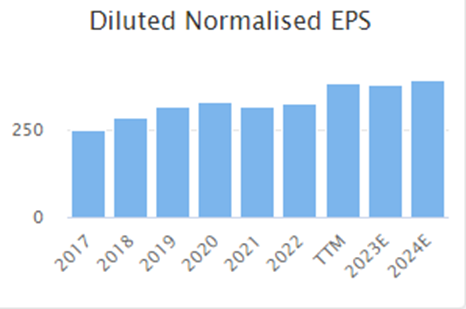
The EPS growth rate is similar, but growth is a bit smoother at British American Tobacco (LON:BATS) :
In the Stockopedia head-to-head comparison, British American Tobacco (LON:BATS) just edges it:
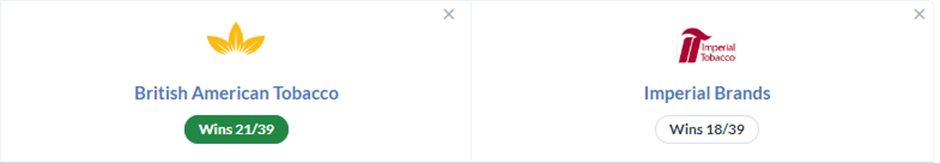
But there is little to choose between them, meaning that both could be suitable investments for the investor who is happy investing in such companies.
Rio Tinto (LON:RIO)
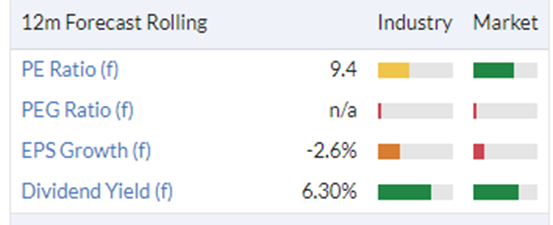
Completing our lineup, is Rio Tinto (LON:RIO) , the mining mega-cap. Similar to Glencore (LON:GLEN) , the P/E is not outstanding, but there is a decent dividend on offer:
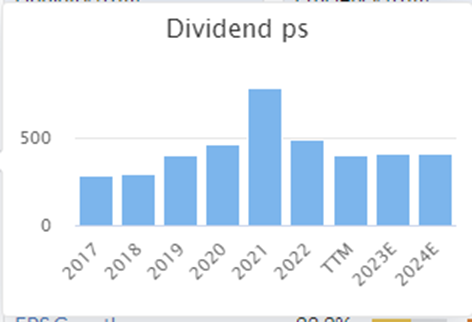
Which is forecast to be maintained going forward:
Unusually for a mega-cap, there is very little debt in the capital structure.
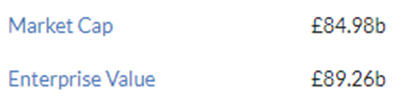
This means investors are getting pure exposure to its primary commodities of iron ore, copper, and bauxite (aluminium). Again, this will appeal to those who want a generous income with further upside if commodity prices rise.
Although I rarely look at large cap companies and hence don't currently hold any of the loonies, I am tempted to research DS Smith (LON:SMDS) , Natwest (LON:NWG) and Barclays (LON:BARC) further, as these appear to offer stand-out value to me.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Mark, I notice all the tags have gone missing, yet again, about Stockopedia sorted this problem out.
Interesting article. Thanks for posting.
Coming out of the 2008/9 bear market I bought British American Tobacco (LON:BATS) . I seem to recall nearly doubling my money over a few years. Who'd have thought you could do that with such a boring share?
I had sold and bought back in 2020 at 3001p (now 2735p), so I'm obviously taking a hit on that right now. Analysts are expecting dividends to rise in 2023 and 2024, as are earnings. So, pretty good, I reckon. I'd prefer debt to be lower, though.
My large-cap winners so far are BAE Systems (LON:BA.) up 81% (bought Nov 2021), 3i (LON:III) up 80% (bought Oct 2022), Shell (LON:SHEL) , that badboy is nearly double (bought Jan 2021). Who'd have thought that elephants could gallop?
I also have a few large-cap laggards (Bunzl (LON:BNZL) HALEON (LON:HLN, IG group (LON:IGG) and Unilever (LON:ULVR) (boy is that one a slow-coach). The first two are recent purchases, so they don't really count.
I'm happy enough to hold IGG. It's on a PE of 6.5, and has averages a ROCE of around 26% over the last few years. Its FCF per share over the last 6 years has been 85p, giving it a FCF yield of 12.7% based on a share price of 671p. That offers good value, in my view.
A share like Investec (LON:INVP) never occurred to me until I read your article. Net cash. Good dividend cover, and analysts expect divvies to increase. FCF per share has averaged 85p over the last 6 years, so if you believe that figure is achievable in the future, it gives a FCF yield of 19.4%. Looks good.
Bouden54Joined 2018650 postsJun 3, 2023
Worth noting that Mondi (LON:MNDI) are long paper - in other words they produce their own paper and thus exposed to the paper price. There are reports of over capacity in paper production which is expected to weigh on paper prices and could be a headwind for Mondi.
DS Smith (LON:SMDS) by contrast are net short paper, meaning they source more of their paper externally than they produce. They should therefore be less affected by falling paper prices. That said, DS Smith have the lowest margins in the sector so could be more vulnerable to a downturn.
Smurfit Kappa (LON:SKG) probably look the best name in this space.
The above comment after Roland Head's article on MNDI (Mondi)https://www.stockopedia.com/co... is pertinent to your research.
All I can offer to complement your useful article. I hold some and it helps me to add or avoid.
any link to the above screen?
Sorry, here you go: https://www.stockopedia.com/sc...
Interesting piece, tho I can see why you dont own any. I dont tend to look at ftse100 companies as theyre usually so damn boring, prefer a little sizzle to keep things interesting. That laziness cost me tho missing out on Rolls-Royce Holdings (LON:RR.) which now has lots of potential sizzle, tho obviously a much higher rating to match.
None of them have forecast EPS growth really either, best to me look the tobacco companies, tho who wants to own defensive tobacco when there's a whole heap of small/midcaps at good prices. I have Glencore in my watchlist as a potential short.