Legal & General appeals to savers

The insurance and savings firm Legal & General (L&G) has a 5% forecast dividend yield for 2015 which rises to 7% by 2018. The ageing population is a key driver as it encourages saving and boosts demand for retirement products. These trends suggest that L&G's shares offer an attractive savings vehicle.
Investors in financial shares sometimes compare the dividend yield they offer to the interest rates on their financial products. In the current low interest rate environment it is almost always the case that the shares offer higher payments.
Clearly equity investments have the risk of capital loss and so the comparison is somewhat unfair. However, Legal & General has rebounded strongly from the global financial crisis which suggests that the business is resilient.
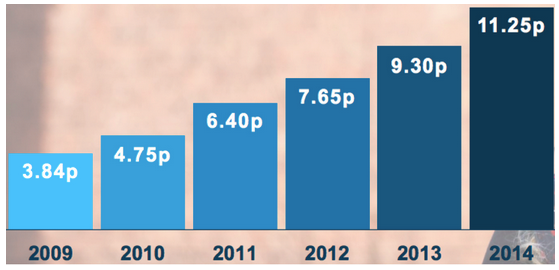
In 2007 the group paid out a yearly dividend of 5.97p which it then cut in the following two years to 3.83p in 2009. Since then the annual dividend has growth at rapid pace and hit 11.25p in 2014.
Legal & General's dividend rebounds
Source: Legal & General investor presentation
The net cash dividend cover has fallen from 2.72 in 2010 to 1.65X in 2014. Subject to solvency II requirements the group expects to reduce its dividend cover to 1.5X in 2015.
Future dividend growth will be driven by the underlying business as dividend cover can only fall so far. Legal & General has a “progressive dividend policy" which is supported by the tailwinds for its key divisions.
L&G's divisions
L&G Assurance is the largest profits generator and provides life insurance, general insurance and savings plans. The division benefits from the need for individuals to save more and buy protection products as the state retrenches.
Longer lifespans and the cut back in defined benefit pension schemes have driven a retirement savings gap. In response the UK government has introduced automatic workplace enrolment into pension schemes.
The second biggest division by profits contribution is Retirement which sells annuities. Demand for individual annuities has been hit by UK pension freedoms but corporate demand is robust demand as firms de-risk defined benefit schemes.
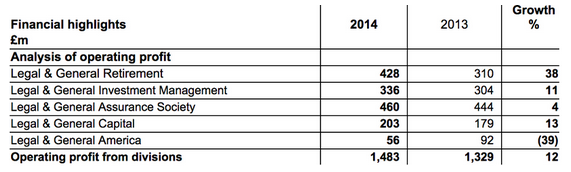
Assurance generated 31% of L&G's operating profit in 2014 while Retirement came in at 29%. Assurance saw modest 4% profits growth in 2014 but Retirement saw 38% growth despite individual “pension freedom" reforms.
L&G's divisional profits in 2014
Source: L&G investor update
Investment Management is the third largest division by operating profits at 22.6% of the total last year and saw 11% profits growth. It is becoming a global business with progress for the group in the US and Asia.
Business growth from 2011 to 2014
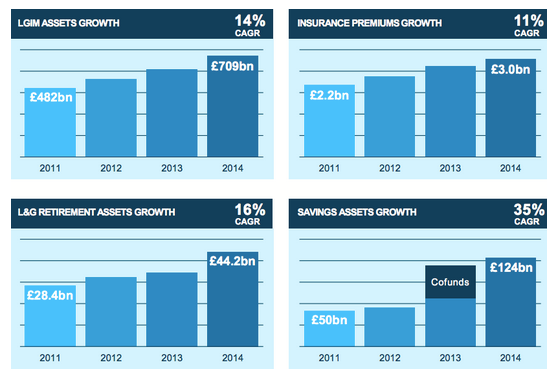
The business growth at these three divisions has been strong from 2011 to 2014. L&G Assurance has seen 11% annual growth in insurance premiums and 35% growth in savings, which is in part due to the takeover of cofunds.
L&G Retirement assets have grown at 16% a year from 2011 to 2014 with a number of large corporate deals signed last year. Investment management has seen 14% annual growth in assets to £704bn.
Strong business growth in L&G's three main divisions
Source: L&G investor presentation
Macroeconomic drivers suggest that this growth will continue despite a changing regulatory environment. The ageing population supports annuity sales, workplace asset growth and liability driven investment management.
Welfare reforms have also helped to drive growth for UK protection premiums for individuals and for corporate schemes. With government finances remaining under pressure further cutbacks in support look inevitable.
The globalisation of asset markets has also helped L&G grow its international assets to £129bn. The group recently won its first US$1bn plus Asian market and has entered the US index and defined contribution market.
Risk profile
While Legal & General's shares are now performing well the shares fell from a high of 167p in February 2007 to a low of 23p in March 2009. The fall in interest rates made life difficult for insurers as it hit their investment income.
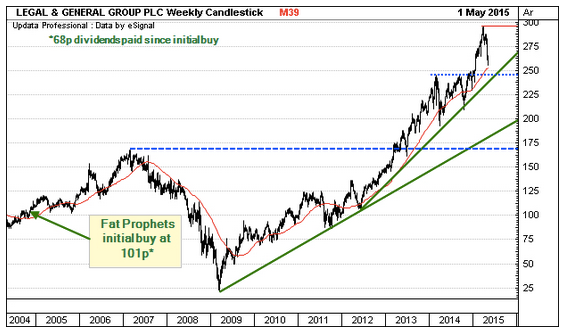
The shares saw a moderate sell-off in March 2014 on the announcement of new pension freedoms in the UK. Previously individuals were forced to buy annuities from companies like L&G with the pension funds upon retirement.
A potential source of risk going forward is the L&G Capital division which started in 2013 and invests directly in projects like housing. It made up 13.7% of 2014 operating profits and is meant to help L&G withstand tough market conditions.
Summary
As a diversified business L&G has been able to offset regulatory changes and successfully come through the financial crisis. The group is now well placed to continue to capitalise on the ageing population and welfare retrenchment.
UK pension auto-enrolment started in October 2012 at large firms and is being rolled out to smaller companies. This should help encourage individual pension savings in the UK while L&G has a strong position in corporate annuities.
Looking at the valuation and a moderate sell-off in the shares has pushed the forecast P/E for 2015 to 13.7X with a 5% dividend yield. This falls to a forecast P/E of 12.6X in 2016, 11.5X in 2017 and then only 10X by 2018.
Given the group's rebound from the financial crisis and the long-term business drivers the valuation doesn't look expensive. This is not least as L&G offers both dividend yield and underlying profits growth, which is an attractive combination.
This report was produced by Fat Prophets Senior Research Analyst, Andrew LattoDisclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?