Lookers: Set for Further Growth?
Lookers plc is an old and well established business engaged in the sale of cars and related services in the UK. Like many of its competitors, it suffered badly during the recession but has since made a good recovery and is trading strongly today. Following its growth over the past 6 years, the company turns up on a number of screens and appears to be statistically cheap in addition to having excellent momentum. The question is, as always, can this continue?
Screen Summary
- A PE ratio of 11.4x is attractive and appears to undervalue the company’s earnings.
- A PS ratio of 0.21x is very cheap indeed although, given the business’s low operating margins, seems somewhat justified.
- A PB ratio of 2.43x is seen as expensive.
- An ROC of 18.8% is excellent despite thin operating margins of around 2.4%.
- A dividend yield of 2.07% is low but may improve if dividends continue to increase as they have done.
Company Background
The Lookers Group was founded by John Looker in 1908, and was initially involved in the sale of bicycles, spare parts and used cars. It was not until 1910 that the business joined with a local garage owner to form Lookers ltd, at which point the business became primarily a Ford dealership.
Over the past 100 years the business has continued to grow, surviving both world wars and countless changes in the ever competitive auto industry. This is testament to the success of consecutive management teams who appear, collectively, to have fulfilled their duties as custodians. The fact that such an inherently low margin business has even survived this long is truly remarkable.
These days, John Looker would be proud that his business has spread from its humble beginnings in Manchester to serve every part of the UK and Ireland, to see it selling almost every car imaginable from Fiats to Ferraris and earning gross revenues of over £3 billion.
Strategy
In addition to its traditional business of selling new and second hand cars, Lookers is very much involved in the aftermarket, with significant earnings coming from the sale of service agreements and franchised parts. These revenue streams tend to be less volatile and have greater long term sustainability, providing a stable base which the company can rely on throughout the business cycle. On top of organic growth, the business has also stated that it intends to make selective acquisitions, where appropriate, to expand the group further.
Andy Bruce, the Chief Executive, states in his review in the 2014 accounts that the group’s aim is to be recognised as the most professional and successful motor retail and aftersales service group by customers, employees, partners and shareholders. This is certainly ambitious but I admire that and I quite like the way in which the approach is geared towards achieving this.
For example, the ‘customer for life’ strategy was launched two years ago, and shows the group’s belief in the importance of maintaining customers to its long term success. This process of continual research and customer satisfaction enquiry has led to initiatives such as extending opening hours to increase convenience and investment in the retail environment.
I like that the business appears to be so proactive in not only recognising areas for improvement but actually in taking action too. This is the same attitude that has helped the business to survive for over a century to date, and it’s great to see the old values held high.
Financials
The financial statements appear excellent at first glance. Revenue has risen smoothly since 2009 growing at a CAGR of 11.7%. As the scale of sales has increased, some efficiencies have been realised and we have therefore seen profit also rise at the far faster CAGR of 42.4%. It is unlikely that such a pace of growth will continue but this gives me comfort that the company’s strategy for growth has been working.
On the balance sheet, debt is certainly significant but does not appear to be unsustainable. The total amount of debt has varied from year to year but overall the trend appears to be downwards. Further, given that book value has increased significantly over this period, gearing has been reduced substantially which gives me further comfort over this aspect of the balance sheet. Finally, an interest coverage ratio of 6.41 times gives some assurance that the business will not struggle to pay interest obligations at its current rate of earnings.
Current assets and liabilities form the largest balance sheet numbers, which is to be expected given the nature of inventory. Under IFRS, inventory is held at the lower of cost or net realisable value, so I expect that a lot of inventory is held at the cost paid to the manufacturer, certainly as far as new vehicles are concerned. Consequently, even in a distressed situation, I think a significant portion of stated inventory could be realised. This is important to consider as inventory represents just under 50% of total assets and is therefore where much of shareholder value is held.
Finally, the cash position is currently not very good but a quick look at the cash flow statement gives us some idea of where the money has been going. Cash from operations has been steadily growing, is positive and has broadly supported net income, so why has the cash balance been falling? The cash from financing activities section reveals that significant amounts have gone every year since 2009 (bar 2014) to paying down debt. This fits in with the story we have seen with the overall debt position and in my opinion is a responsible use of cash.
A Long Term Opportunity?
While current growth appears excellent, is this really the kind of business that we might want to invest in for the long run? I have performed a simple quantitative analysis to demonstrate why I think the answer to that question is no at current prices.
I will consider the 20 year period up until 2035, and am attempting to determine a reasonable growth rate for the UK auto industry over that period. My logic is that the current UK population growth rate can reasonably be expected to remain as it is, and that the number of cars per capita in the UK will also remain constant. I can then extrapolate the population growth rate out to 20 years and apply the ‘cars per capita’ constant to arrive at an expected UK car parc in 2035. From this, it is then possible to calculate an expected annual growth rate in the number of cars in the UK:
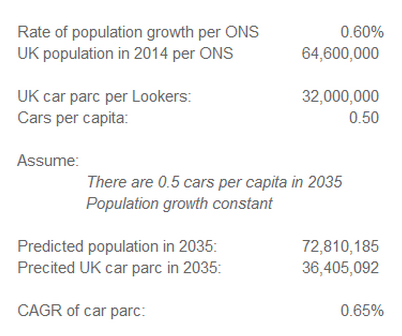
While I am aware that this is simplistic, I think it serves its purpose of demonstrating that the total UK car parc is highly unlikely to grow quickly in the long run. If we also make the assumption that the long run average ratio of the number of car sales (both new and second hand) to the UK car parc is constant, we can deduce that the total number of car sales in the UK is likely to grow at a very slow rate as well.
Now let us consider the valuation of the company on a discounted cash flow basis. Using a simple two stage model, I have performed a rationalisation to demonstrate what the company’s growth profile will have to look like over the same 20 year period in order to justify the current valuation.
First of all, I have used a discount rate of 10%, which I would normally consider too low for a company like Lookers. For a terminal value after the 20 year period, I have assumed a growth rate in line with the long term growth rate in UK GDP of 2.5%. I have then used the goal seek function on excel to find the growth rate in FCF required over the 20 year period for the model to produce the current share price.
I found that an annual FCF growth rate of 10.19% is required over the 20 year period in order for the valuation to reconcile to the current share price, despite the use of a generous discount rate.
In other words, to merely justify its current price, Lookers would have to grow FCF every year for the next 20 years by just over 10%, while participating in a market in which we can reasonably expect total sales to grow by less than 1% per annum. The only way for Lookers to achieve this is to either earn significantly higher margins or to make up a much larger part of annual UK car sales. Both scenarios seem unlikely to me given the business’s long history of low margins and the level of competition in the auto industry.
Concluding Thoughts
The long term prospects of the company are not bad, and the focus on creating ‘customers for life’ through servicing agreements and the franchised parts business is likely to provide durability for at least part of the company’s earnings.
However, when considered rationally, the company’s growth cannot be expected to continue as it has done in the long run. On top of this, a high growth rate appears to be built into the current market capitalisation, so a slowdown in growth is likely to see a reduction in the valuation even if the business remains highly profitable.
It seems to me that much of recent success can be attributed to a low interest rate environment and the economic recovery, factors that will not remain constant forever. That said, for the time being we are still in a period of broad economic growth and interest rates remain low so perhaps it’s not quite over. As is indicated by management’s recent trading statement, earnings growth does not appear to have halted just yet and the stock could therefore make sense as part of a diversified, systematic portfolio strategy.
My analysis has thrown up no big red flags that would lead me to exclude the company from such a strategy and, given the low valuation on an earnings multiple basis, the momentum of the underlying business and its share price, I would expect the stock, statistically speaking, to perform well over the short term.
Hope you enjoyed the article, if so then please share it with your network and feel free to leave any comments or questions below – I am always particularly interested to hear opposing points of view!
At the time of writing I do not hold a position in Lookers plc – LON:LOOK
It is important to note that all opinions expressed in this piece are the opinion of the author only and do not, in any way, constitute investment advice. Any individual seeking to make investments of any kind should conduct thorough proprietary research so as to fully understand the risks they are taking.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
2 comments
Tom, may I ask why you chose Lookers for your analysis,
whether you compared this company with its sector peers
and whether you have done overall sectoral research,
covering such areas as market share, trends and growth.
I can understand your approach, essentially one that is
figures- and assumption-based extrapolation, but it's an
approach that I personally feel uneasy with as it seems
to me to disregard the commercial and market aspects
of the business. It is only part of what is needed in order
to make an investing decision, imo.
Hi Jane,
Thanks for your comment. Firstly, in answer to the second half of your post, I agree entirely with you that this is a heavily assumption-based quantitative analysis, and that if I were to really consider investing for the long run I would want to do a lot more work into Lookers' specific place within the market, its competitive advantages and disadvantages and the strengths of other competitors too.
Such analysis is quite time consuming (as I'm sure you know!), however, and a thought process similar to this one is something I put all ideas through at first in order to determine if I might want to invest the time to look further. As someone in full time employment and with a lot of studying on the side, I don't get that long to look at everything so its key to me that I have a way of focusing my efforts.
All this analysis says to me is that the discrepancy between the rough expected long term growth rate of the motor industry in the UK and the growth rate required by Lookers to justify its current valuation is too great for me to warrant spending the time on.
Lookers appears to be a well run company and they may well achieve the superior growth they need in an optimistic scenario. On the other hand, they may not, and I would rather pick investments that are priced such that I am likely to see a good long term return even if the ideal scenario does not transpire. Had my DCF analysis indicated that a long term growth rate of only 1% was needed to justify today's price, for example, then I might be tempted to look deeper as this would be a much easier target for the company to hit.
On the first point, I chose Lookers for a couple of reasons. I have been looking into the industry a little bit recently as a number of such companies are appearing on screens after a profitable few years. Lookers is one that seemed quite attractive to me on the screens (consistent earnings and dividend growth, consistent and improving ROCE etc) and so I thought it might be one that others would be looking at too and therefore interested in reading about.
I'm still doing a bit of reading on a few of them though and may consider writing up a comparison piece to look at the competitive positions of Lookers and some others - thanks for the idea! Hope that answers your questions and please do say if I haven't explained that well at all.
Tom