LVMH - life of luxury

LVMH is the world’s largest and most diversified luxury goods business with 70 brands and a retail network of over 3,300 stores.The Fashion & Leather Goods division generates over half of profits and includes Louis Vuitton.Luxury demand has positive drivers but is currently seeing a slowdown in Chinese sales.
Bernard Arnault is France’s richest man and is the Chairman and CEO of the French luxury goods giant LVMH.Mr Arnault’s family has a majority of the voting rights in LVMH despite owning only a 46.6% stake.
This structure appears to have worked out well for investors in LVMH with Mr Arnault having grown the company successfully. LVMH is currently the only luxury goods firm that is present in all sectors of the luxury market.
LVMH revenue split in 2014

LVMh’s diversification helps reduce the exposure to any one brand and therefore makes it less exposed to a shift in fashion. This is important given the mixed fortunes of companies like Mulberry, Prada, Coach and Michael Kors.
The long-term investment case for luxury goods is based on the resilient nature of the brands and growing demand. In the Wines & Spirits division the allure of Hennessy, KRUG, Moet & Chandon and Dom Perignon is unlikely to fade.
Growing demand is mainly driven by Asia but across the world the “rich are getting richer.” The luxury goods can also be very profitable as customers focus on prestige and brand quality rather than the price.
LVMH share price
The €86bn Luxury goods group has delivered:
LVMH’s profit drivers
In terms of profits and the Fashion & Leather Goods division generated 56% of LVMH’s profits in the first half of 2015. The Wines & Spirits division contributed 16.3% of profits and then Selective Retailing came in at 14.5%.
The Fashion & Leather Goods division made up only 35.5% of first half revenue and so has strong profit margins. It is the key division that investors focus on for the sales performance and the reception for brands at fashion shows.

The weakness of the euro from early 2015 has served to bolster revenue and profits in euro terms.In the first half of 2015 only 22% of revenue was invoiced in euros while 31% was invoiced in US dollars and 8% in Hong Kong dollars.
Recent trading: Organic revenue growth picks up
Turning to recent trading and organic sales growth reflects the underlying business performance. It is defined as revenue at constant exchange rates and excludes the impact of any acquisitions or divestments.
LVMH’s organic revenue growth was 9% in 2012, 8% in 2013 and had slowed to 5% by 2014. Part of the weakness was due to the anti-corruption campaign introduced by the new Chinese leadership.
The first quarter of 2015 saw organic revenue growth at LVMH come in at only 3% but it rebounded to 9% in the second quarter. As such organic revenue growth in the first half of 2015 came in at a respectable 6%.
LVMH picks up the pace in Q2
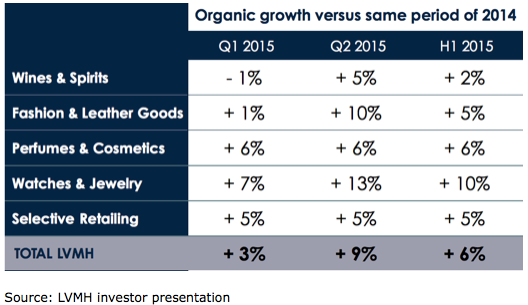
The Fashion & Leather Goods division saw 1% organic revenue growth in the first quarter but this increased to 10% in the second quarter.This has helped bolster investor sentiment given that it generates the majority of profits.
LVMH points to a “strong creative dynamic” at Louis Vuitton under Nicolas Ghesquiere. This is highlighted by the success of the Monogram collection, new leather lines and well received collections at fashion shows.
The Wines & Spirits division saw a 1% fall in organic revenue in Q1 but this reversed to a 5% gain in Q2. The other three divisions either saw momentum pickup or remain flat in the second quarter from the first quarter.
Looking towards the second half of 2015 and the momentum should remain in place given strong marketing and sales expenditure. In the first half of 2014 this was €5.48bn but in the first half of 2015 it had increased to €6.6bn.
Financial performance
The weak euro meant that reported revenue was up 19% in the first half on a year ago to €16.7bn. However, higher marketing and sales expenditure pushed the operating margin down to 17.7% from 18.4% in the first half of 2014.
This meant that the profit from recurring operations increased by “only” 14.7% in the first half of 2015 on a year ago to €2.95bn. The balance sheet remains robust with the net debt to equity ratio at 25% at mid-2015.
Summary and valuation
LVMH offers exposure to the luxury goods sector with less of the potential issues that rivals are exposed to. Its product diversification has helped it to offset weakness in any one market and the business is also geographically diversified.
At the same time the Fashion & Leather goods division generates the majority of revenue and is dependent on “remaining in fashion”. Key division brands include Pink, Loewe, Louis Vuitton, Mark Jacobs, Berluti, Dona Karan and Givenchy.
In terms of management the leadership of Bernald Arnault has kept the family controlled group at the forefront of its industry. It has also served investors well with the shares performing strongly in recent years.
Turning to the valuation and the luxury goods sector tends to trade at a premium to the market due to its profitability. LVMH is on a forecast P/E of 22X for 2015 which falls to 19.7X for 2016 and then 17.7X for 2018.
This is not expensive versus the luxury goods sector as a whole and looking further out the P/E falls to 15X by 2019. The long-term track record of LVMH and its strong brands suggest that the shares will deliver over the long-term.
This report was produced by Fat Prophets Senior Analyst, Andrew Latto
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?