Mader Group - Keeping the machines working

One of the things about broad market sell offs is that they can create opportunities to buy into stocks who are performing well operationally, however their prices had previously done so well, investors were reluctant to take the plunge.
One such stock is Mader (ASX:MAD). Over the past 24 months the stock has increased from 90 cents to eventually reach a peak of $4.84 in February. While the days of 90 cents are well and truly behind it (investors hope), the recent market nervousness has seen the price fall 20% from its peak.
So is this indeed an opportunity for those who missed out on the ride the first time around?
For those unaware, MAD provides specialist labour for the maintenance of heavy equipment in the resources and energy sectors. They also deliver a range of ancillary services such as electrical and mechanical maintenance in the rail, power generation, and marine markets.

Founded in 2005, and subsequently listing in 2019, today the company has operations in Australia, North America, Africa and Asia. Australia still accounts for the majority of revenue and profit, though the company has big aspirations for its North America business, more on that in a moment.
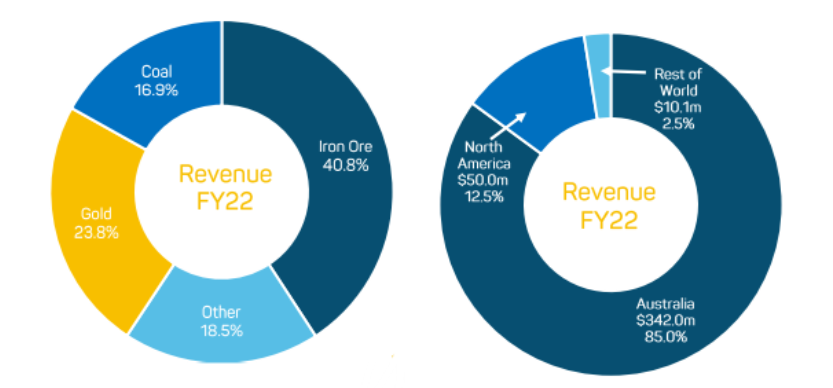
Source: MAD results presentation FY22
Companies in the outsourced maintenance services industry generally compete on price, quality of services, and just as importantly, capacity to provide services.
The company positions itself cheaper than equipment specialists (manufacturers) but on better quality and reliability than lower cost recruitment-based labour hire firms. Their ability to be flexible with the wide brand names they work with is also a major benefit over single supplier equipment specialists.
With over 2,500 technicians on staff, there are almost no other competitors that can deliver the wide range of services MAD does.
StockRank

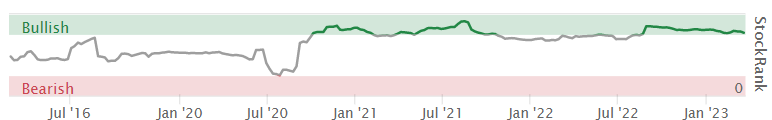
Since late 2020 the stock has hovered around a StockRank of 80, currently finding itself at 76, most likely on account of the recent drop off in Momentum.
From a QualityRank perspective the company rates highly at 85. With most Quality metrics bright green, the question some may ask is why is it not higher?
Part of the answer can be found in the Piotroski score. Given the company’s size, it F-Score carries a lot of weight and with a score of 6 out of 9, it ranks as “a little better than average, but not great.”
The other reason is the company has exhibited lumpy free cash flow on account of its large capital expenditure bill in the FY2022 period, which doubled on the previous. This has had an impact of returning a negative Free Cash Flow number, and still is the case on a TTM basis. This carried over to the recent half year result with payments for plant and equipment much higher than12 months ago.

Source: MAD HY23 report
The company continues to invest in property, plant and equipment as they look to grow and continue to meet needs of its clients (which include the likes of BHP, RIO, FMG etc)
Interesting though that at the latest half year result the company said the 90% increase in net debt was on account of the growth in working capital requirements to support the continued revenue growth of the Group. This will be something to watch how it progresses over time because to date, they have prided themselves on their strong balance sheet.
The biggest conundrum for many investors has been the ValueRank which is still quite low, and even after the recent pull pack, it is one of the more expensive mining services businesses out there.
The reason why they don’t carry the similar ‘mining services sector’ discount, is unlike many in the space who quote for work on thin margins and then try to fulfil the role without going broke, MAD earn most their revenue at hourly rates per tradesperson provided, therefore the utilisation of staff is more important than work in progress. This makes things more manageable and much less risky operationally. The market therefore attributes this added control in the valuation.
The MomentumRank over the past few months has been a challenge (though it is definitely no island here). Thirty days ago the stock had a MomentumRank of 99, however that has fallen by 12 points since on the back of the poor month from mid-Feb to now.
While the score is now 87, long term price momentum still remains solid, though the short term blip and the fact that it has performed worse than the market in the month has been a drag.

Despite the pullback, analysts haven’t stopped their upgrade cycle charge, consistently upgrading the stock since June. Most recently at the time of the half year profit result.
We last covered MAD in a momentum article back in December last year. At the time we pointed out how the resistance level of around $3.30 had now become support. Interesting to see that 4 months later after bouncing off that support line it reached its all-time high, but is now retracing back to that level.
It will be very important that this level holds as the Head and Shoulders pattern formed between January and March means that should the level be breached, $3.10 becomes an inevitability.
Any glass half-full investors may actually see the recent short-term lower low as a new base. That is because it is still higher than the low of December, and if it can rebound more, history may show this as the start of another up leg. We shall see.

ASX:MAD 1 yr Daily chart
Outlook
The company at its most recent half year profit announcement, upgraded its FY23 guidance to revenue of at least $580m, delivering an NPAT of at least $37m. This equates to 16% and 11% growth respectively.
Consensus analyst expectations are for slightly higher than that, but overall have seemed to put a fair bit of weight to that outlook.
North America is where the company sees immediate growth coming from in the 25 states where they have active operations. They have completed a significant recruitment program in Canada and revenues are rapidly growing in the region. For example, over the last 6 months revenue grew 197% to $57.4M. This means the region now accounts for 21% of total revenue.
Into the future they also see a massive opportunity in the North American Energy Markets where the total addressable market is deemed to be just as large as the mining maintenance sector. While early days just yet, there is the potential to achieve solid growth there as well.

Source: HY23 MAD Financials presentation
It was the heavy investment into Canada that in large part resulted in the increased level of working capital required. Though the company believes the size of the opportunity makes it worthwhile.
The other added benefit emerging from the North America business is the improved margins being generated. In the latest half yearly update the North America segment had margins of 19.2% vs 11.5% in Australia. As North America grows to be a bigger portion of revenue, this should enhance profitability.
But let’s not be too quick to forget the company’s strong presence currently in the Australian market. It is estimated that MAD have circa 75% penetration into Australian mines. While the domestic business in mobile equipment maintenance is long established, future growth in the region is more likely to come from the emerging fixed plant maintenance division.
One thing is for sure, the cash generation from the Australian business will go a long way to supporting the global expansion.
Holders
The current largest holder in the company is Luke Mader who founded the company that bears his name. With over 58% interest in the company, his interests are definitely aligned with that of shareholders.
Board member, and early Investor Craig Burton has 19.5%. In total the top 20 shareholders hold 82.5% of the company.

Despite this, the stock trades on average $350,000 per day. While this is not huge, it is liquid enough for most to take a position in the stock.
The company has been frugal in issuing shares. In fact it has not raised any capital since its back-door listing as MAD back in 2019. It’s one of the key reasons why the company retains much of its cash, only paying out a dividend of 4 cents (1.1% yield fully franked) equal to a 27% payout ratio.
Risks
As with all mining services businesses there are risks, though as discussed earlier they are somewhat mitigated by the utilisation pricing structure they follow.
Key risks include 1) Labour availability and cost pressures, 2) price pressure from competitors, 3) cyclical future earnings from a cyclical business, 4) loss of key customers who make up a large part of the total revenue and 5) there is a risk that customers decide to insource these functions in the future if the costs get too high.
There are also the regular risks of future capital needs, lack of stock available for investors to participate with, key person risk and geopolitical risks - though mitigated somewhat by our strong trade relationships.
Conclusion
MAD has found a profitable niche spot in the Australian mining sector boom, and with opportunities in North America ahead of it, investors have been willing to support the stock to date.
For some, the stock has been overvalued, and though it still is, the pullback in recent weeks may prove an opportune time to re-look at the investment case for this mainstay of the mining sector services space.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?