Market Musings 010424: gold surges even higher

Market Musings 010424: Gold surges yet higher
Gold gallops to new all-time highs
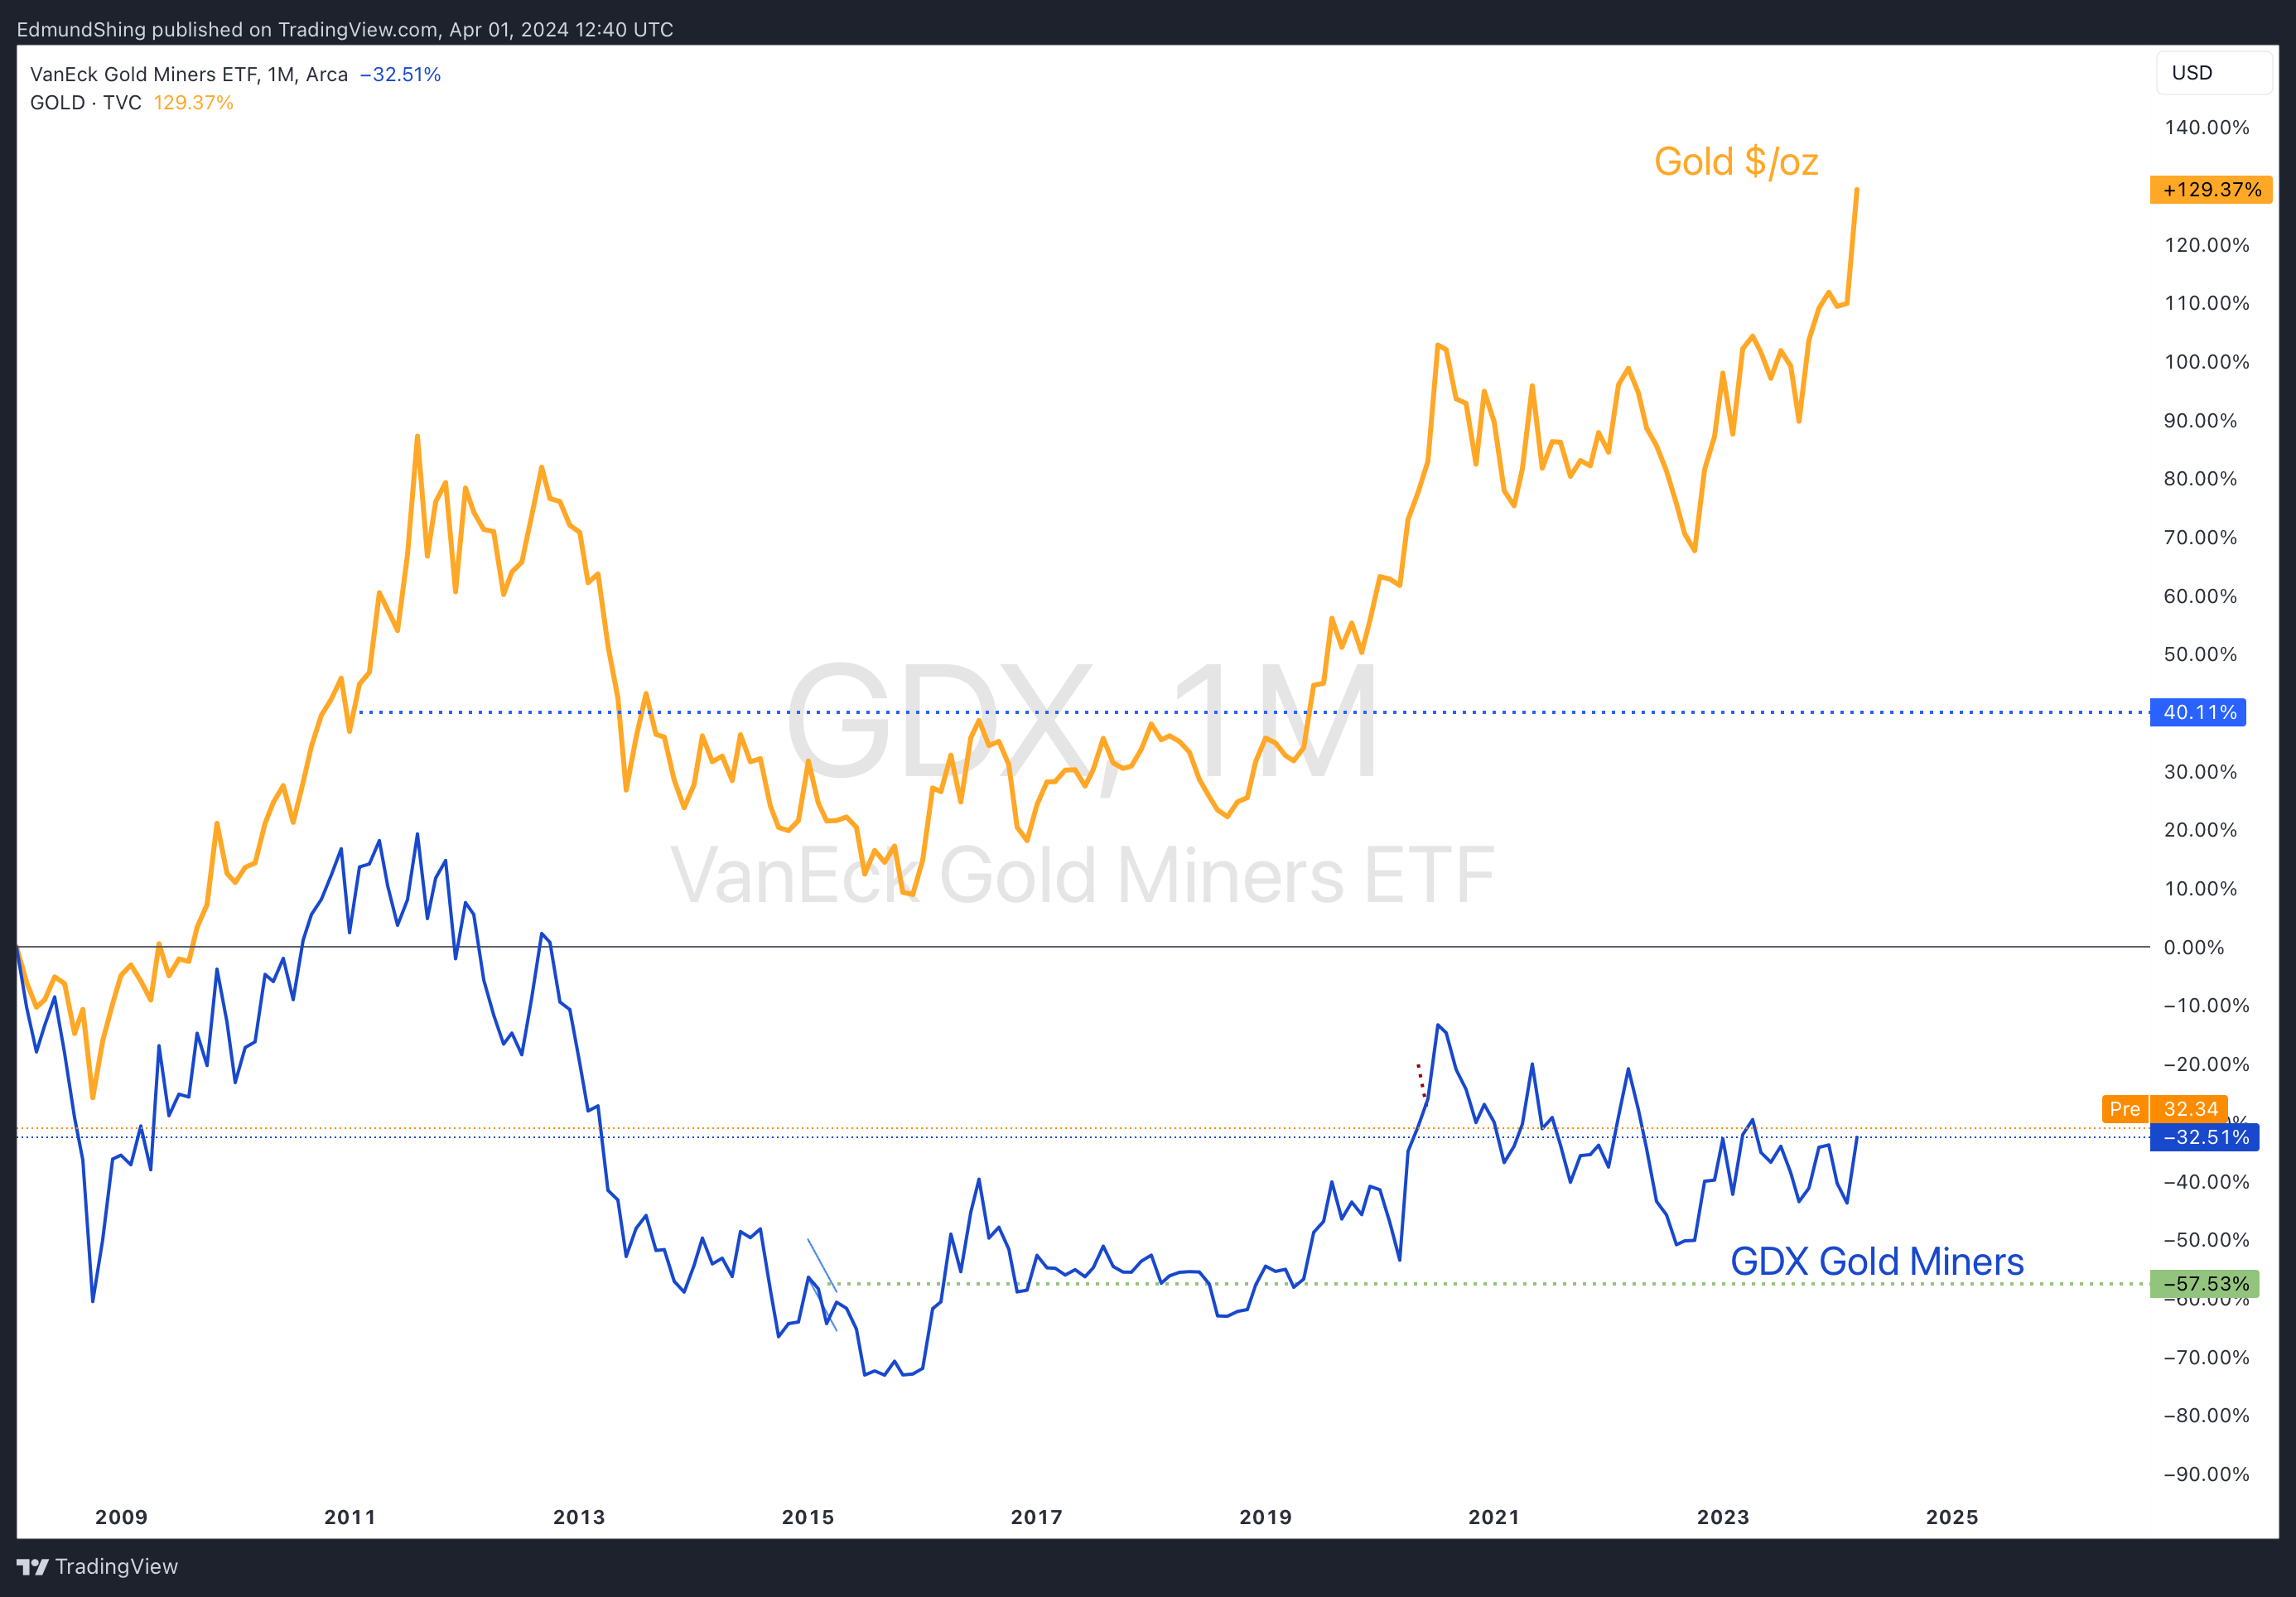
The gold price continues to make a new all time high to over $2,250 per ounce.
Source:TradingView.com
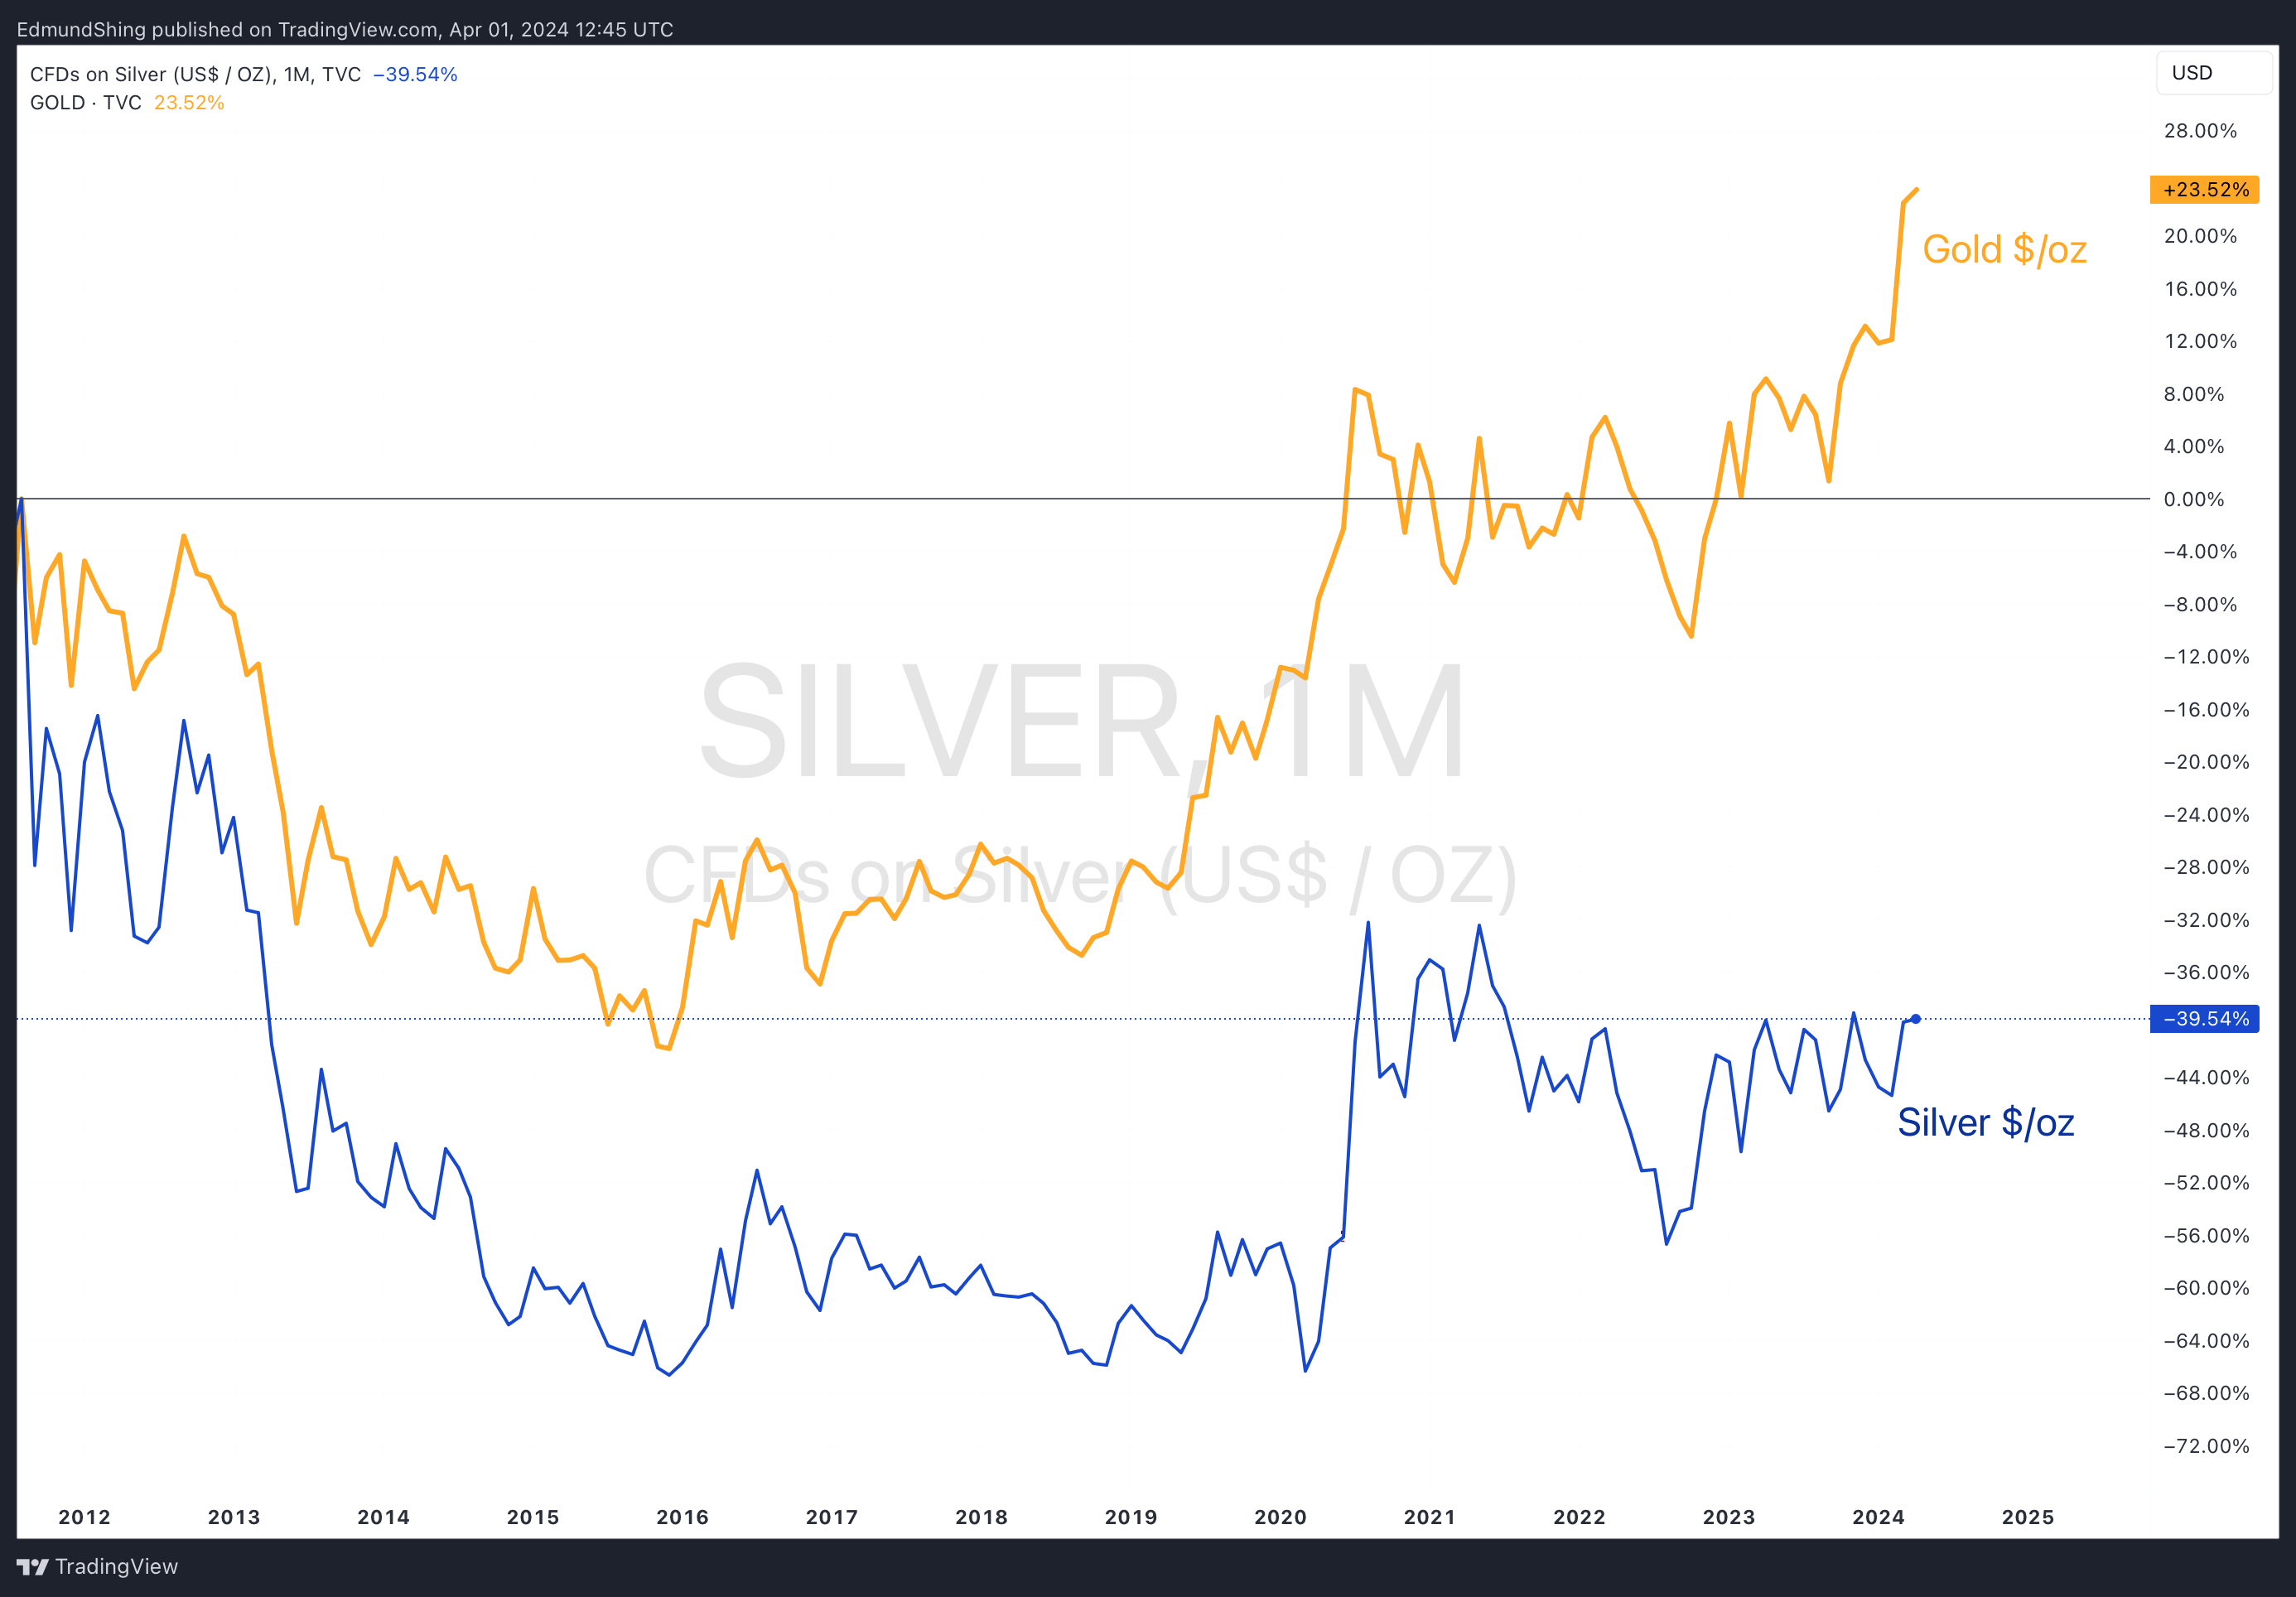
Meanwhile silver, which is also an ancient form of money like gold continues to languish 50% below its all time high reached in 2011 of $50 an ounce today at just over $25 per ounce.
Source: TradingView.com
But there are signs that silver may finally be starting to react to the upwards momentum in the gold price,
Over the very long term, the ratio between the gold and the silver price has been around 67, but has varied enormously around this. It has been as low as 14 times and as high as maybe 120 times. Today it hovers at nearly 90 times, so at the higher end of the ratio, suggesting that silver could have an accelerated catch up to the gold price should gold continue to move higher towards $2,300 per ounce. To give some example, at today's price of $2,250 params and at an average Gold Silver ratio of around 67. This would put silver closer to $33 per ounce as opposed to the current 25 and change.
But it's not only silver that lags the gold price. The share price of gold miners has also dramatically lagged physical gold over the last few years.
This is obvious by looking at the relative performance of the HUI gold miners index against the physical gold price, gold miners have dramatically underperformed gold despite offering a gross profit margin (Taking the spot gold price today of $2,250 an ounce and the all in sustaining cost of between $1,300 and $1,400 per ounce) of around 40%, if not more, which is historically very high.
Nevertheless, gold miners continue to languish and valuations are relatively low by historical standards.
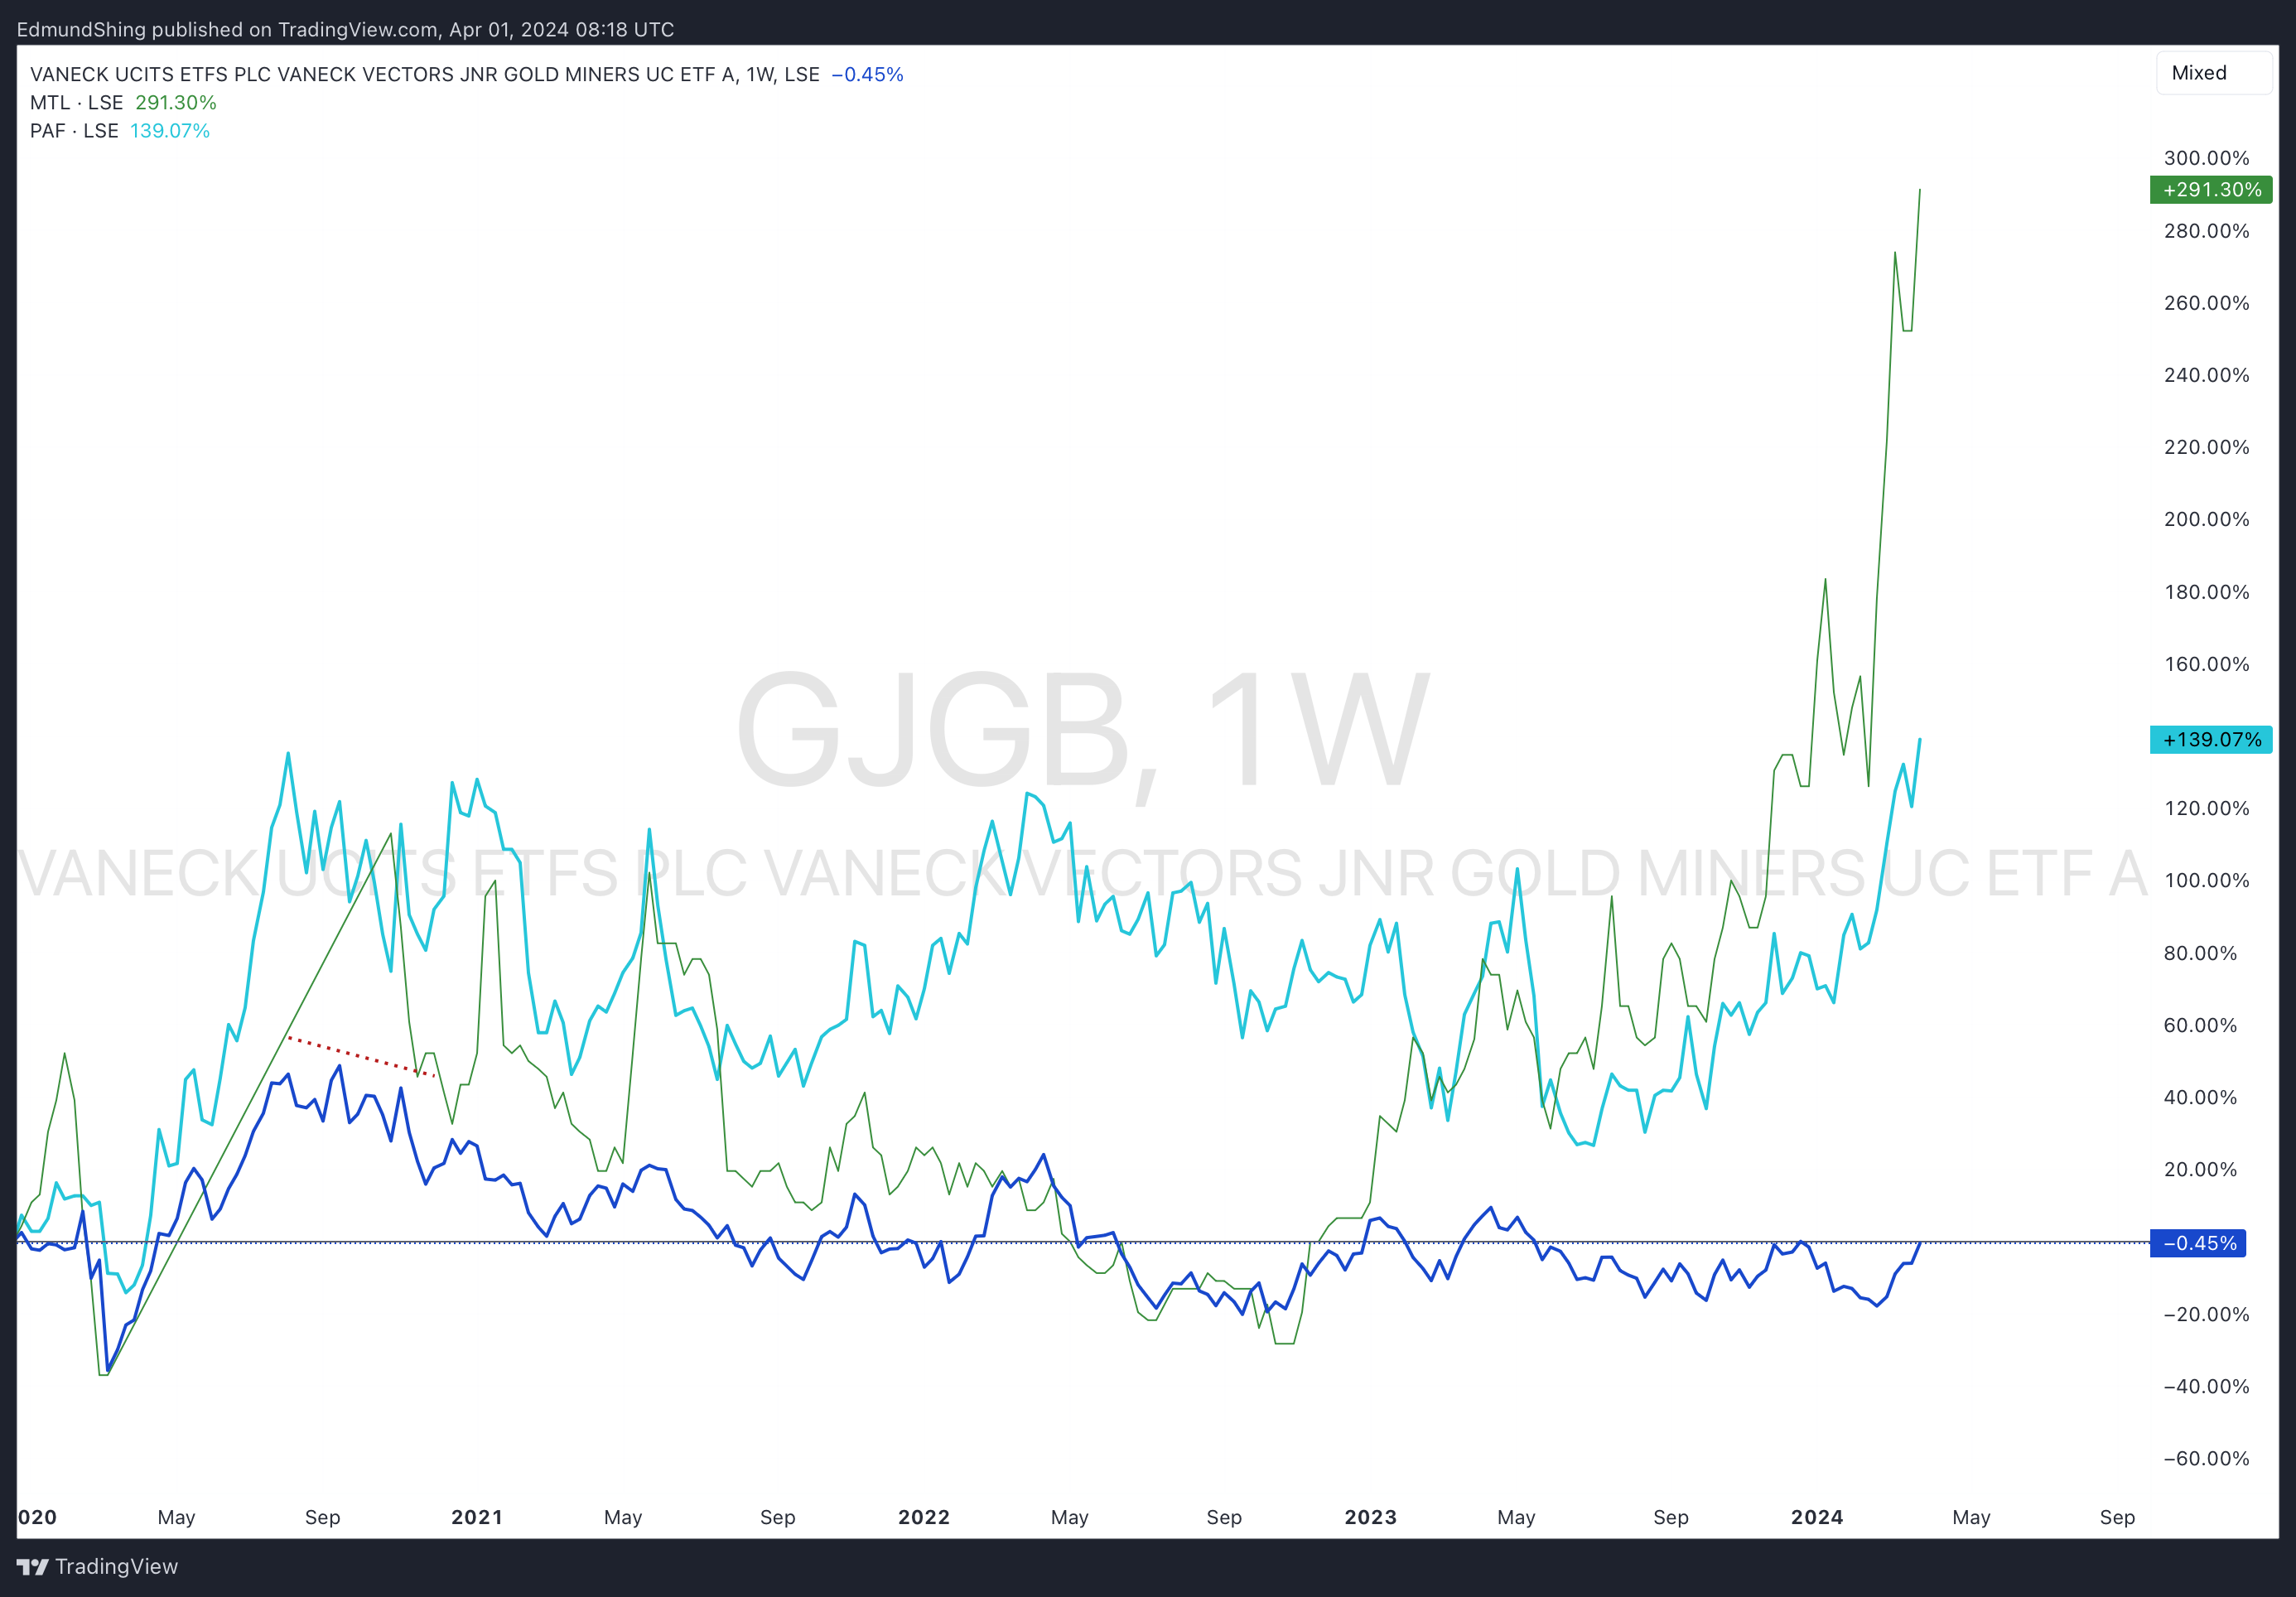
In the UK, there are a number of UK listed gold miners of interest including MTL Metals Exploration and PAF Pan African Resources. Of the UK-listed small cap gold miners, these two exhibit the best earnings and price momentum for now and are clearly very cheap on metrics such as free cash flow yield, prospective P E., They are also relatively cash rich and low or zero debt Thus these are companies that may well benefit from a strong gold price.
Metals `Exploration (green) and Pan African Resources (cyan) lead the Gold Miners index (blue)
There are also silver miners listed in the UK within the large caps, FRES Fresnillo and HOC Hochschild. These have lagged the silver price, which itself then also lags the gold price. Hochschild in particular is also lowly valued on PE and therefore is worthy of further research.
Note that a forthcoming catalyst for the gold price could well be central banks, and in particular the US Federal Reserve beginning to lower benchmark interest rates from June. In fact, the European Central Bank and the Bank of England are also likely to start lowering interest rates by June following the lead of the Swiss National Bank which recently began to cut rates. Traditionally, gold prices performed very well over the last four times that the US Federal Reserve has begun cutting its benchmark interest rate in previous interest rate cycles.
In the meantime, strong demand for physical gold continues to come from central banks and Chinese consumers. Curiously, in spite of the strong momentum in the gold price, Western investors have remained noticeably absent from gold demand up to now, if anything selling into the rally, judging by the constant outflows from physical gold funds and ETFs up to now.
Best
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

12 comments
The Value Gap Between the Gold Price and Gold Miners
The big royalty companies (Franco-Nevada (TSE:FNV) , Wheaton Precious Metals (TSE:WPM) , Royal Gold (NSQ:RGLD) , etc) were the safest place to be in the gold space for the last 4 years. Franco-Nevada (TSE:FNV) oversold recently with the Cobra Panama / First Quantum debacle of course. Sandstorm Gold (TSE:SSL) looks very cheap to me right now...
With all the current fervour around PM miners I think it’s worth highlighting a few salient points that investors must consider to sort the wheat from the chaff:
AISC - All in sustaining costs. Lower the better, feeds into operational leverage and subsequent beta of a particular SP. Life of mine? How big is the deposit? What is the ore grade?
Jurisdiction risk, where are the mines? Some countries are more mining friendly than others. Political risk must be considered here too.
Is the company an Explorer, Developer, Producer, Waste Processor? Only in a mature bull market will explorers take off…
Management, management, management…. Are these guys proven or are they just deal makers?
The best gold miners are not listed in London…
I rate a worthy gold miner as one who admits to having more than ten employees and also pays a dividend.
Add to that one that actually mines gold without having some sort of leach pit fiasco and upsetting the local population !
Inflation-Risk Latecomers Pile Into Silver
"As gold makes new highs, speculators’ net longs in silver are jumping higher."
With gold and silver going straight up there is an obvious play buying miners who typically top a month after the metal index. Silver also lags gold. Not too late to add precious metal miners to your portfolio. Hochschild Mining (LON:HOC) Centamin (LON:CEY) Metals Exploration (LON:MTL) Serabi Gold (LON:SRB) Resolute Mining (LON:RSG) . Take your pick.
PS. Don’t forget the picks and shovel makers. Capital (LON:CAPD) looks woefully undervalued. Had a nice growth story too.
Yeah, but $47m of NAV is an E&D portfolio which really seems to p**s the city off.
Not saying Capital (LON:CAPD) is a bad investment, quite the contrary, but it is not liked. You have to decide whether you can live with that.
I have done OK in a small gold miner- originally Cluff Gold became Amara who were then acquired by Perseus Mining (ASX:PRU) . I have sold a few shares over the years as price doubled but still showing a 500% increase on what is now a tiny investment in cost terms. So pick a good small miner and you can do very well. I was impressed by Algy Cluff back in the 1980's as a young stockbroker- he was a serious player then, although I only bought into Cluff in around 2012.
On a broad front, worth noting VanEck Gold Miners UCITS ETF USD A (LON:GDGB) is up nearly 20% since late Feb so miners certainly seem to be moving.
For info Hochschild Mining (LON:HOC) has just poured its first gold so will increasingly benefit from the price of gold as well as silver.