Market Musings 030123: A better starting point for 2023?

Market Musings 030123:
A better starting point for 2023?
While 2022 has been difficult enough for investors predominantly invested in stocks and shares, spare a thought for so-called conservative investors who were primarily invested in supposedly less volatile bonds.
2022 Bond Breakdown
On the back of a resurgence in long-dormant inflation, US investors in long-term (20 years and longer) US government Treasury bonds lost nearly 30% in value over 2022, even after accounting for interest payments (coupons). Those investing in a US total bond index lost nearly 14% over 2022, the worst such annual return for US government bonds in 100 years.
The worst annual US bond return in 100 years
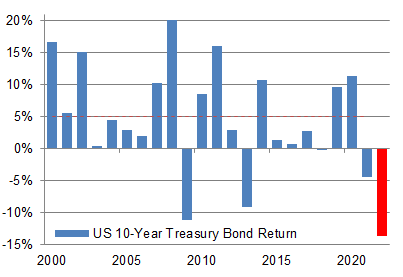
Source: NYU Stern
In the UK, UK government bonds (gilts) have been equally awful for conservative investors, with a typical UK gilt ETF losing 27% of its value (including income) over the year.
2022 has now wiped out more than all of the cumulative positive performance of US and UK government bonds over the last 5 years (since the start of 2018).
It is thus hardly surprising that the combination of poor stock and bond performance combined hsa resulted in the worst performance for a US balanced portfolio (comprised 60% of US stocks and 40% of US bonds) since 1937!
The worst year since 1937 for a US balanced investor
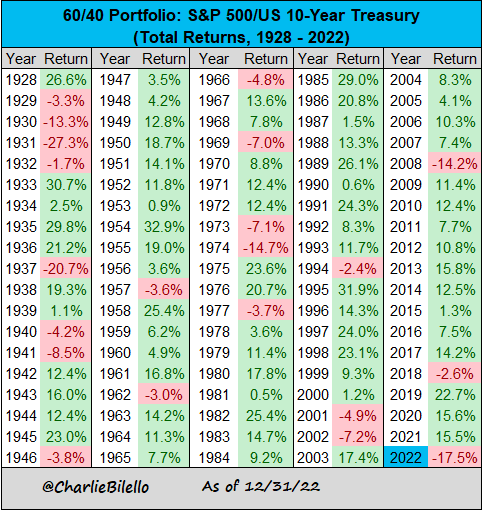
Source: Charlie Bilello via Twitter
Thanks to the more resilient performance of the UK’s FTSE 100 index (indirectly due in part to the weakness of sterling), a similarly composed UK balanced portfolio of 60% FTSE 100 stocks and 40% UK gilts would have returned -11% over 2022, due almost entirely to the sharp drop in bond prices.
A longer term perspective looks healthier
But it pays to look at what preceded a painful 2022 for investors. 2019 to 2021 saw three consecutive years of healthy double-digit gains for US balanced portfolios which had resulted in a cumulative return of +64% for the 3 years to the end of 2021. So even including 2022’s setback, the cumulative 4-year return from 2019 to end-2022 was +35%, equivalent to a compound annual average return of nearly 8% per year.
A UK-based investor who had invested in the MSCI World index (in GBP sterling) would have gained a cumulative 57% from the beginning of 2018 to the end of 2022 (a compound annual average return of 9.4%), even including a 9% loss for 2022.
The point I want to make is that the last 4-5 years have delivered healthy returns in line with or better than long-term annual average returns for stocks and bonds, even including a very poor 2022.
Remember the power of compounding returns over the long term: at 8% per year, £1000 would double to £2000 in just 9 years
Theoretical example of £1000 invested at 8% return per year

Source: Edmund Shing
We should then perhaps view 2022 as a reset to financial markets after a bumper few years, achieved in spite of unprecedented world events such as a worldwide COVID-19 pandemic and widespread lockdowns, plus now the biggest war in Europe since 1945.
A consensus for a poor Q1 2023 for stocks
Glancing over a broad spectrum of year-end outlook reports from both investment banks/brokers and fund management firms points to a consensus that the first quarter of 2023 will likely see stock markets fall on the back of economic recession.
I personally would not put a lot of faith in these short-term predictions for a number of reasons, the most obvious being:
Investment banks were notoriously poor in predicting 2022 stock market returns in their end-2021 outlooks: in the US, they predicted an end-2022 price target for the US S&P 500 index of 5000 or above. In the end, the S&P 500 ended 2022 at 3839, 23% or more below Wall Street’s price targets. So why should they be any better at predicting stock market returns over the next 3 months?
This recession is the most-forecasted recession possibly in history, so it is catching precisely no-one by surprise. If anything, the surprise could be that the world in fat avoids a global recession, and manages to eke out a sluggish but positive rate of economic growth in 2023.
Recency bias is very powerful - that is to say, that even so-called finance professionals have a robust tendency to extrapolate from the recent past into the future. So investment strategists at banks and fund managers are likely basing much of their predictions for 2023 returns on the poor returns experienced in 2022, and then rationalising these somewhat pessimistic predictions on a largely post-hoc basis.
Perhaps I have become too cynical over my long tenure in the finance industry, but I would nbt place any significant value on these “professional” forecaster views given how inaccurate and prone to bias they have been in the past. On our side, the biggest mistake is then to place too much faith on these predictions.
What is working, now?
There are a number of asset classes, investment themes and styles that are working at present which investors can focus on today. In my view, this is a more fruitful endeavour than spending a lot of time gazing into virtual crystal balls to try to divine the direction of stock and bond markets over the next 12 months
OIl & Gas sector: oil and gas producers continue to perform well in spite of the cooling of crude oil and natural gas prices of late. Yes, oil & gas companies may have performed very well in 2022 post February, but remember that they had suffered a relatively poor 10 years leading up to 2022, and remain very cheap in view of the bumper cash flows and dividends that they offer today.
Precious metals: commodity exposure in general has been a poor investment since 2011, but rebounded sharply in 2022. Precious metals as a group generated a 14% return in sterling terms in 2022 led by gold, with platinum also performing strongly and silver now starting to catch up. With the burgeoning weakness in the US dollar and the potential for a commodities supercycle, precious metals and precious metals producers look like a good place to be invested.
Battery metals, specifically lithium and nickel. Lithium prices ended 2022 up 89% on the year, while nickel prices rose 41% over 2022. Stockpiles remain low by historical standards, while demand from electric vehicle production and renewable energy generation and storage should continue to grow quickly in 2023 and beyond. There is little obvious new production of these metals in the form of new mines and refining capacity, suggesting a positive outlook for producers of these two metals.
Healthcare sector: pharmaceutical stocks are well-oriented, have performed strongly over the long term and continue to be driven by the ageing demographic trend and new blockbuster drug launches for a number of cancers and age-related diseases.
Europe Value: despite the spectre of an energy crisis and recession hanging over Europe, European value stocks are performing surprisingly well, and continue to offer excellent value in terms of P/E and dividend yields (relative to history). Interestingly, the MSCI Europe Value index has a surprisingly high 14% exposure to the Healthcare sector and a 31% exposure tio UK stocks. So it is not just commodities exposure that is fuelling the performance of this value investment style.
Nickel continues to ride strong battery demand wave

Source: kitco.com
Strong performance of Europe Value ETF since 2020

Source: tradingview.com
Conclusion: Funds to consider
Energy exposure: BERI Blackrock Energy and Resources Income Trust, with 38% exposure to energy producers, a 4% discount to NAV and a 3.3% dividend yield.
Nickel: NICK Wisdomtree Nickel ETC giving exposure to physical nickel futures contracts
Healthcare: PCGH Polar Capital Global Healthcare Trust, with a 5% discount to NAV (for the ordinary shares) and exposure largely to US healthcare stocks (60%)
Have a great week,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

11 comments
Great article, thanks Ed, Ed mentions an ETF in a previous article VanEck Ms Developed markets div lead UCTIS ETF TDGB which I believe has oil & gas and healthcare amongst others sectors. I am thinking about a closer look. Ia anyone currently invested or have a view?
Great article Ed I wonder if you or anyone else could give me a steer on investment trusts or etf's that invest in ten years plus goverment bonds or the strategic bond sector, also with etf's do you benefit from the yield same as you would in funds and if I have it correct etf's are not covered by any compensation scheme in the event of fraud unlike funds which are covered for 85k ?
Thanks Andy
Hi Andy
I have exposure to Bonds through my Vanguard SIPP they offer various products for example Vanguard U.K. Gilt UCITS ETF GBP Dis (LON:VGOV) or Vanguard USD Em Mkts Govt Bd UCITS ETF USD Dis (LON:VEMT) when you go through their fact sheets they will give you the yield data against the current market price, and also the holdings within there.
Not sure which provider you have (SIPP/ISA/Share dealer) or what products they offer, there are obviously a lot of other players in the market Wisdomtree, Blackrock etcetera so a bit of digging is required to work out the right product for you and of course the fee structure and purchase.
Good luck
Tommy
Hi all, there's something about bonds that I don't quite understand.
The bond value goes down when yields go up... But does that impact current bond holders, or only instruments which track bond value?
E.g. If I purchase a 1-year bond for £100, and the value drops to £90 at the end of the year... do I get my £100 back, or do I get £90 back (plus, of course, any interest paid on the bond)?
If you hold to bond maturity you get £100 back plus interest per the interest payment schedule (provided, of course, there hasn't been a default).
Funds of bonds tend to follow the price of bonds i.e. as yields go up the price of the fund falls.
Clear, thank you!
Hi Edmund,
Excellent article. The 60/40 portfolio was a real eye opener demonstrating that 2022 was in the same league as years in the Great Depression, run up to and in WW2, the oil crisis/inflation/industrial relations problems of the 1970s and the GFC of 2008.
I agree with your comments on 'what is working now'. My investments in oil & gas, precious metals, mining and healthcare have kept my overall portfolio loss for the year to around 8%.Unfortunately I have significant holdings in alternative asset investment trusts and quite a few managed equity funds which have been an unmitigated disaster. When & if the market recovers I will be considering going passive in many areas as equivalent ETFS have outperformed fund managers in many cases (what do fund mangers get paid for!?)
You commented "There is little obvious new production of these metals in the form of new mines and refining capacity, suggesting a positive outlook for producers of these two metals". However, nobody seems to have told the stock price of one of the world's leading producers of Lithium, Albemarle (NYQ:ALB). The stock price peaked at $325 in mid November only to collapse to the current level of $210 today! Similarly not all is well in the Health care sector as my holding in Coloplast A/S (CPH:COLO B) fell by 26% during 2022 albeit after a very strong run over the past few years. I know these are individual cases and there may be specific reasons for the declines but it perhaps demonstrates individual stock picking in these generally positive sectors can be problematic (perhaps makes the case for diversification through ETFs!)
Thanks for another great article Edmund. I particularly liked your section on “Consensus for a poor Q1 2023 for stocks” and agree with all of it.
Don’t agree though with your “Commodity exposure has been a poor investment since 2011.” It was from 2011 to 2015 when there was an extreme Mining Sector bear market while the markets in general were often doing well. That bear market was so extreme that even the big Miners like Anglo American (LON:AAL) fell up to 90%. And they fell way below the 2008 Banking Crisis lows too.
BUT since the Mining Sector bottomed at the end of 2015 there have been some extraordinary gains (albeit with a temporary big Covid dip in 2020) even for the big FTSE100 shares.
I bought Mining Investment Trusts CQS Natural Resources Growth and Income (LON:CYN) Blackrock World Mining Trust (LON:BRWM) and Blackrock Energy and Resources Income Trust (LON:BERI) too early in 2015 and Rio Tinto (LON:RIO) £KAZ Glencore (LON:GLEN) and others . Once they recovered from even further drops, the gains since early 2016 have turbo charged our portfolios.
e.g Glencore (LON:GLEN) fell to 80p in 2015 and is now over £33. Rio Tinto (LON:RIO) to £18 and now £58 AAL an astonishing £2.20 and now £34 £KAZ to just 80p and went to £10 before falling to a bid. The 3 Trusts CQS Natural Resources Growth and Income (LON:CYN) from 78p to £2.15 today, BRWM from £1.80 to £7 today and Blackrock Energy and Resources Income Trust (LON:BERI) from 47p to 133p.
AND dividend yields have been extraordinarily high too. E.g RiO dividend last year was 20% and this year could well be over 10% again with likely further specials. And Glencore (LON:GLEN) even now is on a PE if 6 and 8% dividend excluding specials. Thee big Miners have switched from big Buybacks £40 billion or so for RIO) (followed by very big share price falls) to paying big special dividends, which unlike buybacks, always give a definite and genuine financial reward.
I do agree that Mining Sector still looks good.
What IS such a shame is that on Stockopedia there is massive (and fully deserved bearing in mind the depth and quality of Paul and Graham’s analysis) interest in Small Companies , but little interest in equally attractive sectors like Mining and Investment Trusts etc. And some superb articles, including some of yours Edmund get far less follow up than they merit.
Couldn't agree more on the comment about small companies.
It really is time there was a large cap value report, a mining report, etc. No need for it to be daily or even weekly, but a broader spread of topics feels overdue.
Thanks AJB.
Obviously I agree, but lack of subscriber interest except for small Companies is so low. No need to look beyond this thread to see that. Just 7 replies in 3 days, and no real follow up to Edmund’s excellent article and Edmund himself hasn’t responded to any of those posts either.
My post intended to tinitiate further discussion of Mining sector has seen no comment at all. . I can’t see it changing unfortunately.
Happy new year Edmund
Thanks for this masterpiece of first essay of the year.
For anyone interested in short term- less than a year-performance, this is the best I have read this year!
I am happy to follow this theme with investment in BRWM and PCGH.
Thank you for the suggestion.