Market Musings 051123: Trend change in long-term rates?

Market Musings 051123: Trend change in long-term rates?
Summary:
Long-term interest rates take a tumble
What if, over the next six months, inflation rates continue to fall faster than expected?
Europe: the 3 leading sectors since start-2022
Podcast this week:
Five surprising facts about Gold
In this podcast, Edmund Shing analyses the recent highs in gold and shares five surprising facts.
How much gold is in circulation today?
What are the main uses?
Who has been buying gold lately?
How much more gold is mined every year?
Do people tend to buy gold via funds and ETFs?
Long-term interest rates take a tumble
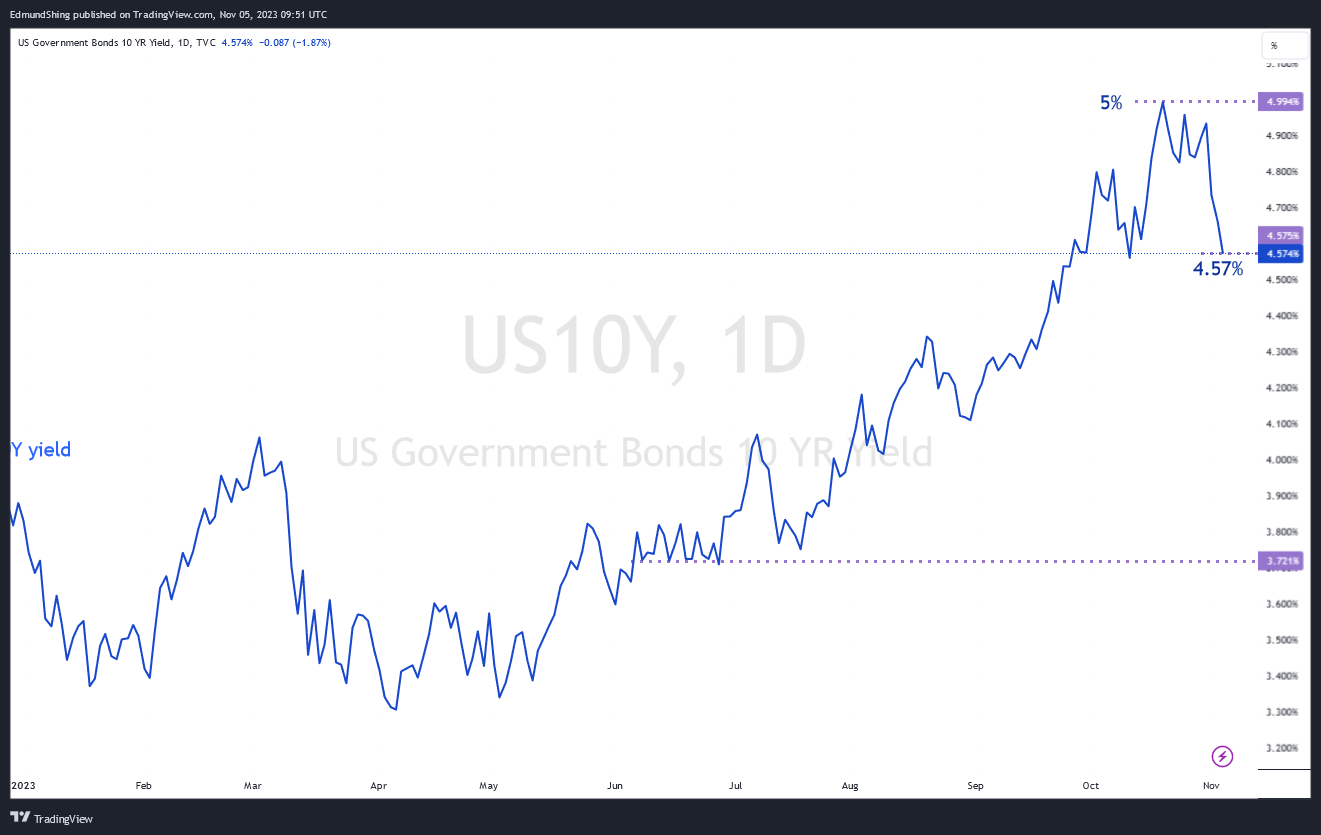
Following on from last week's article, the US 10 year bond yield (“the one rate to rule them all”) fell sharply towards 4.5% on Friday. In total this long term interest rate has therefore fallen half a percent from the 5% peak it reached recently.
US 10-year Treasury bond yield drops nearly 0.5% from 5%
Source: tradingview.com
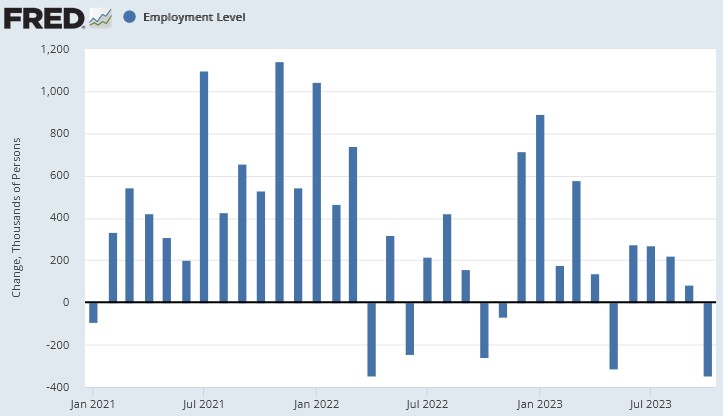
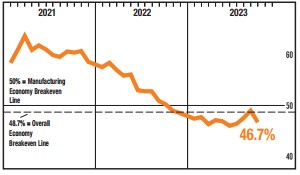
The drivers of this fall in bond yield were effectively weaker economic activity in the US, underlined on Friday by relatively weak employment reports, which followed on from a weak ISM manufacturing Survey Report for the month of November.
US employment survey: -348,000 employed in October
Source: St Louis Fed
US ISM manufacturing survey in contraction territory (< 50)
Source: ISM
At the same time, inflation indicators continue to point lower particularly in the form of lower gasoline prices as well as weaker rents, falling housing activity including prices and also evidence that wage inflation continues to moderate.
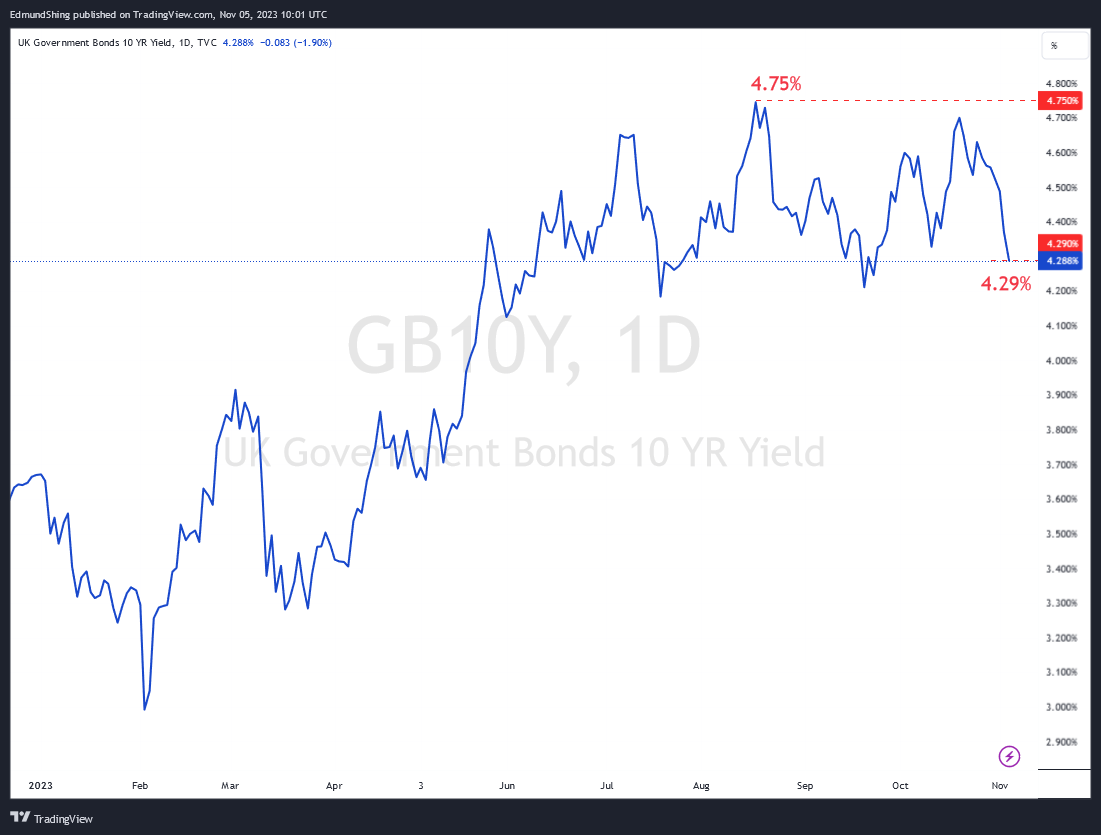
Long term interest rates around the world have also followed suit, notably in Europe and the UK, where the UK 10 year gilt yield and the German 10 year bond yield have both also declined, taking their lead from events in the US.
US 10-year bond yield: down to 4.57% on Friday
Source: tradingview.com
Economic activity has already slowed dramatically in both Europe and the UK. And indeed, the most recent inflation data seems to be slowing even more sharply than consensus expectations had predicted.
Dutch inflation slips below zero in October

Source: tradingeconomics.com
Frankly, I believe that the UK and Europe are pretty much in recession right now, as defined by a general weakening of economic activity, with demand weaker as a result. So it is hardly surprising that inflation continues to moderate
What if, over the next six months, inflation rates continue to fall faster than expected?
This could suggest that long term interest rates could fall further. If the US 10 year bond yield were to fall to lower than today's level of 4.5%, what assets would benefit in particular?
In many ways, those assets are exactly the same assets that have suffered as long term interest rates have shot up over the last couple of years.
Property and housing is one area that could find some respite in lower long-term interest rates. Both real estate investment trusts or so called REITs have been hammered over the last 12 months as interest rates have shot up.
Euro, UK REITs start to recover after losing nearly 50% since 2022

Source: tradingview.com
Equally, house building stocks have suffered as housing activity has collapsed on the back of much higher mortgage rates in the US and the UK, for example.
UK, US house building stocks start to recover too

Source: tradingeconomics.com
Infrastructure is a third area which relies a lot on long term debt financing and therefore which has suffered from the sharp hike in these long term interest rates i.e. the cost of financing of these long term infrastructure projects. Lower financing costs should therefore be better for infrastructure prices.
Infrastructure is inversely correlated with long-term interest rates

Source: tradingview.com
One sector which may be overlooked at the moment, but which over time is sensitive to the level of long term interest rates is Utilities.
Companies for instance provide water supply, electricity and natural gas to households and industry. Lower long term interest rates could be a boon to the utility sector. This is a sector with predictable revenues and high levels of debt.
Utilities price increases are usually limited by local authorities or governments by law on the one hand, but need to continue to make infrastructure investments over time on the other, in renewable energy or in improving the water pipe infrastructure to reduce leaks for instance. All of this is related to the cost of financing over the long haul, as they have high levels of debt to help finance these long-term investments backed by dependable revenues.
Utilities are sensitive to long-term rates, and are generally defensive

Source: tradingview.com
I favour Insurance, Euro Banks, Oil & Gas…
Overall, I remain optimistic of a bounce in both bond and stock markets to year end as inflation pressures continue to ease, and hopefully long-term rates also continue to ease lower.
In Europe, 3 of my favoured sectors that should benefit from a stock market bounce are:
Insurance, Eurozone Banks and Oil & Gas.
Europe Insurance, Oil & Gas, Euro Banks have led since start-2022

Source: tradingview.com
Have a great week,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

1 comment
Edmund, thanks for the article. These musings on long term interest rates are really appreciated while the direction is so unclear.