Market Musings 060925: Bad employment news is good stock market news

Market Musings 060925: Bad employment news is good stock market news
Podcast this week:
Investment Strategy Podcast: The stock market: breakouts galore!
(click on title to listen)
Investment Strategy Focus: Summary
Tighter US fiscal policy balanced by looser monetary stance. US tariffs are a tax principally on US households and businesses, thereby slowing growth. Lower interest rates should partially offset this drag. But US corporate profit margins are at risk and could prompt cost-cutting actions. World ex-US stocks have maintained their 2025 outperformance at +10% versus the S&P 500.
Improving Euro activity implies an ECB now on hold. Improving manufacturing activity, positive loan growth and easing energy costs support modest eurozone growth, with the impact from defence & infrastructure spending yet to materialise. We now expect no further ECB rate cuts, with the deposit rate maintained at 2%.
No big shift in bond yields, and credit spreads remain tight. The US 10-year Treasury yield remains at around our 12-month target, i.e. at 4.3%, while eurozone sovereign yields creep higher. Investment grade credit spreads remain at historic lows, offering few compelling fixed income opportunities to investors at present.
New multi-year highs in multiple stock markets around the globe. The MSCI World ex- US index hit new highs in August, led by Japan, Canada, the UK and Emerging Markets ex-China. We continue to prefer exposure to the UK, Japan, China and South Korea. We also like eurozone mid- and small-cap exposure given the improving domestic economic momentum.
No strategic metals, no technology: strategic metals are essential for creating tools for technological progress. Their supply can be at risk due to scarcity and geopolitics, when global demand increases. We favour exposure to copper, silver and rare earth metals via investment in physical metals and via miners.
Stock markets shrug off a weak US employment picture
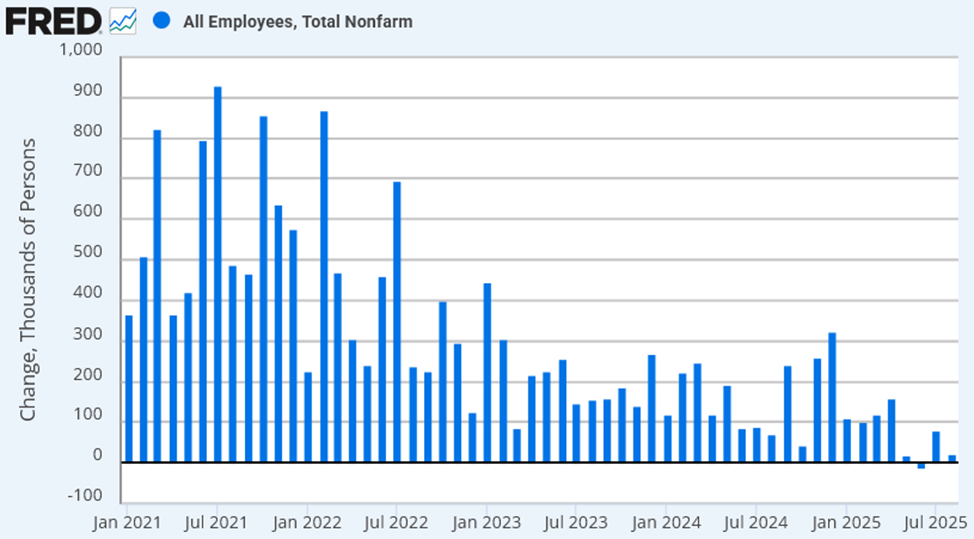
Friday’s US nonfarm payrolls were undoubtedly poor, with just 22,000 jobs added in August.
This represents a sharp slowdown in employment hiring from previous months.
Recall that this year’s nonfarm payroll data have already been revised dramatically lower recently. Another revision lower is likely to occur on September 9, making current trends likely look even weaker.
US nonfarm payroll additions decline to almost nothing
Source: St Louis Fed
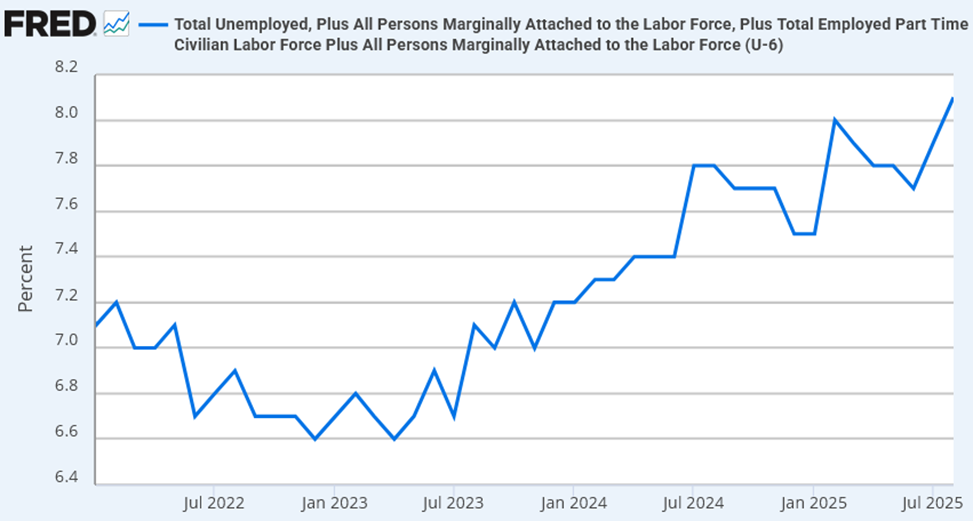
While the official US unemployment rate remains low by historical standards at 4.3%, note that the rate of un- plus under-employment (including those working part-time but who would like to work full-time) continues to rise, now to 8.1%. This underlines the continued deterioration in the US labour market and gives the US Federal Reserve good enough reason to cut their Fed Funds benchmark interest rate this month and at least once more later this year.
US under-employment rate has risen 1.5% since mid-2023
Source: St Louis Fed
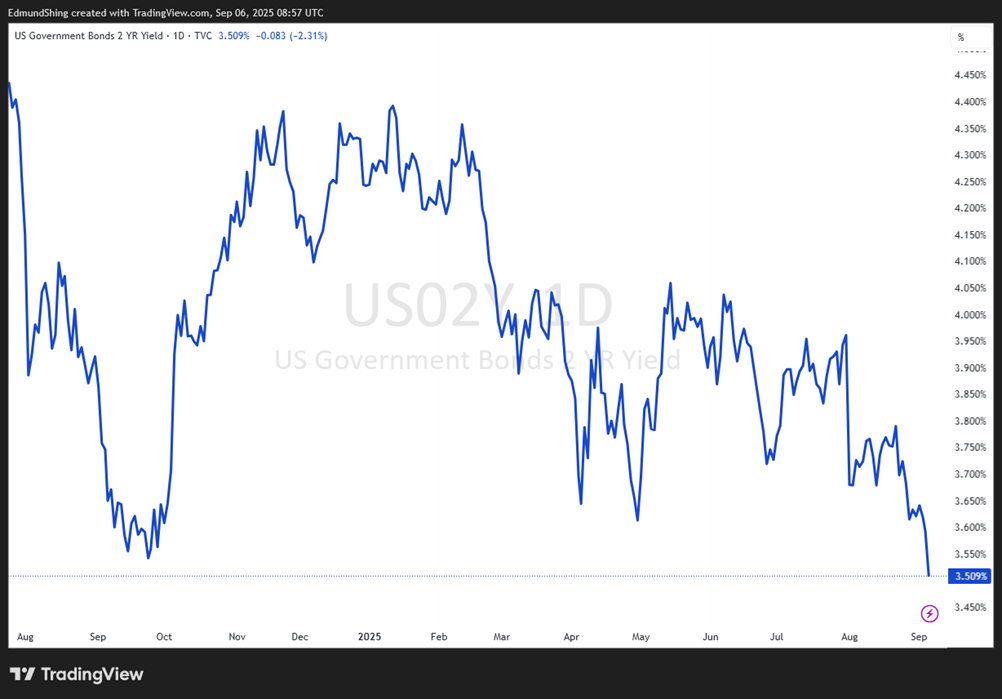
The 2-year US Treasury bond yield has moved lower to 3.5%, reflecting the higher likelihood of a lower Fed Funds interest rate into 2026.
President Trump should get his wish of lower interest rates soon
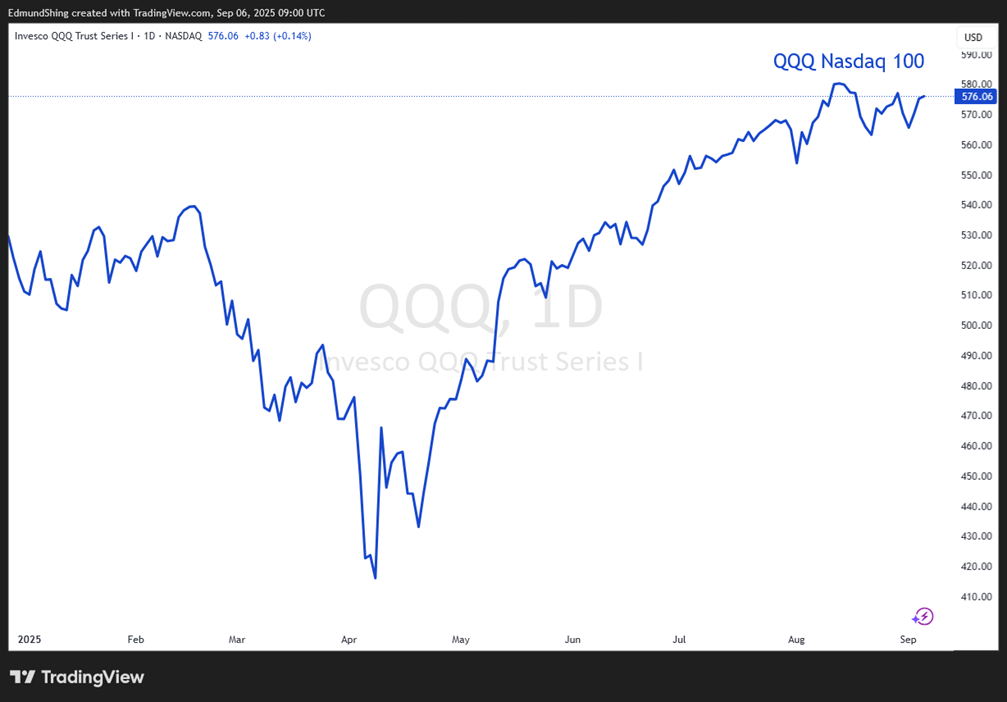
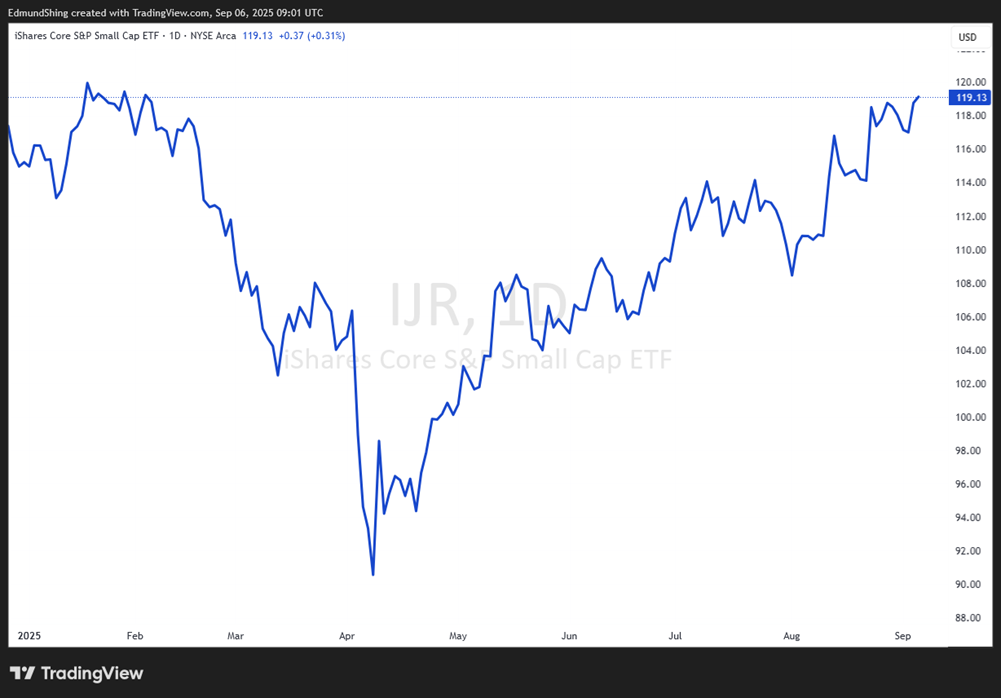
Judging by the reaction of the US stock market on Friday, investors are more cheered by the prospects of lower interest rates than they are worried by prospective weakness in the economy. The tech-focused Nasdaq 100 index managed to eke out a gain, as did US small-cap stocks. Small-caps maintain their pattern of outperformance against large-caps that they established in August.
Nasdaq 100 rose on Friday, still consolidating
US small-caps continue their ascent
Did you know that over the last 5 years, US small-cap value stocks have actually beaten the S&P 500?
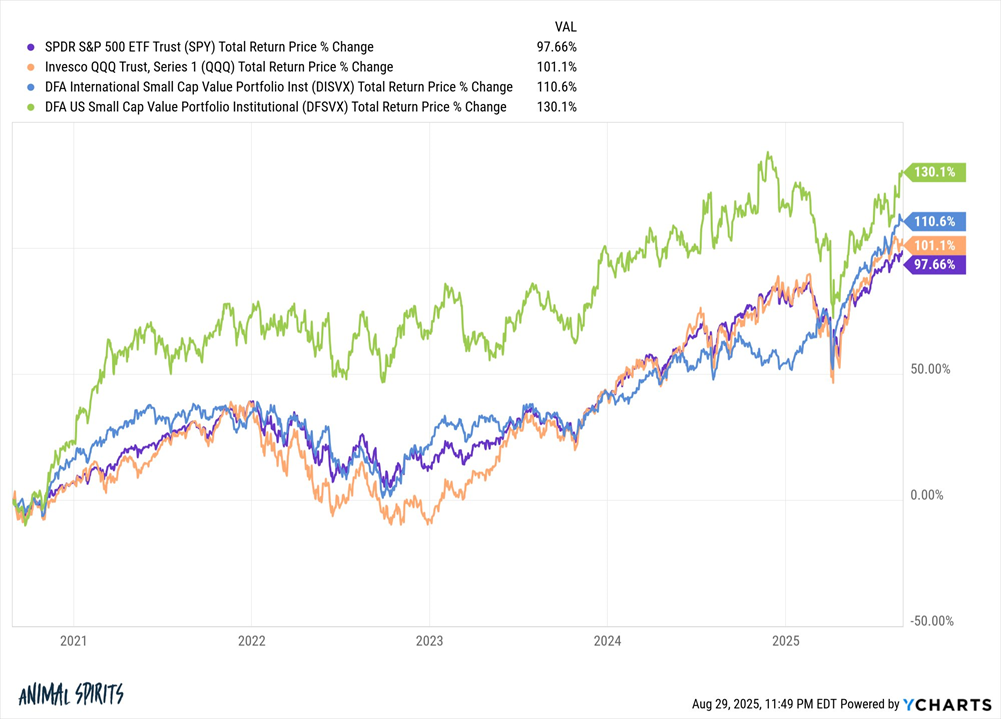
Source: Ben Carlson, YCharts
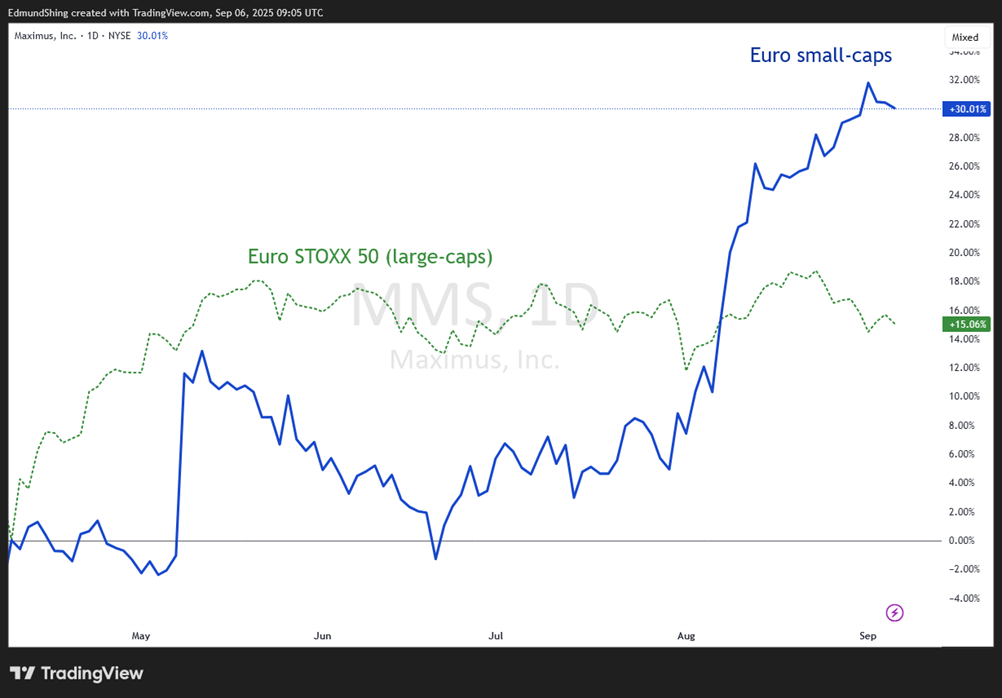
In Europe, small-caps also continue to beat large-caps as they have done since the April low…
European small-caps maintain their August surge
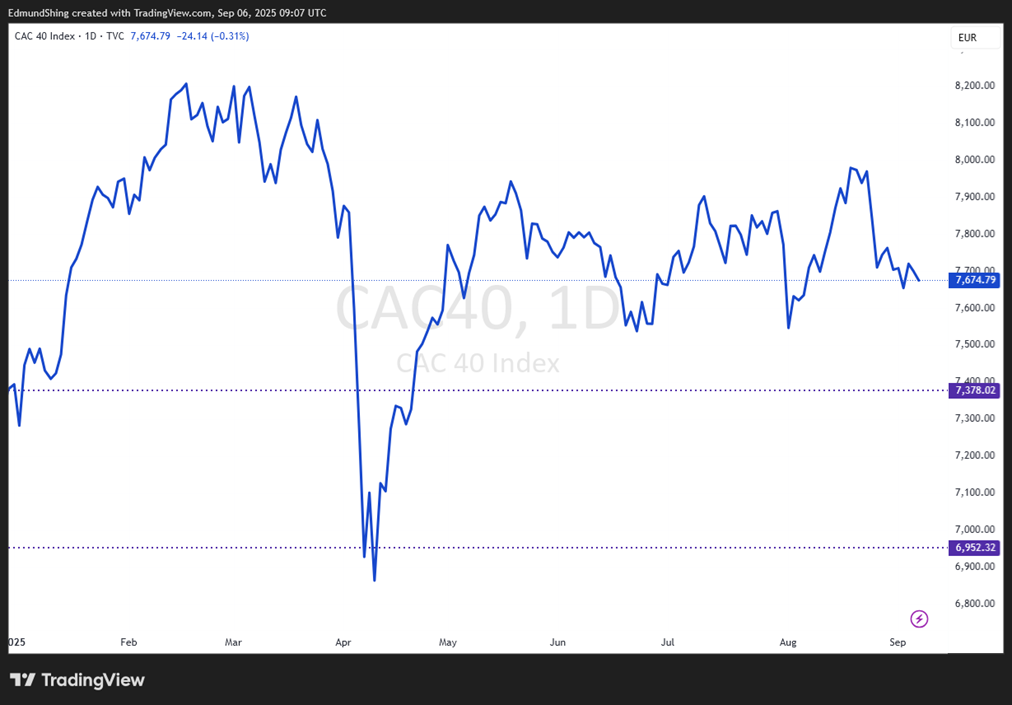
French stocks weigh heavily on the Euro STOXX 50 due to ongoing political uncertainty, with the CAC-40 index trading sideways since May.
French CAC 40 index suffers under a cloud of political uncertainty
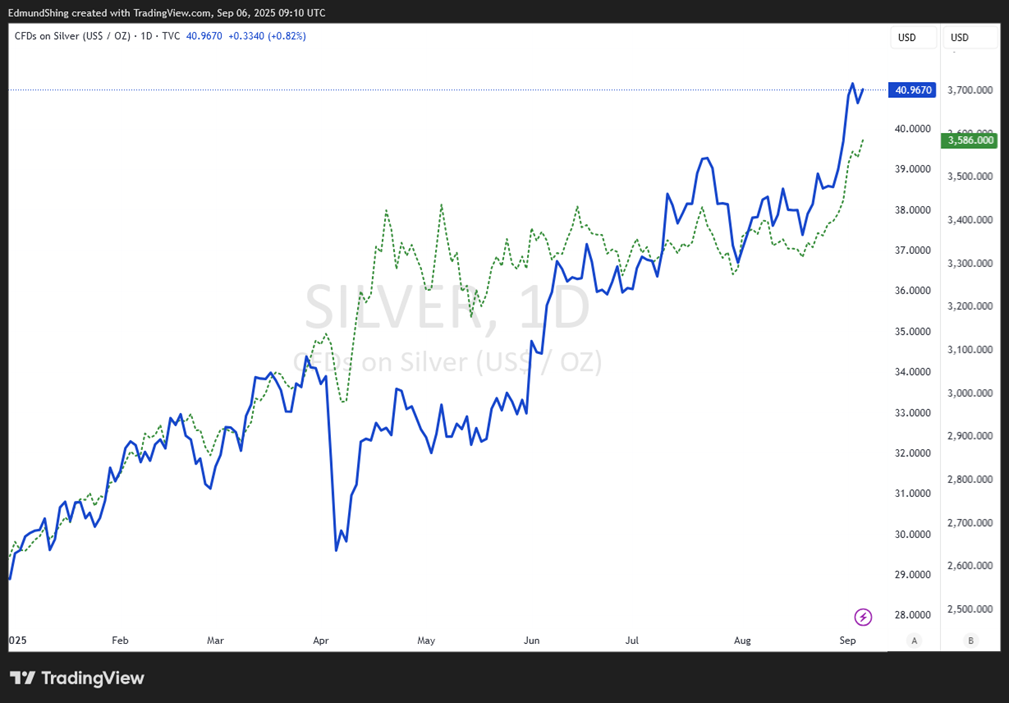
Gold and silver continue their dizzying ascent, with silver broaching the $41/ounce level this week. The $50 all-time high now seems within reach.
No stopping the gold and silver train
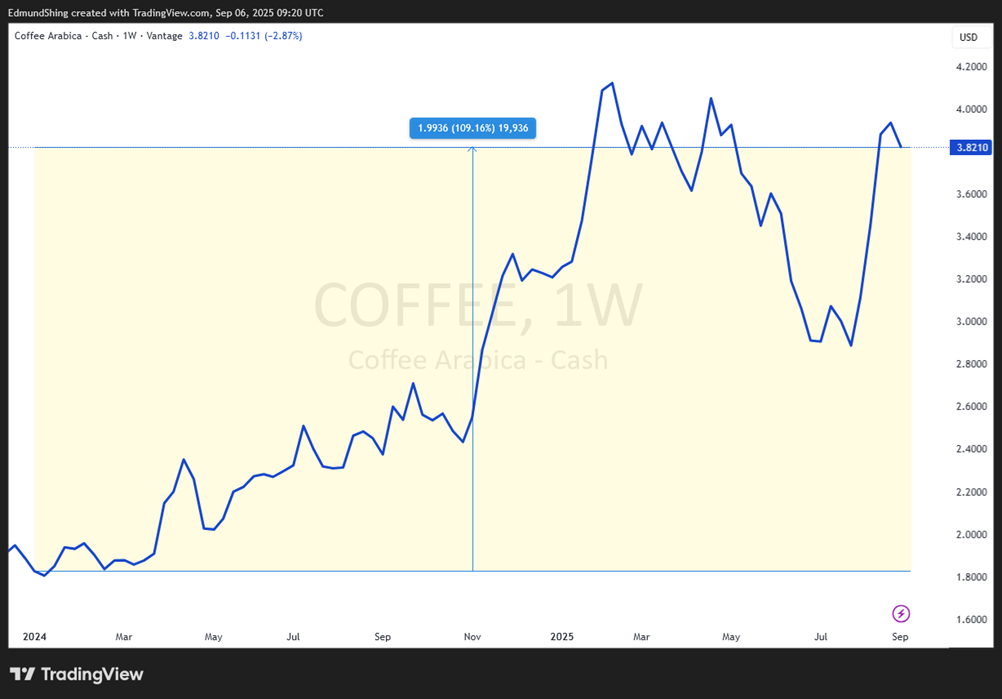
Another commodity that has quietly established a huge upswing in price is one that will impact many of you - coffee. The price of arabica coffee (the good stuff) has surged once again in August, leaving the coffee futures price over 100% higher now (in $) than at the start of 2024. And yes, I have seen the impact of this already in supermarket coffee prices, but they are likely to rise even further now.
Arabica coffee prices on the rise again
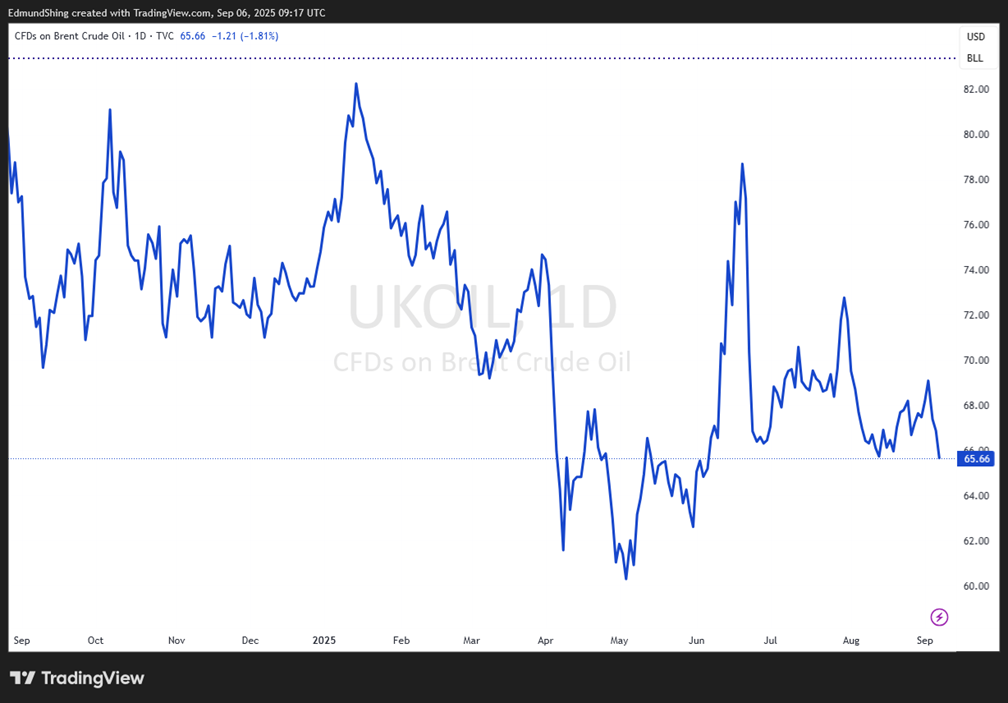
But it is not all good news in the commodity sector. With crude oil prices sinking once again as OPEC+ members prepare to increase oil production quotas once again, we should see further good news for consumers and companies from lower energy costs in future months.
Brent crude oil price sinks, over 10% lower than a year ago
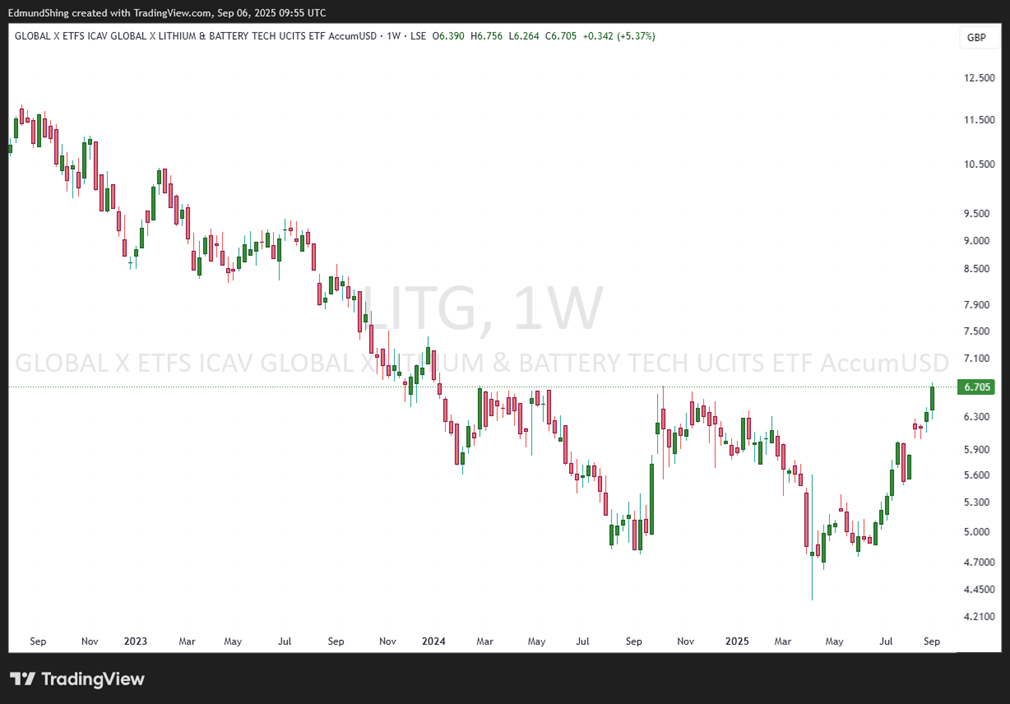
Lithium and Batteries continue to look good
Good luck for the coming week,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Some wear Rolex Submariners others wear a gold braided tie. I have a nice yellow one from Jermyn Street from 30 years ago but just silk and the watch is a cellphone.
FX fees is a good heads up on traders. I have a USD IKBR account but if the USD falls then my investments need to keep up and better those falls.
Agree China seems a contrarian play but difficult to be involved if live in the UK. Is there a Dragon ETF.
always informative articles thanks
The melt up continues.