Market Musings 070123: Off to a good start

Market Musings 070123:
Off to a good start
So 2023 starts well for stock market investors after a terrible 2022
Weekly Podcast - 2022: Annus horribilis
In this podcast, Edmund Shing discusses the link between the unprecedented events in 2022 and the difficulties in financial markets.
1) What was the main trigger of the annus horribilis for financial markets?
2) Why does unexpected inflation cause so many problems in financial markets?
3) How bad was bad last year?
4) What were the challenges for central banks?
5) “Things can only get better”: is there hope for 2023?
Summary
Stock, bond markets benefit from weaker inflation prints
Weaker employment, wage momentum helps
World ex US stock markets generally in rising trends, above 200-day moving average
Emerging Markets back in focus: Hong Kong/China, Mexico, Indonesia
Sectors with strong momentum: European/UK Banks, Insurance, Gold and Copper Mining, US and European Industrials
How persistent can the post-2022 rally be?
Can this continue? In my view the key factor to watch at the moment inflation and associated wage growth in the US
inflation rates are clearly falling from admittedly very high levels, both in the US which has been happening for some time incidentally, but now also in the Eurozone.
Spanish inflation falls quickly Eurozone to follow

Source: Steno Research Bloomberg
Spanish inflation seems to lead Eurozone inflation by two months. I note from the graph above h that Spanish inflation has started to fall really quite sharply over the last couple of months. This suggests that eurozone inflation should follow suit in the very near term.
Friday’s good news on the US wage, employment front
In addition, the second associated factor to inflation is of course, wage growth. Here again, we are seeing incrementally better news in the US.
The first data point to note is that average hourly earnings growth, which is one measure of wage growth, has been steadily declining from its highs. Yes, it still registers just under 5%. Which is of course uncomfortably high for the US Federal Reserve. But it is falling and consistently.
US average hourly earnings continues to ease
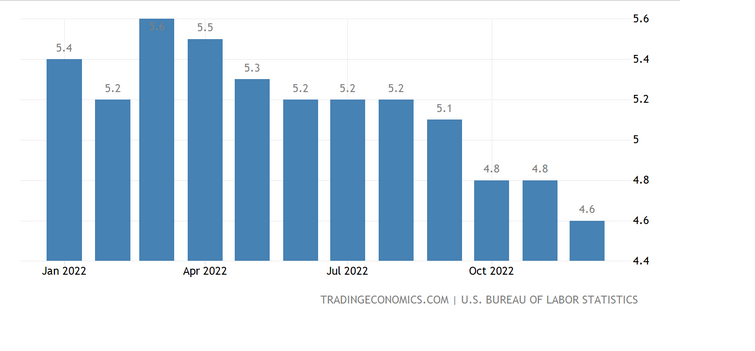
Source: Tradingeconomics.com
I also would expect European wage growth to moderate for similar reasons. As inflation moderates, the pressure for huge salary rises should also moderate and on top of that, do not forget the effect of a weaker economy on weaker employment growth and potentially rising unemployment.
Weaker wage momentum incoming
This factor will also weigh on wage growth because inevitably at some point people's preoccupations will turn from demanding huge salary increases to rather just preserving their jobs in the face of rising redundancies.
This is not so evident yet in either the US or Europe but I believe it's coming, with focus on certain employment heavy industries that are already experiencing weakening activity such as housing and construction.
Weaker US services reading on Friday
An associated data point which was interesting to observe in the US was the ISM services PMI survey. In particular, not only the fact that the headline services index fell below 50, suggesting that the service sector of the US economy is contracting - showing negative growth for the first time in many many months.
US services sector no longer growing

Source: ISM
But also that the employment subcomponent of this services PMI also fell below 50, suggesting contracting employment trends in US services for the first time in many, many months. Given that employment is disproportionately heavy in the services sector in the US, and that the services sector in the US represents roughly two thirds of the US economy, this is thus a big deal.
It suggests that in the months ahead, wage growth pressures should continue to ease and with that, the pressures on inflation should continue to ease.
All of which suggests that central banks will be under less pressure to raise interest rates in future months than they have been in the last few months. This is true not only in the US but also in Europe, for the ECB, the European Central Bank and also the BoE the Bank of England.
So in prospect, what do we have? I think we have the prospect of sharply falling inflation rates in the US, EU and Europe over the next three to six months at least, on the back of:
lower goods prices,
weakening employment trends, and
lower energy prices, plus
a weakening housing sector.
I would expect growth to remain weak: both industrial growth and of course consumption growth.
But I think that as central banks look to stop raising interest rates potentially in the first quarter of this year, that some of the pressure on the economy will ease not only from the inflation front, but also from the interest rate front.
Incidentally, if we look at long term interest rates, i.e. bond yields, they are cooling down on the back of lower US wage growth and the weaker ISM services PMI reading.
Lower long-term interest rates support PEs
The US 10 year Treasury yield, the benchmark in the US, is pulling back towards 3.5%.
This is pulling down the UK 10 year gilt yield at I think 3.7% and also Eurozone bond yields - Germany's 10 year bond yield is about 2.3%.
10-year bond yields all ease lower

Source: tradingview.com
Remember, lower long term bond yields tend to be better news for stock markets because they allow for higher fair market valuations over time.
Keeps an eye on earnings trends
Of course, the other part of the equation is earnings growth in earnings momentum. In a weakening economy, we would expect this to fall. And indeed mid has largely been the case earnings expectations.
For us, the US and European companies for the year ahead have adjusted to this weaker economic outlook.
US earnings forecasts take an increasing hit

Source: Yardeni Research, IBES
But I would say in the case of Europe, that earnings estimates have actually been surprisingly resilient. They have not fallen as much as I would have thought over the last few months. And this is principally due to better than expected quarterly results.
Eurozone earnings forecasts hold up surprisngly well

Source: Yardeni Research, IBES
This comes back to my contention that many companies particularly in Europe have responded quickly to the European energy crisis. They have managed to economise on energy consumption without heavily affecting production. This is clearly the case in Germany and I think also elsewhere.
If wage growth moderates, the pressure on profit margins from having to pay out higher wages as well as high energy costs could start to cool down.
And if consumption can be maintained at a reasonable pace as inflation comes down, with employment levels remaining, historically very high, then we may be in for a relatively positive surprise in the months ahead from the momentum in earnings forecasts in Europe.
Bearish consensus may be upset
All of this flies in the face of the very bearish consensus on the global economy and on Europe in particular because of the energy crisis.
Institutional investors remain pessimistic on the economy

Source: Bank of America
But remember, European energy prices are coming down fast, not only because of the relatively warm weather at the moment, but also as I said, because of the rapid adjustment to energy demand from industrial companies and in particular in Europe.
To give one example, European natural gas prices, the Dutch TTF benchmark, have fallen from a peak several months ago of 300 euros per megawatt hour to under 70 euros per megawatt hour today - a reduction from a peak of well over 75% already.
European gas prices cool

Source: FT, Refinitiv
We are now at natural gas and baseload electricity prices in Europe equivalent to the pre-Ukraine conflict period at the beginning of 2022. If this can be maintained, then the pressure from soaring energy prices will actually reverse to a large extent.
Yes, energy prices will still be higher than they were in 2020 and 2021. But the scale of the increase will be far lower than we might have feared some months ago. And therefore, the impact overall on the European economy, including the UK correspondingly should be lower than feared.
Where Is the Momentum: Regions to focus on
At an aggregate level, stock markets are behaving relatively well. In the main we see very strong momentum in a number of regions, notably the UK in the form of the FTSE 100, the Euro STOXX 50, and also emerging markets.
European gas prices cool

Source: tradingview.com
Funds to research:
VUKG Vanguard FTSE 100 ETF
FEV Fidelity European Values trust
JMG JP Morgan Emerging Markets trust
FCSS Fidelity China Special Situations trust
In particular, the emerging market gorilla which is China is seeing very strong rebound at the moment, thanks to an increasing number of measures put in place by the Chinese government to:
stabilise and support the property market e.g. with lower interest rates and easier lending policies, and
substantial relaxation of its zero COVID policy, to the extent where it doesn't really mean anything anymore.
The final piece of the puzzle which is encouraging is that they're now launching trial production of an mRNA-based COVID vaccine similar to the technology employed by Pfizer/Biontech and Moderna. This should allow for a much more effective vaccine against the Omicron variant which is the principal variant spreading today in China.
Chinese stocks rebound by c. 50% from October lows

Source: tradingview.com
Consequently, I feel pretty bullish on global stocks ex the US, including the UK, Eurozone, and China/Hong Kong. To this list, we can also add a number of other emerging market countries that I think look particularly favourable, including:
Mexico, which would benefit from nearshoring by US companies bringing production back from Asia, too much closer to home, and also
Indonesia, which benefits from proximity to China and the potential rebound in consumption there. Secondly, its commodity exposure potential potentially, particularly in areas such as palm oil, and of course, crude oil. And thirdly, a young and vibrant, vibrantly growing population, - so a growing labour force, which are all positive drivers of growth in Indonesia.
Funds to research:
XMEX Xtrackers MSCI Mexico ETF
HIDR HSBC MSCI Indonesia ETF
Latin American earnings forecasts have largely been positive
Source: Yardeni Research, IBES
Sector momentum: Financials, Industrials, Mining
At the sector level, the focus is should be on a surprising number of sectors, including:
Gold and silver producers, as the gold price rallies substantially on the back of weakness in the dollar and falling bond yields.
Financials, particularly banks, which are performing very well in the Eurozone and the UK, potentially particularly retail banks.
Industrials seem to be performing well, even as the economy cools.
Funds to consider:
AUCP L&G Gold Mining UCITS ETF
SILG Global X Silver Miners ETF
PCFT Polar Capital Global Financials trust
CB5 Amundi ETF MSCI Europe Banks ETF
ESIN iShares MSCI Europe Industrials Sector ETF
One final sector to keep an eye on is one of my favourites, the mining sector, because the sharp rebound in Chinese credit impulse should lead to a real sharp rebound in growth overall.
BRWM Blackrock World Mining trust
CYN CQS Natural Resources trust
And that in turn should lead to a rebound in the demand for base metals in particular copper. So I remain keen on companies exposed to base metal production, in particular copper production. And that leads us back to many of the global miners listed in the FTSE 100 but also copper miners specifically such as, of course, Antofagasta and so on.
Have a great week, let’s hope the current rally is extended!
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

7 comments
Becoming a weekly must read for me...thanks Edmund
I prefer to hold Deutsche Bank shares rather than a European Bank ETF.Anybody who knows their history will know Germany will never let Deutsche Bank go bankrupt .The same applies to the USA and JP Morgan.
Thank you Edmund very informative and helpful.
I do share your optimism in relation to China, softer monetary policy, government incentives, reopening (speed uncertain due to Covid) BUT I remain bearish on US, European, and UK markets still suffering during 2023 of high-interest rates, reduction real earnings and possibly exposed from inflationary effects from China reopening. A near all time high for the FTSE100 seems unjustified (despite its exposure to Energy and Resources).
Every time I think about shorting the ftse100, it continues to rise! Can't rise forever though...
Thank you Edmund for another informative article and podcast presented as usual with balance and sound reasoning.
Great article as always, full of useful information and ideas.
Thank you for a very interesting and thought provoking article