Market Musings 070424: A Copper Cauldron in the making?

Market Musings 070424: A Copper Cauldron in the making?
5 Crucial Charts of the week
Copper, Tin and Zinc poised to surge higher in base metals breakout
5 Charts to Consider
1.Bond volatility remains contained, for now:
US bond market volatility remains close to the lows of the last 2 years in spite of solid US economic growth and employment. Bond markets remain relatively calm about the prospects of longer-term inflation. Should this rise significantly, it could trigger a correction in global stocks

Source: TradingView.com
2.US dollar still trapped in trading range:
Another warning sign for stock markets would be a US dollars surging higher, which is often a sign of rising financial stress and risk. So far, the US dollar has not risen much despite strong growth and stagnation in the US inflation rate, which could prompt the US Federal Reserve to delay the start of interest rate cuts beyond June.

The CEW emerging market currency ETF (v USD) is holding up well, highlighting that the US dollar is not strengthening against emerging market currencies in general.
3.Emerging Markets ex China show strong momentum:
EM stocks ex China, led by India, South Korea and Taiwan continue to show strength, although they have trailed the US and Eurozone over the year to date.

4.Oil & Gas sector takes its lead from a rising crude oil price
US oil & gas stocks move to a new all-time high off the back of a rising crude oil price (rising Middle East tensions) and elevated oil refining margins, which boost profitability. In Europe, TTE TotalEnergies follows US integrated oil stocks to new highs, but in general European oil stocks remain far cheaper than the US ExxonMobil or ChevronTexaco.

5.Copper joins the commodities party
While crude oil, gold and cocoa have taken the limelight as star commodities performers this year, watch Dr Copper which is also starting to make a move higher. Typically copper reflects the health of global industrial demand, as it is a material used heavily in construction (pipes and cables), electrical machinery and cars (cabling), electronics and electrical infrastructure.
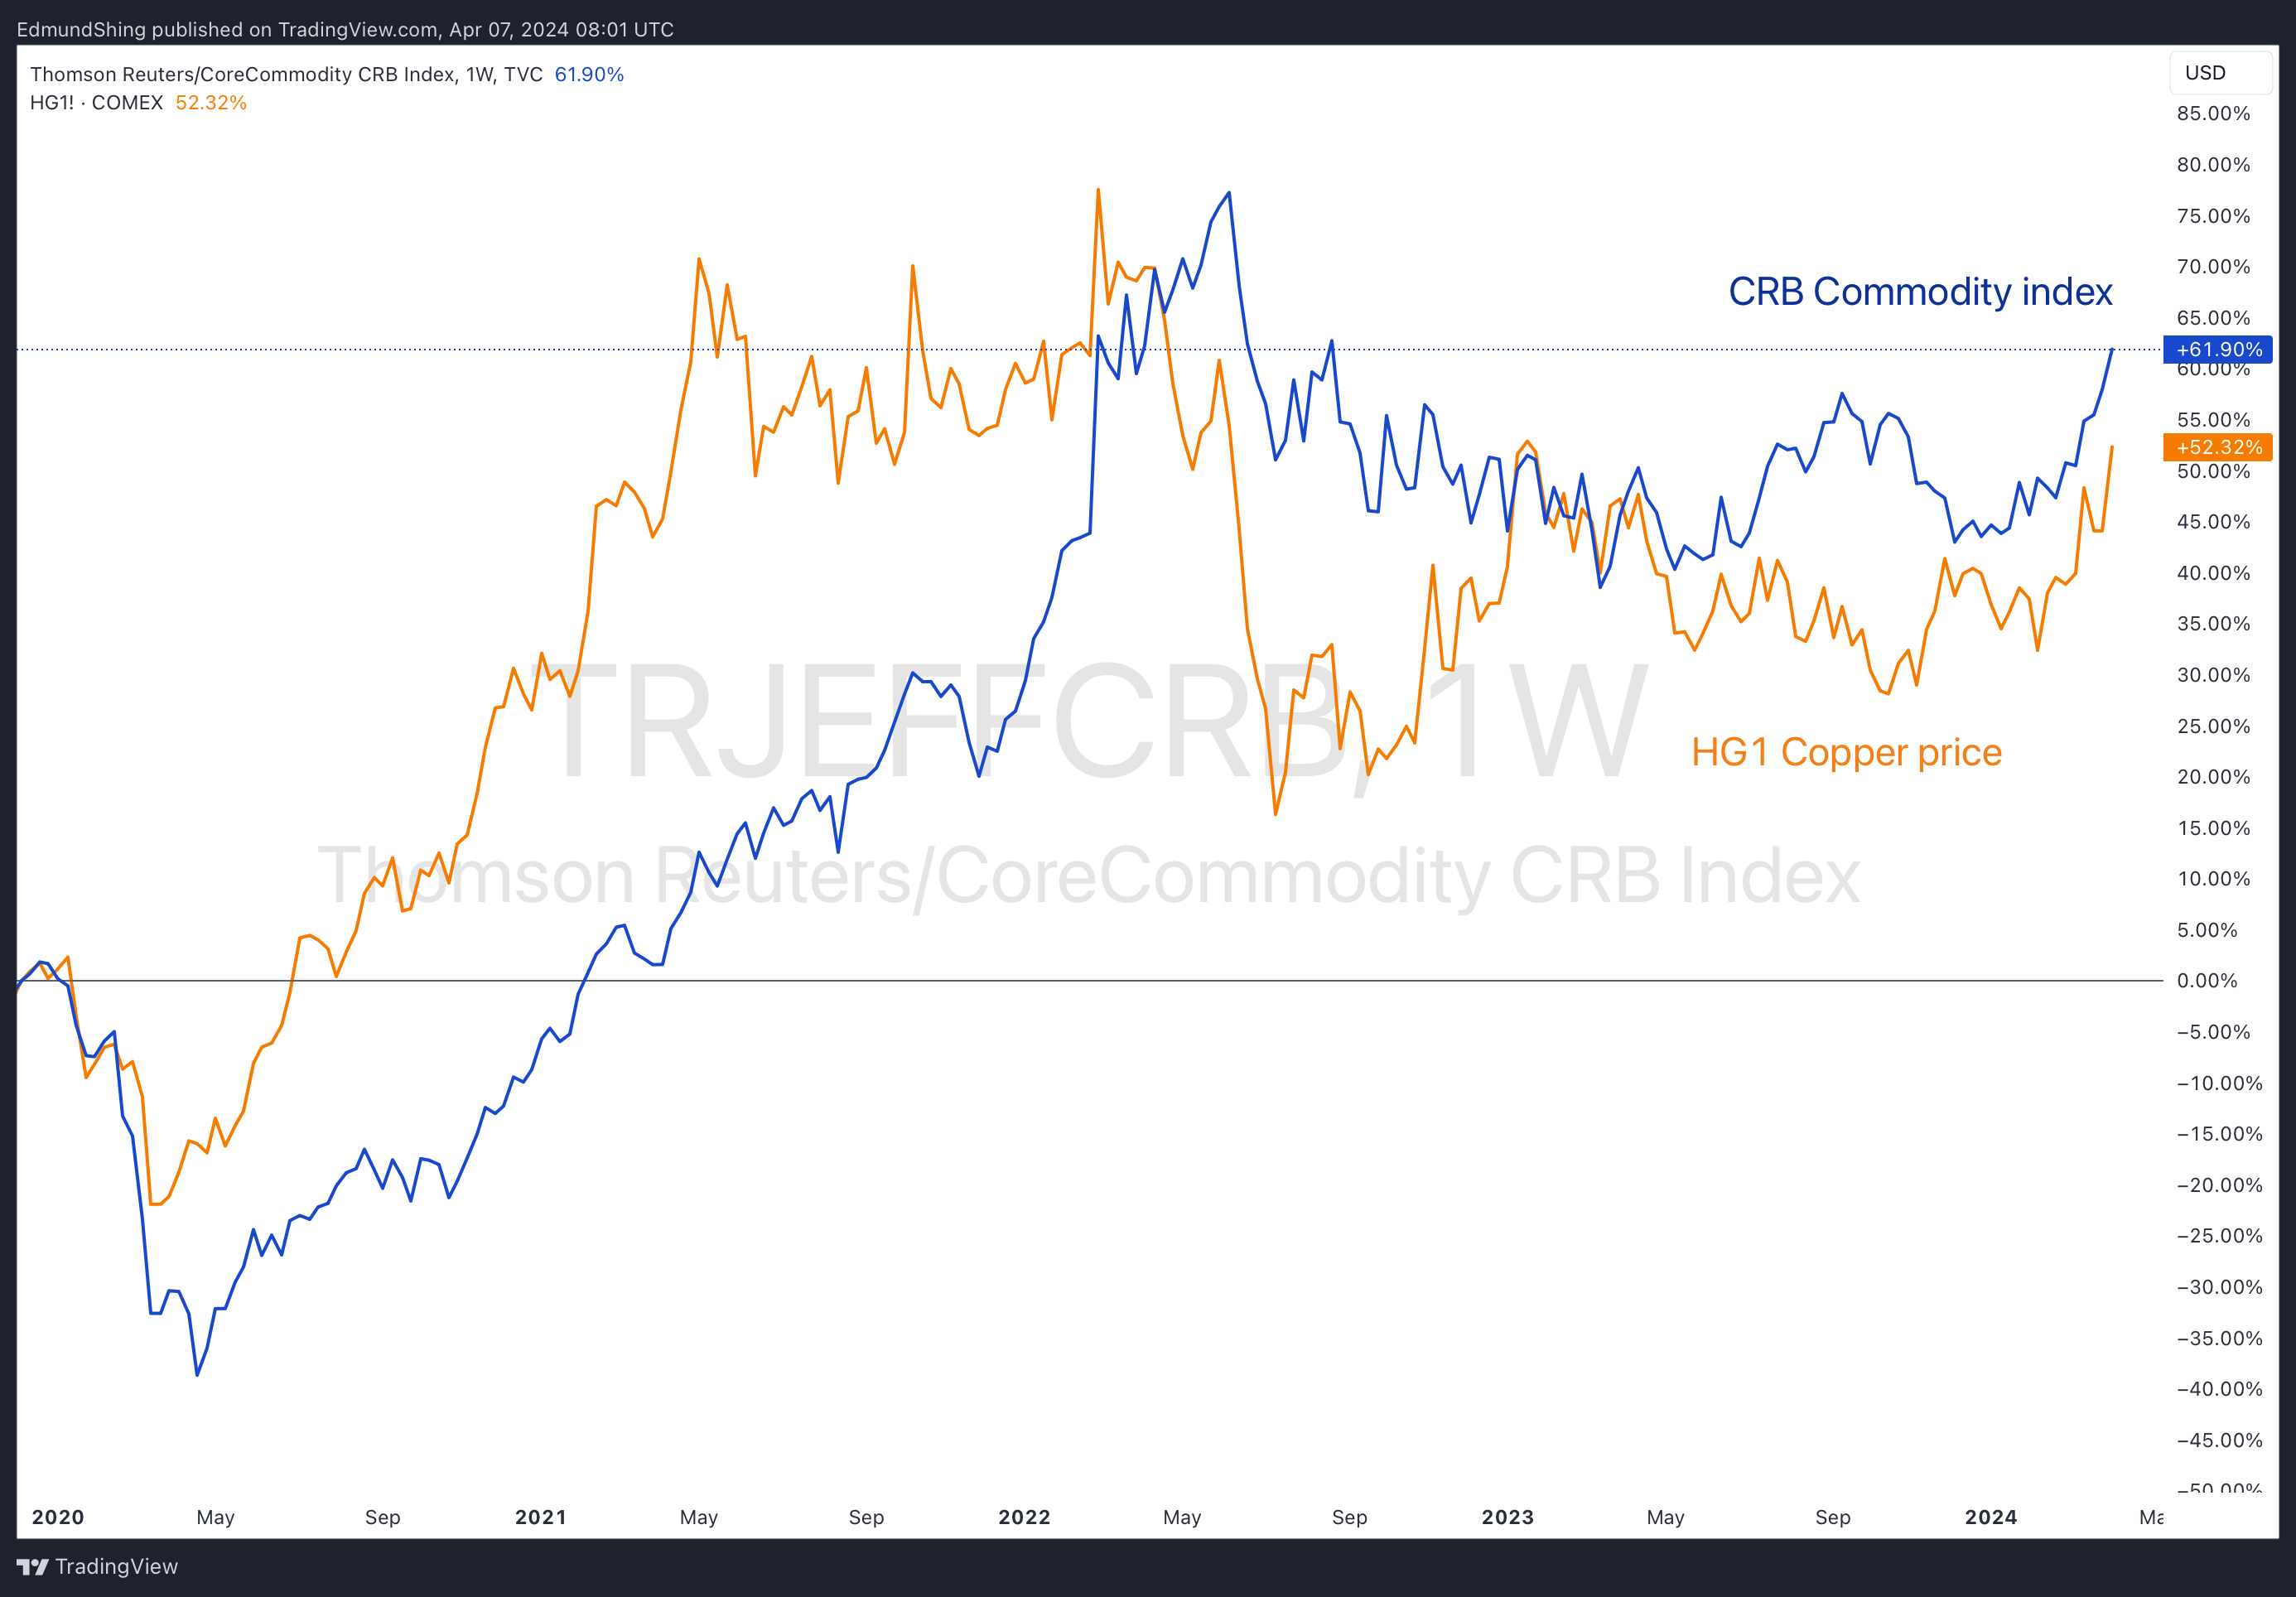
Copper demand growth and supply shortages could turbocharge price
Copper demand should continue to grow steadily over the coming months and years driven by a number of clear needs;
Investment in energy transition via battery and hybrid electric vehicles, electronics and solar panels;
Investment in energy infrastructure upgrades prompted by energy transition plus heavier energy usage from Artificial Intelligence-related data centres
Global manufacturing activity is picking up at last, with a cycle of inventory restocking of goods ahead of us, given the low current levels of global inventories. This general pickup in industrial activity should also fuel greater demand for copper in the months ahead.
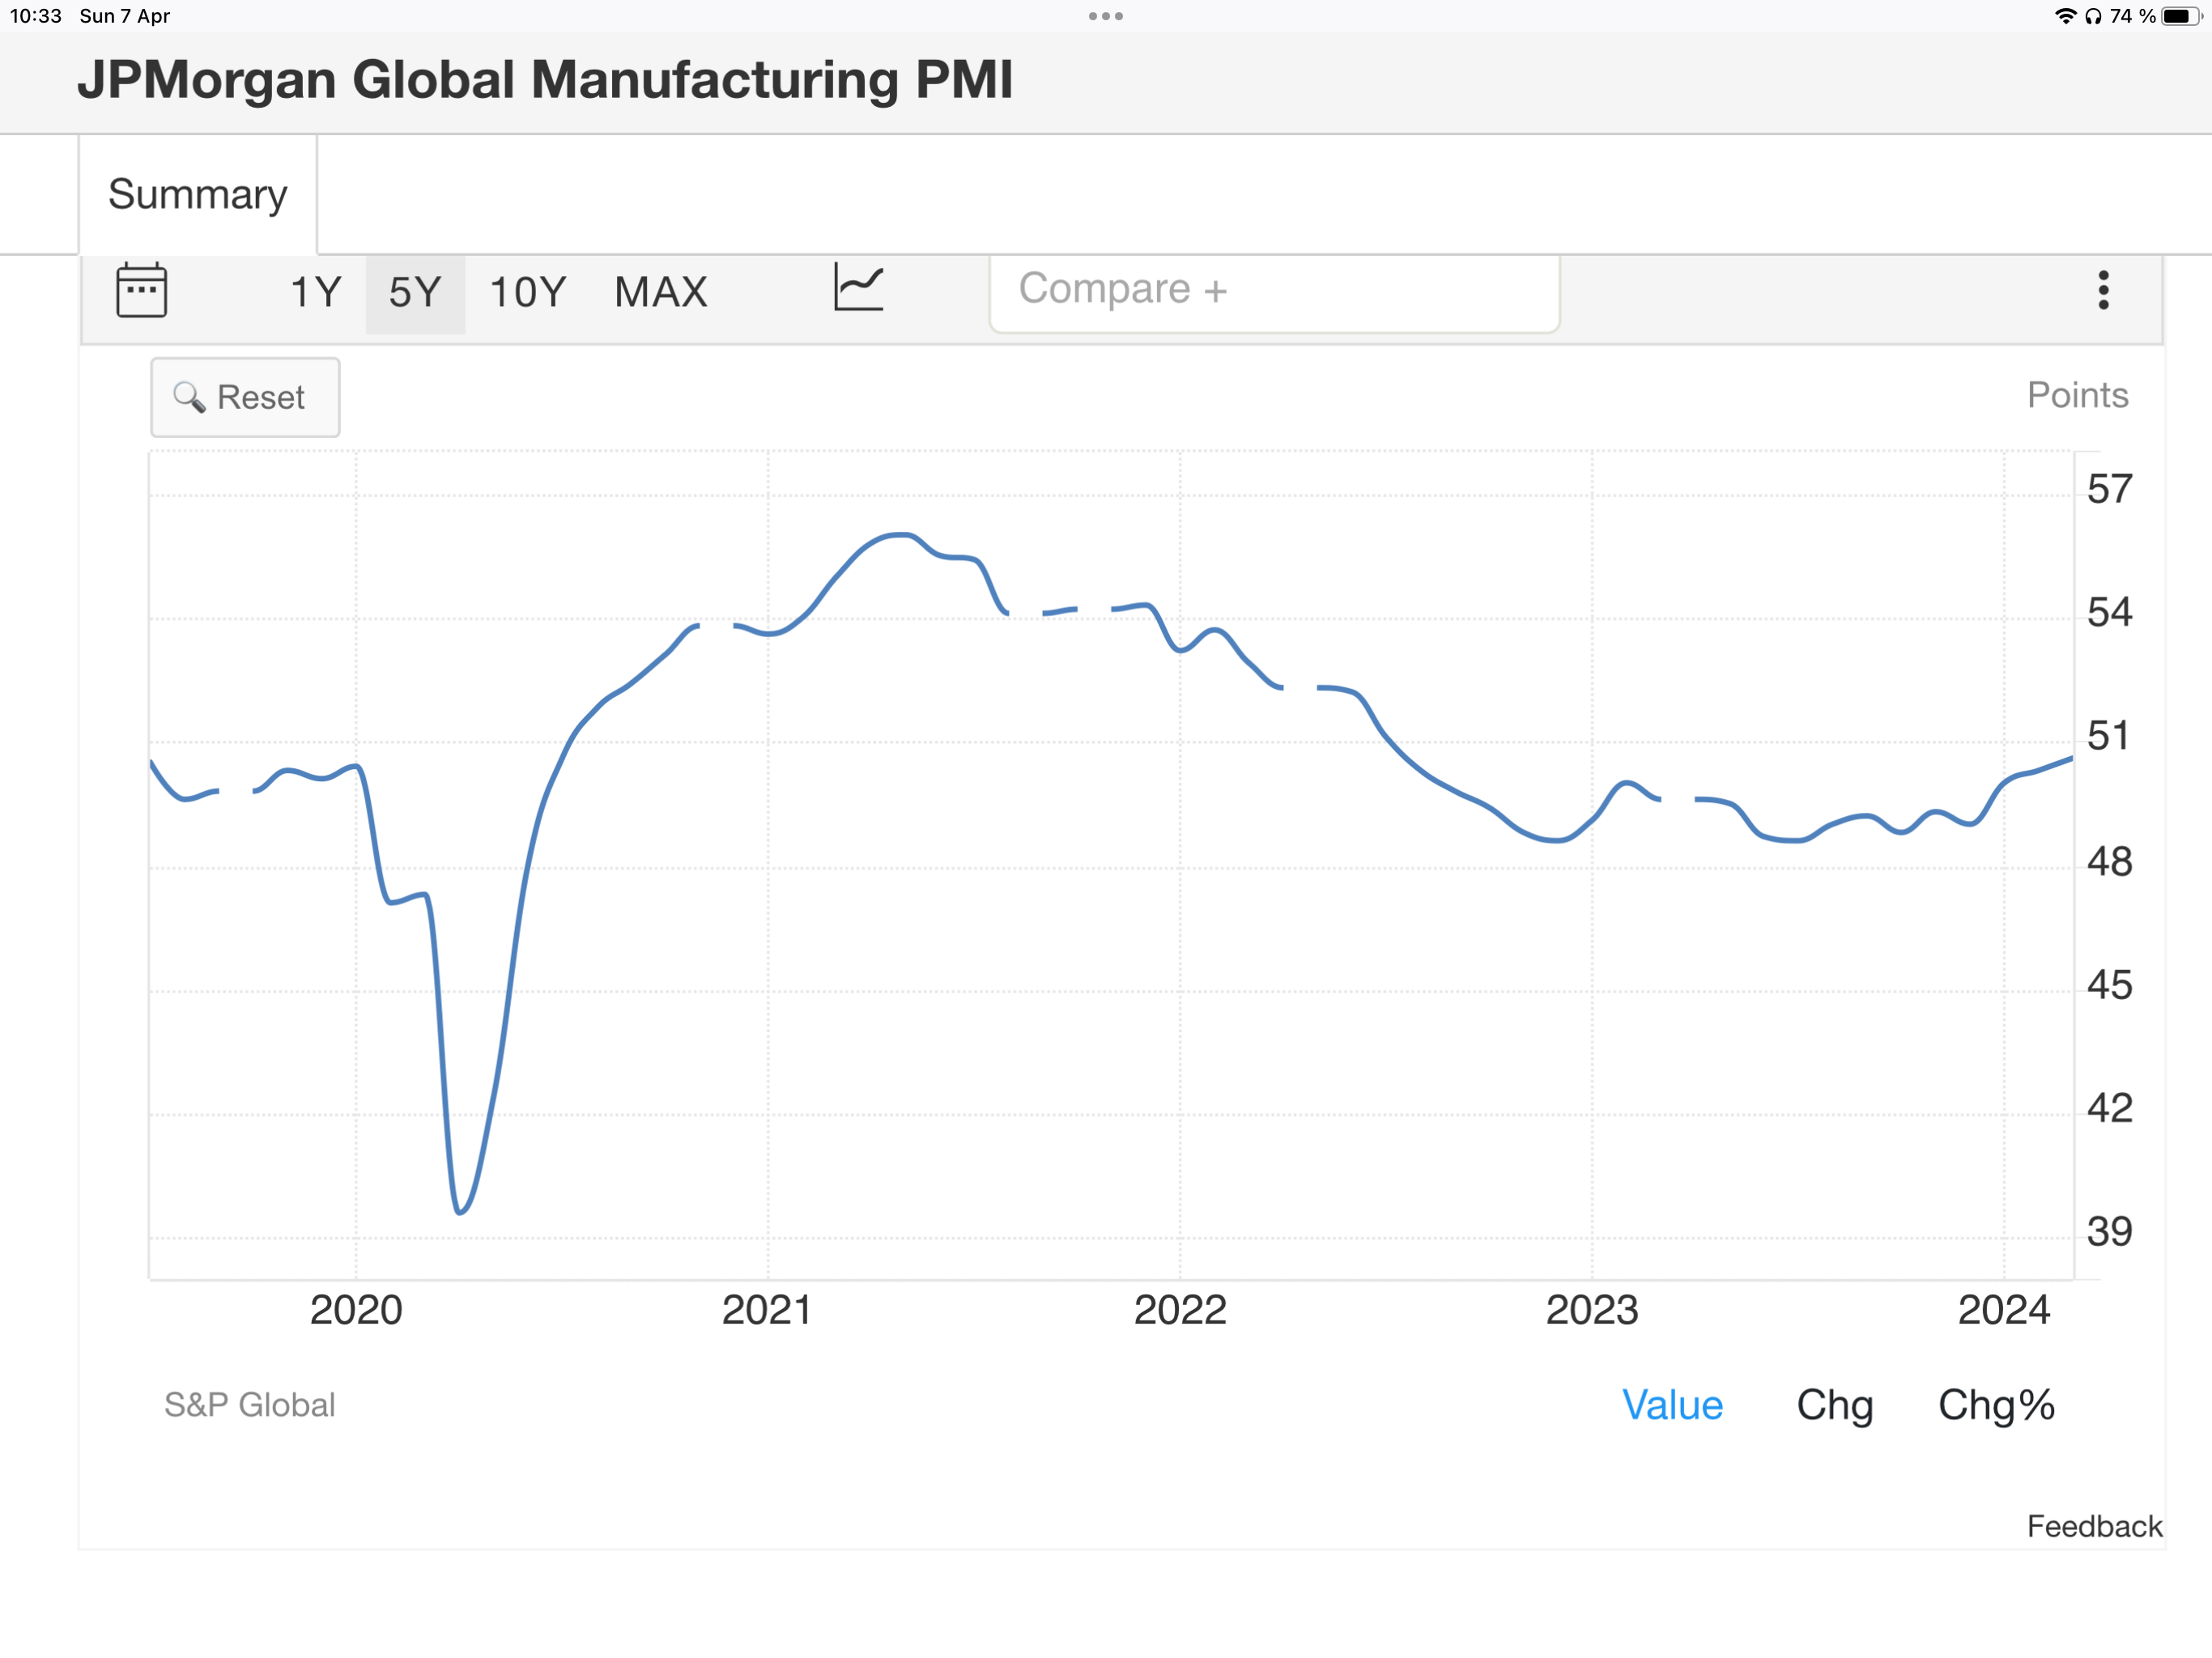
In addition, copper supply is constrained more and more by geopolitics in Central and South America, with the recent shutting of a huge mine in Panama and ongoing production shortfalls from major mines in Chile.
Note too that there have been remarkably few major discoveries of new copper deposits in the past 10+ years, while mining capital investment has also been running at low historical levels since 2015.
Long-term copper price could rally to $5/pound and beyond
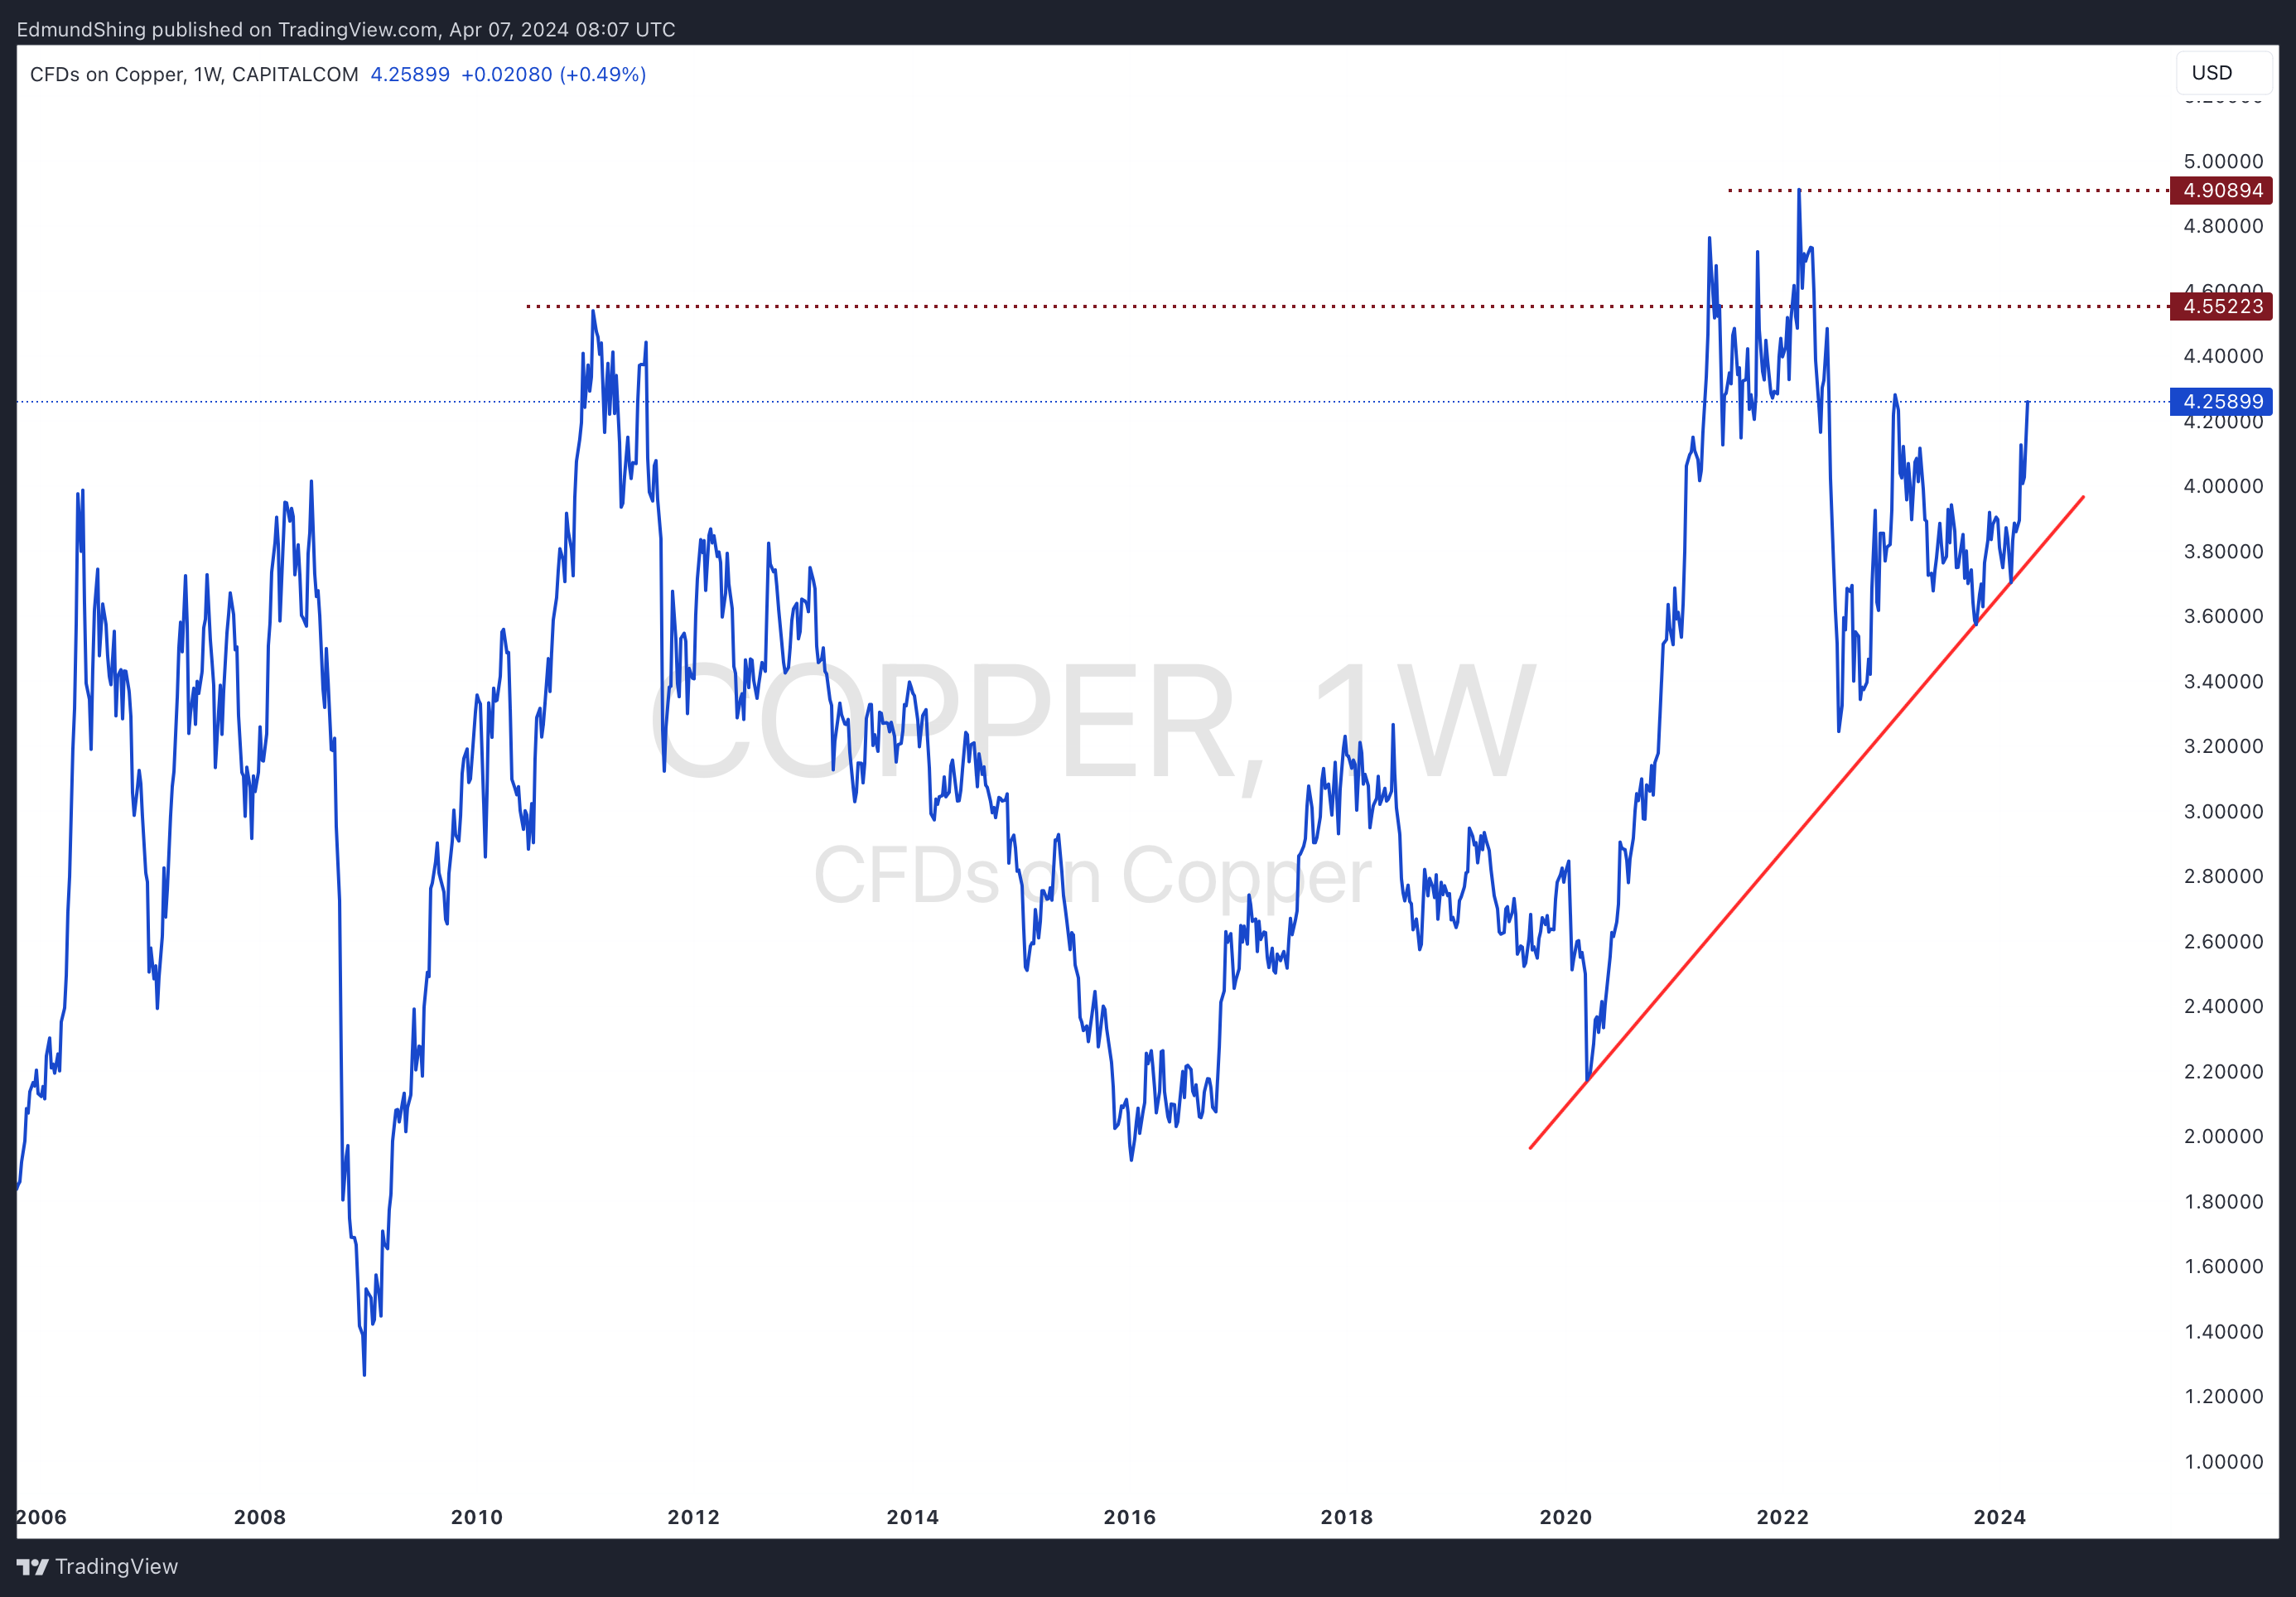
I think that copper, together with zinc and tin could all experience sharp rises in price over the medium-term due to this demand growth combined with restriction in supply.
Ways to invest in this theme include the following:
A physical copper ETF that invests in the commodity (COPA);
A copper miners ETF that invests in the largest global copper producers (COPX, MINE);
Specific individual copper-producing companies (ANTO, ATYM, CAML FCX)
COPX Global X Copper Miners UCITS ETF
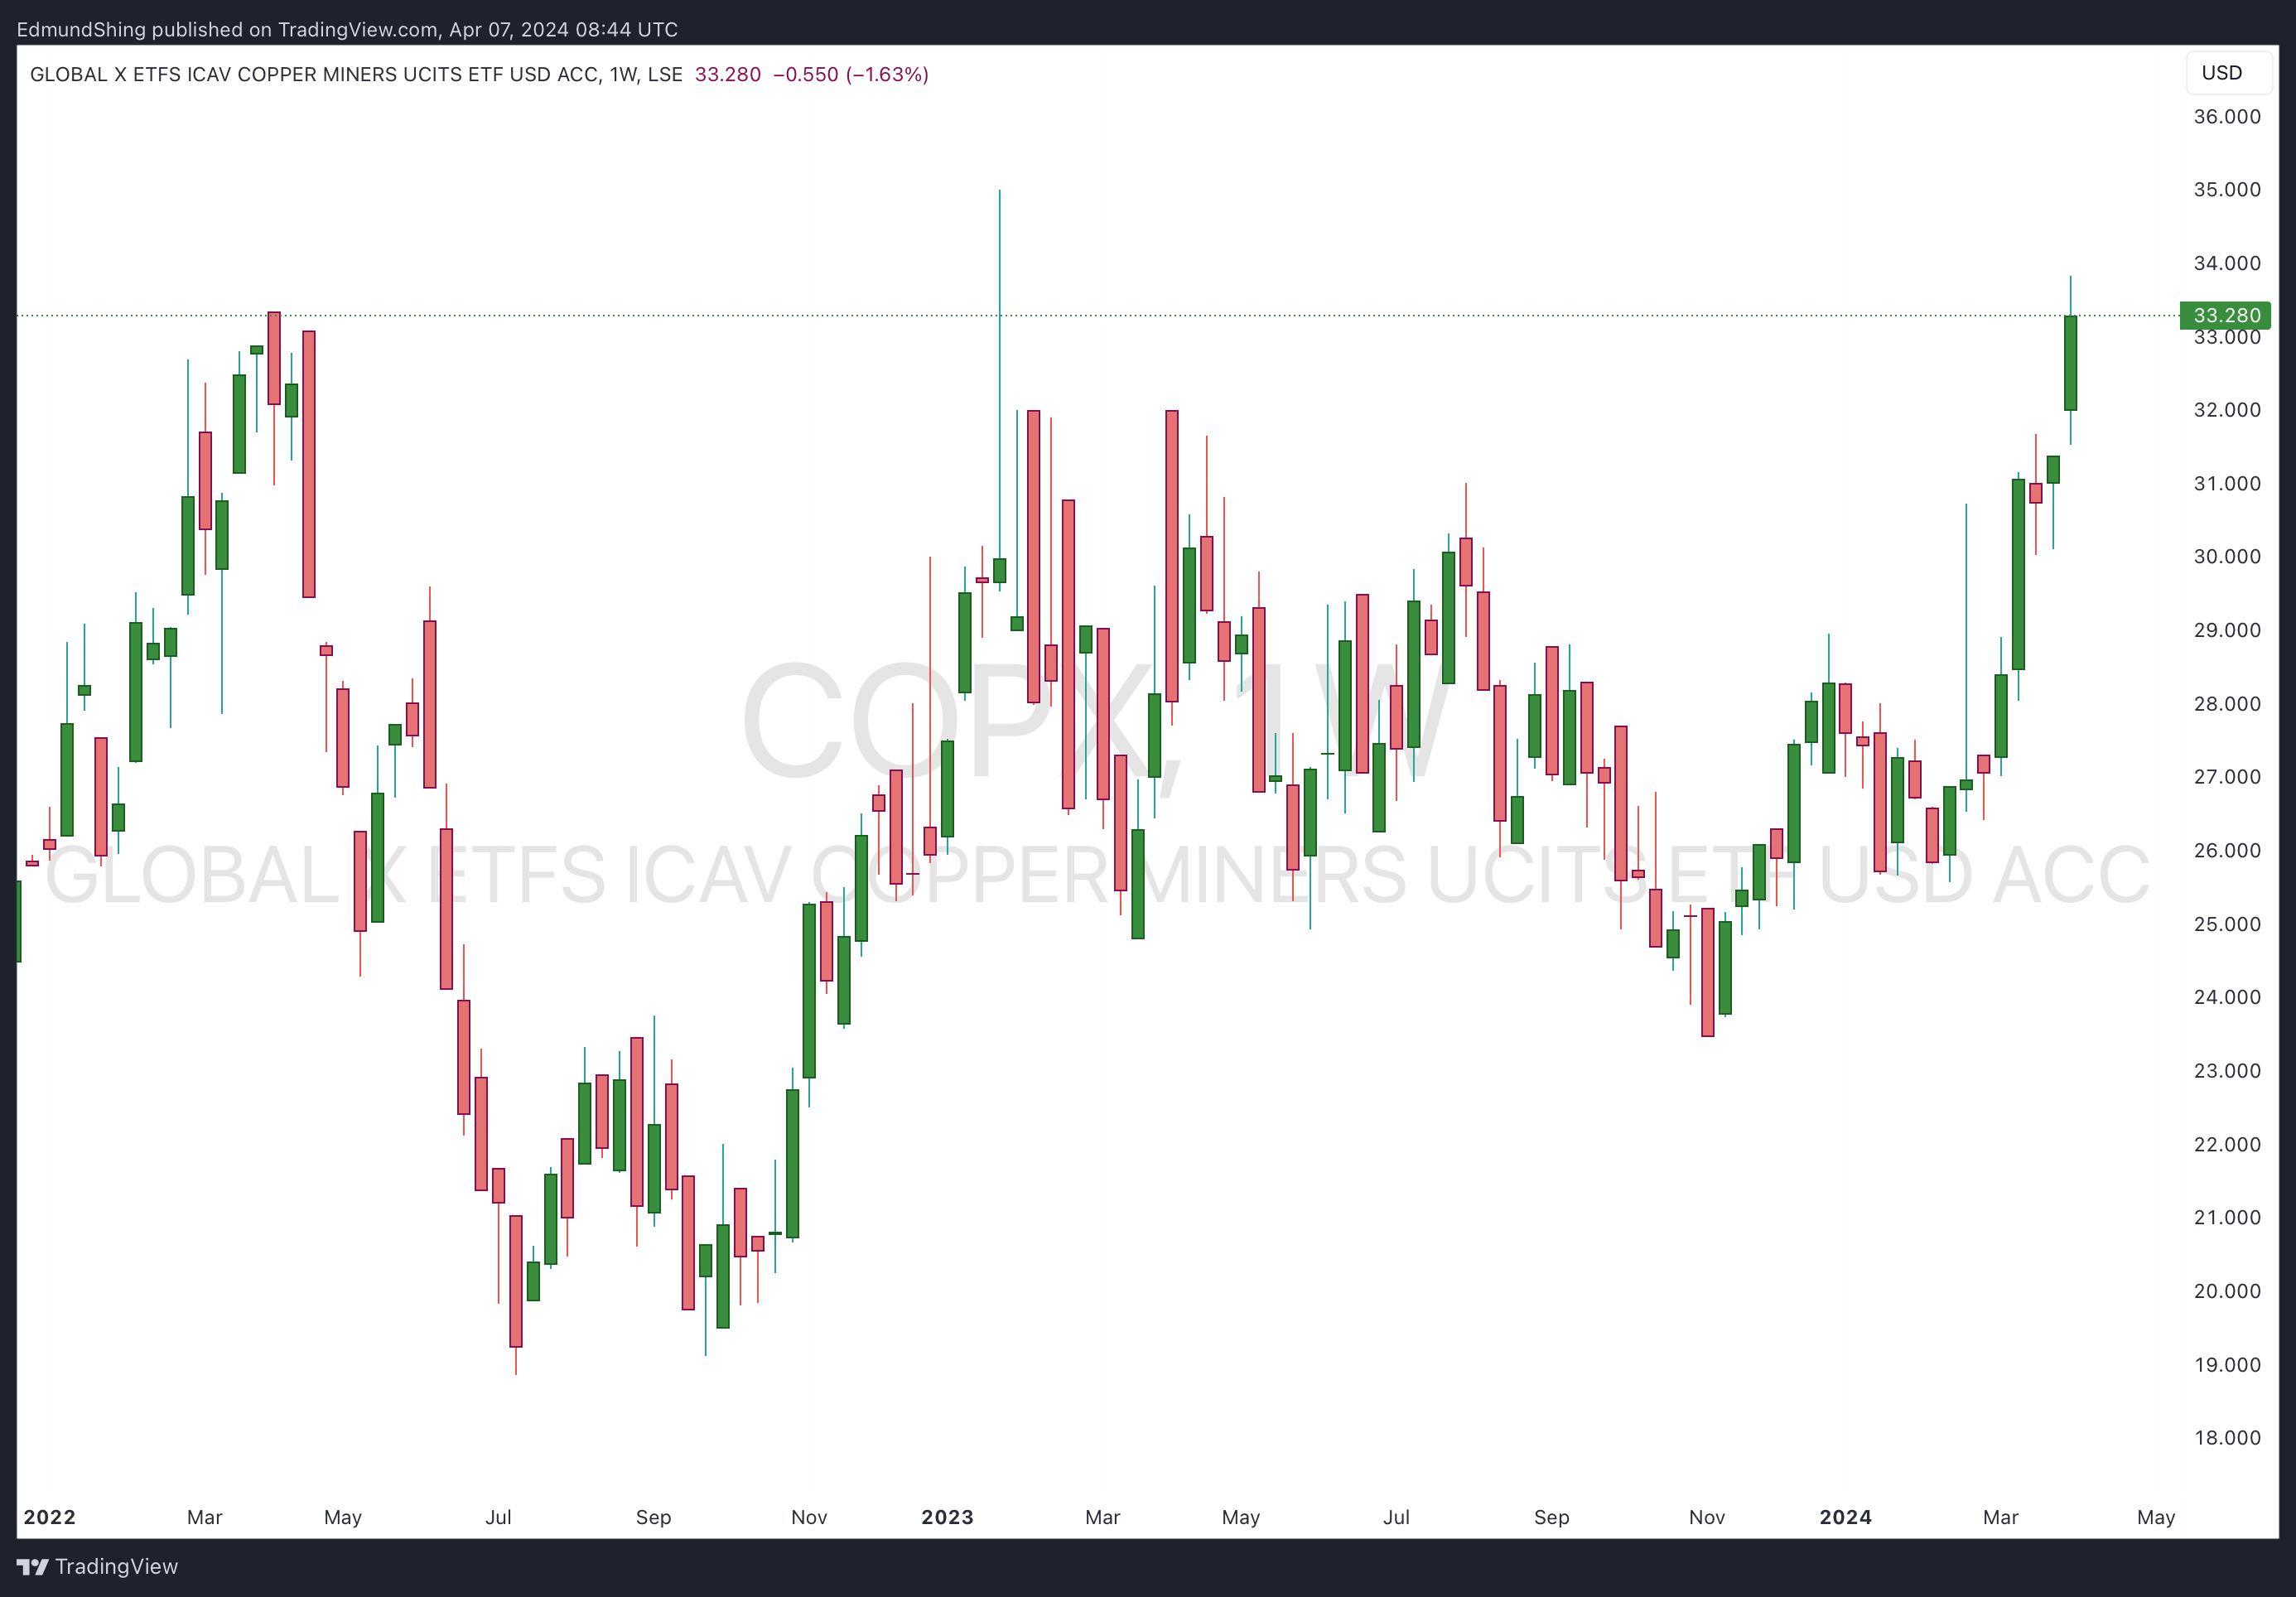
As always, do your own research into these possibilities.
All the best for the week ahead,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
Rubbish.
Biggest user is China and they are in recession. Investors are 0desparate to buy something so they push up copper ETFs and others jump on the bandwagon until reality sets in.
Brass is 60% cu, 37% zn but galvanised steel used more zinc that is not now needed-false zinc market as property sales fal. Zinc traders killing the business.
Hello Edmund, good article, thank you.
I share your view on Copper. I rarely pay attention to macro issues being a very long term stock-picker by nature but copper intrigues me. It seems to be often overlooked, unyet its key to so much of the future? As an electronics engineer with training and experience in aerospace and defence and technology industry sectors I have no mining or commodity knowledge, except from the mistakes I've made over my investing career.
I understand the current issues facing demand for copper, a slowing in global growth and weak demand from China. As well as the current supply issues - an unforeseen ramp up in African and Indonesian copper production partly as a byproduct of the demand for cobalt and nickel. As always its cyclical. And Current prices seem to have an overly large impact upon the forecasts for future prices? I'm guessing that's because a DCF tends to discount future cashflows quite heavily. Though when you arrive in the future those cashflows are no longer discounted and the value in the past is no longer relevent? Intriguing.
In addition to the energy transition and growing global demand for higher living standards I'm not sure that the implications of the abrupt reversal in decades of falling defence spending has been factored in at all? Not just future defence spending but the enormous rate at which drones and missiles are fighting it out with AI enabled defensive electronic warfare systems instead of humans with guns. The rate of destruction of equipment, some of which has been stockpiled for decades, is phenomenal. Replacing it will be a gradual process of increasing demand. And don't discount guns. The demand for ammunition is currently limited by the remaining factories. The 2 remaining in the UK are said to be working 24/7/365. I asked an AI to estimate the copper content of the brass in small arms and artillery ammunition. Currently only a couple of percent of copper demand. But not for long? And unlike commercial uses it has a distinct national security chime to it - which could see a premium for some mines in favoured locations, or national stockpiling of raw materials?
I'd prefer a steady rise in copper to a price-spike. Mainly because my preferred investment has been Ecora Resources (LON:ECOR) whose deal with South32 royalty company has transformed them into a 'copper bottomed' royalty company - but with big production increases forcast in 2-3 years as new mines and extensions in Australia and Chile come on line - I'd prefer to see big cashflow then to a spike in the price now? Sadly I rarely get my way!
cheers
Mark
PS Ecora Resources (LON:ECOR) also has useful assets in cobalt, nickel and vanadium with an interesting side bet on uranium, through a small royalty from Four Mile in Austrilai, a toll-milling income stream from Denison in Canada and until last week an unknown and unvalued basket of prospective uranium royalties through its Advance Royalty Corp subsidiary in the Athabasca valley.
Hi Mark,
Good point on Ecora Resources (LON:ECOR) . On watching their recent investor meet company presentation, the CEO focussed on their preference for quality copper royalties. Those royalties are still some way out, and the current share price has basically completely discounted any value in their non-producing, developmental royalties at present. SP stands at a 60% discount to NAV right now