Market Musings 120223: Time to cool down after a hot start

Market Musings 120223:
Time to cool down after a hot start
Consolidation to be expected after a strong start, negative seasonality for the rest of February.
Summary
US Soft/no landing narrative gains traction
Short-term interest rates rise, pricing risk of higher central bank rates
Higher rates put a brake on the stock market rally, for now
European stocks remain cheap and unloved
But European Q4 2022 company results have generally been positive
Remember that over the long term, mid-caps in US, UK and Europe outperform large-caps, by far
Podcast: Our investment strategy for February 2023
How is the decarbonisation of the economy going?
How are we financing the energy transition?
Efficiency is the name of the game.
What is a good way to invest in the energy transition?
US Soft/no landing narrative gains traction
Markets are giving increasing credibility to the potential for the US economy to escape economic recession in 2023 - a so-called soft or no landing scenario. The strength of the US employment market (an incredibly strong January non-farm payroll report and a sharp rebound in the ISM Services PMI survey for January to growth) has given some credence to this possibility.
January US ISM Services PMI survey - sharp rebound

Source: ISM
But at the moment, good news for the US economy can be bad news for stock and bond markets, as unexpected economic strength could prompt the US Federal Reserve to raise interest rates by more than expected in order to ensure that inflation rates return to more comfortable levels over the remainder of this year.
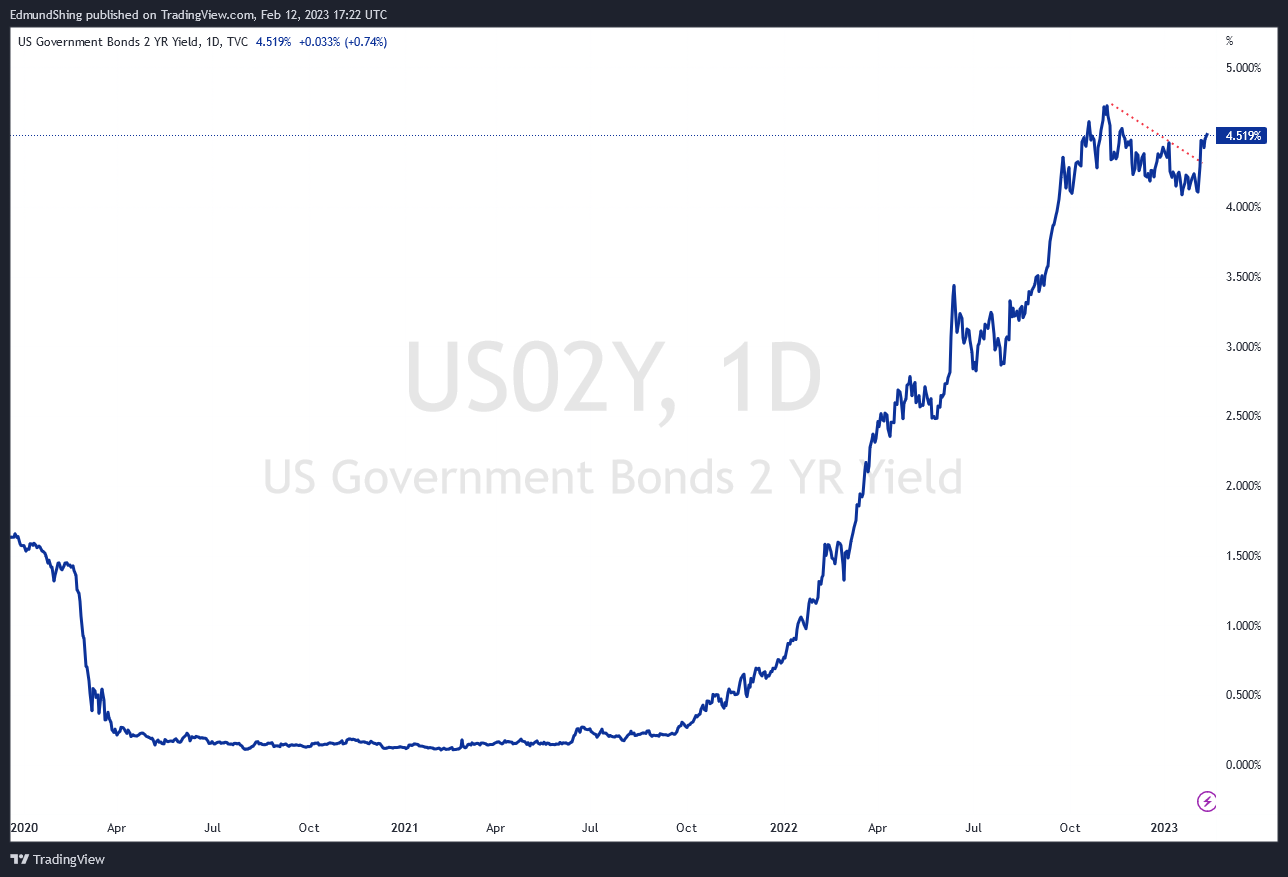
This prospect has been reflected in sharply higher short-term bond yields as the bond market discounts the risk of a higher peak Fed Funds rate than the 5% expected in the next few months.
US 2-year bond yield breaks recent downtrend, rebounds to 4.5%
Source: tradingview.com
Higher interest rates are bad for not only bonds but stocks, as investors have the potential to invest their savings in even higher risk-free (or nearly risk-free) interest rates, reducing the appeal of stocks. In addition, higher interest rates bizarrely raise the risk of an eventual economic recession! So good news in the short term can become bad news in the longer term…
The key statistic to keep an eye on this coming week is the US January CPI inflation number, to be released on Tuesday. This will help to confirm whether we should really be concerned about persistently high inflation and thus the risk that the Fed will raise rates higher than the expected 5-5.25% level. If the downward trajectory of US inflation is maintained on Tuesday, then stocks could benefit from the resulting relief.
Expectations for month-on-month US CPI inflation for January

Source: tradingeconomics.com
Seasonality tends to be negative for stocks for the second half of February, historically. So don’t be surprised if stock markets continue to consolidate in the short term, after what has been a very strong start to 2023 - this would be entirely normal.
Remember that after that, the months of March and April then tend to be seasonally strong months for stock market returns…
Still unloved, European stocks makes a comeback
Let's be clear - since 2009, global investors have fallen in love with US stocks given their tremendous performance, led by growth stocks in the form of the Nasdaq index. Prior to that, from 2003 to 2007, emerging market stocks were all the rage, led by a China boom.
Emerging Market stocks +400% from mid-2003 to mid-2007 (in USD)

Source: tradingview.com
So for the last 20 years, global investors have taken less and less interest in European stock markets - for good reason, as the better growth prospects have been found elsewhere over this period. To date in 2023, there is little evidence of substantial buying of European equity funds/ETFs by investors in Europe or elsewhere.
European stocks have been out of favour for ages, US and EM preferred

But as we say in English, "every dog has its day". Is this the day for Europe, despite all of the economic pessimism around conflict, slowing growth/recession and high inflation rates?
From a valuation viewpoint, world ex US stocks including European stocks are still relatively cheap on a range of metrics. This is important for long-term returns, but matters little over a 6-12 month timeframe.
Europe, UK and Emerging Market stocks all much cheaper than US

Earnings and price momentum are what count over this timeframe. Earnings and price momentum is clearly with UK and French stocks, judging by the breakout of the UK FTSE 100 large-cap index to a new all-time high, and with the French CAC 40 index very close to doing the same.
UK FTSE 100 index breaks to a new All-Time High

Source: Bloomberg, BNP Paribas
UK and European stocks are buoyed by strong quarterly results for Q4 2022 from key oil & gas, mining, banks, and luxury goods stocks at a time when US technology stock results have been somewhat disappointing.
Conclusion
With the prospect of healthy shareholder returns from a combination of dividends and share buybacks, better-than-expected economic momentum (as inflation declines), and stable long-term interest rates, European stocks have several reasons to shine over the next few months.
Since 2009, total returns from UK and French large-cap stocks have been strong at nearly 8% on average per year for FTSE 100 stocks, and over 9% per year for French large-cap stocks (including the effect of dividends, reinvested).
Since 2009, healthy returns inc. dividends from FTSE, CAC 40

Source: Bloomberg, BNP Paribas
Moreover, mid-cap stocks (i.e. the FTSE 250 index in the UK) in the US, Europe and the UK have traditionally outperformed large-caps in each of these markets over the long term, by wide margins.
So it may be an idea to look at smaller-cap companies in the UK and Europe too…
Since 2009, UK mid-caps have outstripped the FTSE by miles

Source: tradingview.com
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
Well you need to consider the impact of a growing cold war with China on supply chains and of course defence stocks. Also a protracted war in UK which continues to deplete western invantories of munitions. So some insight into the direct impact on linked stocks and the indirect impact on companies dependant on the new cold war countries. Is Apple moving to India fast enough? Can India be seen as a safer haven anymore given its recent love in with China, not to mention South Africa and its joint military exercises with Russia. I feel too much emphasis on sentiment, not enough on geopolitics
This sort of macro commentary is very welcome. The direction of the market is the main factor driving individual shares. It is very interesting how the narrative has changed from deep gloom in November to sunny optimism now. Personally i am still gloomy, but perhaps this is my personality!