Market Musings 131225: Santa Rally incoming?

Market Musings 131225: Santa Rally incoming?
December video: Outlook 2026 (click on link)
1. Government stimulus to support growth:
the US should focus on tax cuts and deregulation efforts ahead of the
November 2026 mid-term elections. Europe will spend on infrastructure
and defence, while China and Japan will also add targeted measures to
support domestic consumption and the property market.
2. Moderating inflation to allow lower US rates: steady
US inflation and low/falling inflation in Europe and Asia should allow
for lower interest rates in the US and emerging markets. Long-term
yields should remain around current levels, with IG credit potentially
benefiting from tighter credit spreads. Favour Euro IG credit including
financials, EM sovereign bonds in local currency
3. Ongoing bull market in stocks.
Ample liquidity, lower rates, earnings growth, deregulation and buoyant
buybacks support global stock markets. Prefer World ex-US (Japan,
emerging markets), health care, Euro banks and mining sectors.
4. Precious and strategic metals:
long-term positive on precious metals given expected weaker US dollar,
lower rates and persistent geopolitical volatility. Copper to benefit
from strong global AI/electrification demand with supply limited. Favour
exposure to physical copper, global mining stocks.
5. Six investment themes for 2026:
i) Ride the bull but guard the gains; ii) Escape shrinking cash
returns; iii) Beyond algorithms, the new AI frontiers; iv) Welcome to
the new age of scarcity; v) Investing when policy rules markets; vi)
Opportunity Rising: the allure of Asia.
2026 Investment Themes (click on link)
Global markets are entering a new phase marked by falling interest rates, abundant liquidity, and structural changes in technology and resources. These dynamics are reshaping returns, asset allocation, and long-term investment opportunities.
- Lower rates squeeze returns
Central banks worldwide, led by the U.S. Federal Reserve, continue to cut rates, pushing short-term yields near zero and dragging long-term bond returns lower. Savers face minimal returns on cash and government bonds, while corporate spreads remain at cycle lows—reviving the hunt for yield. - Liquidity fuels equities
Strong liquidity, robust earnings, record buybacks, and retail optimism could drive global stocks higher despite stretched U.S. valuations. Volatility, however, is expected to rise as the bull market enters its fourth year. - Dollar weakness and global shift
The dollar’s sharp depreciation signals a turning point for U.S. exceptionalism. We see opportunities in non-U.S. equities and tech-heavy Asian markets dominating critical hardware sectors. - AI’s next wave
Artificial Intelligence moves beyond language models toward robotics, automation, and autonomous vehicles—boosting demand for electricity and ultra-clean water. - Resource scarcity reshapes commodities
Rising demand for strategic metals and energy, combined with supply constraints and geopolitical leverage, points to a long-term bull market in commodities.
Santa Rally incoming?
Officially, the Santa rally refers to the last 5 trading days in December and the first few days of January when typically stocks perform well.
However, in actual fact looking at the last 20 years, the year-end rally has started more often in mid-December and cooled by mid-January. This can be seen in the seasonal chart below of the typical US S&P 500 index performance from mid-December through to the end of the first week in the following January, based on the last 20 years-worth of history.
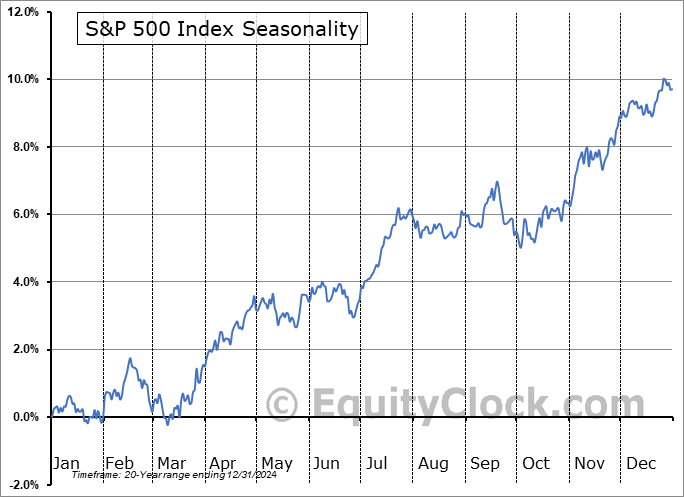
Source: equityclock.com
In the case of the UK FTSE 100 index, the performance seems to be stronger over the last 2 weeks of December, but fizzles out easly in January. The FTSE 100 has posted an average monthly return of +2.0% in December over the last 20 years, statistically the second-best month on average only just afcter April (+2.1%).
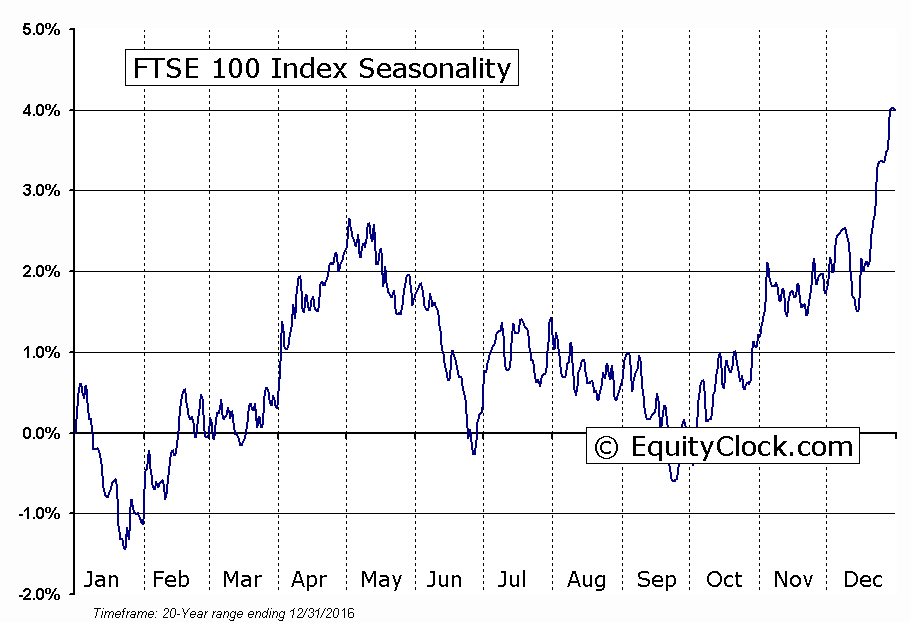
Source: equityclock.com
Another stock market that does particularly well on average in December is the Japanese Nikkei 225 index, with an average +2.1% gain over the month.
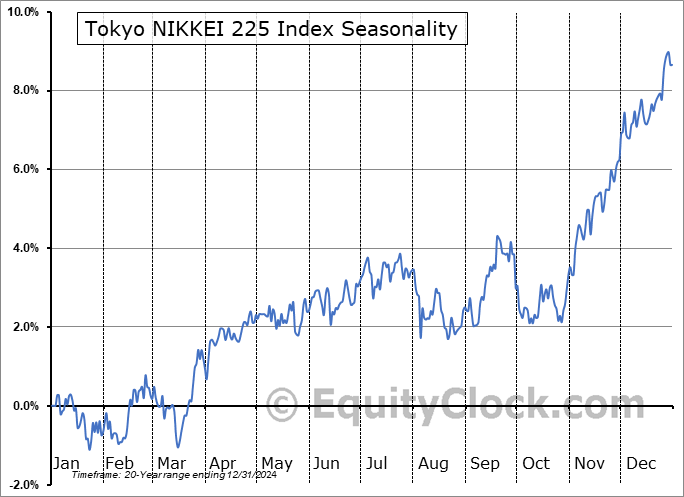
Source: equityclock.com
Where is the strongest recent momentum to be seen
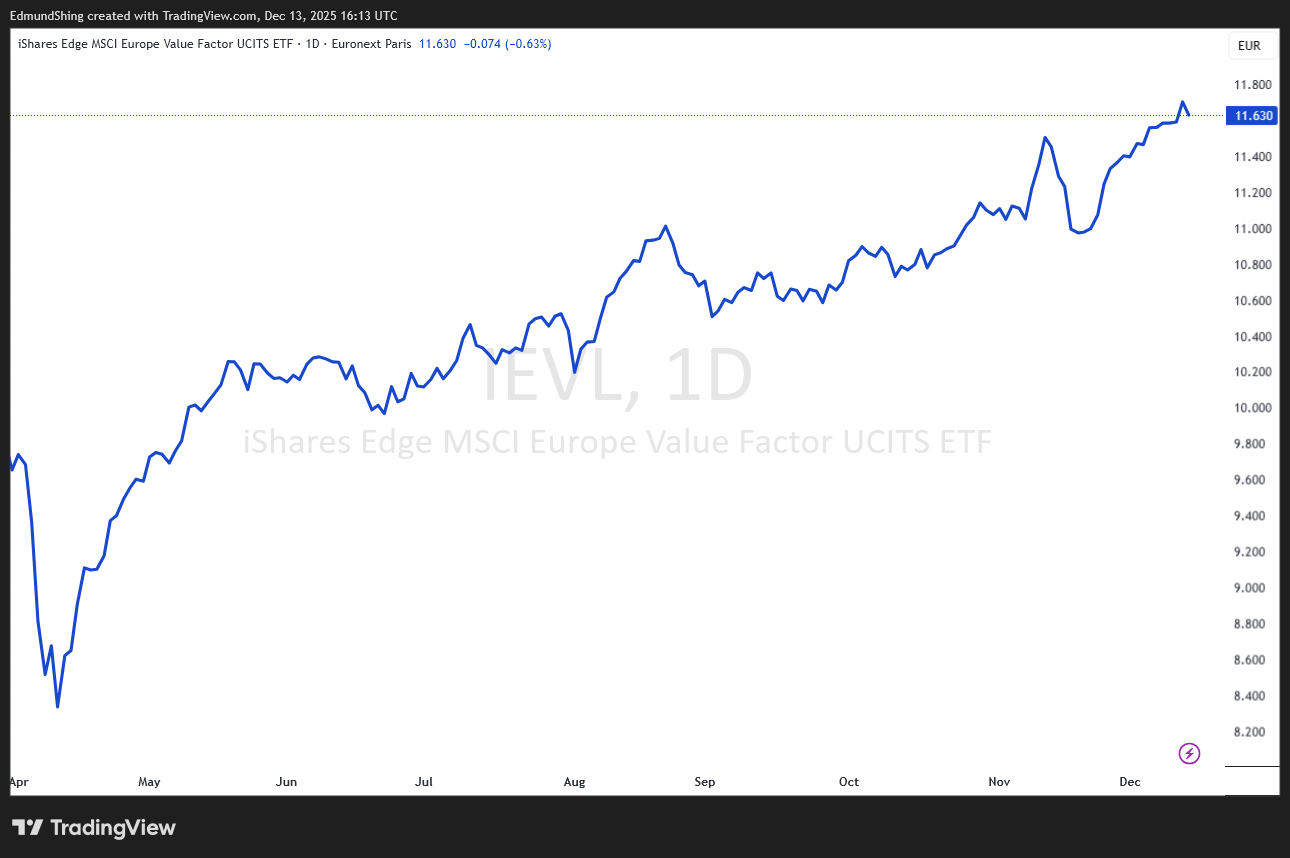
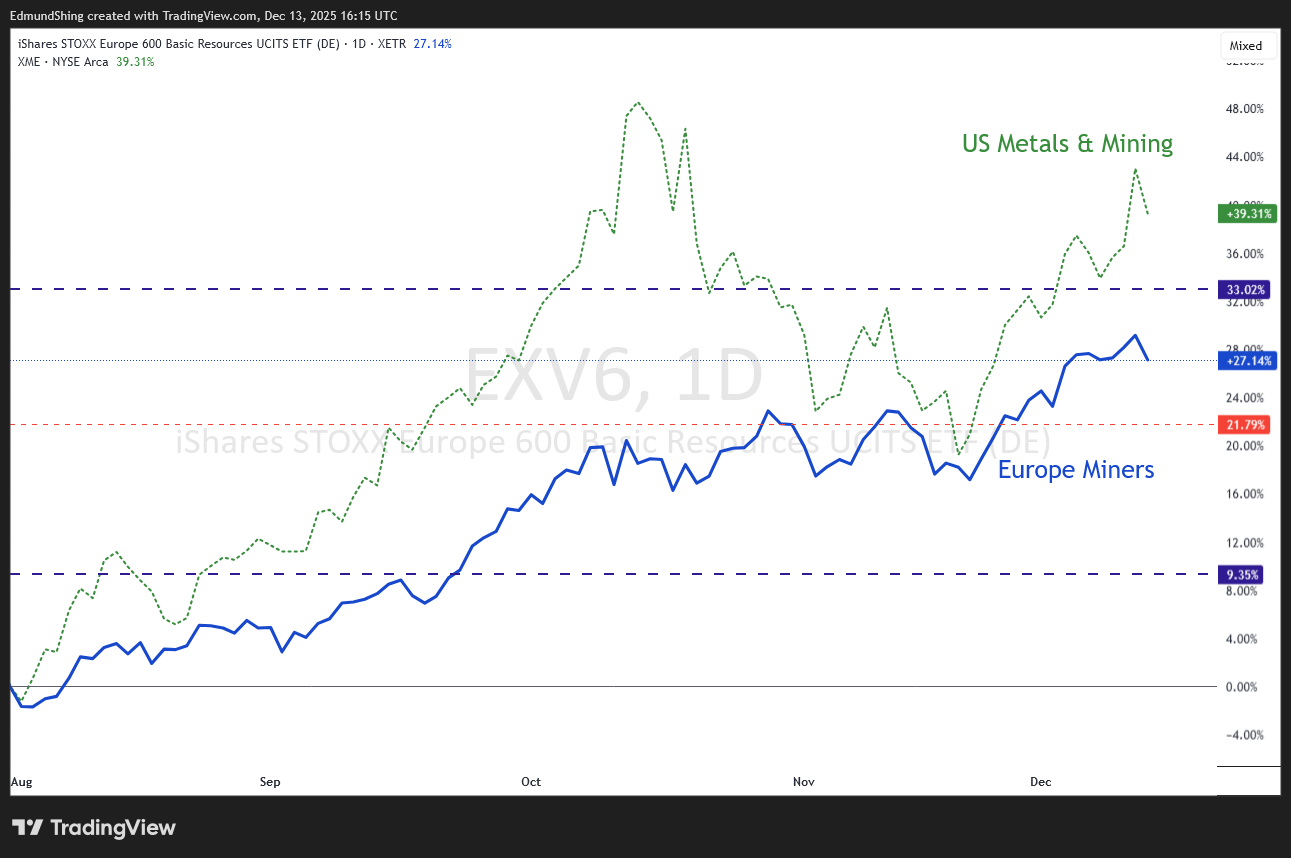
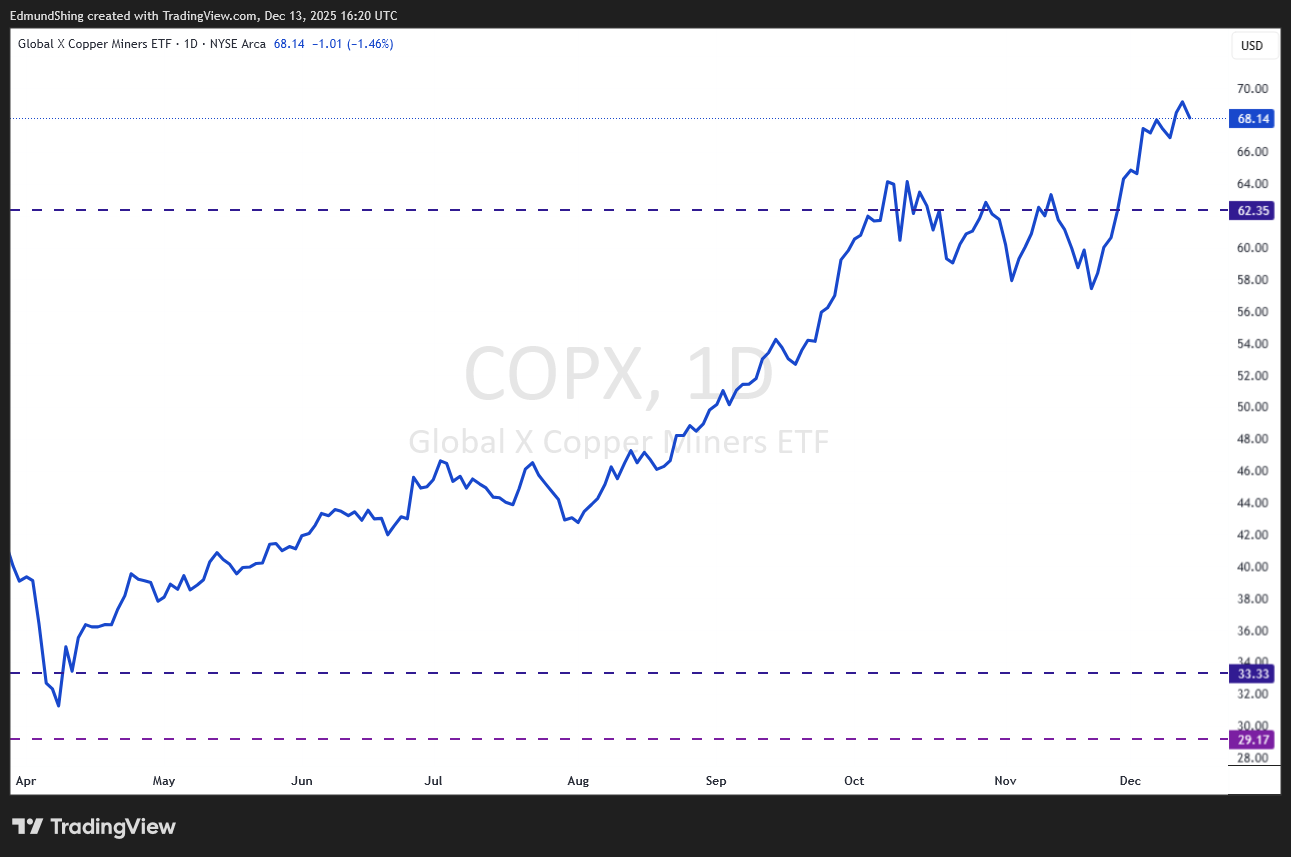
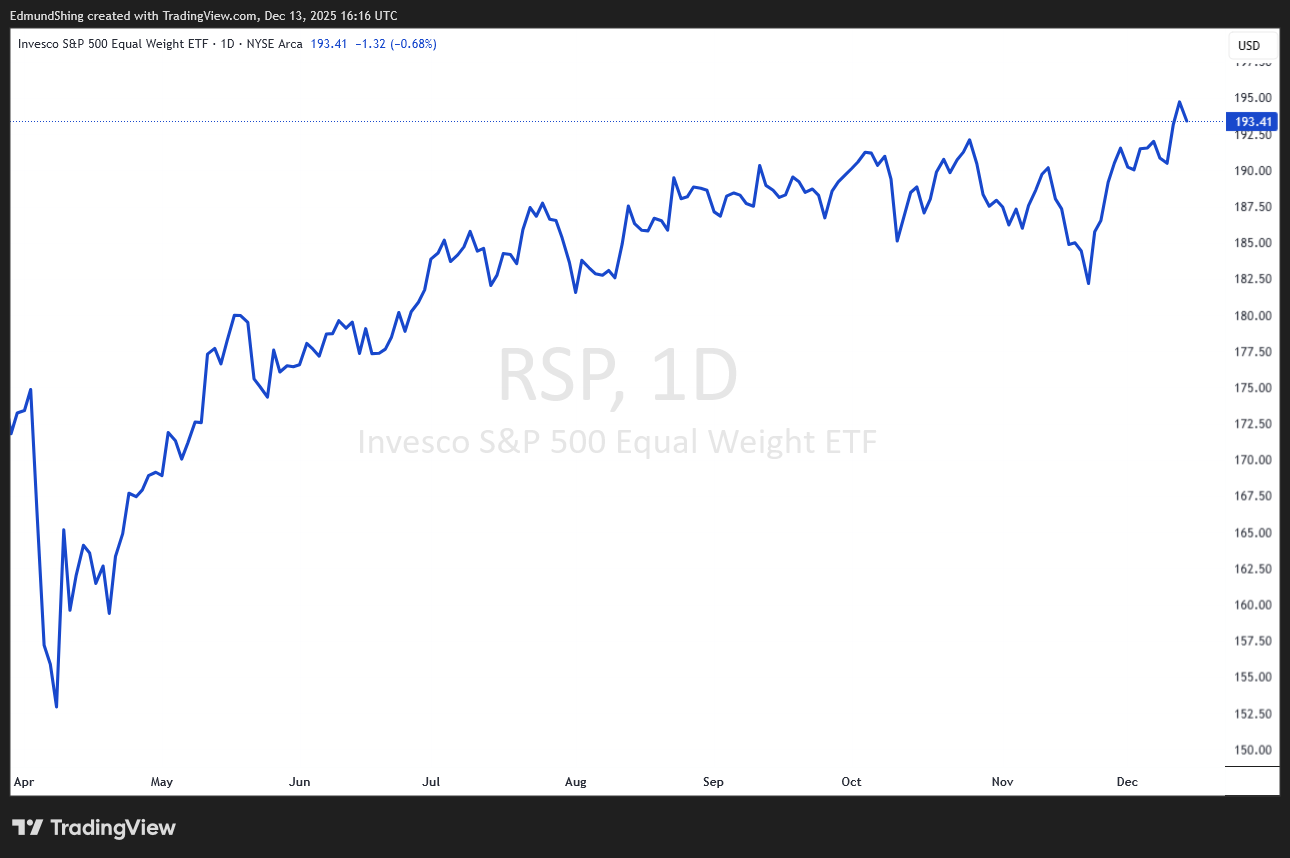
The strongest recent momentum over the last few months in stock markets and sectors can be seen in a few areas, including European Value (e.g. Banks), global mining stocks including copper miners and the equal-weight S&P 500 index (which does not have an over-sized weighting in tech stocks).
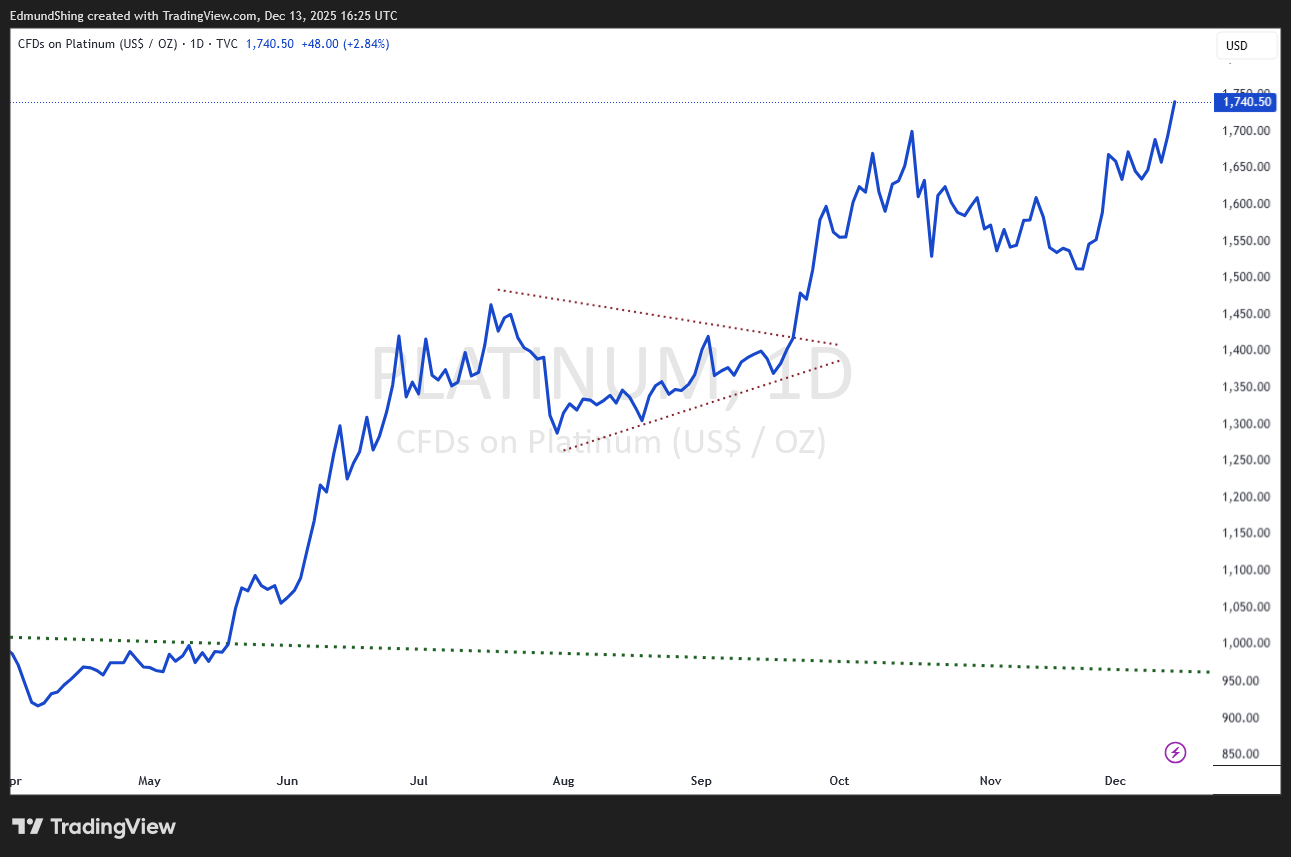
In commodities, while silver is grabbing the headlines with a new all-time high well over $60/ounce, watch the smaller precious metals markets of platinum and palladium. These metals are also breaking new multi-year highs.
1. European Value stocks (including Banks)
IEVL iShares European value ETF
2. European and US Mining stocks
EXV6 STOXX Europe Basic Resources ETF
3. Copper Miners
COPG Global X Copper Miners ETF
4. Equal-weight US S&P 500 index
EWSP iShares S&P 500 Equal Weight ETF
5. Physical Platinum
SPLT iShares Physical Platinum ETC
have a great week
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
Really appreciate your insights and the strategic approach that follows. One contrary thought I have been pondering is the attractiveness of the US market on a say 3 year view.
As the dollar is weak currently we are able to buy US assets at a more favourable exchange rate than for a few years. This may well become more favourable and is clearly a risk factor. But is there enough value there now?
For all his faults and bluster the Orange idiot has made a lot of businesses think twice, and make significant promises, about investment in the US. At what point will we see that come to fruition?
US exports will also be more competitive in world markets, even if not welcomed by their alienated friends and allies. Will commercial reality prevail? Removal of US alcohol from Canadian shelves is perhaps an example at the extreme end of that range. Threats of more and tougher sanctions might reverse such actions.
Businesses like GSK (LON:GSK) and AstraZeneca (LON:AZN) have promised significant spend and have estimated something like 50% (I think I remember that correctly) of their revenues are US based. Makes every sense to match production to market need at least on a continental basis surely? Tariff impact will drop out of the US inflation numbers at some point mid next year on and the investments start to kick in. Providing there isn't a complete breakdown of public order and confidence before that could it be the start of a significant upturn for the US economy? And that's without the AI and tech lead that the US has over most of the rest of the world.
Not something I welcome but trying to put my biases to one side! On the other hand I am also determined not to judge all Americans by the behaviour and actions of their political elite.
Thanks Edmund, great post. It’s very helpful providing ideas to set up a portfolio for 2026. Merry Christmas.
UK last ten trading days, on average. So from Tues 16th, possibly
Well looks like today!
Great post and fantastic video's, thank you Edmund. Have a great Christmas
Thanks again Edmund, very useful. Merry Christmas and prosperous 2026.
Thanks Edmund for all of your insightful posts this year. They have added real value to my own investing.
Thanks Edmund - some really useful ideas for 2026 to get the thinking cap on for further research. Have a great Xmas & New Year.