Market Musings 171026: Boring is BACK

Market Musings 171026: Boring is BACK
Summary:
1. Bond now offer the best yields in many years.
2. Despite US inflation above expectations, US bond prices unexpectedly rose.
3. Energy prices remain the key focus for inflation, Brent crude oil finished the week higher. But chances are that energy prices will be substantially lower in 12 months.
4. Stocks ease further lower on average, Tech cooling but more defensive sectors like Health care, Food & Beverages and Utilities rallying.
4. The US dollar may have peaked, and could follow bond yields lower. This could be better for gold.
5. Suggestion for research: World Health care ETF
Podcasts this week:
US midterm elections: Gridlock favours the bull. (click on link to lsiten)
- The 2026 midterms could reshape the balance of power in Washington, with control of both the House and Senate in play and prediction markets currently favouring a Democratic-leaning outcome.
- Three scenarios are possible, each with different market implications. Republican control would likely favour a looser regulatory and fiscal environment, while a blue wave (Democratic control of both the House and Senate) could benefit sectors such as healthcare and clean energy.
- Divided government and political gridlock may be the most likely outcome. This could limit major domestic policy changes without fundamentally reversing the direction of the Trump administration, particularly on foreign policy.
- Gridlock is not typically bad news for investors. Historically, US equities have performed well under a divided government, while the period following midterm elections has also tended to be supportive for stocks.
- We remain constructive on US equities. Strong earnings growth and continued AI investment should remain very supportive.
Diesel markets (click on link to listen)
- The US-Iran war-induced energy shock has turned into a refined products shock. The premium for a refined product, such as diesel, is now nearly as high as the price of crude oil itself.
- The Good. Europe still has close to 390 million barrels of diesel inventories, more than 60 days of final demand. This volume far exceeds that of the US or Asia.
- The Bad. Net exports of refined products from the Middle East remain well below 50% of pre-war levels. Moreover, net gasoil exports from the Middle East and Russia have dropped by 1.3 million barrels per day from a year ago.
- The Ugly. The cost to ship crude from the Middle East to Asia has increased tenfold since the start of the US-Iran war, squeezing refinery margins outside the Gulf and threatening global diesel supply.
- The Cavalry? The International Energy Agency pledged on 15 October to exceed the volume of oil stock releases agreed in March. They confirmed that over 20 million barrels of diesel would be released as soon as possible.
Investors are buying bonds now
Since at least 2022, the two financial markets that have provided the best returns have undoubtedly been Stocks and Commodities. But in the last few weeks, investors are rediscovering the benefits of buying bonds once again, for the first time in a very long time.
From 2008 until 2022, both short- and long-term interest rates remained very low as inflation rates persisted at 2% or lower, allowing central banks to keep rates low in order to stimulate the global economy in the aftermath of the seismic shock from the Global Financial Crisis (GFC).
ECB Eurozone deposit rate at or below zero 2009-2022
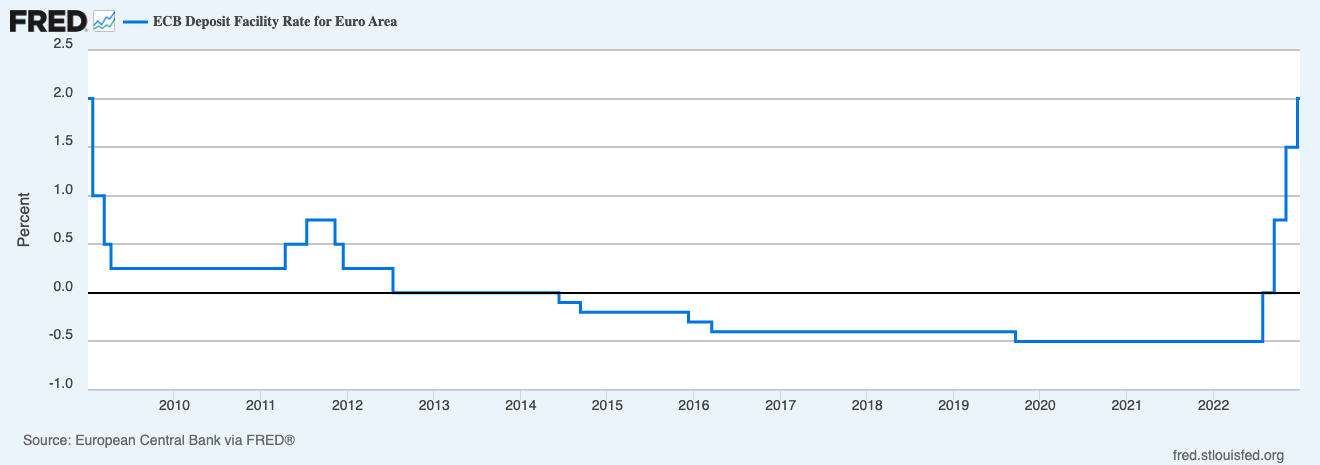
As an example, an investor buying a 10-year German government bond between 2014 and 2022 would have received an average bond yield of around 1%. The Euro area deposit rate, the key benchmark short-term interest rate set by the European Central Bank, was zero or even negative between 2013 and 2022. This was mirrored throughout the developed world, leaving investors with very few sources of relatively safe income
Today, a 10-year German government bond offers a yield of over 3%, while an equivalent US 10Y Treasury bond yields sits at over 5% and a UK 10Y gilt (government bond) yield is 5.4%. A sharp contrast to the post-GFC era...
UK v Italian v French 10-year government bond yields have all risen sharply
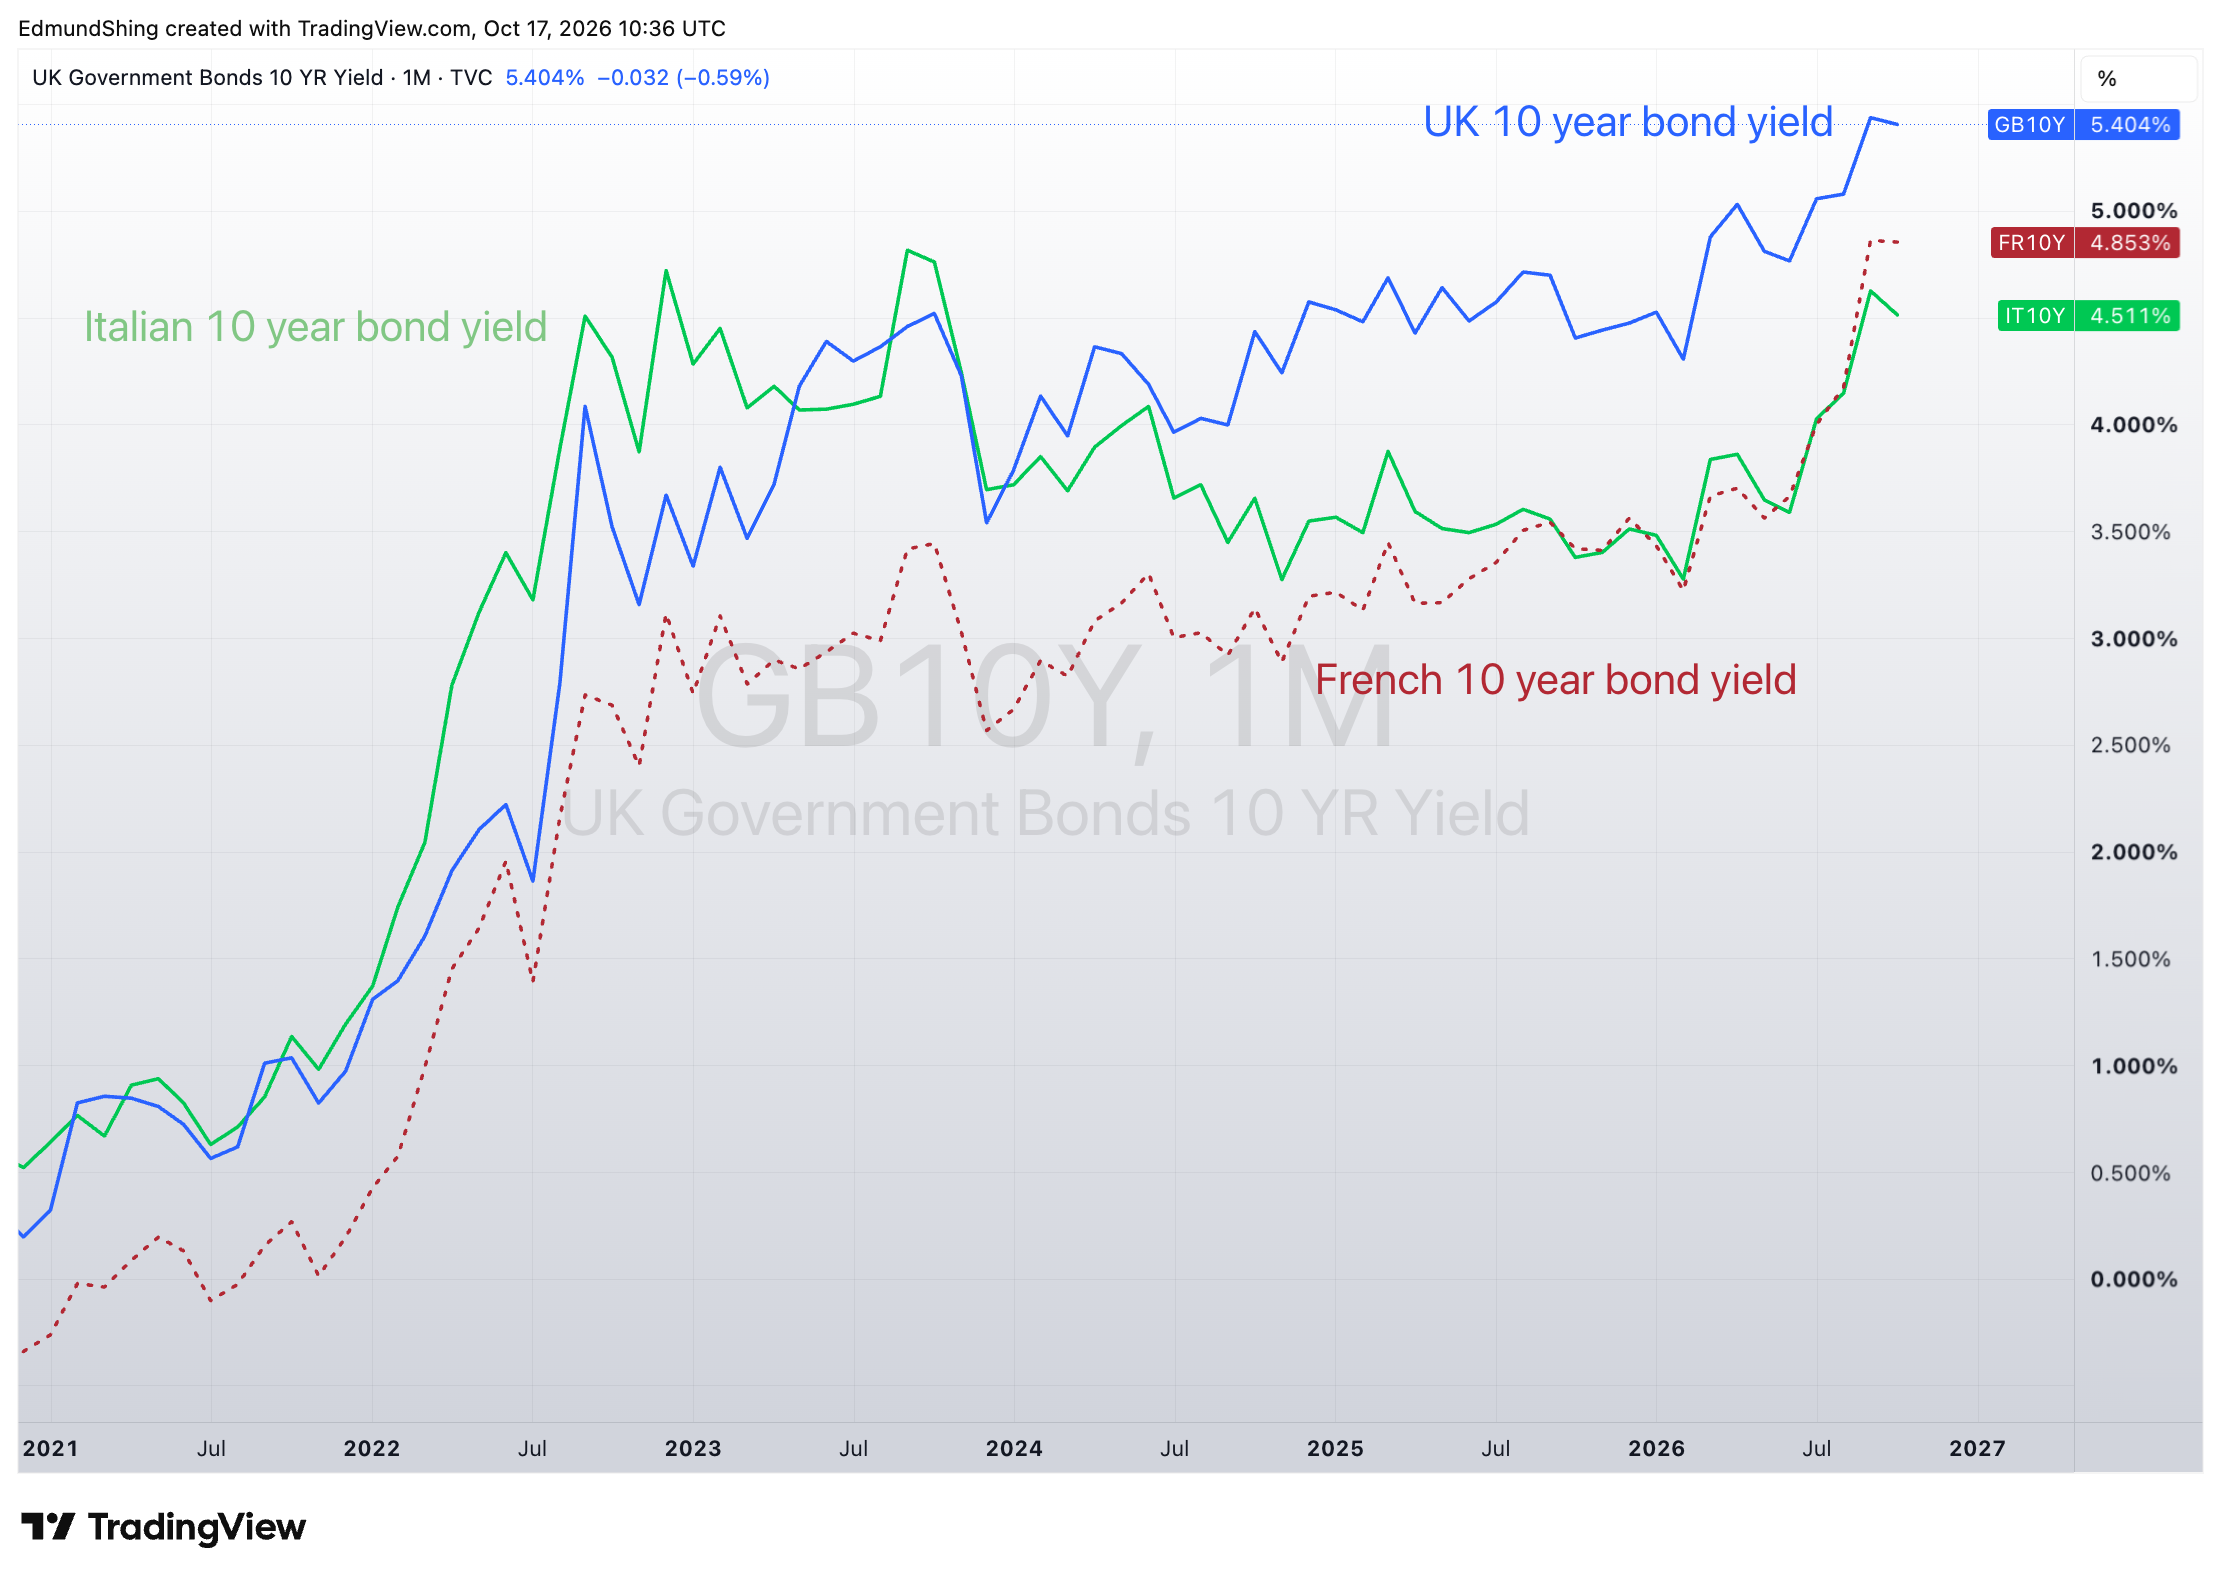
No surprise, then, that investors in the US and UK in particular are starting to warm to the attractions of money market funds and bonds, given the much more generous income yields now available.
In relatively safe investment-grade (i.e. high quality) corporate bonds (where investors lend money to companies rather than governments for a fixed length of time), yields have risen to over 6% in pounds sterling, nearly 6% in US dollars and 4.4% in euros. Of course, even higher yields can be achieved in riskier bonds...
At these yields, even if inflation stays at over 2% in the eurozone, and closer to 3% in the US and UK, investors can still earn an after-inflation (real) return of 2%-3% without needing to take much risk. That has not been true for a long time...
For investors sitting on a lot of cash in a low or even no-interest bearing bank account, I believe that the opportunity to generate a good level of interest income is compelling.
In the UK, you can achieved a 1-year fixed term interest rate of close to 5% in a deposit account if you shop around (e.g. Close Brothers via Hargreavess Lansdown). In France, a 1-year fixed term deposit account (*compte à terme*) from Boursobank offers 2.8%, well above the prevailing Livret A savings rate of 1.7%.
What it means is that today, there are good income-bearing alternatives to investing in stocks and property.
In Stock Markets, Defensive Sectors rally
For most of this year, and indeed for most of the last 4 years, stock markets have been dominated by (a) the AI trade and the Technology sector, and (b) Commodities and the Mining and Energy sectors.
MSCI World Technology and Energy sectors have more than doubled since 2022
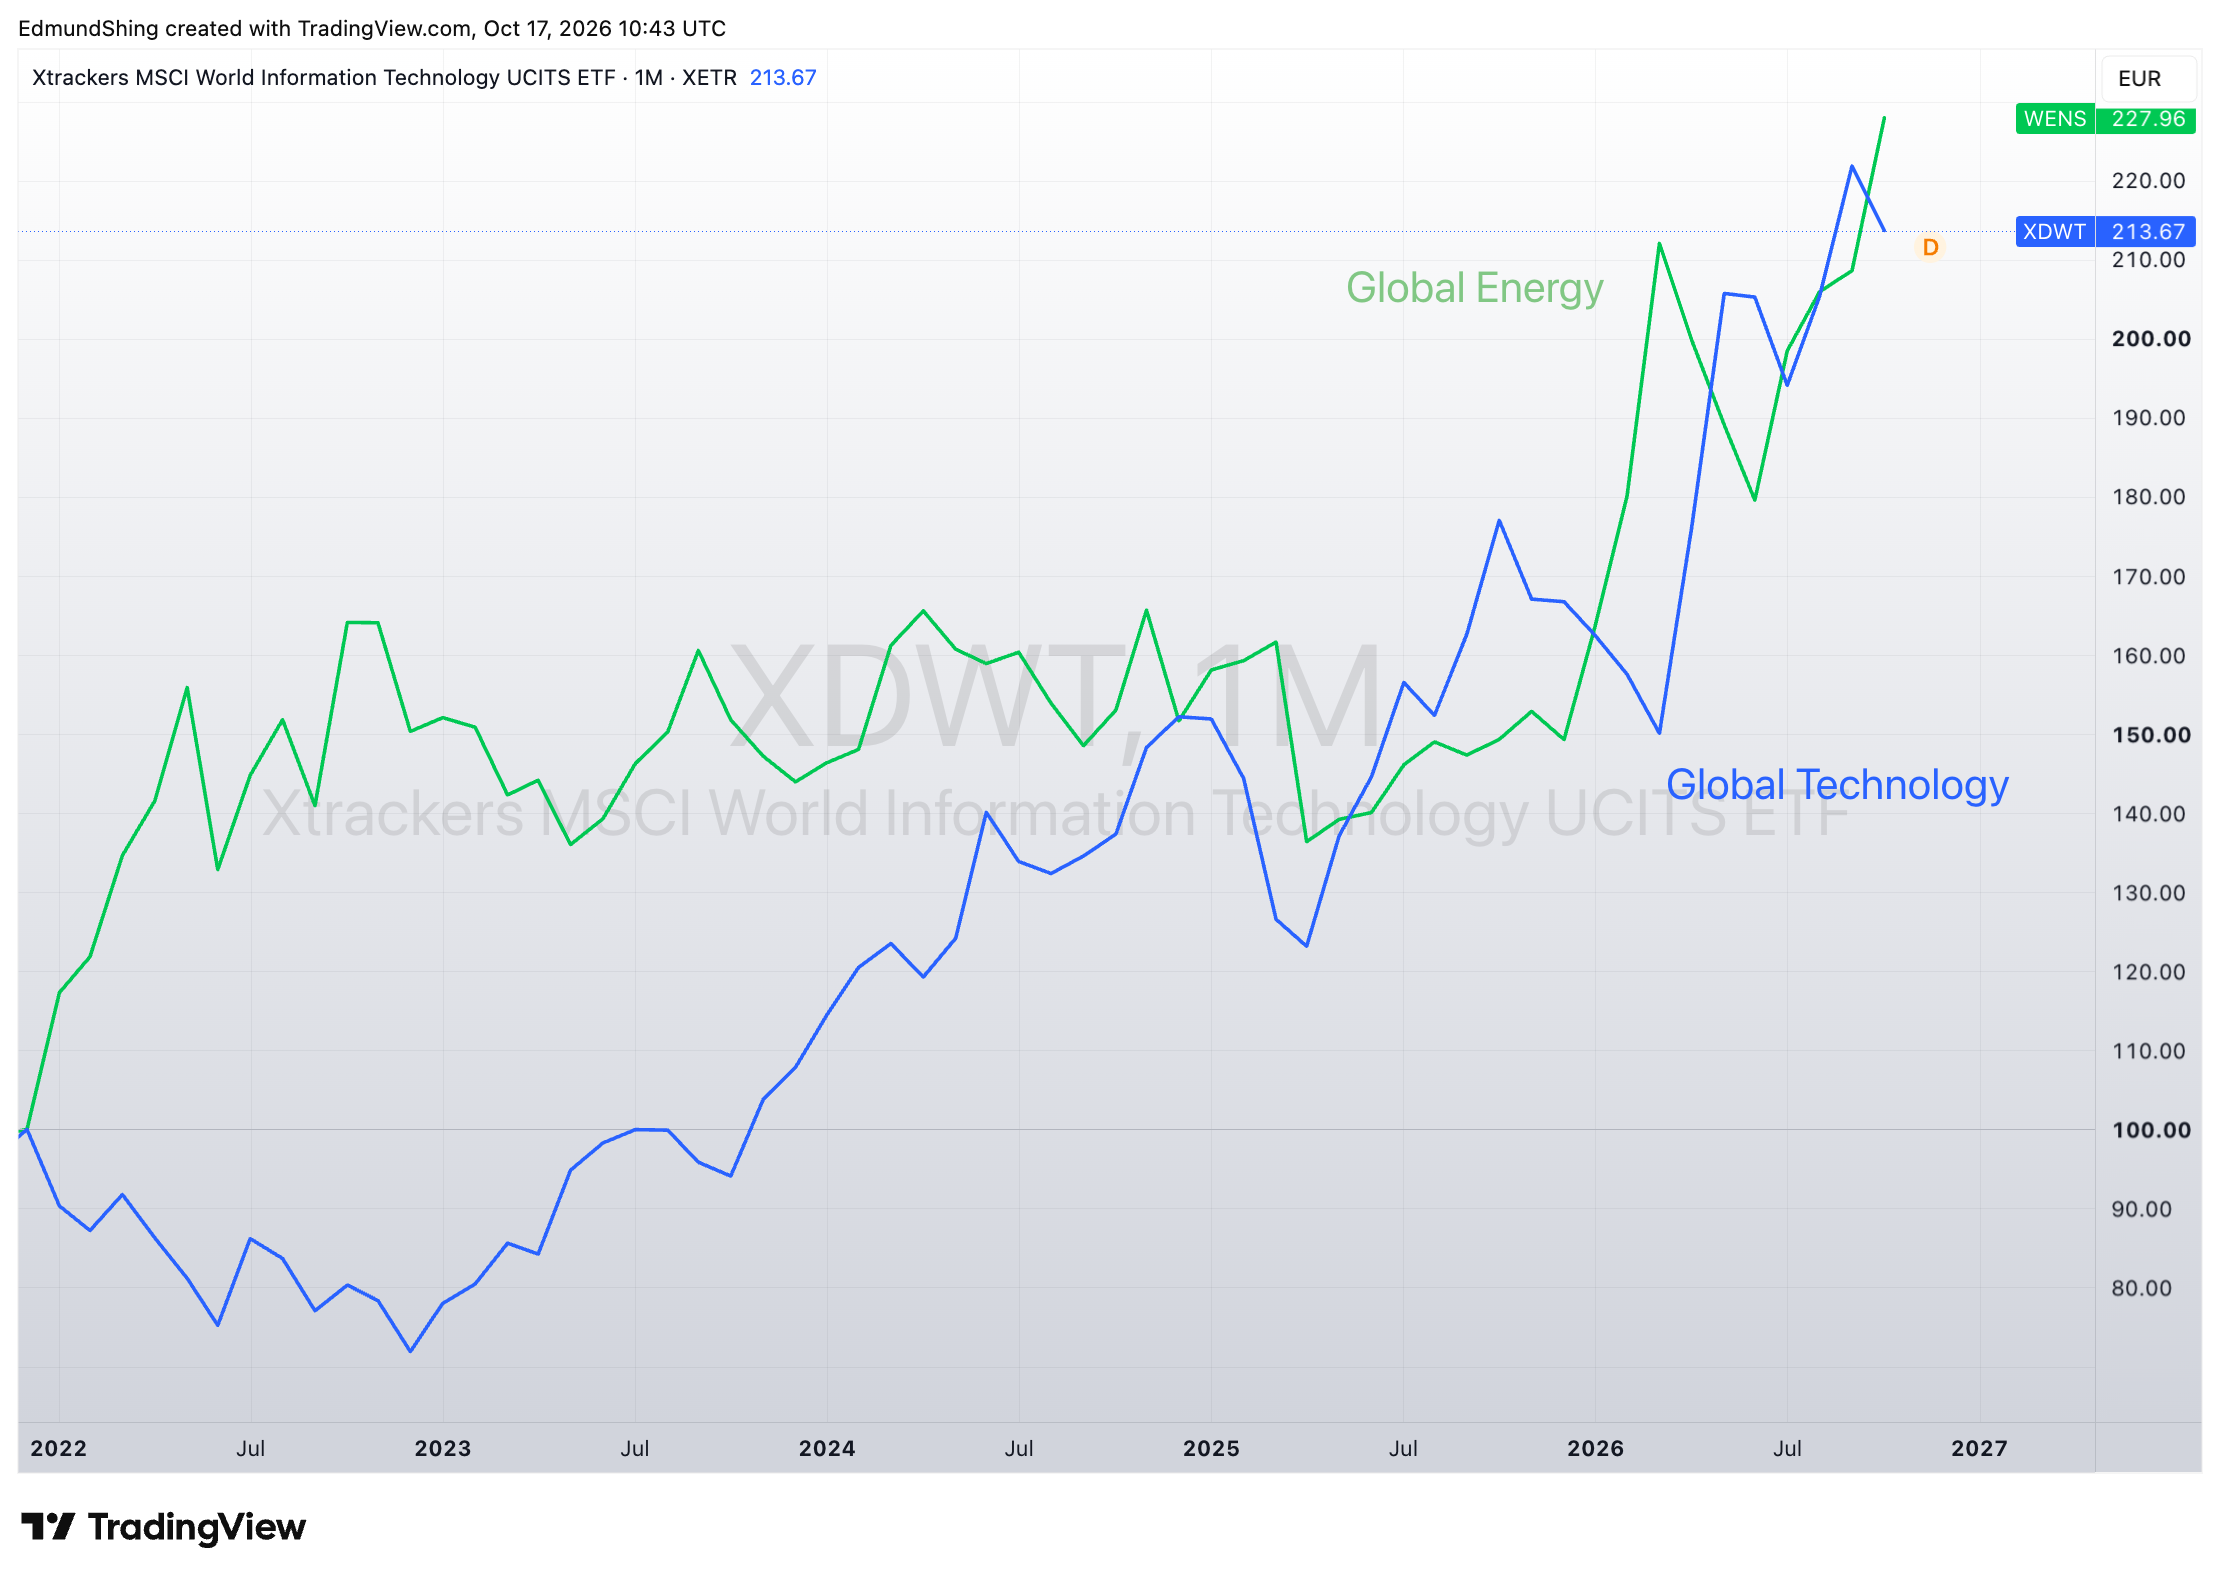
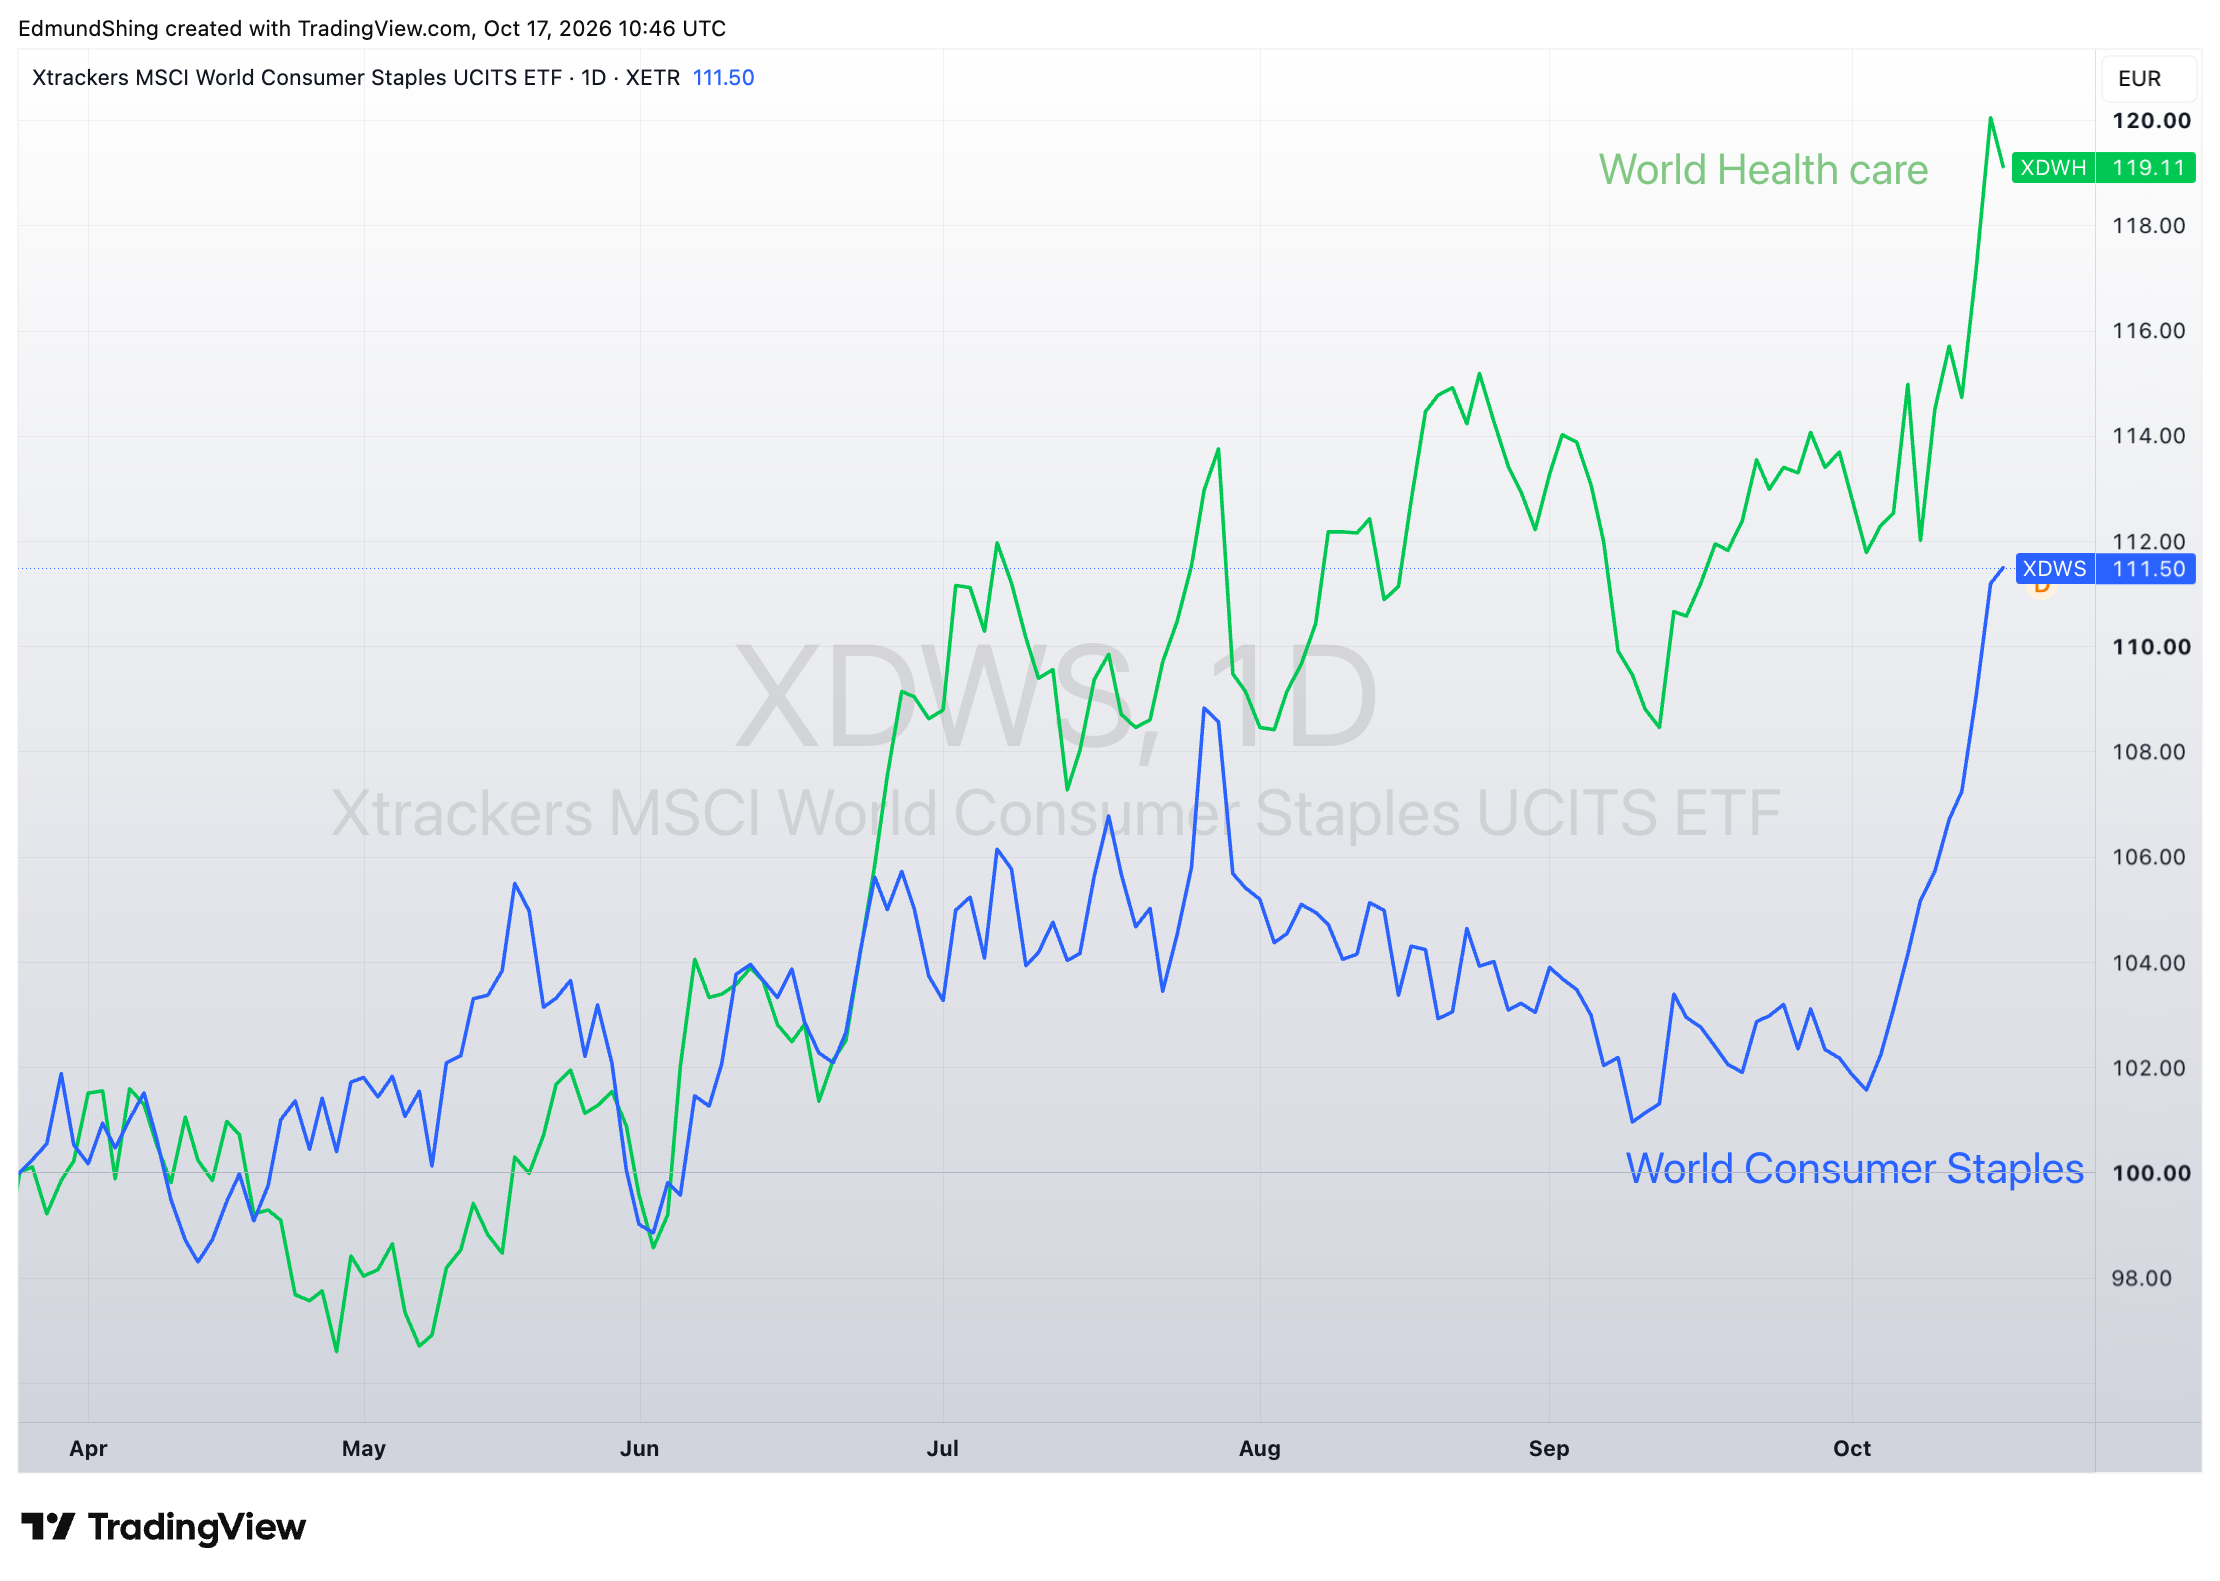
However, over the last month we have seen a marked rotation away from pro-growth technology stocks back towards previously out-of-favour defensive stocks in the Food & Beverages and Health care sectors.
World Consumer Staples (Food & Beverage) and Health care rally hard in October
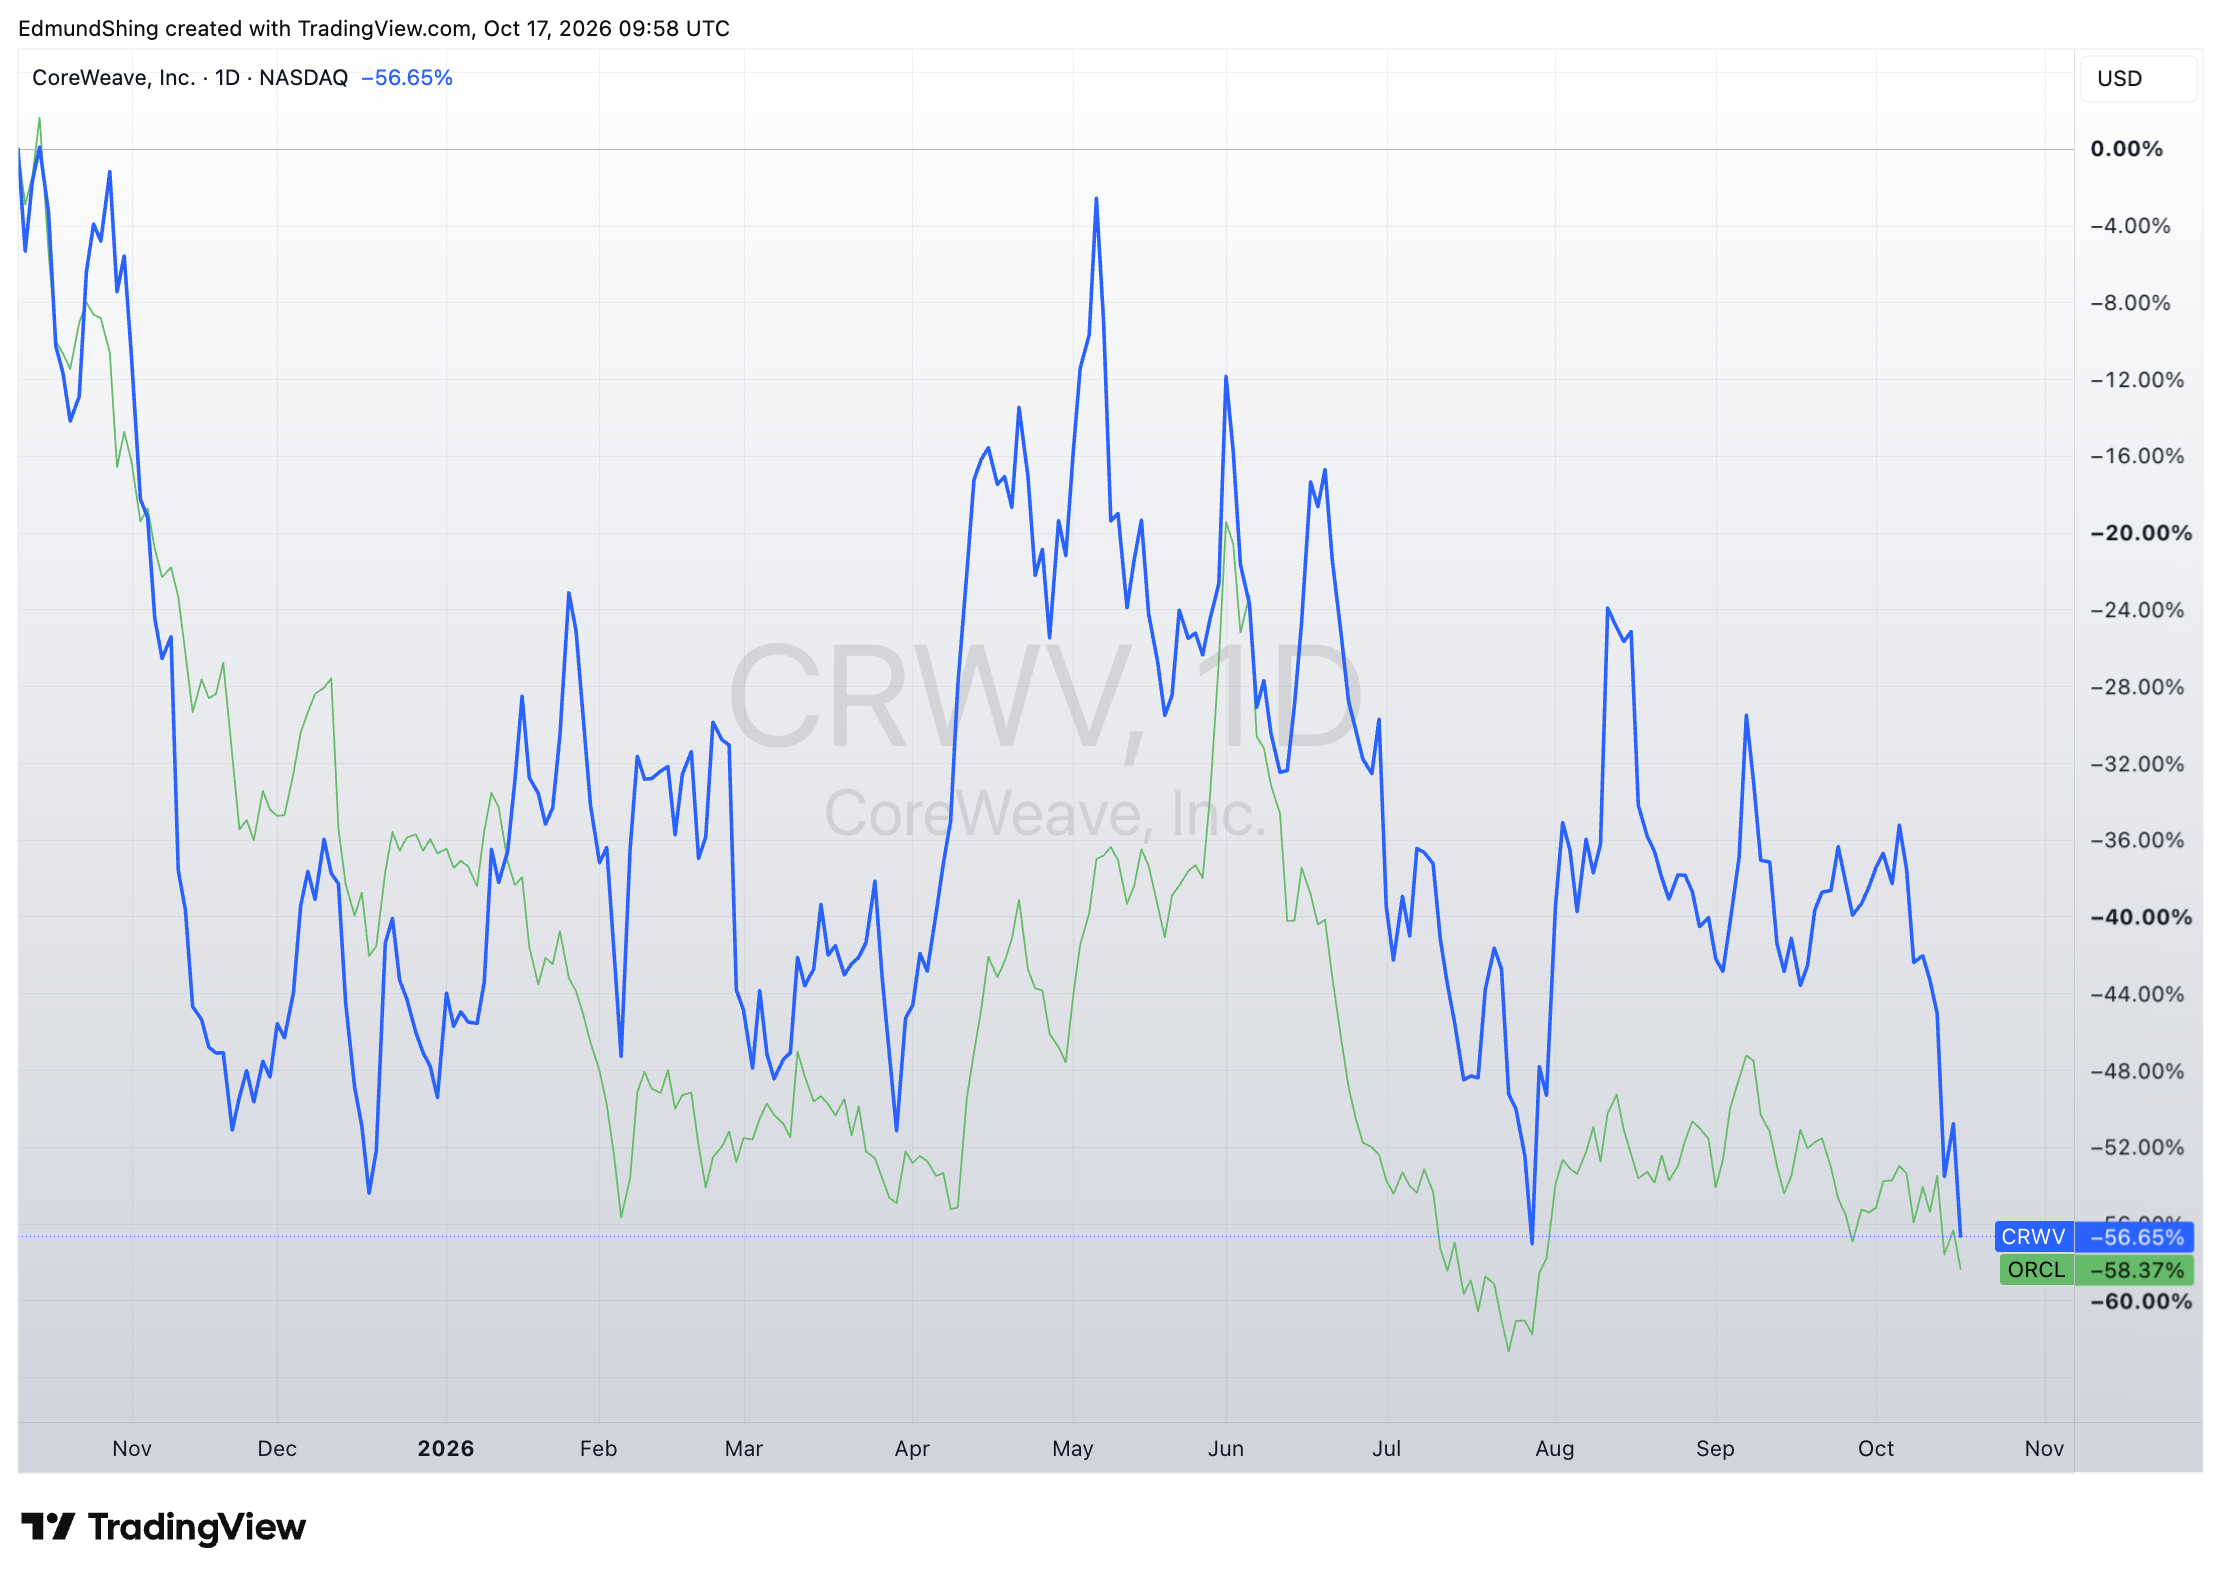
Given the performance of certain AI data centre-related stocks such as Oracle and Coreweave, we can see that doubt are creeping into parts of the AI theme. The stocks have bother fallen sharply from their late 2025 highs, while Coreweave bonds are now trading at a 15% yield, highlighting heightened risk perceived by investors. These concerns are also behind a rotation in the stock market towards more defensive, stable sectors.
Oracle (green) and Coreweave (blue) suffer since late 2025
Global Heath care is a sector that I continue to like for the long term, given the structural demand drivers of a rapidly ageing population in the US, Europe and Asia (China, South Korea and Japan) plus the kicker of productivity and growth gains to come from AI implementation in drug discovery and diagnostics. Note how the MSCI World Health care ETF has broken out to new highs in the past week.
But perhaps the most interesting rotation is into Food & Beverage stocks, that have been very out of favour for some time. In particular, alcoholic beverage stocks have been hit by the trend towards drinking less (GLP-1 related and also a structural decline in alcohol consumption in younger people), but are finally starting to pick up from the lows.
ETF of the week: MSCI Europe minimum volatility ETF
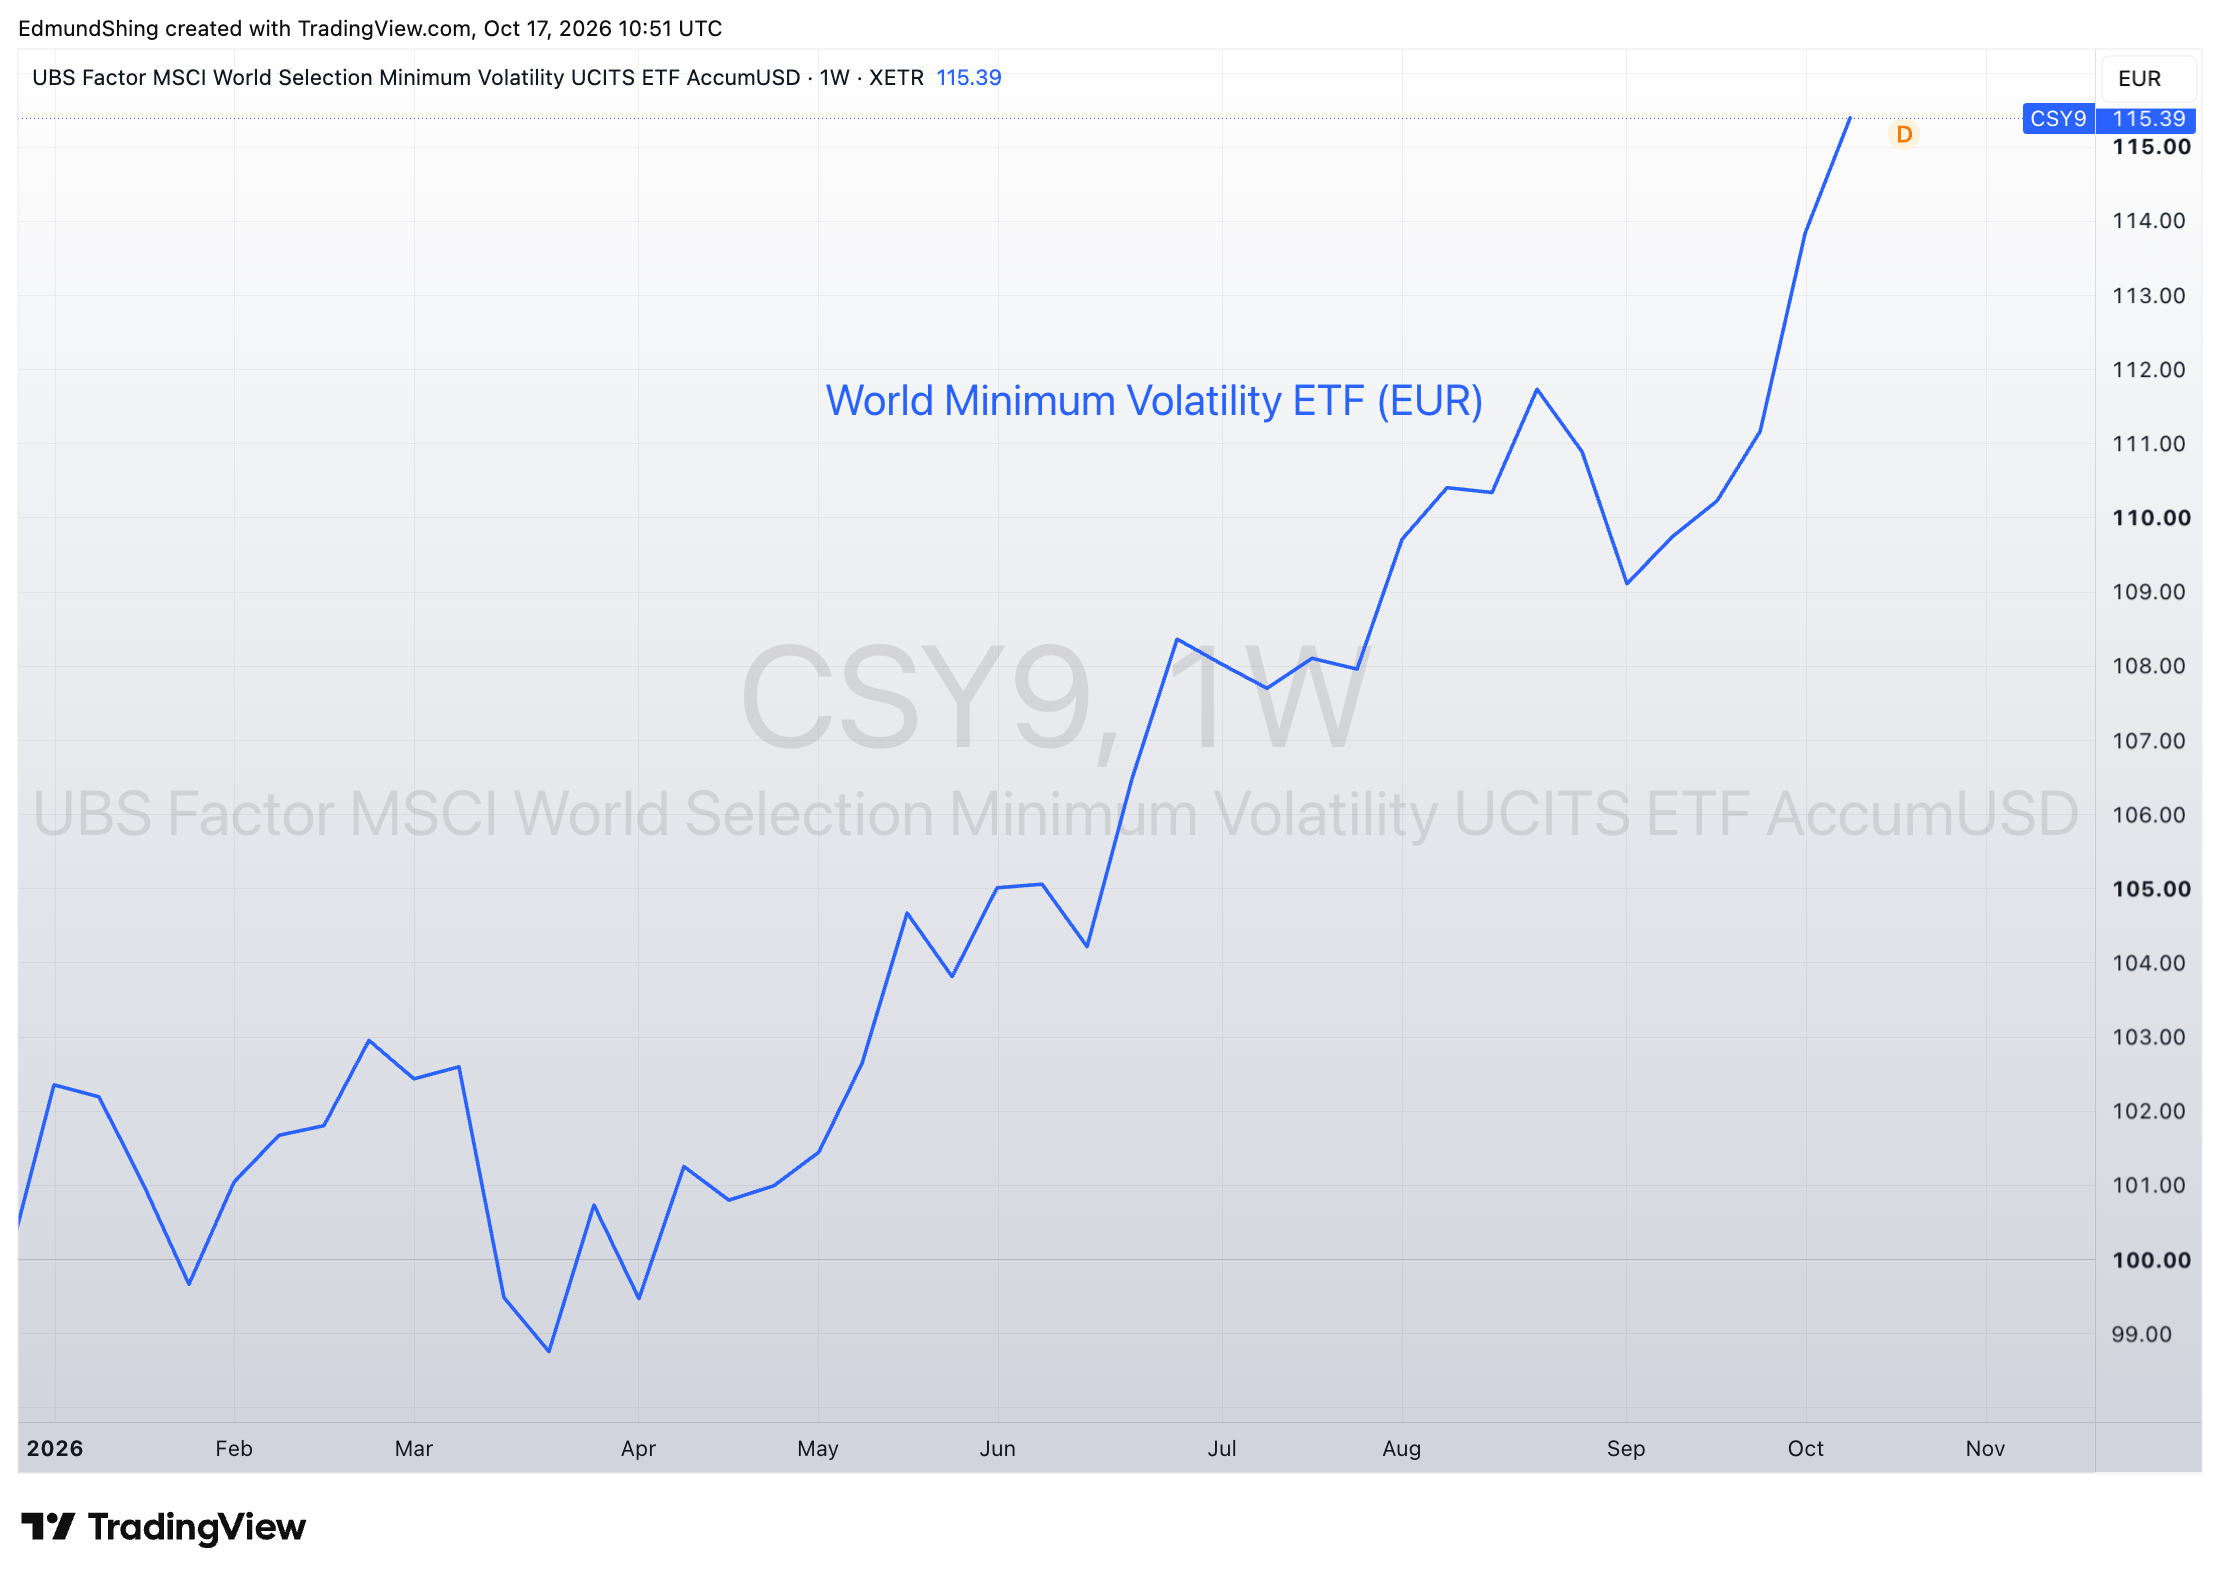
One easy way to capture this rotation back into more "boring", defensive stocks and sectors is via this World Minimum Volatility ETF, that favours global companies which are less volatile, thus holding more of the defensive stocks like Utilities, Health care and Food & Beverage, and less of the more growth-oriented stocks like Technology.
UBS MSCI World Minimum Volatility ETF +15% (in EUR) year to date
Hve a great week ahead,
\Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

5 comments
SLXX current yeild 6.19%
The kids and the losers want a life - reduce the losers and need to support those that want a life. It's not rocket science.
...even if inflation stays at over 2% in the eurozone, and closer to 3% in the US and UK..
...does Edmund subscribe to the theory that the authorities conveniently omit items that have risen in price in their inflation calculations in order to hide the fact that the inflation rate is much higher ?
Pension Funds and Insurance companies are obliged to buy bonds and even banks have to hold reserves that are probably declining in real value.
Retail investors do not have to. Those who find 'safety' in a bond are ignoring the fact that the purchasing power of their capital repayment will depreciate, especially if they hold it to maturity.
OK equity markets will sell off as interest rates rise so they will face losses there too.
'Income' investing is perilous, partly because seen as a way to preserve capital.
Ed's suggestion to 'park' profits from a rising market in Money Market and other vehicles has been headed.
Inflated values versus Inflation is a conundrum, however.
There is or was an opportunity in Trading long bonds.
Apparently statistics show that a sharp spike in bond yields, such as we have just seen, has never been sustained over a two year period.
Anyone who bought TLT (US 20+ years long bond ETF) on Oct 7 has done well.
Is there more to come ?
Short term resistance at 82$. Will the Gap-up fill downwards at 78$ short term ?
Long term resistance at 84$ because prior support (hence Blue line).
Pleased to see you back Emund! Now to read your musings.