Market Musings 221125: H1 2026 Outlook

Outlook H1 2026
Weekly Podcast and Snapshot: Cooling of investors over-optimism
(click on title to access link)
Following the strong momentum led by technology stocks in the US and in Asia, concerns rose over the elevated valuations that tech stocks had reached.
Over the last week, a mini correction was seen, sending among others bitcoin down by 29% and tech giant Oracle by 34% from its September highs. This setback of global and US stocks should not worry investors as the Nasdaq 100 index has merely returned to the level it had reached in early October.
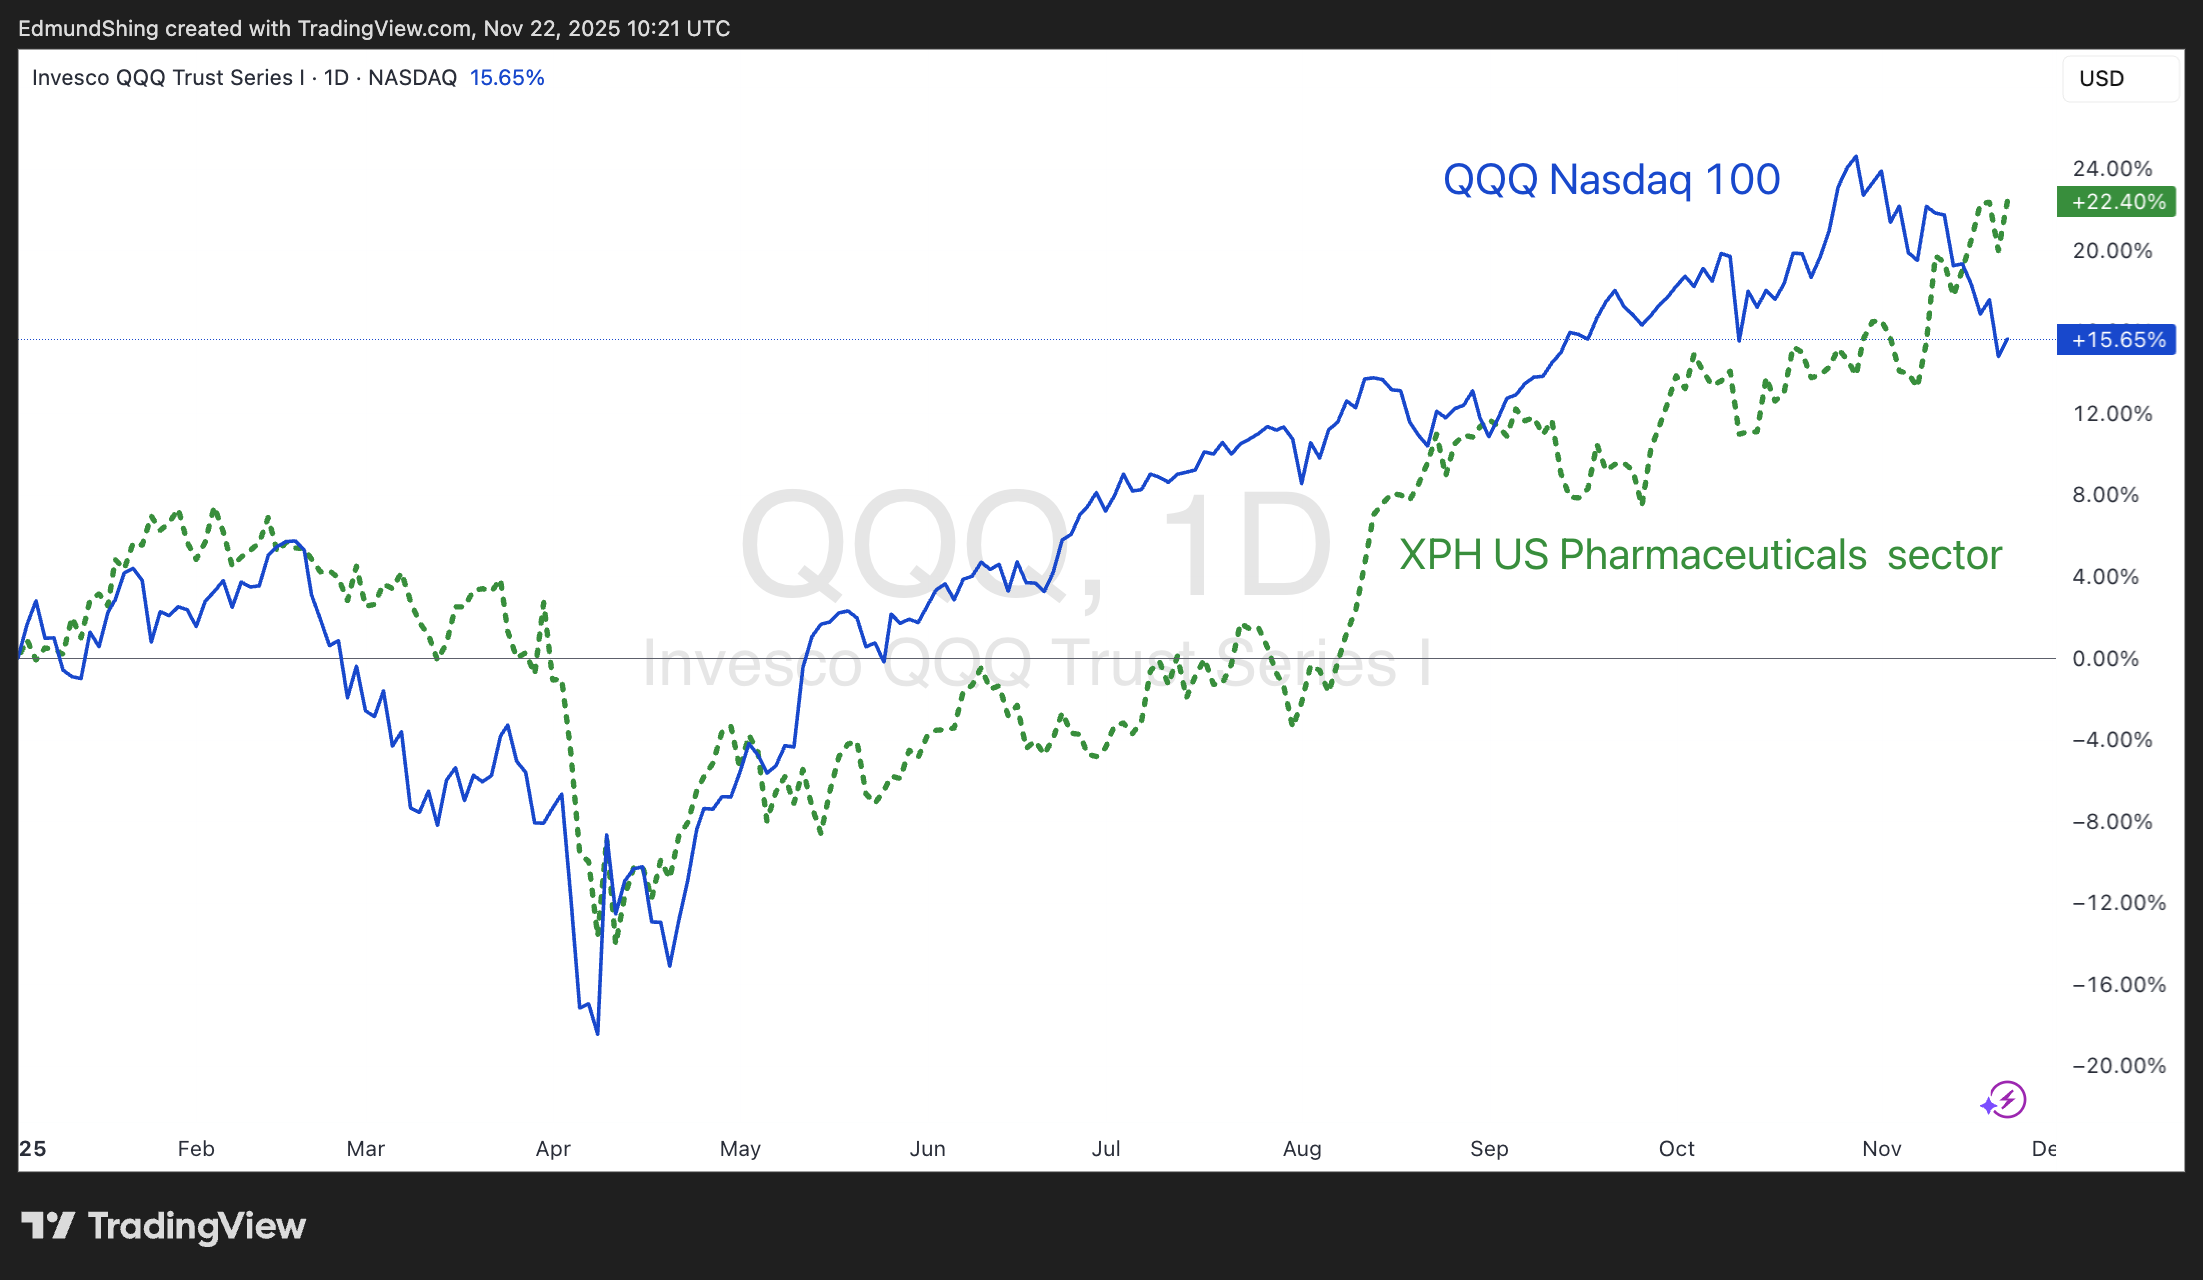
However, while more speculative names and the tech sector stumble, other sectors are taking over leadership of the global stock market. Pharmaceutical & biotech sectors are lately outperforming the Nasdaq Index. Another more surprising outperforming industry in November is Oil & Gas.
We maintain our positive 12-month view on global stocks and would suggest that now is a good time to look at sectors and stocks displaying relative strength outside of technology.
5 themes for H1 2026
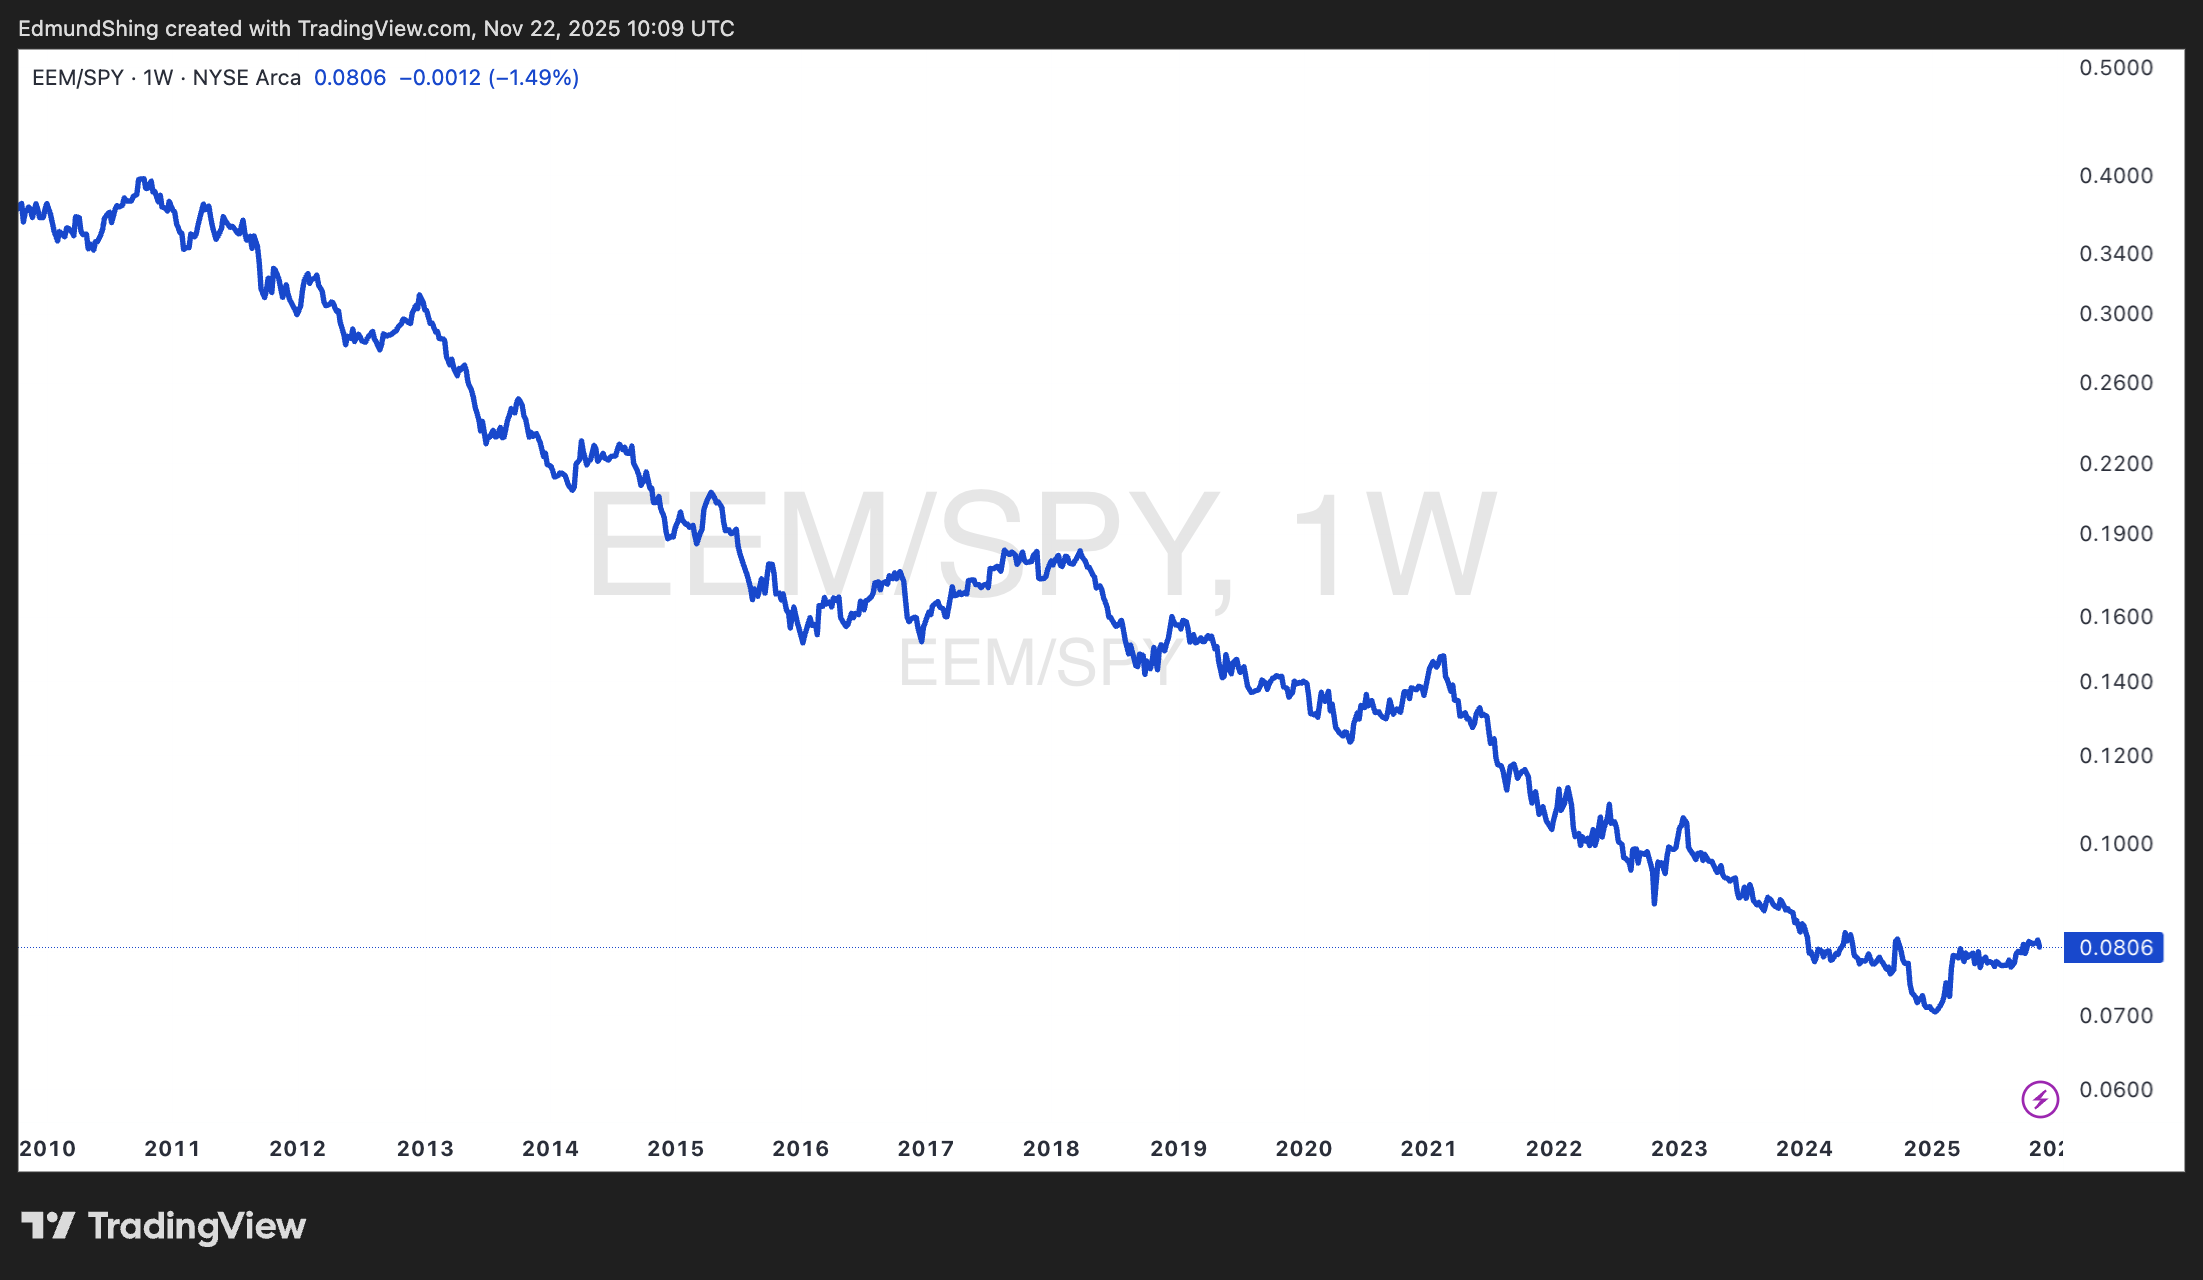
Emerging market stocks to rebound further versus US on weaker USD, cheap valuation, lower interest rates, improving earnings. China to benefit from further government stimulus, ultra-low short- and long-term interest rates, retail fund flows into stock markets. Brazil and Mexico should see strength from interest rate cuts, strong domestic currencies, benefits from higher commodity prices and increased oil production.
Global tech arms race: competition between the US and China in AI and other related technologies ensures increasing investment in AI and data centres globally, not necessarily in the interests of shareholders. Governments to strategically support domestic industries via selective investment, a loose regulatory regime and via accelerated tax write-offs on investment. Accelerates take-up of AI outside of tech, benefiting early AI adopters in sectors such as financial services, health care and professional services. A potential negative for employment growth given near-term pressure on white collar jobs.
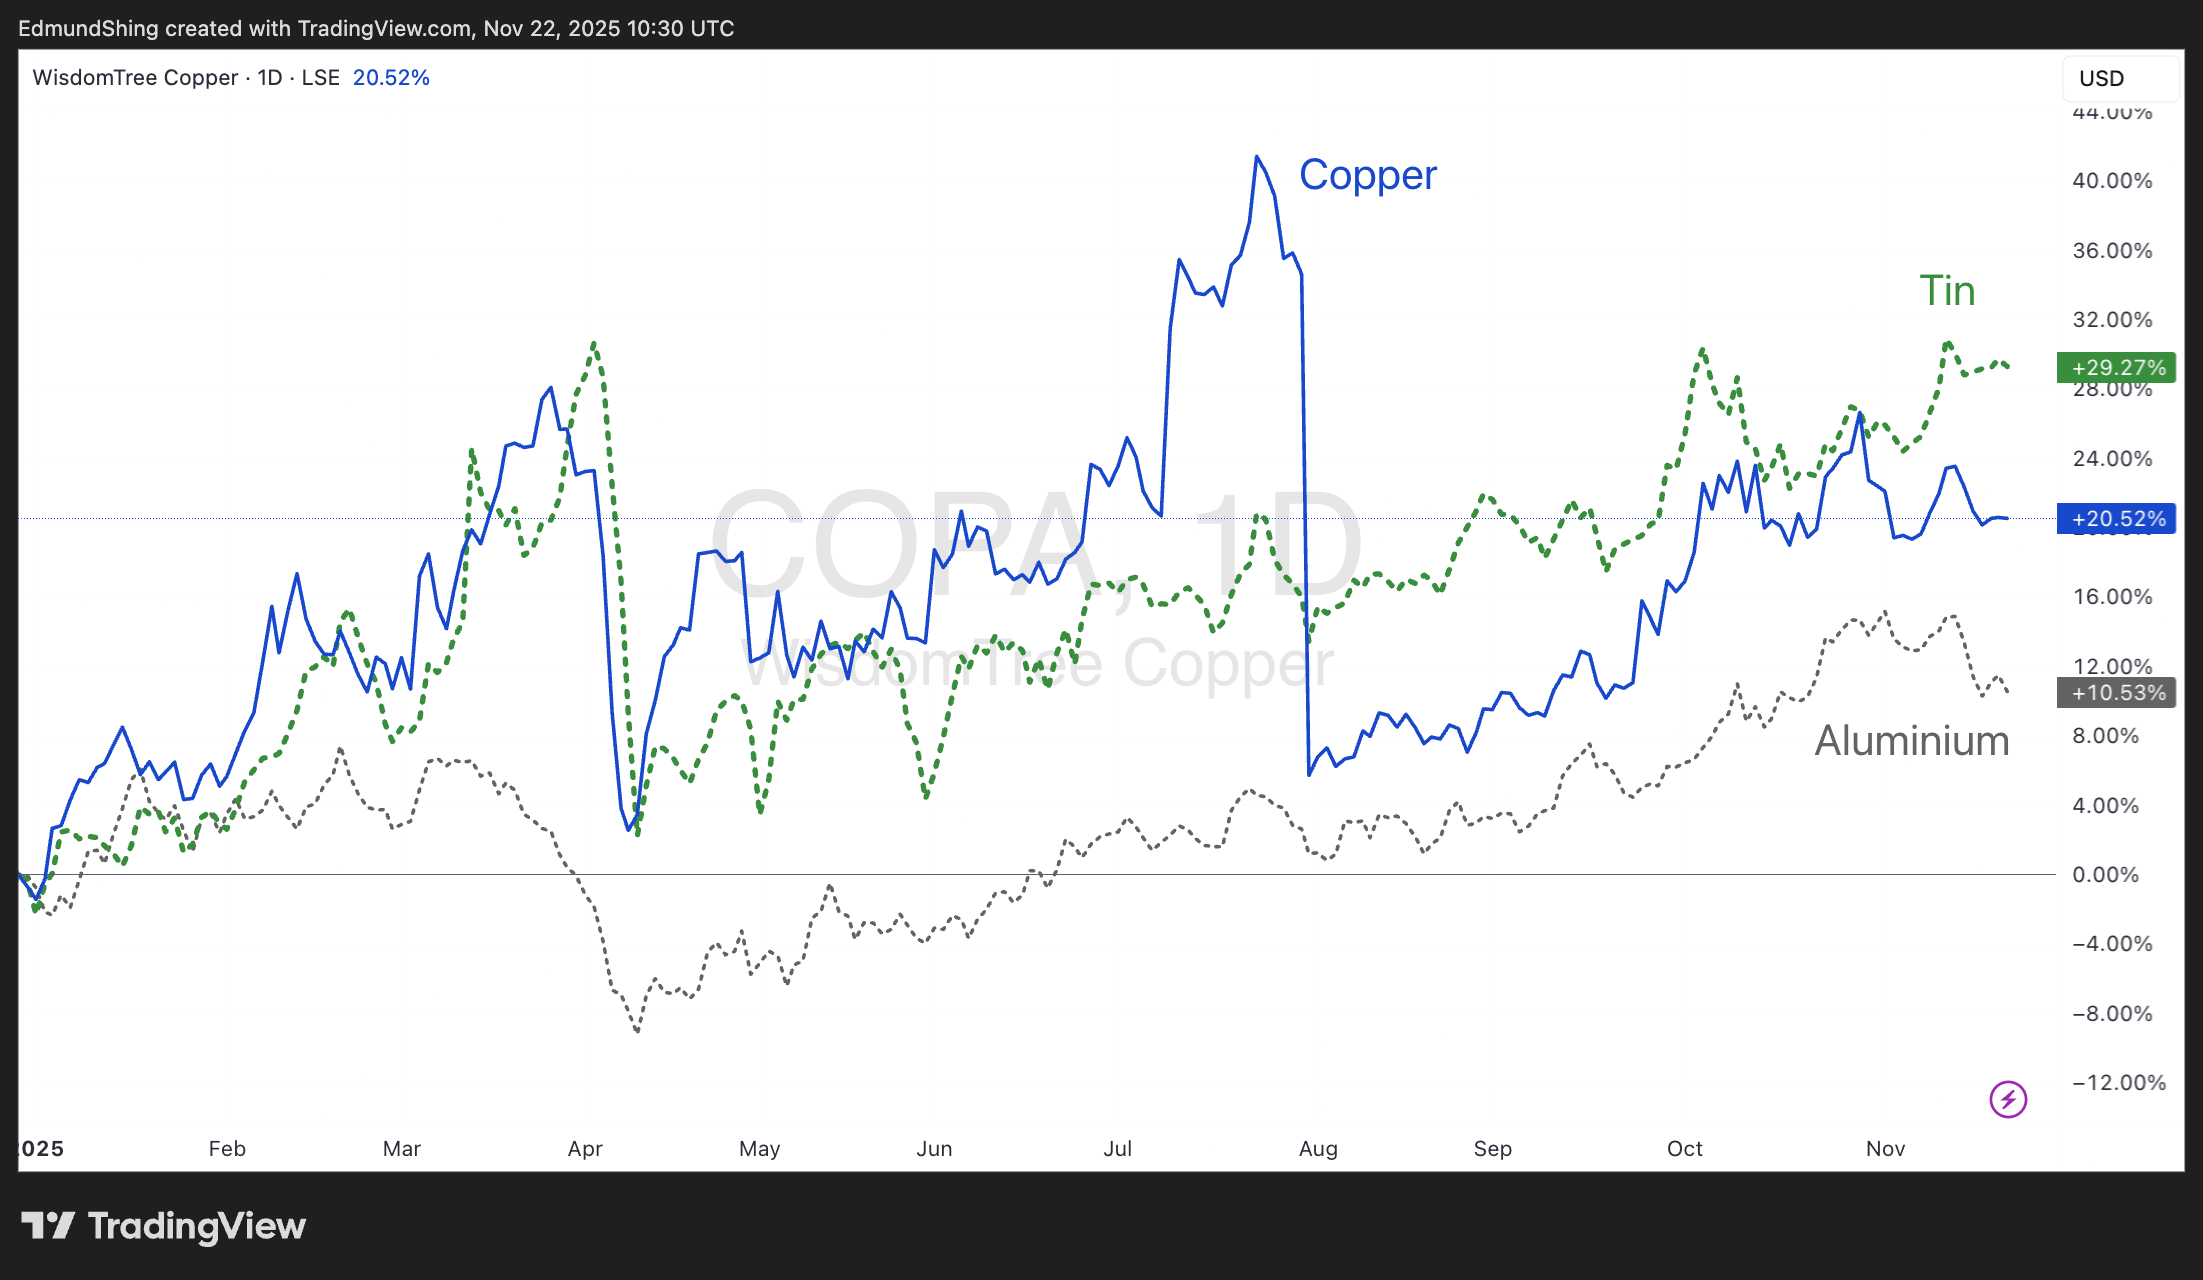
Commodities to rise further, led by precious metals, strategic metals (copper, aluminium, tin, zinc, rare earth), natural gas and uranium in energy. Driven by growing demand, limited supply growth, geopolitical pressures, energy security and de-globalisation trends limiting export of key strategic metals and minerals.
Government stimulus to boost growth: German/EU defence and infrastructure spending to increase in 2026, China to support property market and domestic consumption further (involution campaign) via further measures, the US to look to support the consumer via targeted tax cuts before the mid-term elections. Favour European strategic autonomy theme, listed infrastructure.
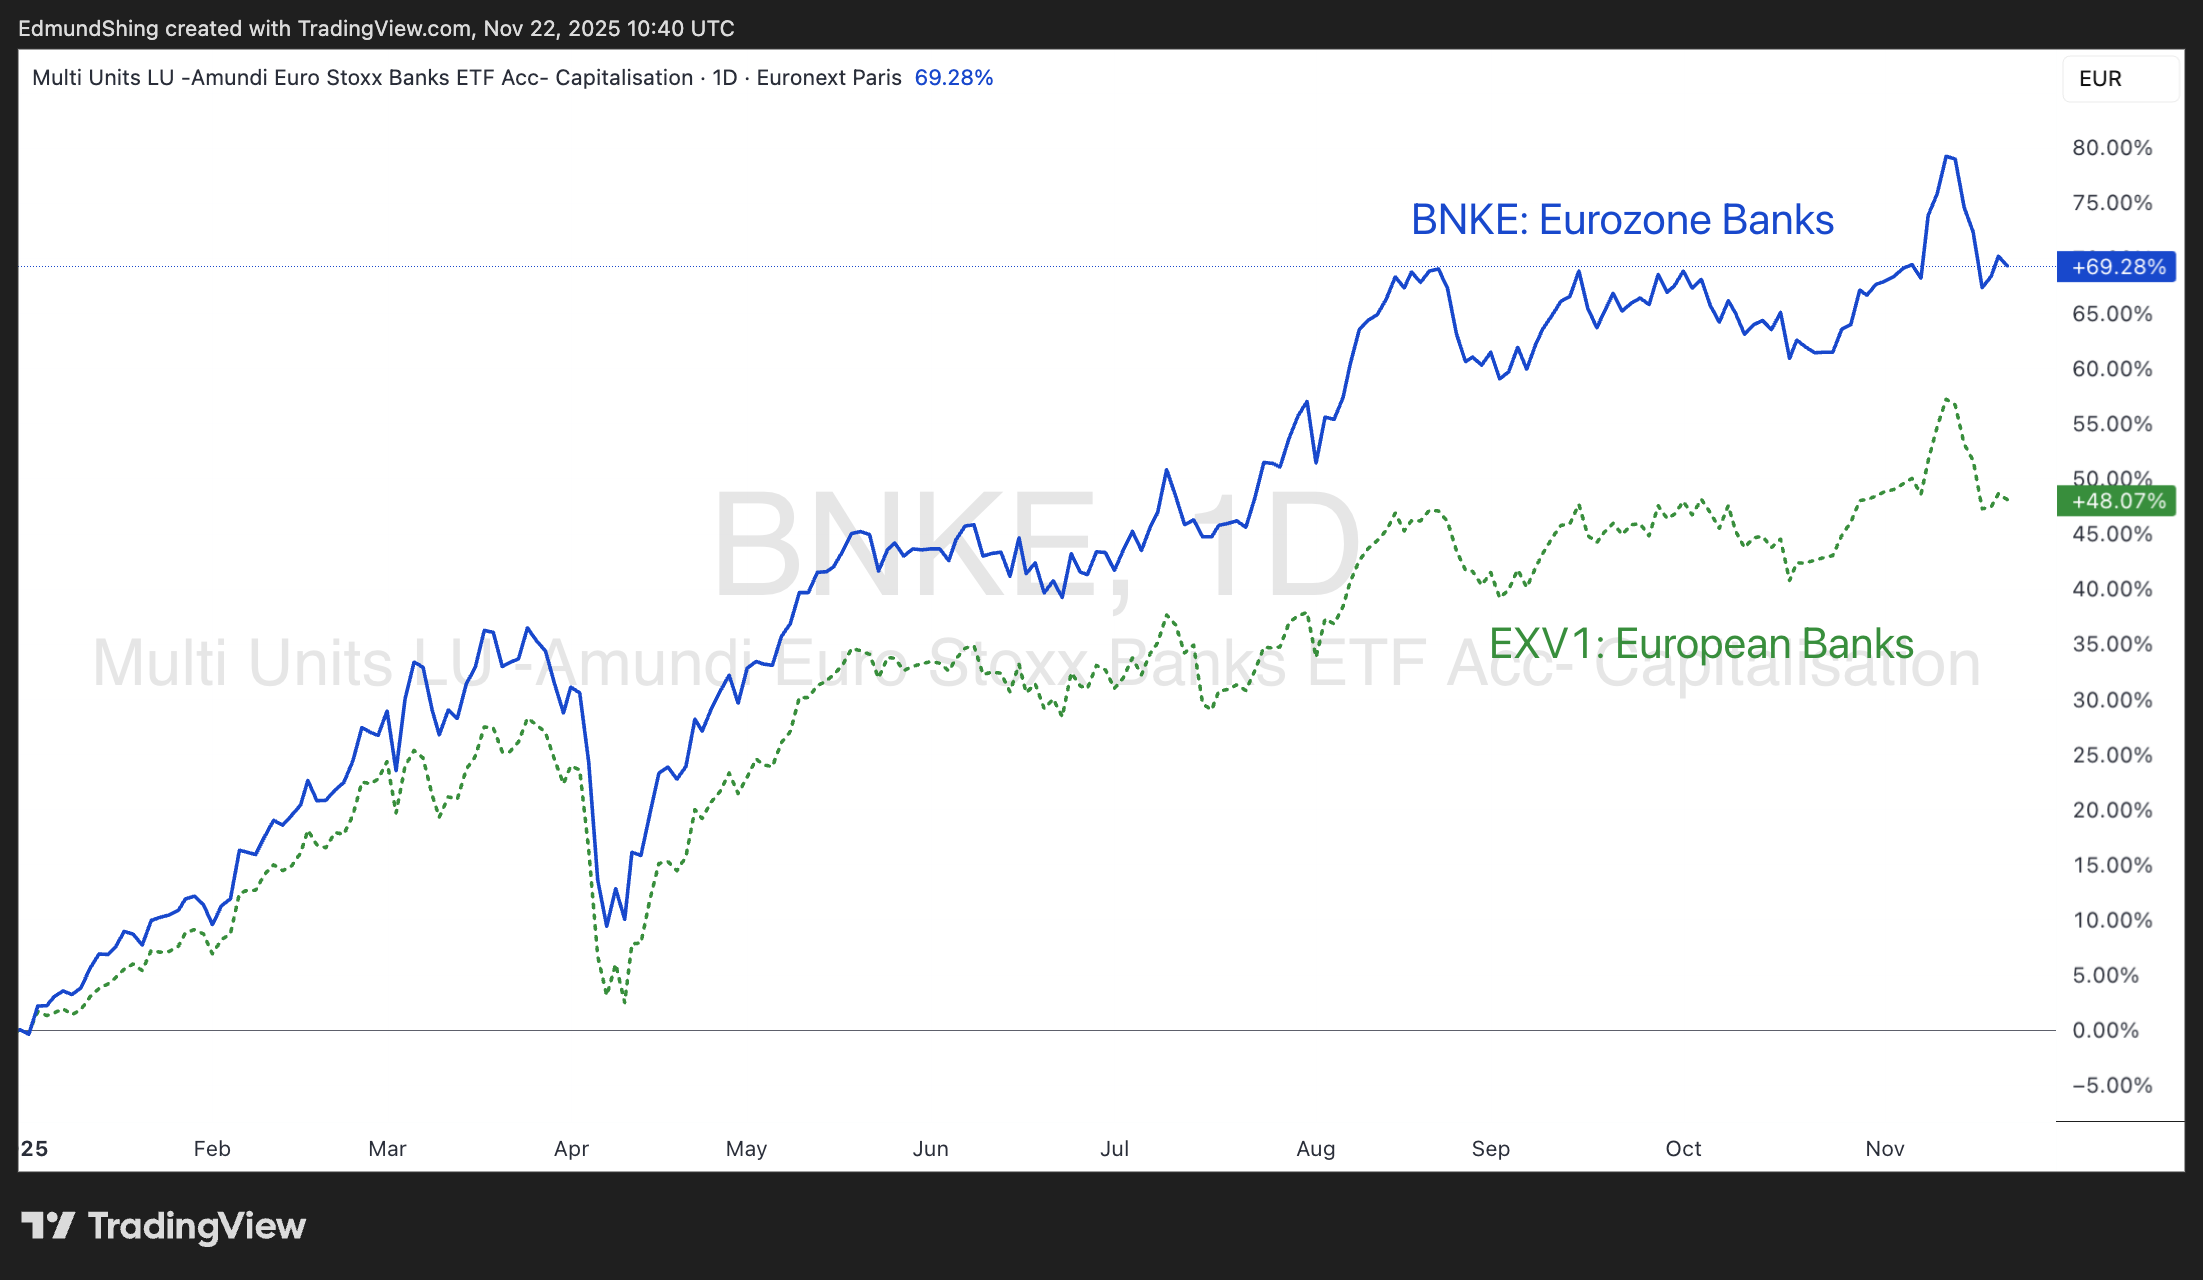
Improving Euro area growth momentum to buck persistent investor pessimism, from low interest rates, loan demand growth, increasing investment in defence, infrastructure and technology. Domestic consumption can improve on modestly lower savings rates, recovering property prices, lower inflation as energy costs ease further. Good for Banks, Travel & Leisure but not necessarily for goods makers given growing Chinese imports.
Illustrative charts
Emerging market stocks have outperformed the US by far in 2025
Grey dashed line: Emerging Europe. Blue line: Emerging Markets. Green dotted line: US
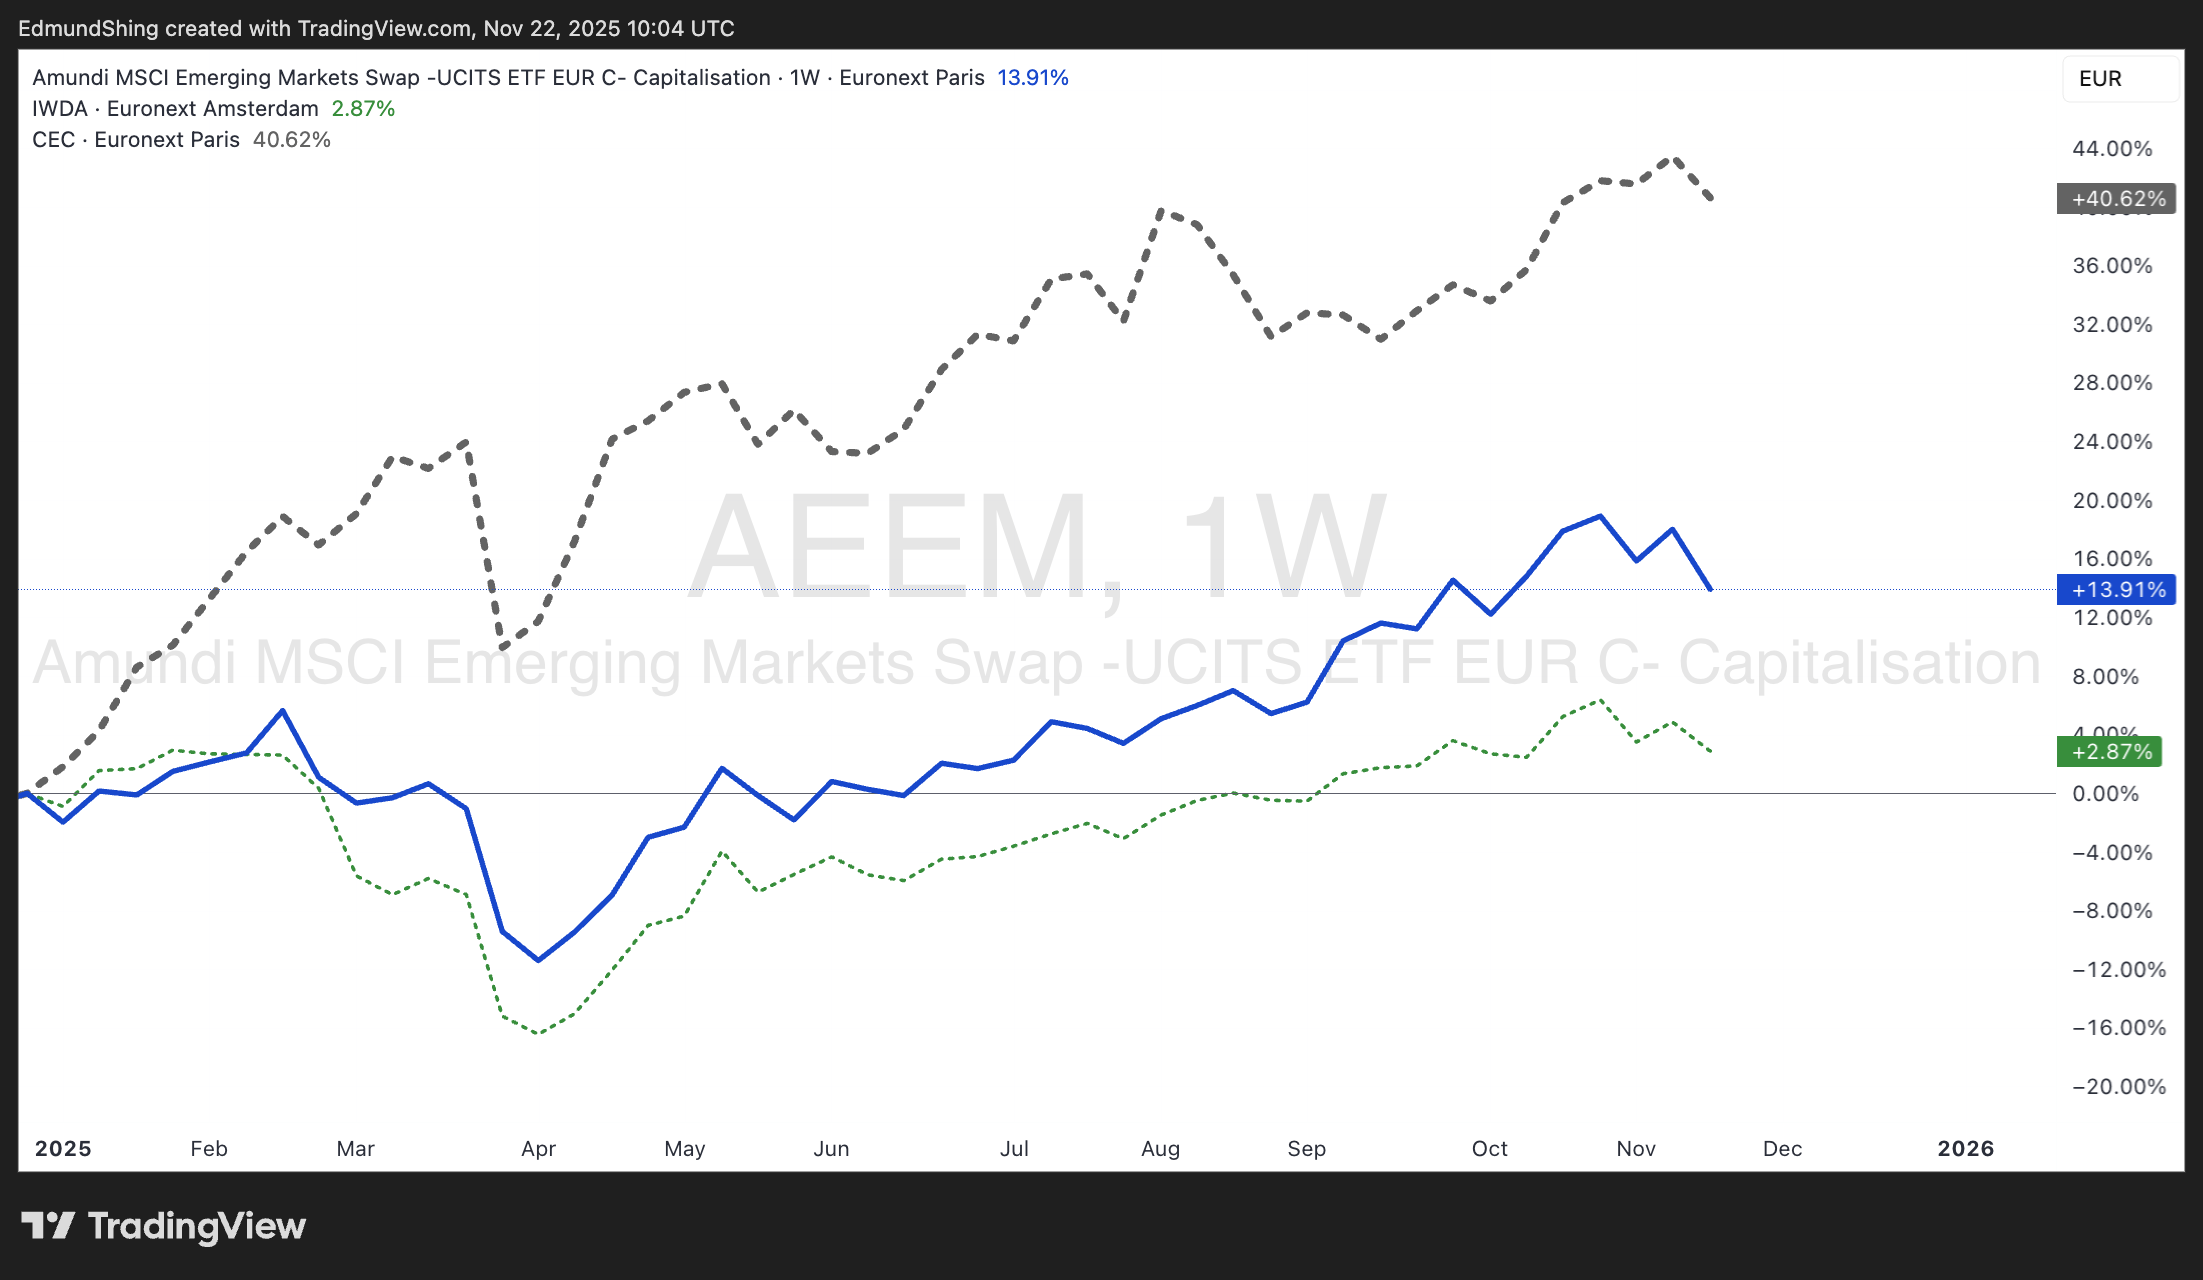
Note: all ETFs in euros
But massive under-performance of Emerging Markets vs US since 2011
Shifting sector leadership in US: from Tech to Pharmaceuticals
Copper, tin, aluminium all rising in line with global demand
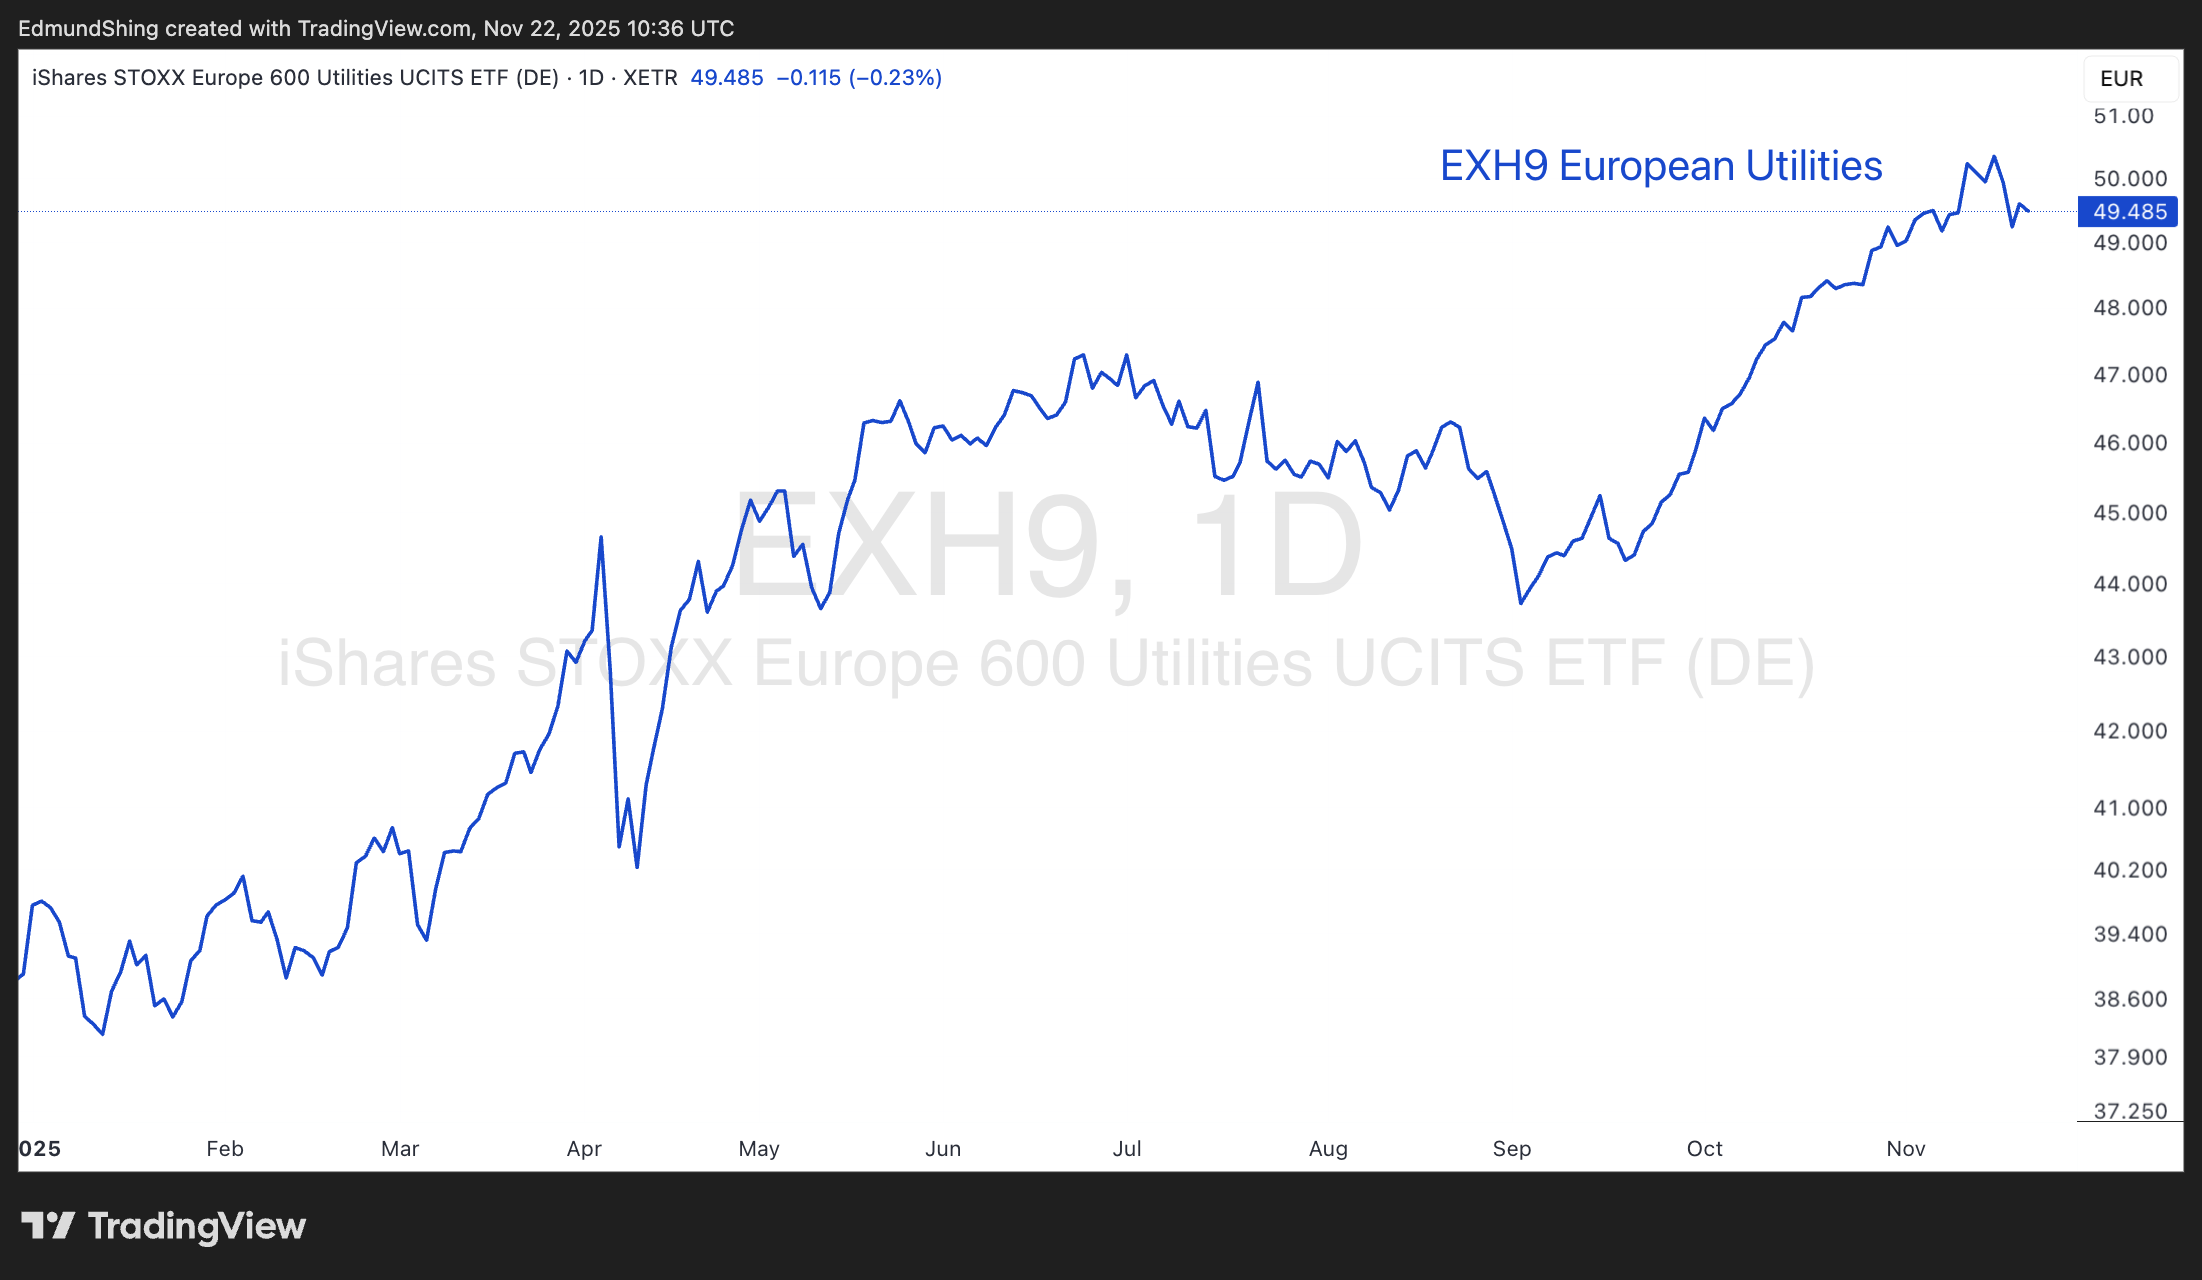
European Utilities rise on electric infrastructure demand
European Banks offer loan demand growth, well-backed dividends and capital returns to shareholders
Good luck for the week ahead
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

2 comments
It's the Budget that will set me back this week, that's for sure though it is nice to be reassured about the oil and gas outlook Edmund.
Reassuring! We all had a wobble last week .