Market Musings 221225: My Convictions for H1 2026

Market Musings 221225: My Convictions for H1 2026
Weekly Podcast and Snapshot report: A year of uncertainties (click on title to listen/read)
2025 was a year of volatility filled with uncertainties and geopolitical risks. However, it has also been an unusual year in asset class terms, with all major asset classes registering positive annual returns.
On one hand, central banks have cut benchmark interest rates, with short-term interest rates falling. On the other hand, bond markets have been steady over 2025, led by corporate credit markets on the back of strong demand and positive fundamentals driving tightening credit spreads.
While the US dollar weakened 10% against other major currencies, the global stock markets recovered strongly since “Liberation Day” in April to register double-digit gains for the year across the board, led by Europe and emerging markets. Finally, commodities represented the star of the year with gold increasing more than 50%.
In conclusion, we see good reasons for 2025’s positive financial market momentum to persist into 2026 given an encouraging backdrop of buoyant liquidity, low interest rates and positive economic and earnings growth.
Equity Focus report - December 2025 (click on title to read)
1. Arrivederci, GINO! The most common type of portfolio among equity investors is the GINO-portfolio as their allocation is Global In Name Only. We feel it´s time to wave goodbye to GINO and start rebuilding a truly global portfolio
2.What (not) to buy in Europe – We reiterate our neutral call on Europe as it will be a European equity market of two speeds: We like locally focused companies benefitting from efforts to enhance European autonomy while we keep avoiding the pockets of the market with too much US (Dollar) exposure. European SMIDs look particularly cheap.
3.Southern Momentum – Fitting our overweight call on Emerging Markets, we discuss the positive political backdrop in Latin America and why Mexican Equities are attractive again
4.Upgrading India to Overweight- India has underperformed the rest of the world this year. We expect to see India to catch up next year. There are some signals of a turnaround in economic and earnings momentum which was shown by strong Q3 results. Valuations against EM peers have normalized, making it a compelling case given the strong fundamental backdrop.
5.Sectors - No changes : In both the US and European regions, we consider it sound (and bullish !) to observe a certain sector rotation, with interestingly Health care and Utilities having led the last few months, while other 2025 underperforming sectors are also trying to recover.
My personal convictions for 2026
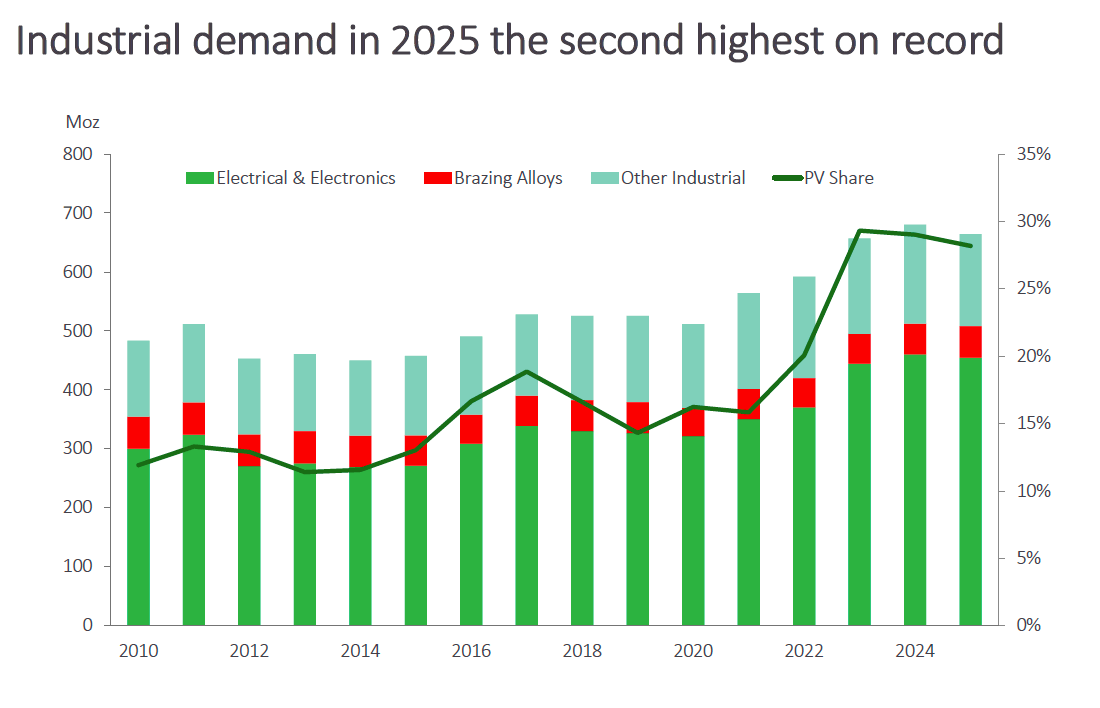
Silver: while silver has already risen over 130% this year in USD terms to $69/ounce, there could be more to come in 2026. Remember that silver is very volatile, so any continued rise is likely to be accompanied by substantial falls in the short term. The main drivers for any continued rise in silver are a) growing industrial demand e.g. from solar panels (29% of silver demand in 2024), and b) increased investment demand. I continue to target a long-term gold/silver ratio of around 50:1 (it has been over 100:1 in the recent past, and has now fallen to around 67:1). With gold at $4400/ounce at present, this would suggest a silver price in the 80s.
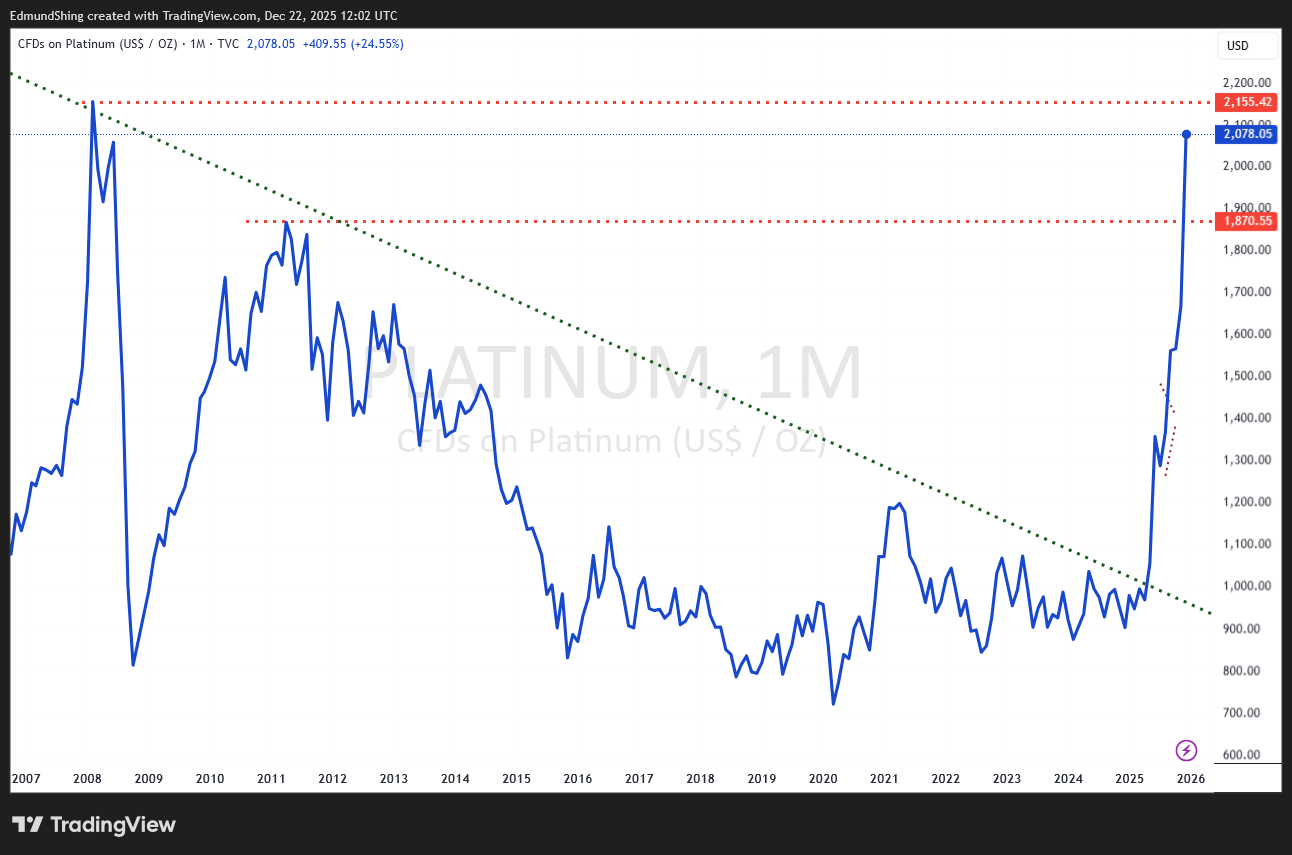
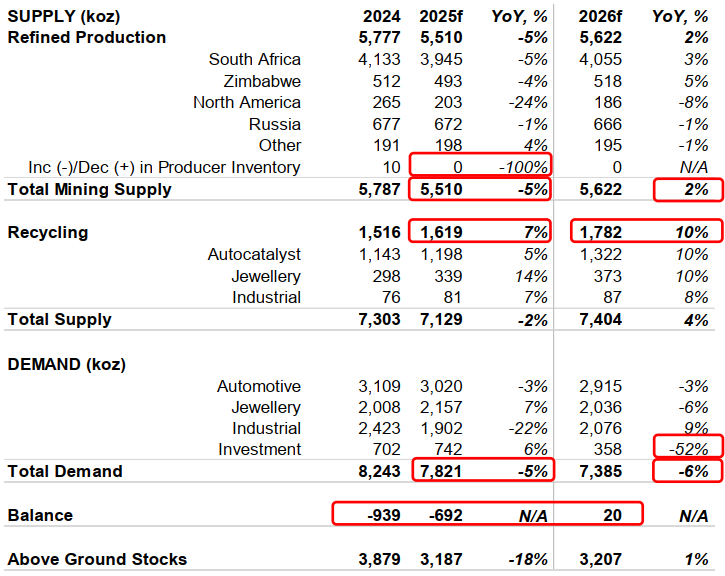
Platinum group metals (platinum, palladium, rhodium): platinum prices are rising sharply off the back of surprisingly stable industrial demand (car catalytic converters) and jewellery purchases (a cheaper substitute for gold, which today is more than twice as expensive). The market for PGMs remains small, far smaller than for gold or silver, and platinum and supply has persistently undershot demand for several years. Even in 2026, the market is only expected to return to a balanced market, assuming that investment flows into platinum more than halve. The situation for palladium is even more extreme, with structural deficits in palladium for the last 13 years and falling global production. If the US Commerce Department effectively sanctions Russian palladium via punitive tariffs (together with South Africa, the largest producer of palladium) in March 2026, the palladium price could soar further. In 2022, palladium peaked at over USD 3000/ounce versus the current USD 1774 level.
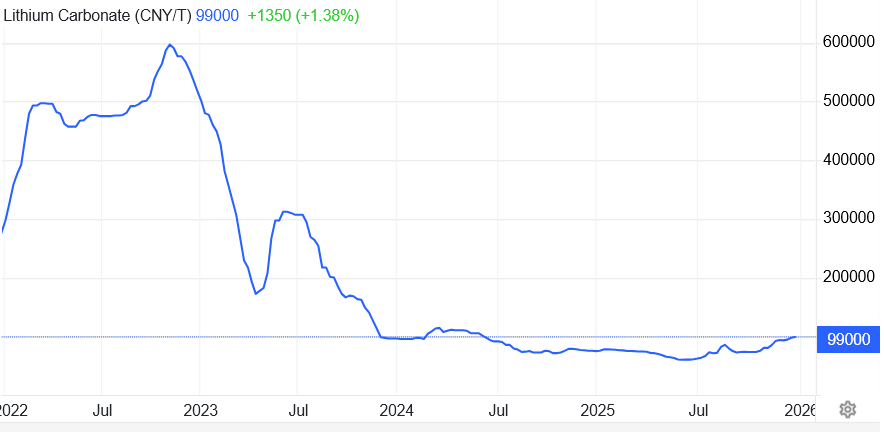
Lithium: lithium has an even more volatile history than silver, falling from CNY 600,000/ton in late 2022 to a low of CNY 6,000/ton by May this year thanks to overinvestment in lithium mining and refining. Industrial battery storage has become a new source of demand for lithium in addition to growth from both electronics and electric vehicles. Moreover, lithium prices remain too low at present to stimulate investment in new capacity, suggesting further upside for lithium prices in 2026 as battery demand continues to increase..
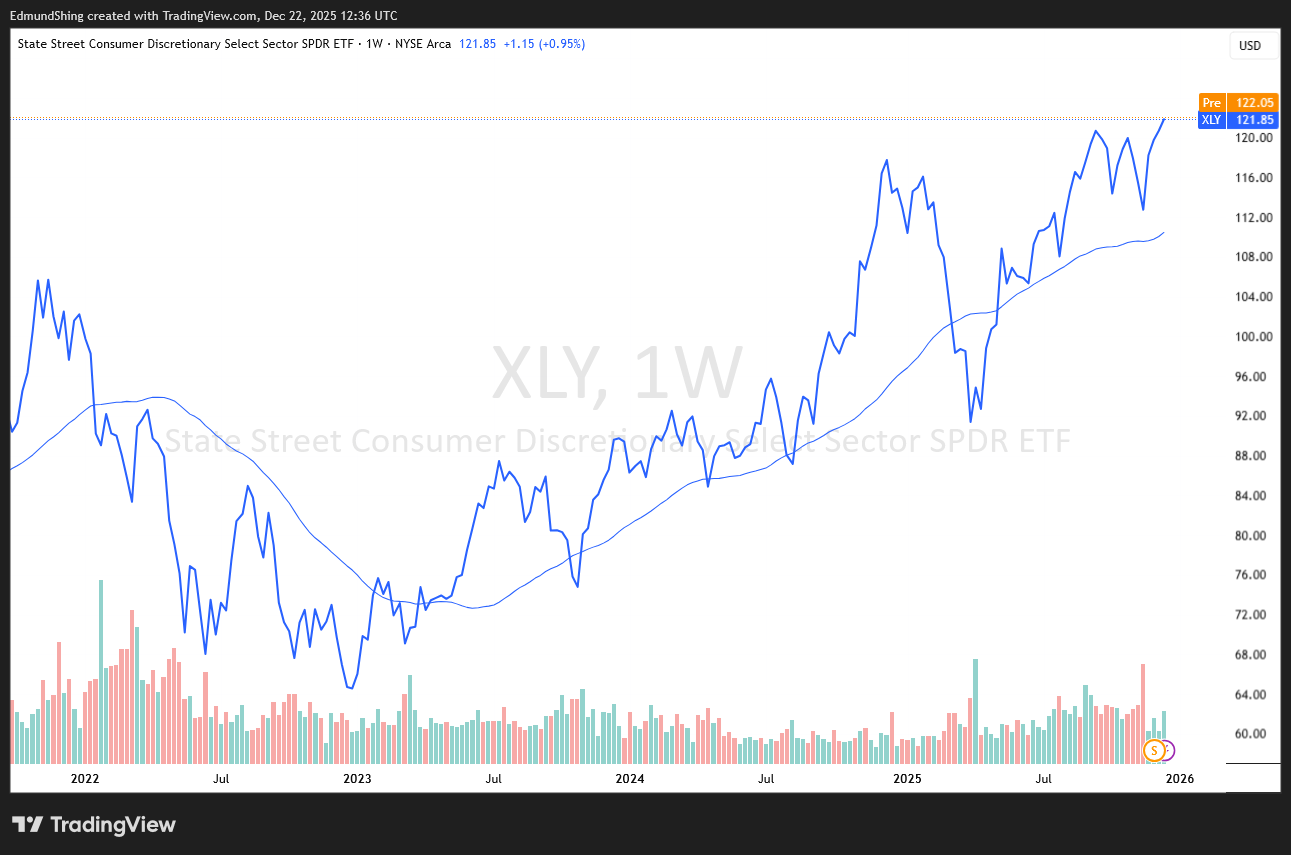
US household consumption to be boosted by record Q1 2026 tax refunds: thanks to the tax cuts built into the One Big Beautiful Bill Act (OBBBA) passed earlier this year by the Trump Administration and Congress, US households will receive tax refunds on tax already paid (at previous higher tax rates) for fiscal year 2025. In some cases, household tax refunds could be $1000-$2000 higher than in previous years. Some of this extra tax refund money may be saved, but a lot will likely be spent, fuelling US domestic consumption. Sectors such as restaurants, travel & leisure and e-commerce are likely to benefit from higher consumption. Airlines (JETS ETF) could be a particular beneficiary from increased travel, as could the Consumer Discretionary sector in general (XLY ETF).
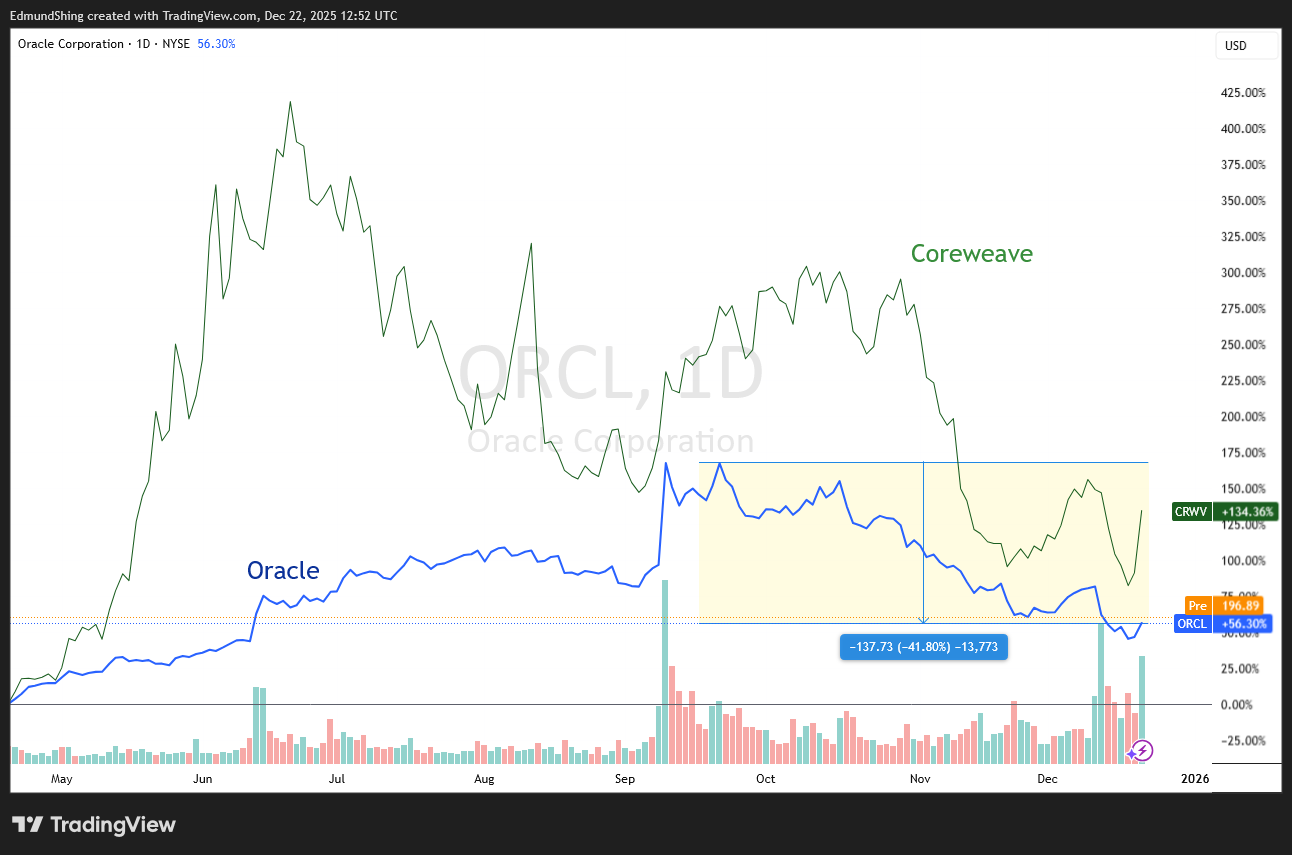
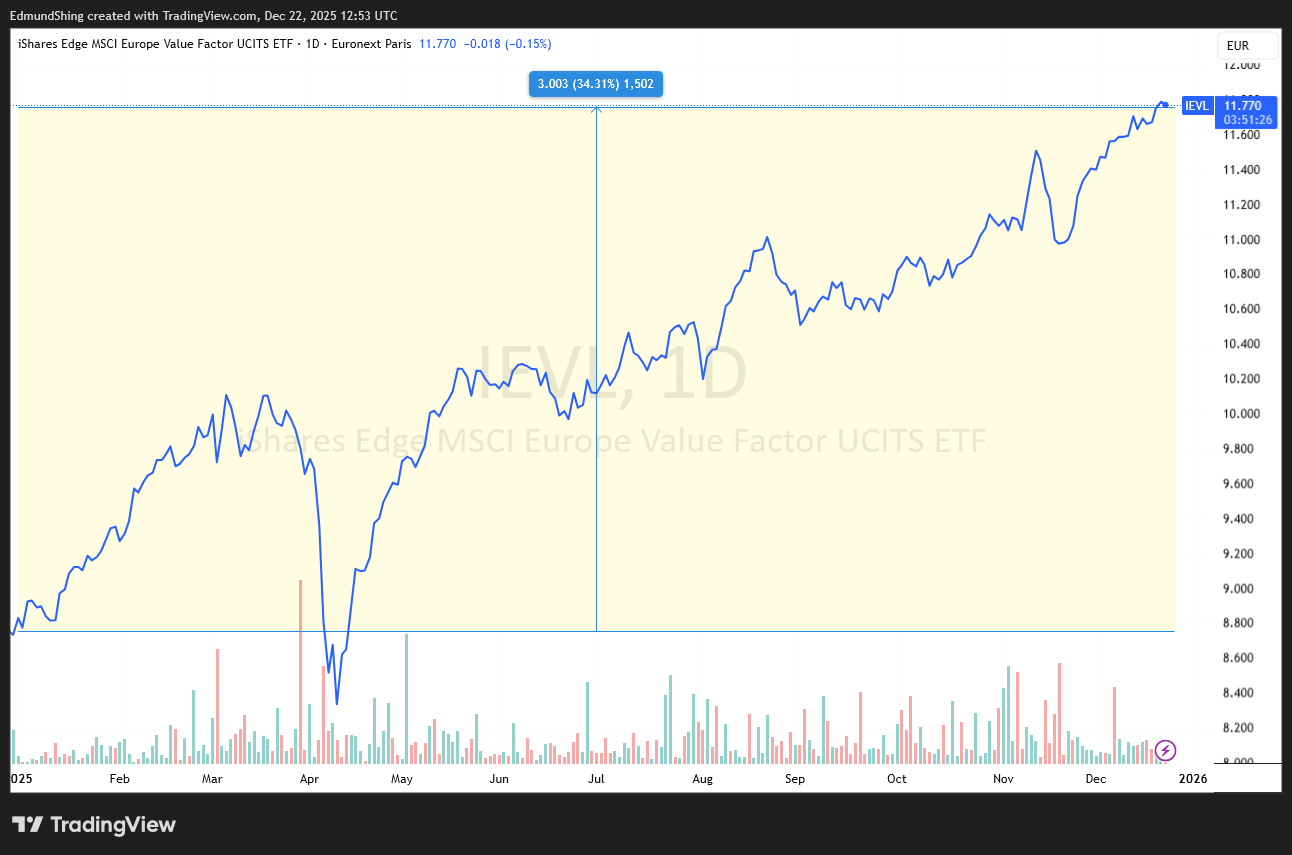
Continued global rotation away from US tech/growth towards World ex US/Value: I expect to see further questioning of the AI investment bubble in 2026, triggering further relative under-performance of US large-cap tech stocks in conjunction with further weakening of the US dollar against other G10 currencies.
Silver demand is strong
Source: Silver Institute
Platinum price has yet to follow gold and silver to a new all-time high
Platinum market has been in persistent supply-demand deficit, only moving to stable balance in 2026
Source: World Platinum Council
Lithium prices: a dramatic collapse since 2022 but now rebounding
Source: tradingeconomics.com
XLY US Consumer Discretionary sector ETF hits new highs
The fall of Oracle and Coreweave has been dramatic
While Europe Value +34% in euros this year, +44% in GBP
Have a great Christmas period and New Year,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

8 comments
Hi Edmund — interesting call on upgrading India to overweight for 2026. I can see the logic, but after some quick research there are a few things nagging at me and I’d love your take.
• Have valuations really normalised or are they still at a premium to EM?
• INR has been sliding 4–6% a year — will that not be creating a drag on expected returns?
• Is it the case that FPIs are still net sellers — what’s the catalyst that brings foreign flows back?
• And timing‑wise, is this really the moment to overweight? I'm thinking India would be better put on the shopping list if and when there is a market crash.
Keen to hear how you’re thinking about these points (or, as I don't expect Edmund to have the spare time to respond does anyone else have any thoughts on this? If not I'll just keep India on the market crash shopping list)
CoreWeave (NSQ:CRWV) Edmund, I take it your view is no short. med or even long rebound on this one? I have read so many confusing views!
Thanks Edmund, always enjoy your articles and the insights they provide. Wishing you a merry Christmas and a healthy and prosperous 2026 to come.
Thanks Edmund. I always look out for your musings and have benefited from following up on several of your ideas over the years.
On lithium — a slight correction on the price: I think you missed a zero. It fell to around 60,000 CNY/ton rather than 6,000 CNY/ton. Still a massive drop.
I hold iShares Lithium&Battery Producers UCITS ETF USD Ac (LON:LITM) and Global X Lithium and Battery Tech UCITS ETF USDAcc (LON:LITG) (the latter being the better performer). Both rallied strongly off the April–May lows, but they’ve flattened out over the past few weeks as the lithium market itself has paused. There may still be upside, but I’m currently more inclined to trim than add. I suppose a lot depends on whether the delayed 2026 supply pipeline restarts as prices rise, or whether those projects remain pushed out. One to watch.
Good article. What about platinum miners? Which ones?
Sylvania Platinum (LON:SLP) are a good bet
There are only four worth looking at and one of those is a tad tricky to invest in as it is Russian (Norilsk Nickel). That leaves Valterra Platinum (LON:VALT, Sibanye Stillwater (NYQ:SBSW) and Ivanhoe Mines (TSE:IVN) who have recently opened their new Platreef in South Africa. Ivanhoe comes with significant jurisdictional risk due to their copper mines in the DRC, but Mr Friedland's experience in the DRC there will no doubt be useful in South Africa where AK47 gangsters control the electricity and sometimes the water supply. I own Valterra Platinum (LON:VALT) and Sibanye Stillwater (NYQ:SBSW).
I publish my full portfolio at Alastair Kendall | Substack
You could also consider WisdomTree EnTrnMtlsandRrErthMnrs UCITS ETF USDAcc (LON:RARE) if you want to diversify your risk from a single miner. This includes access to lithium and platinum miners.