Market Musings 251025: Stock bull market in full flow

Market Musings 251025: Stock bull market in full flow
Podcast this week:
Rare Earths: A new flashpoint (click link to listen)
Rare earth metals are elements extracted and processed for use in several technological products, in wind turbines and in defence equipment. Mainly mined and refined in China, the growing demand for these elements in a world of rising technology investments has led to a global overreliance on China for access to these crucial materials. This dependence is currently creating trade tensions between the US and China. On one hand, the US is threatening to increase tariffs, while on the other hand, China is threatening to impose new controls on the rare earths’ exports.
Since Liberation day tariffs, global demand for rare earth elements and strategic metals has risen and has driven their prices, and the price of related producers, higher. The Wisdom Tree Strategic Metals and Rare Earths Miners Index, for example, has increased by more than 100% since April 2025. A variety of rare earth metals mining funds and ETFs are available to invest in this theme.
Bonus report: The impact of “Sanaenomics” on Japanese Equities (click link to read)
A paradox: Sanae Takaichi has been elected as Japan’s first female prime minister. While the move symbolises diversity in leadership, Ms Takaichi is a conservative traditionalist.
We expect her to pursue a balanced pro-growth and proactive fiscal strategy which strengthens our constructive view on Japanese equities.
The two arrows of Sanaenomics: an acceleration of earnings growth and a renewed focus on corporate reforms, which should provide further upside potential. Stay overweight!
Global stocks roar higher
While certain bullish themes such as precious metals and nuclear are cooling off after massive bull runs, the stock bull market that began in October 2022 and which is now beginning its 4th year shows no signs of coming to an end, in spite of a myriad of global geopolitical concerns. The MSCI World index continues to make all-time highs: year to date, +6% in euros, +11% in GBP and +19% in USD.
Global stocks hit new highs: MSCI World index in solid uptrend
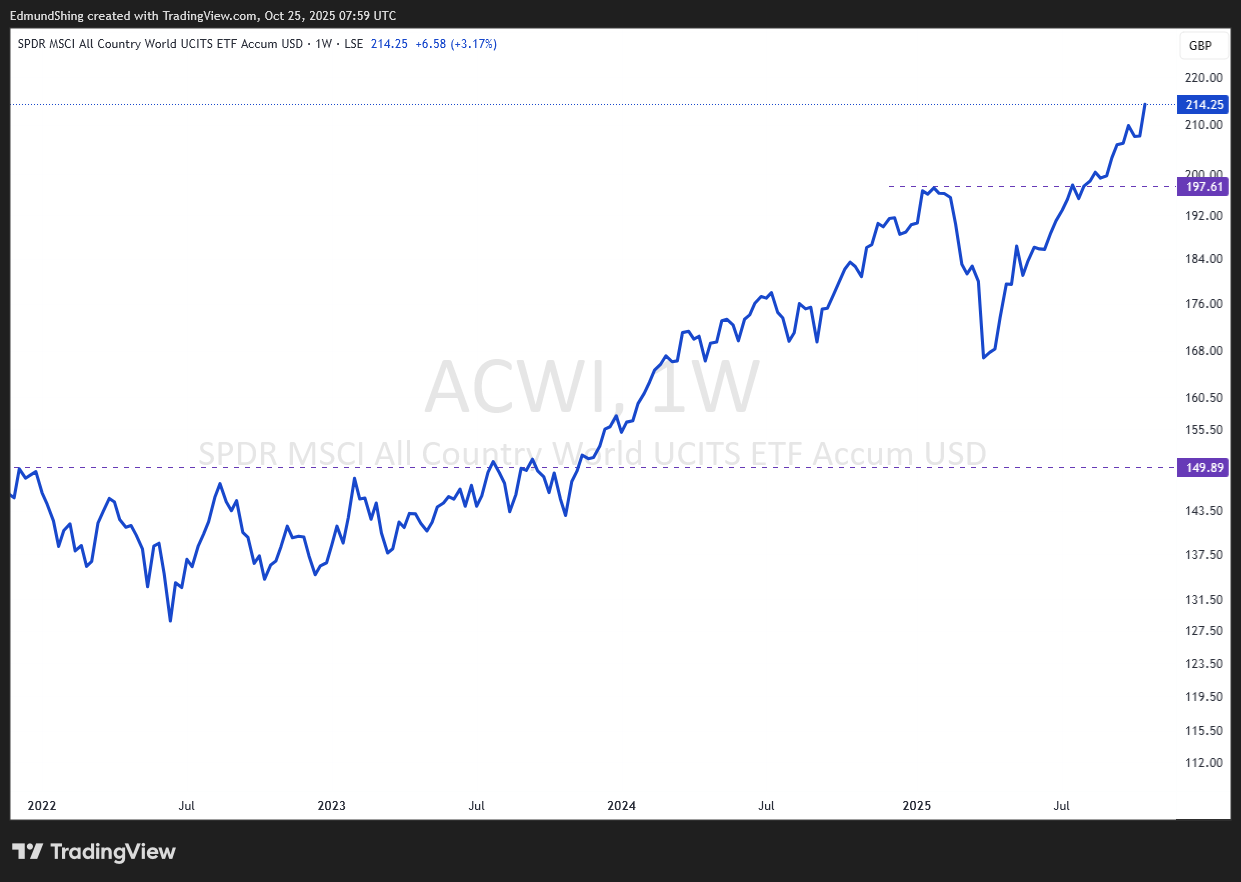
What makes this advance to new highs more robust in nature is the broad-based advance globally, with many regional and country stock indices simultaneously marching to new highs at the same time, including:
Chinese domestic A-shares (Shanghai Composite)
Japanese Nikkei 225
Korean KOSPI
UK FTSE 100
Euro STOXX 50
European small-caps (MSCI Europe Small-Cap index)
French CAC 40
Spanish IBEX 35
Swedish OMX 30
Brazilian BOVESPA
Australian ASX 200
As well as the main US indices such as the S&P 500, Nasdaq 100 and the Russell 2000.
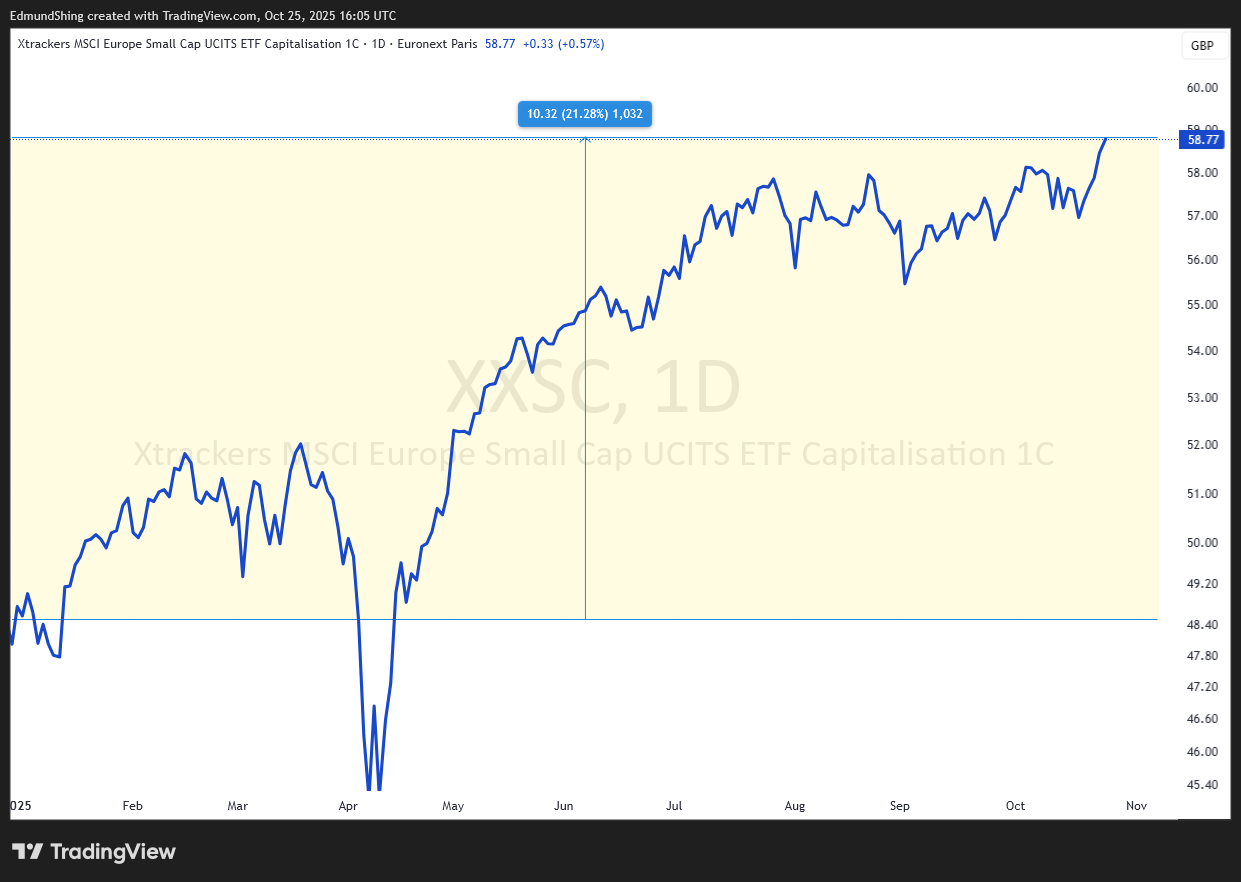
Out of these, look to European small-caps as they have already delivered a 15% return so far this year in euros and 21% in GBP.
European small-caps to benefit from improving eurozone economic momentum
The key motors behind this broad stock market advance remain the same:
Plentiful global liquidity, especially from the US and China
Lower long-term interest rates and the US 10-year bond yield in particular declining to 4%
Record level of share buybacks in the US, UK, Europe and Japan shrinking outstanding equity in these markets
Strong Q2 earnings results in the US, Europe
Falling cash interest rates prompting retail investors to look elsewhere for better returns
At this point, valuations are expensive versus history in the US and fair in Europe and Japan. Valuations are important in determining likely 10-year average returns, but have a surprisingly low correlation with subsequent stock returns over a 1-year investment horizon. Put another way, higher-than-average valuations can persist for years while earnings growth is solid and liquidity ample.
Gold and silver in correction mode
Precious metals, on the other hand, have eased lower in the last week, presumably on the back of profit-taking after a very strong year so far. Even after last week’s correction, gold has gained 54% this year and silver 68%. It is worth bearing in mind that the strongest bull markets often see big corrections along the way, so we should not be surprised to encounter a corrective cooling-off period after such a strong advance.
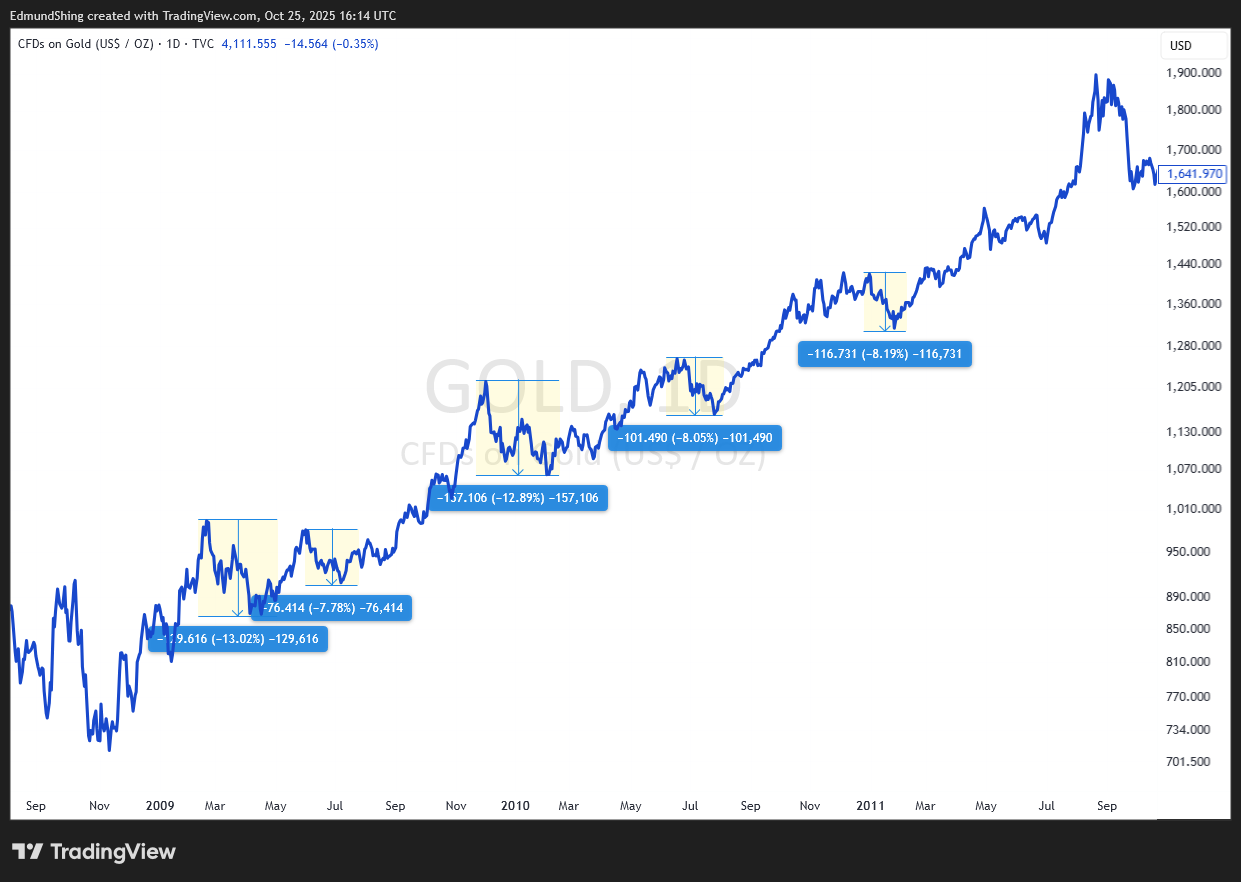
In the 2009-11 gold bull market, the gold price dropped 8% on 3 occasions and 13% on 2 occasions on its way to a cumulative 167% gain.
Gold suffered 5 pullback periods in the 2009-11 bull market
In this bull run which started in October 2022, gold has only pulled back 8% once in November 2024 and 11% once in early to late 2023. So far, gold has gained 152% over the last 3 years, and the current pull back is only a 6% drop so far. At USD 4112/ounce, the gold price thus far remains above the September closing high of USD3874.
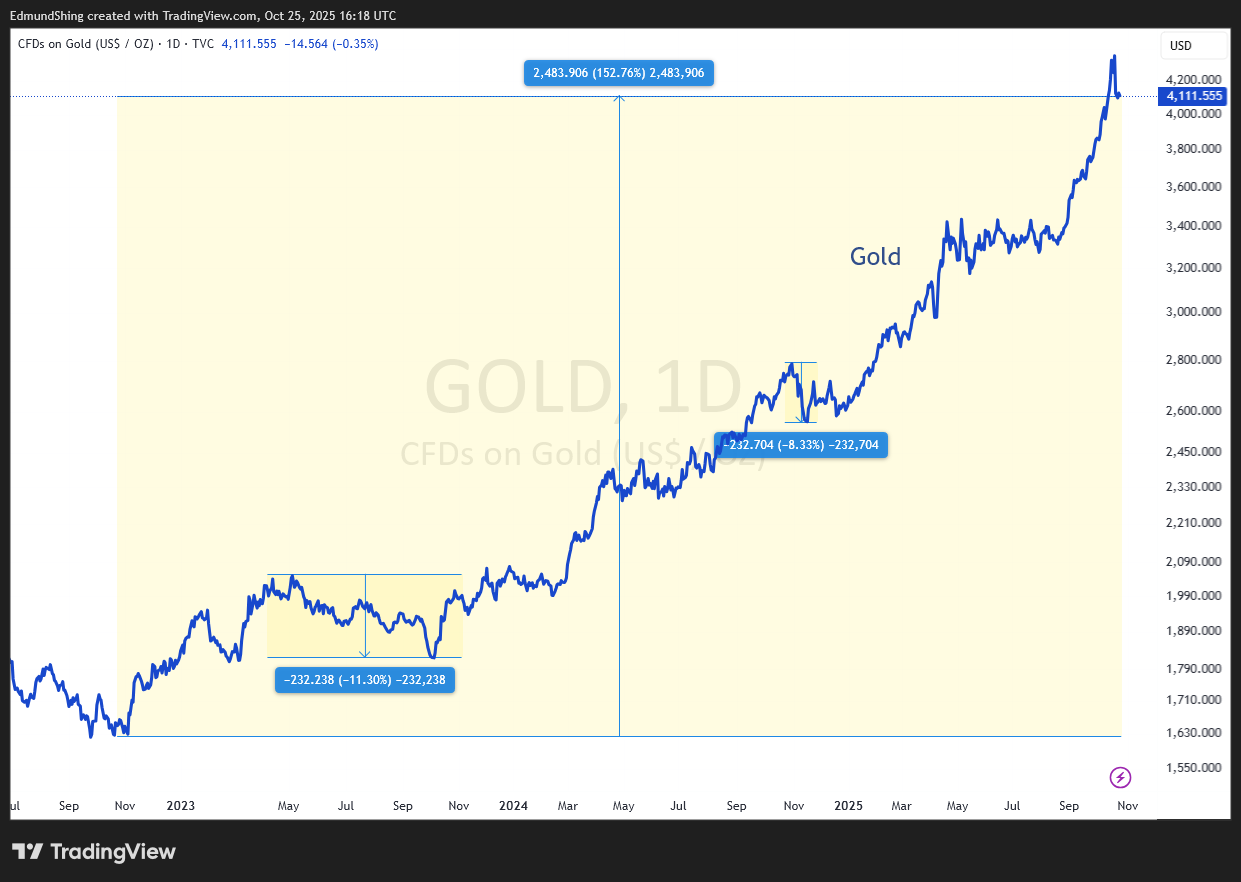
This correction in precious metals could easily run further, without breaking the current long-term bullish uptrend.
The same is even truer for gold and silver miners, which is a notoriously volatile sector. The GDX gold mining ETF has fallen 14% from recent all-time highs, but has still delivered +233% since October 2022.
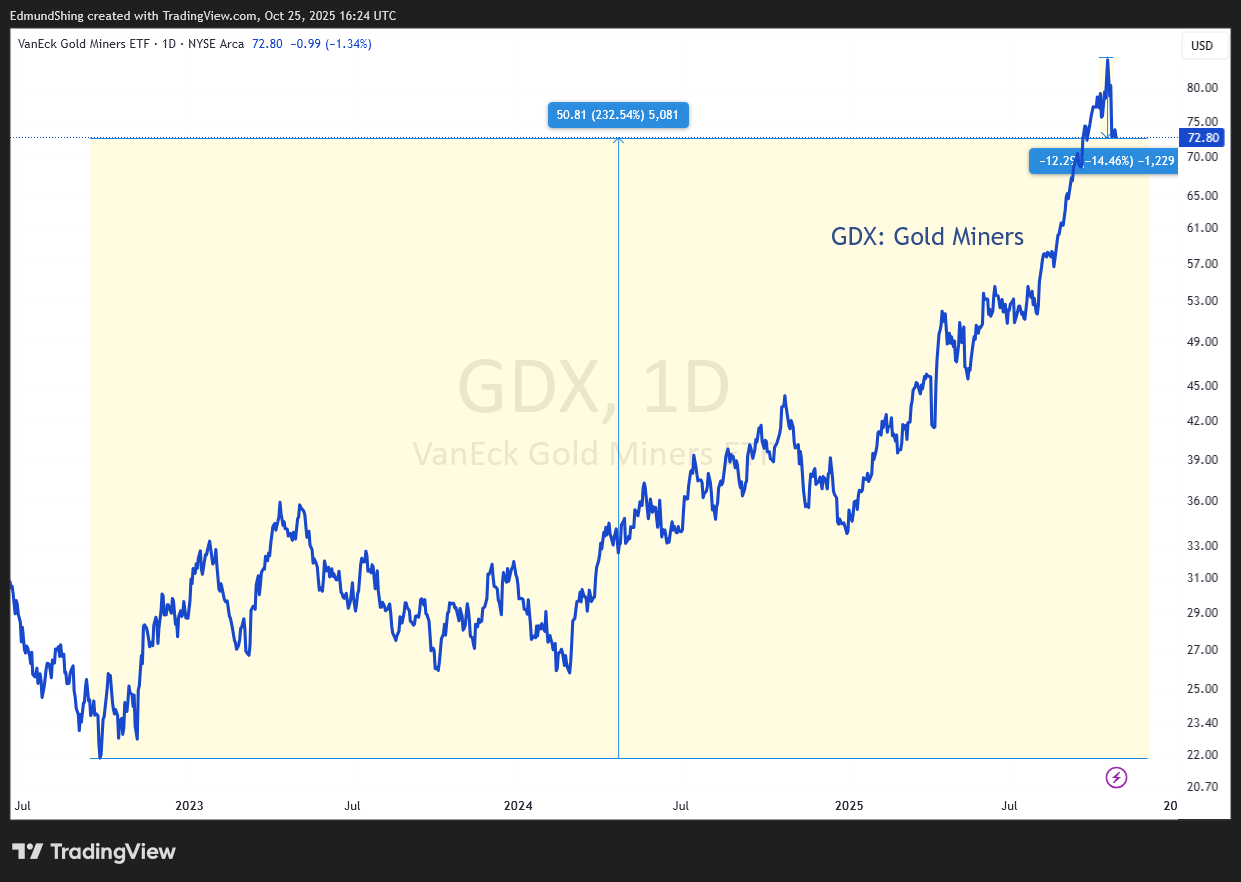
I remain bullish on both precious metals and miners, but will wait to see stabilisation in prices before adding more exposure.
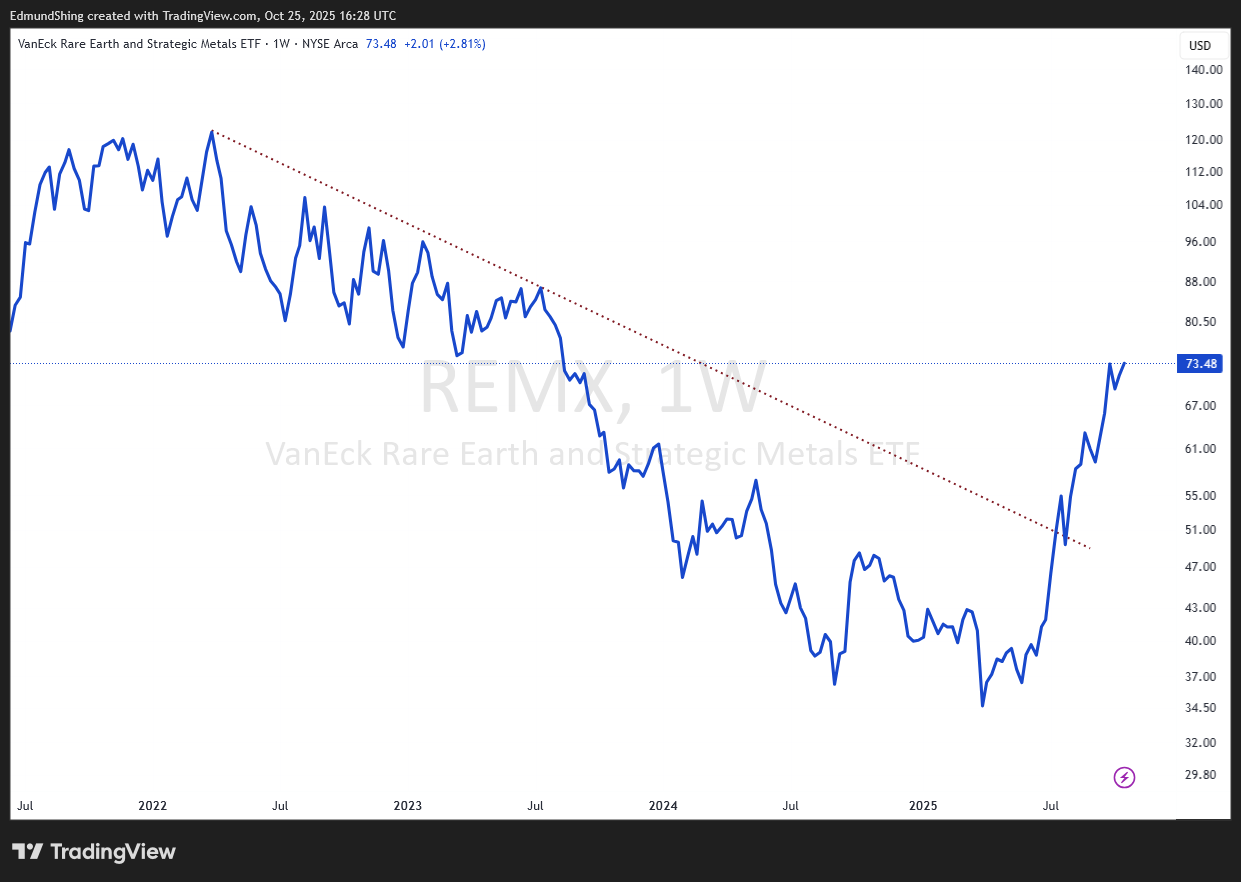
Rare earth metals continue to mark a strong recovery, helped by US government investment in domestic production of critical minerals including rare earth metals as they look to depend less on supply of these critical metals from China (who dominate with 90% of the world’s rare earth refining capacity).
Rare earth metals miners continue to rebound
Have a great week everyone,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

3 comments
I recall reading about China's dominance of rare earth mineral mining and processing back in about 2012. It's staggering the US and Europe have taken so long to act.
Good article on how China managed to dominate rare earth minerals:
https://tinyurl.com/zaxxumm6
And US realisation that market intervention is required in order to try to catch up:
https://tinyurl.com/4rnxn3pb
Thanks as always Edmund.
I notice the BBC reports that the US and China may have reached a framework for a trade deal that defers China’s tightened rare-earth export controls and averts the threatened steep US tariffs ahead of the leaders’ meeting in South Korea. China will delay its rare-earth export restrictions for one year under the US–China trade framework, easing short-term supply risks for US tech and manufacturing sectors. This development could influence related stocks, ETFs etc. tomorrow do you think?
Medium/Long-term, the over reliance on China will still need to be addressed of course.
Thanks for musing on my favourite subject Edmund!