Market Musings 251026: Are the highs in for yields?

Market Musings 251026: Are the highs in for yields?
Key Points:
Bonds: Most 10-year government bond yields have declined from peak since the beginning of this month: potentially a trend change after the sharp rise in long-term interest rates since March;
Stocks: While most major stock markets are relatively close to historic peaks, many stocks and sectors are already in a bear market (down 20% or more).
Commodities: Energy prices have rallied further, with Brent crude oil even above the April peak
FX: Euro remains weak, notably against sterling as the UK Budget (28 October) approaches fast. GBP/EUR looks ready to test the EUR1.20 soon
Bond yields may have peaked
The start of the US-Iran war in March dramatically changed the environment for bonds. Up until March, global inflation rates were on a declining trend, allowing US and European central banks to continue to cut benchmark interest rates further over the following months.
Instead, the resulting surge in energy prices following the start of the (now 7 month-old) Iran conflict has forced central banks to raise interest rates in the face of inflation that has stayed stubbornly high. As a result, 10-year government bond yields rose by anywhere from 1% to 1.8% to their late September to October peaks.
But in the last 3 weeks, most 10-year bond yields look to have peaked, retreating 0.1% to 0.3% by 23 October. This coincides with the market’s reassessment of how many central bank interest rate hikes are forecast over the next 12 months.
Country | 10Y Yield %: 1 Mar. | 10Y yield % peak Sep./Oct. | 10Y Yield %: 25 Oct. |
US | 4.0% | 5.3% | 5.0% |
Germany | 2.6% | 3.6% | 3.4% |
Japan | 2.1% | 3.1% | 2.8% |
UK | 4.3% | 5.5% | 5.4% |
In the case of the US Federal Reserve, interest rate futures markets price between 2 and 3 further Fed rate hikes between now and June 2027. Three weeks ago, this expectation was for an additional 3-4 rate hikes. Somewhat softer US economic and inflation data in October has led to this adjustment, in spite of energy prices that remain extremely high.
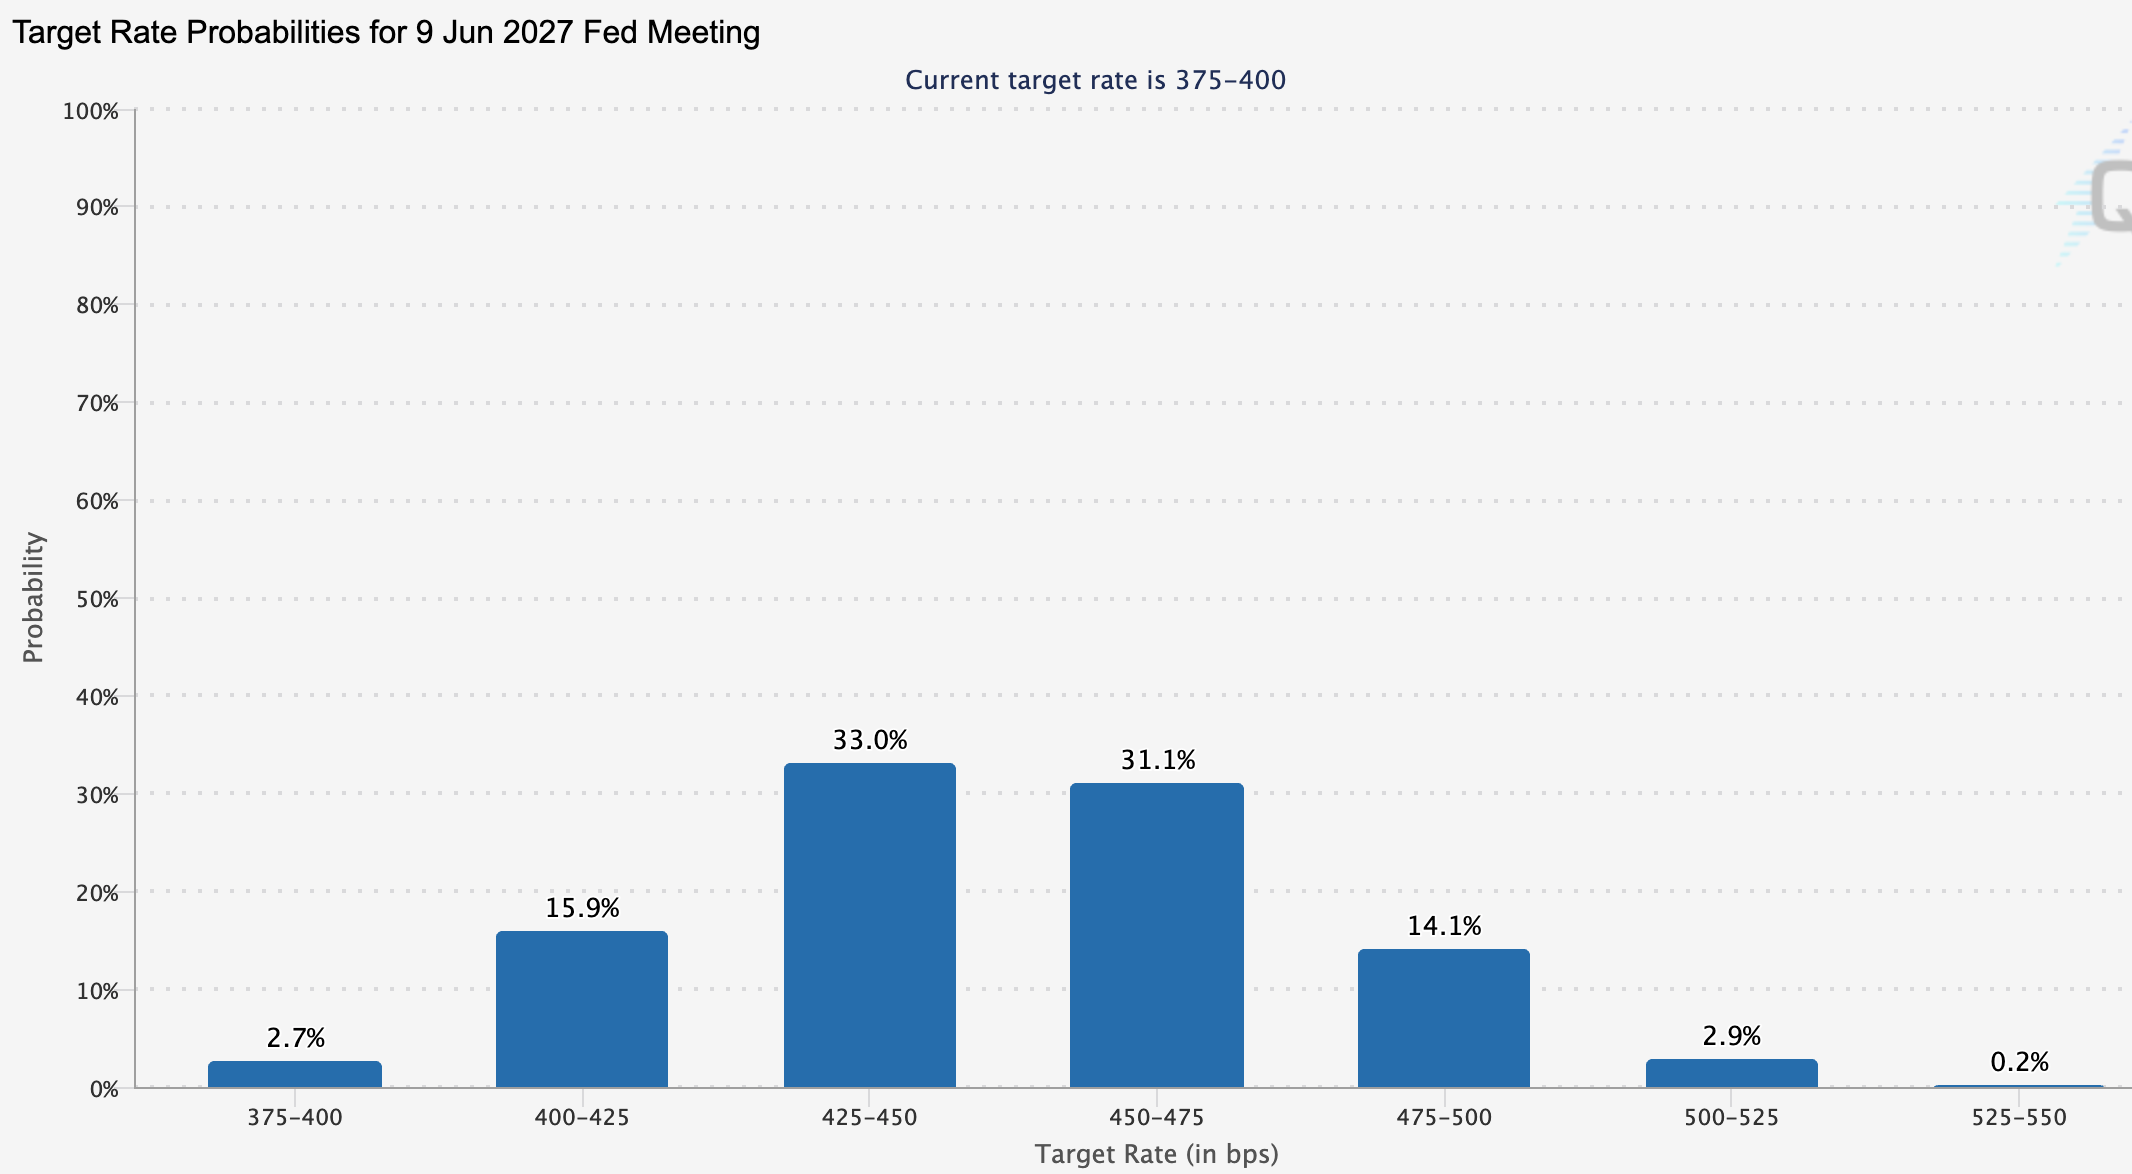
Source: CME Group
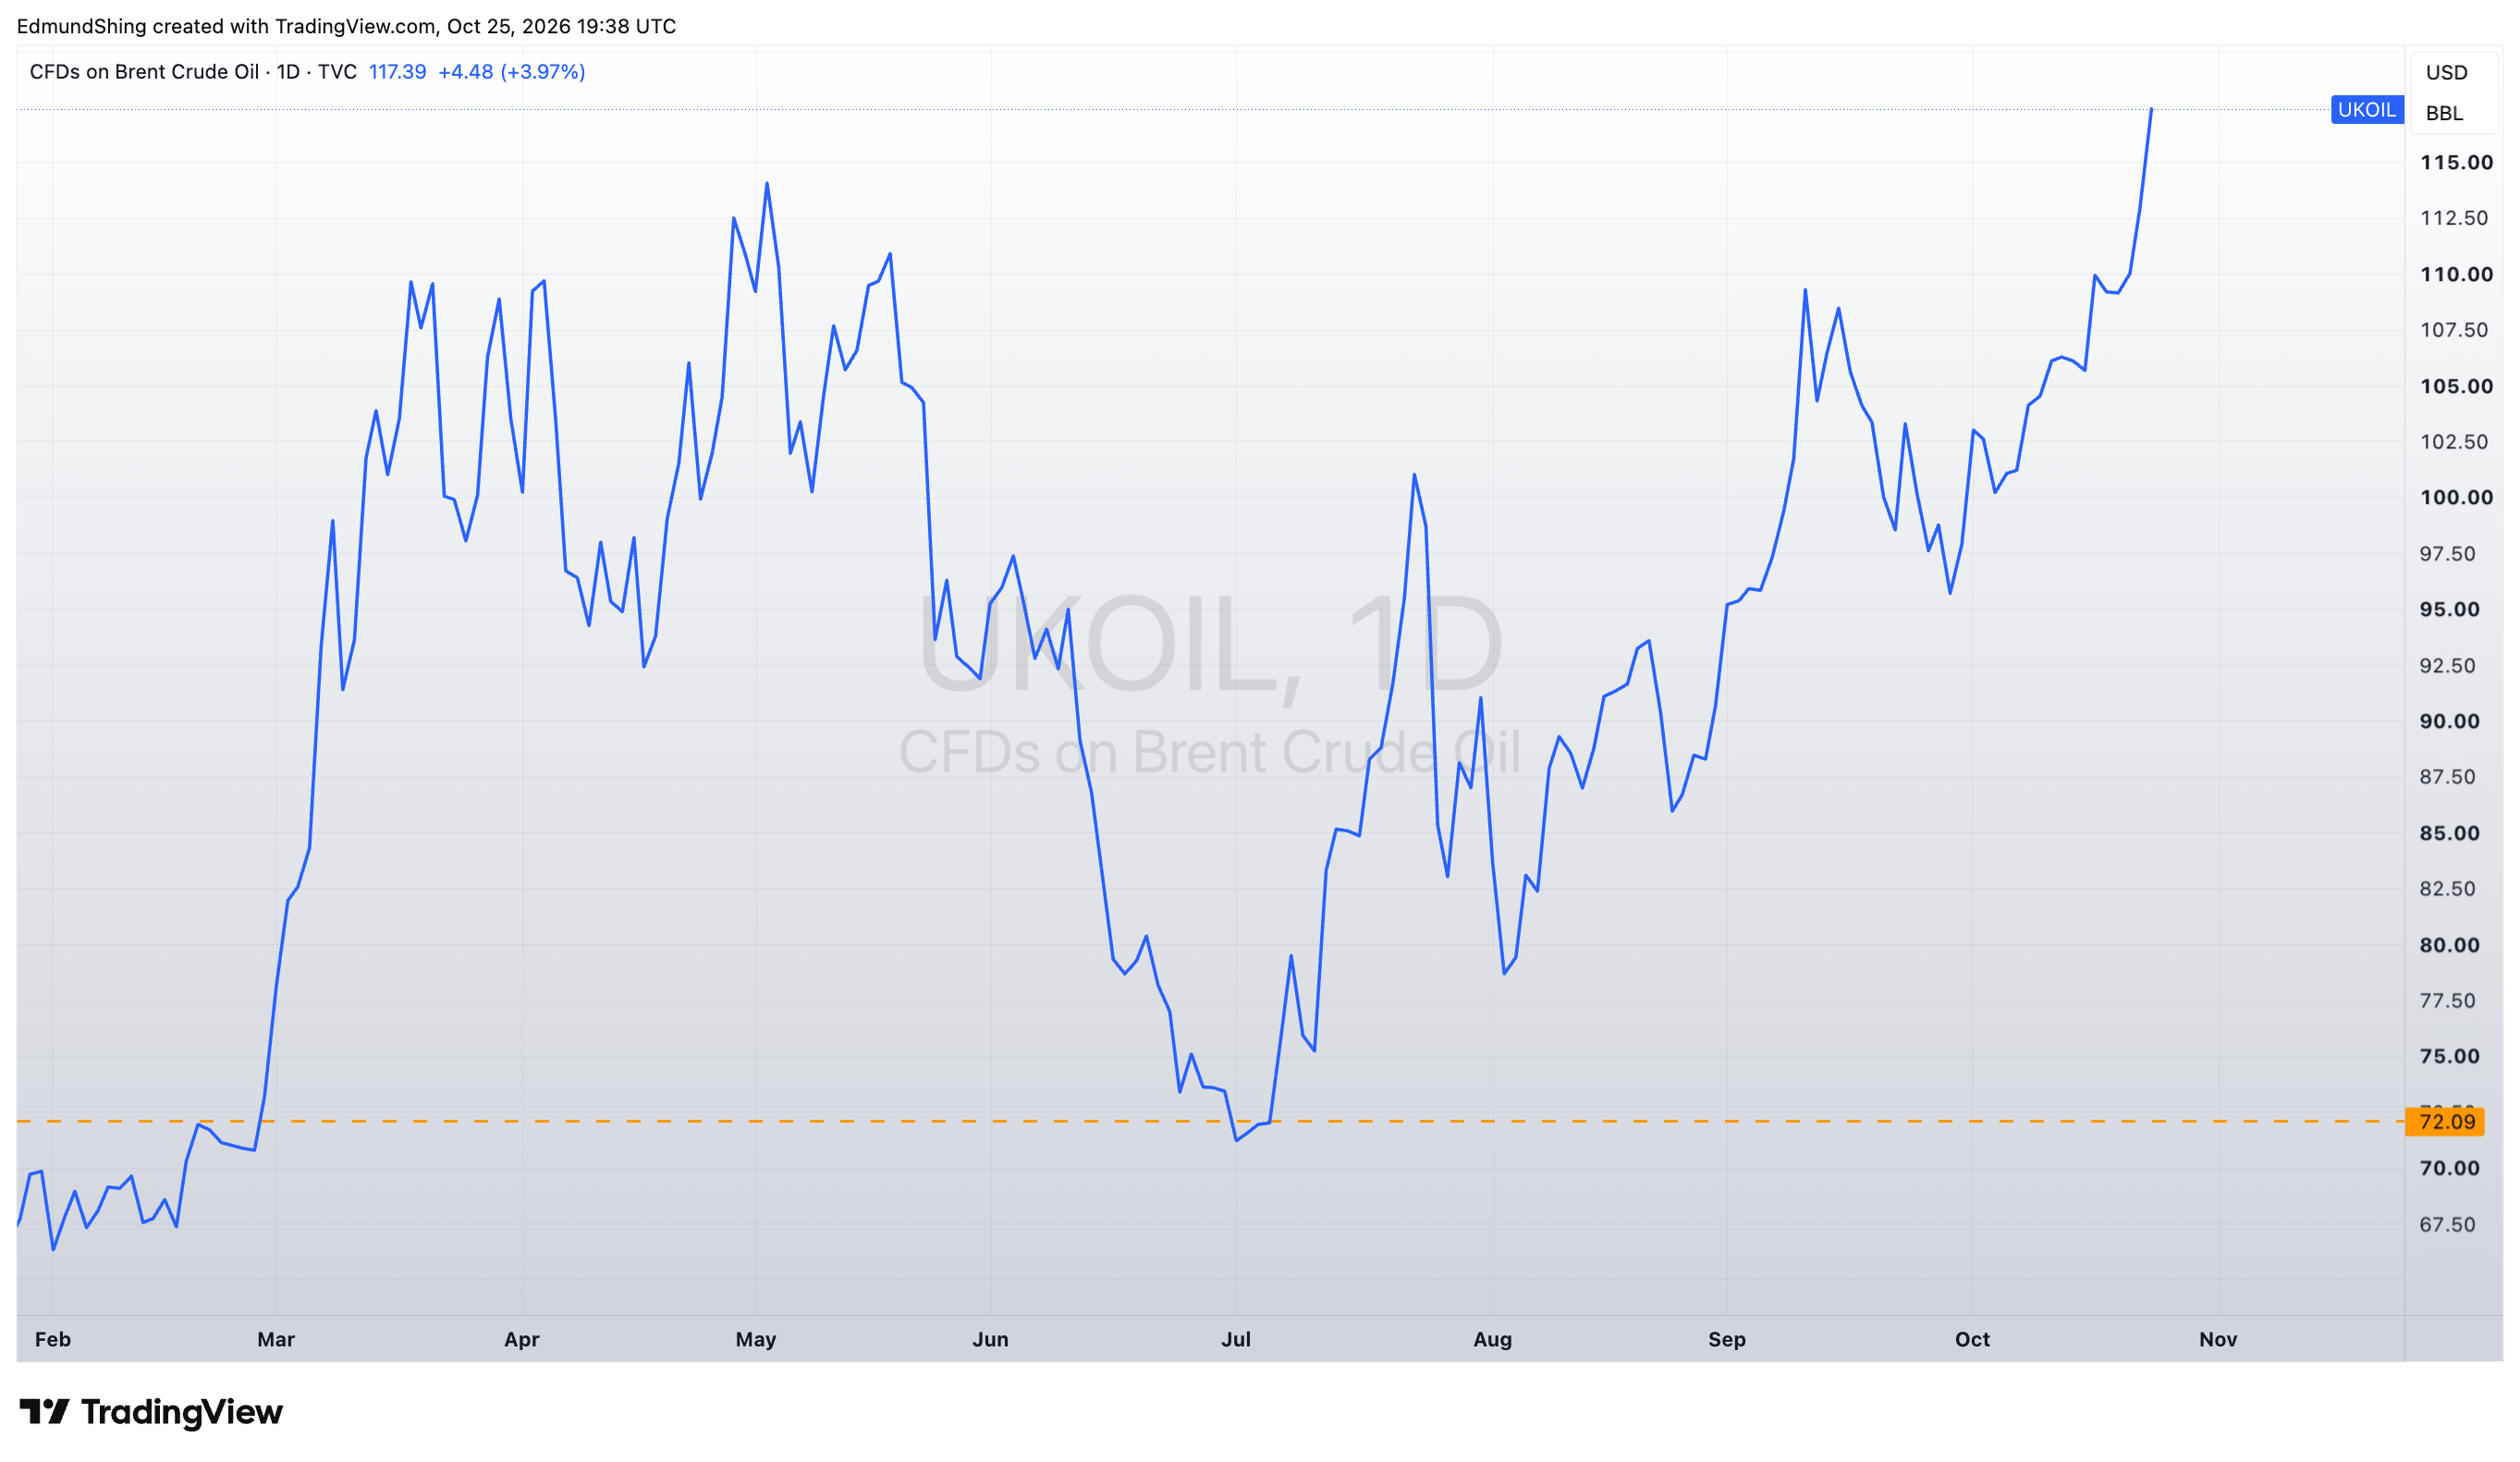
But this is not the only reason for the fall in bond yields. After all, crude oil and diesel prices have not declined, but if anything have continued to go up, with the Brent crude benchmark hitting a new year high of USD117/barrel on Friday 23 October.
Brent crude hits a new high, above the prior April peak
A major factor in this retreat in bond yields was a flight to safety, i.e. the renewed buying of bonds by both professional and retail investors as they reduced exposure to riskier technology stocks in favour of the relative safety and attractive income offered by bonds.
Stock Markets are close to Peaks, but weakness lurks beneath the surface
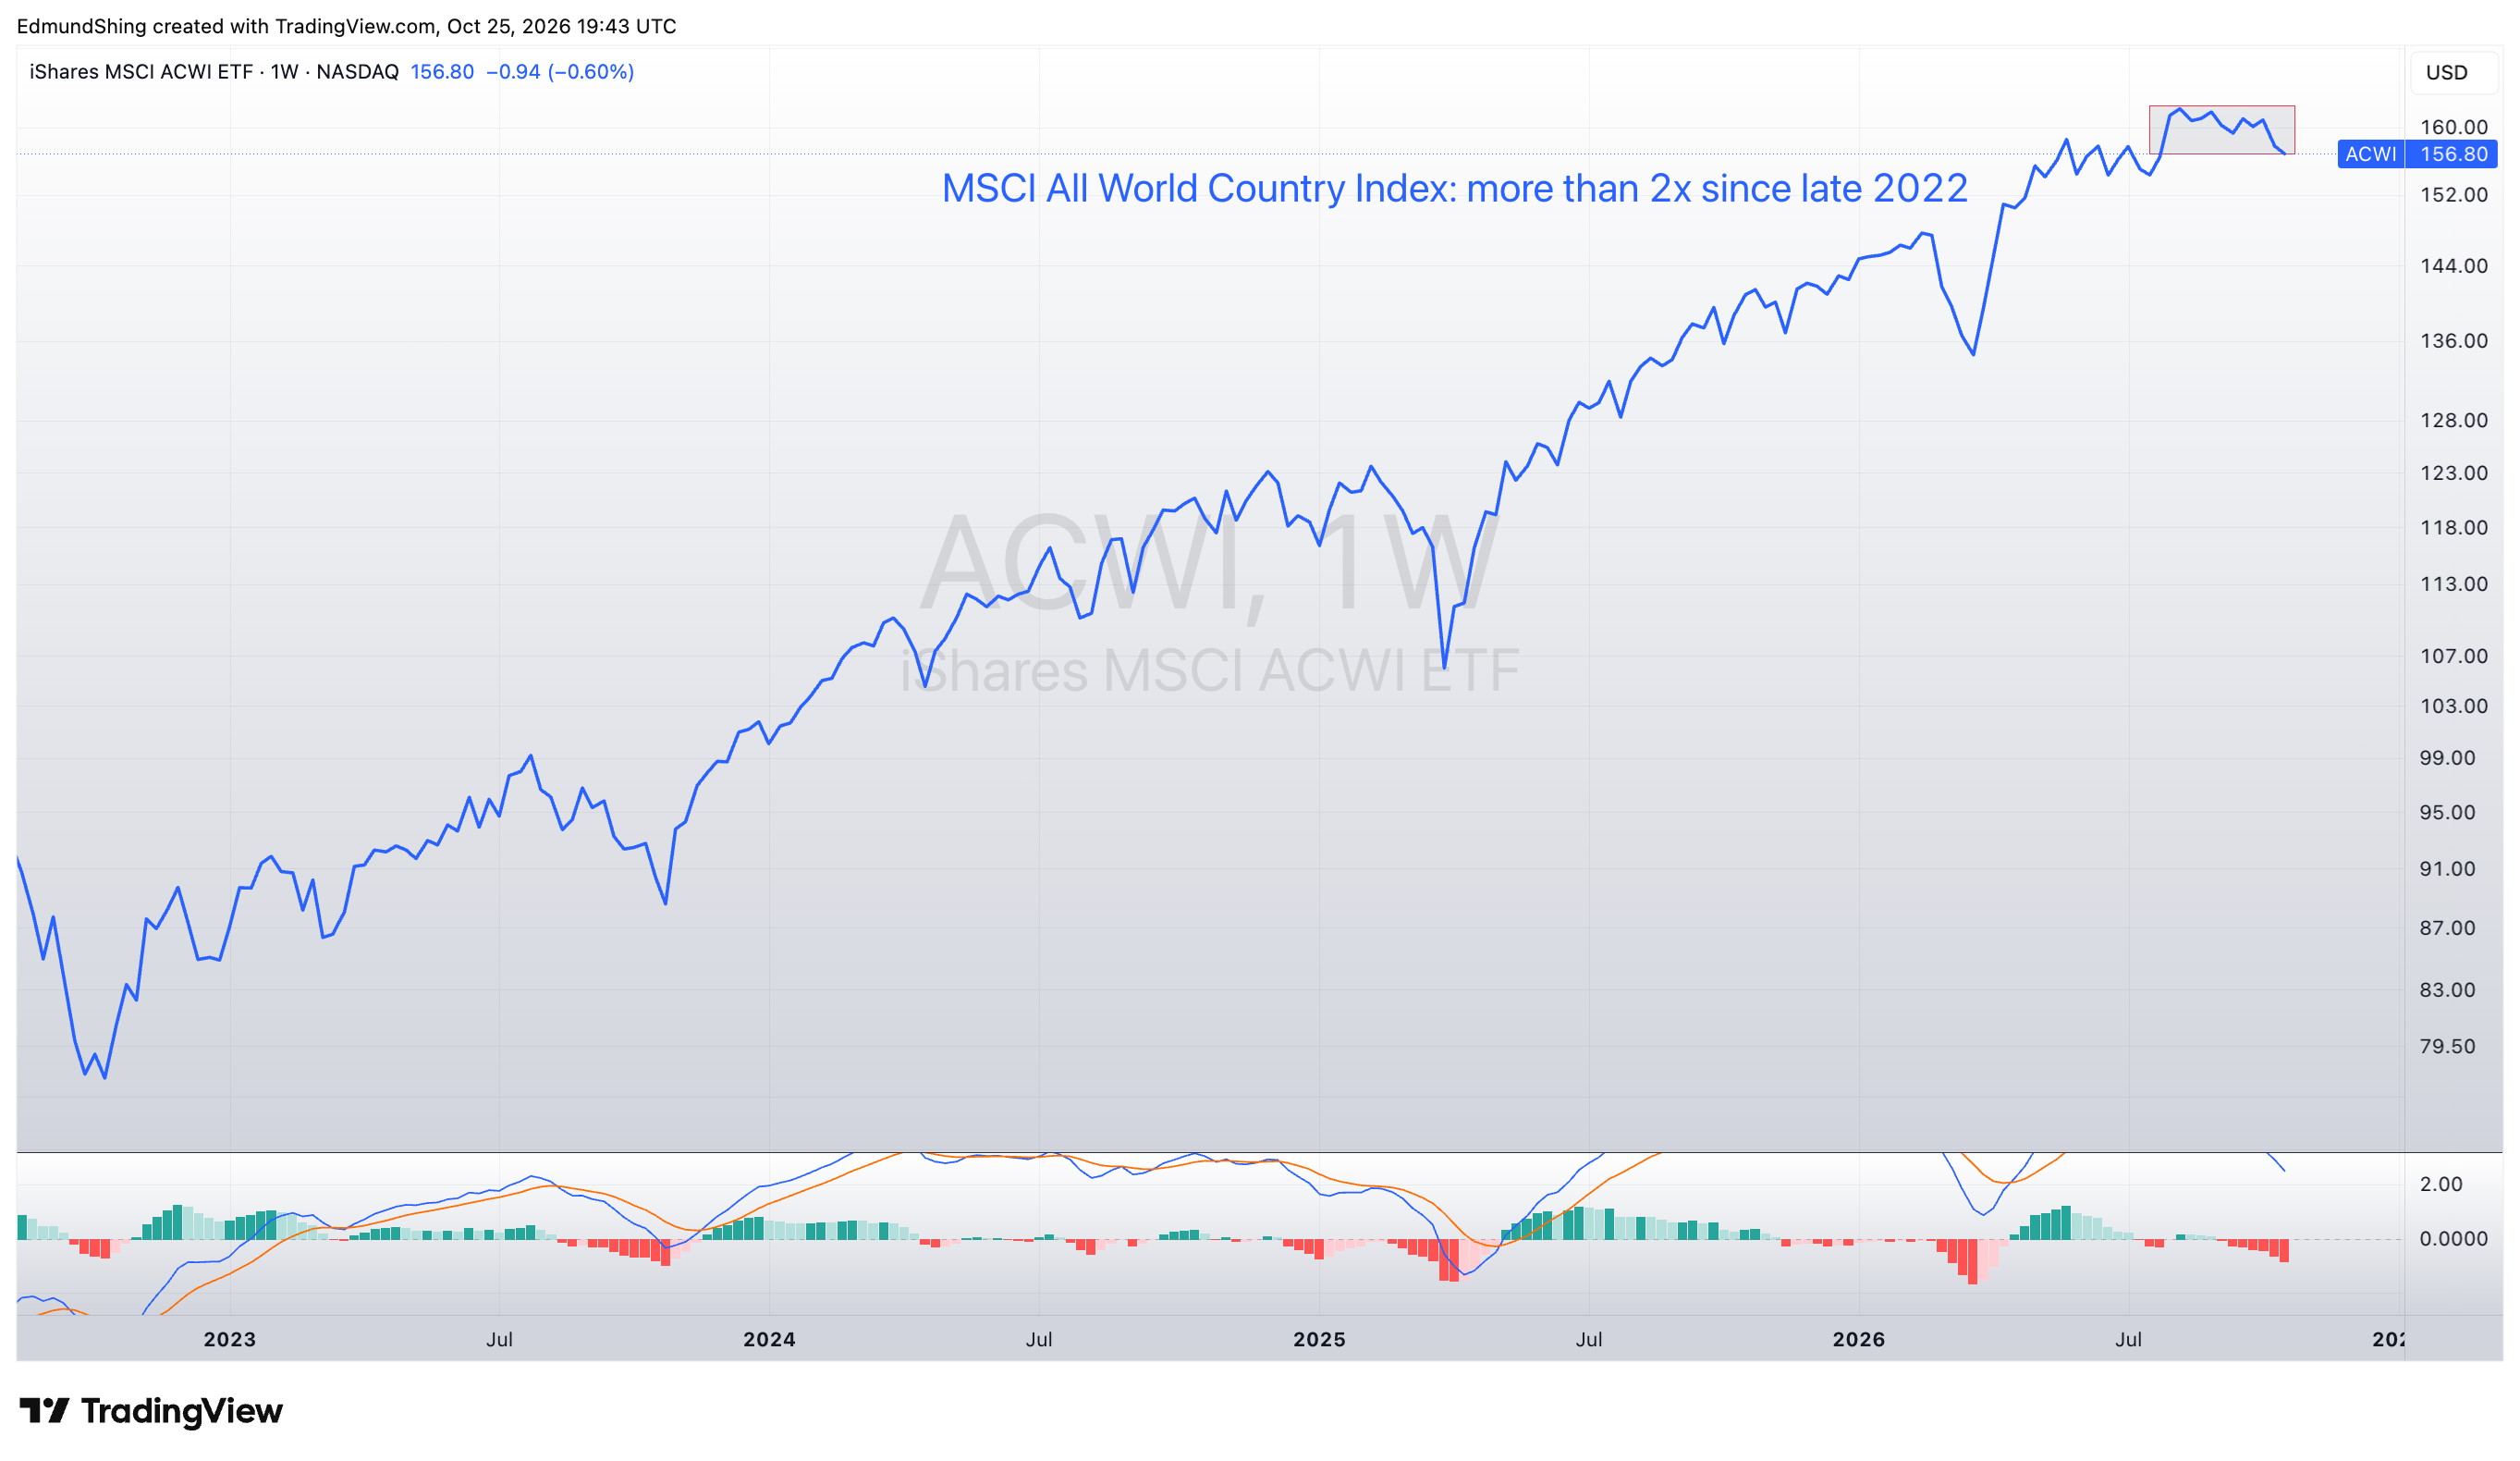
Major stock markets are still close to multi-year or all-time highs in spite of the seasonal weakness over September and October. The MSCI All-Country World Index has fallen 3% from its recent high, a similar amount for the US flagship S&P 500 index. Eurozone stocks and the tech-heavy Nasdaq 100 index have weakened more over these last 2 months, the Euro STOXX 50 down 7% and the Nasdaq 100 down 8% from peak.
However the apparent resilience of major World and US stock markets masks greater damage underneath the surface in a range of themes and sectors.
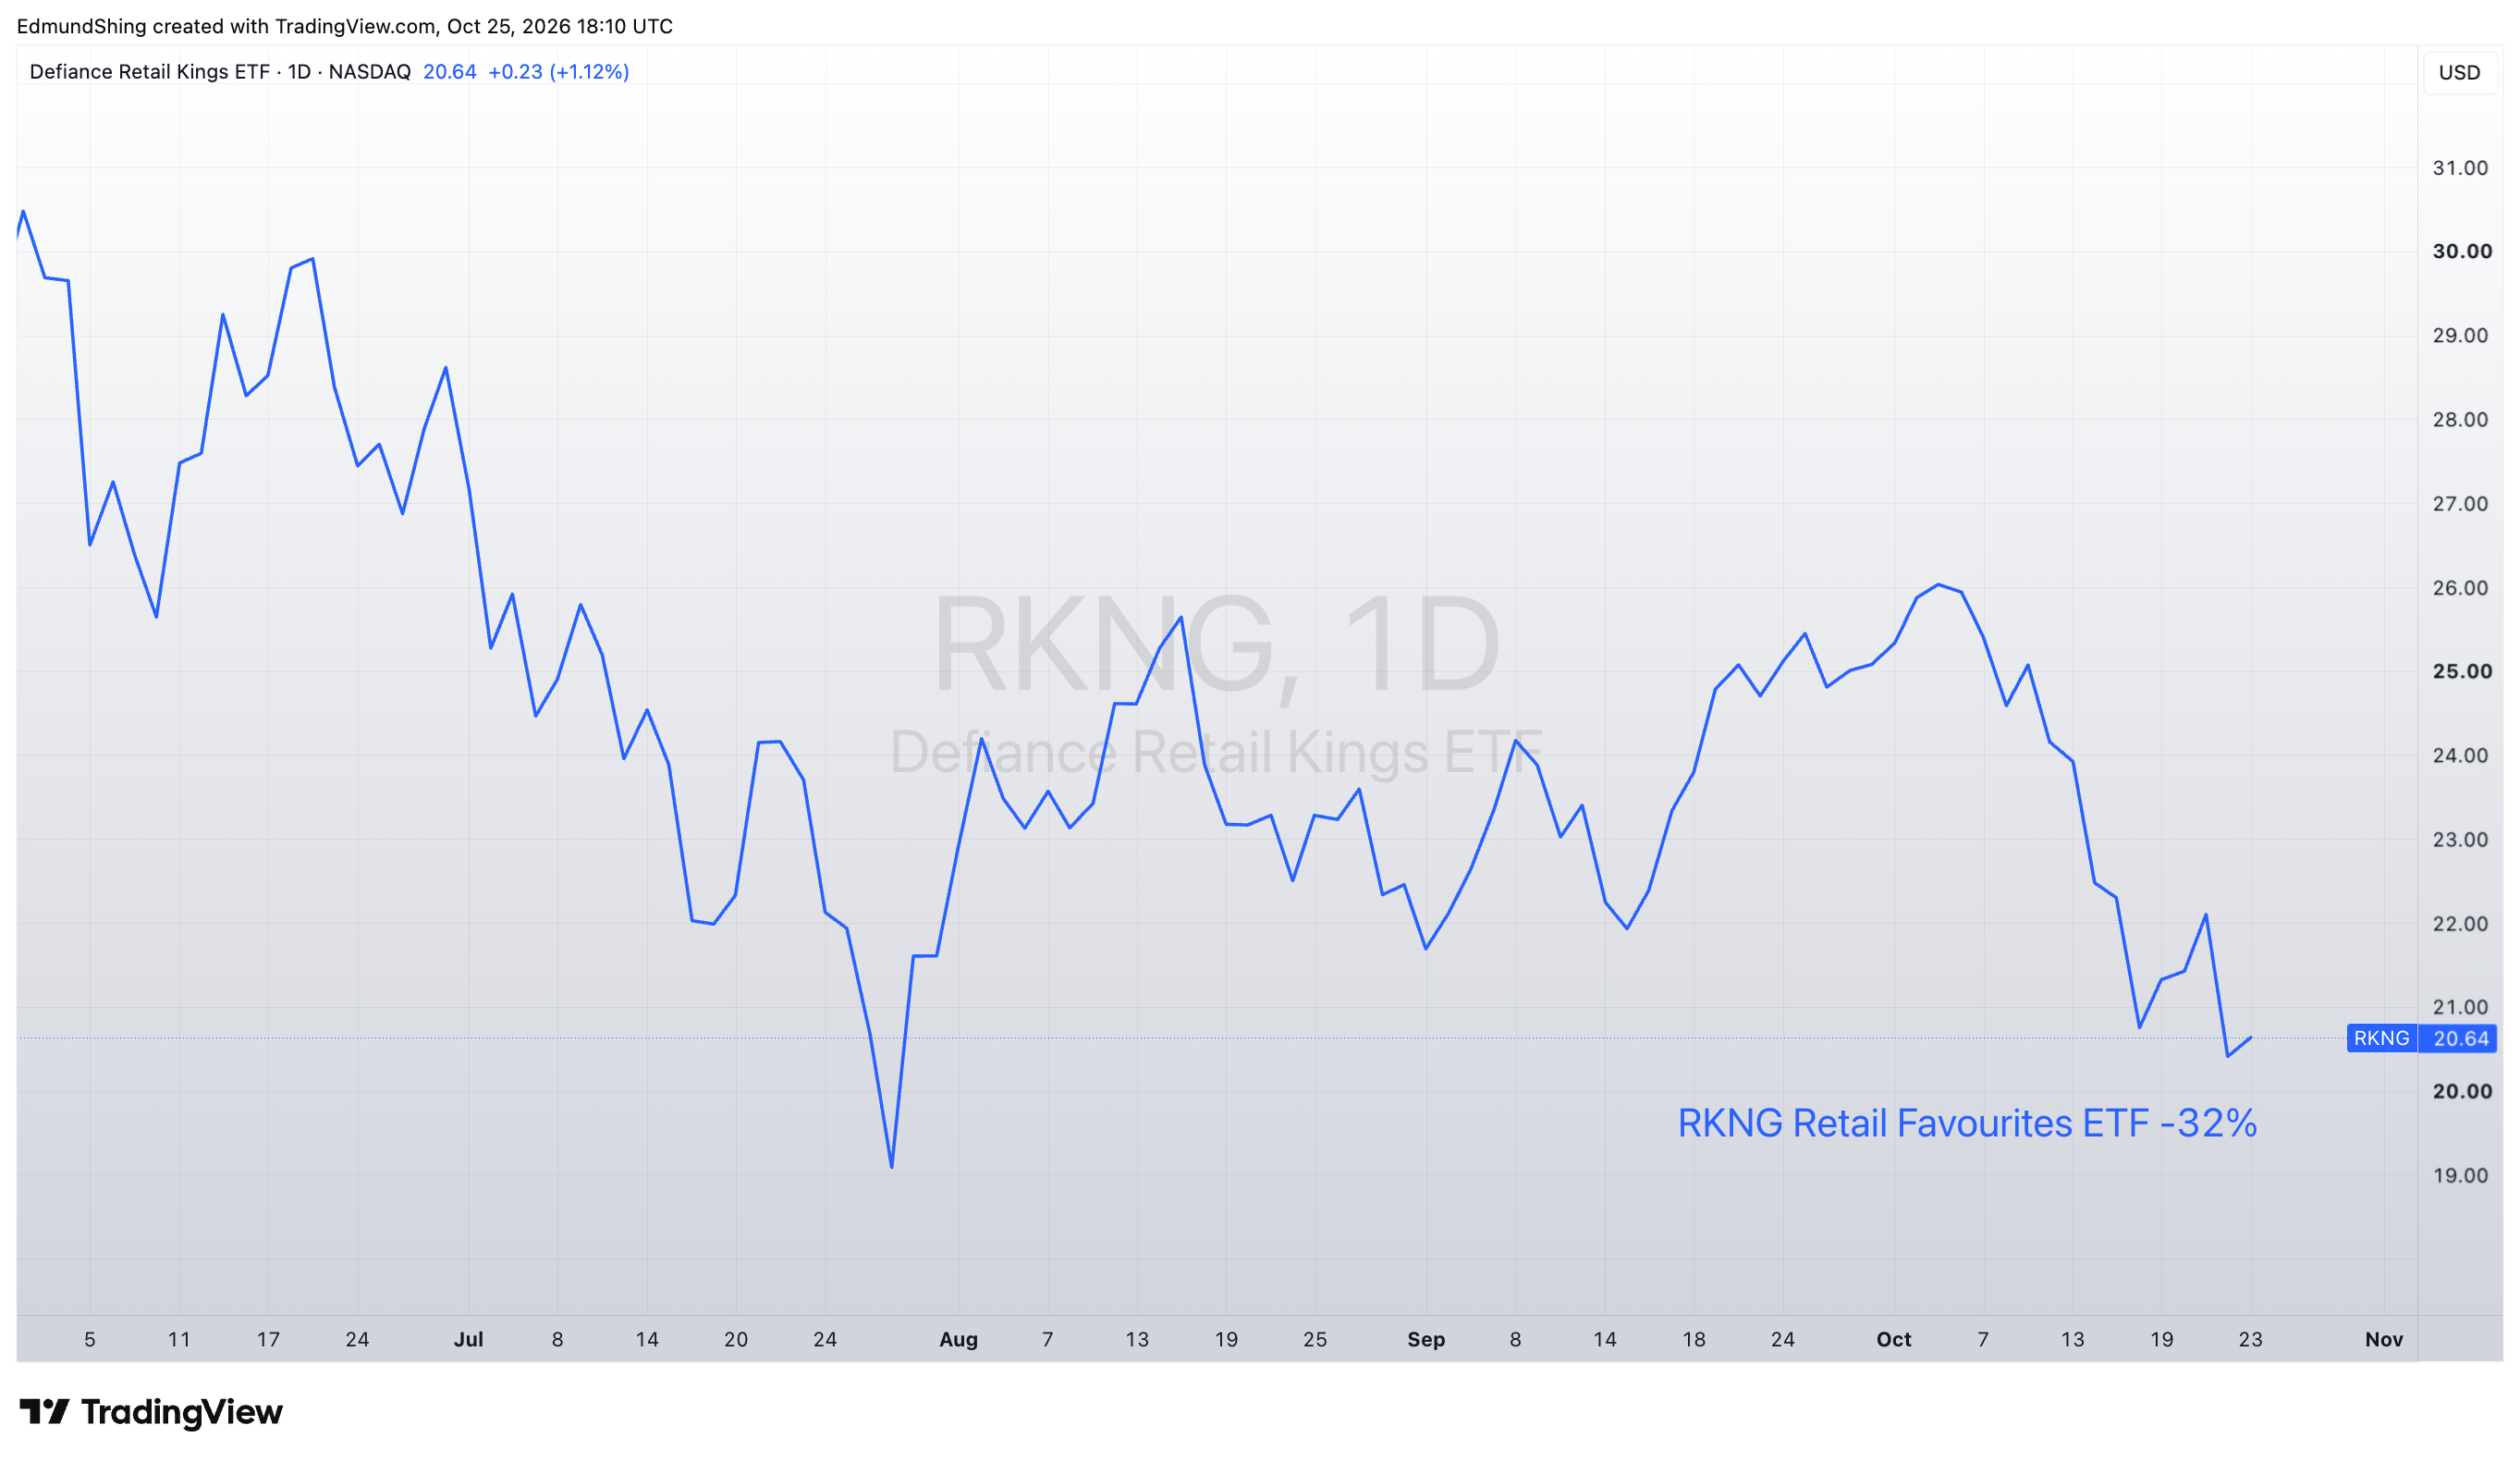
US retail investors have been hard hit by the correction in a number of formerly high-flying themes such as AI infrastructure, photonics, space and memory semiconductors. The RKNG Retail Kings ETF captures the US stocks most popular with US retail investors across technology and biotech including SpaceX, AMD and Moderna, and has fallen a cumulative 32% since June, and 21% in October alone.
The memory semiconductor ETF has corrected 42%, Space 41% and Blockchain 42% since their mid-year peaks in a violent rotation away from high-momentum growth themes back towards Energy (+11% in October) and defensive sectors such as Health care (+8%) and Consumer Staples (+13%).
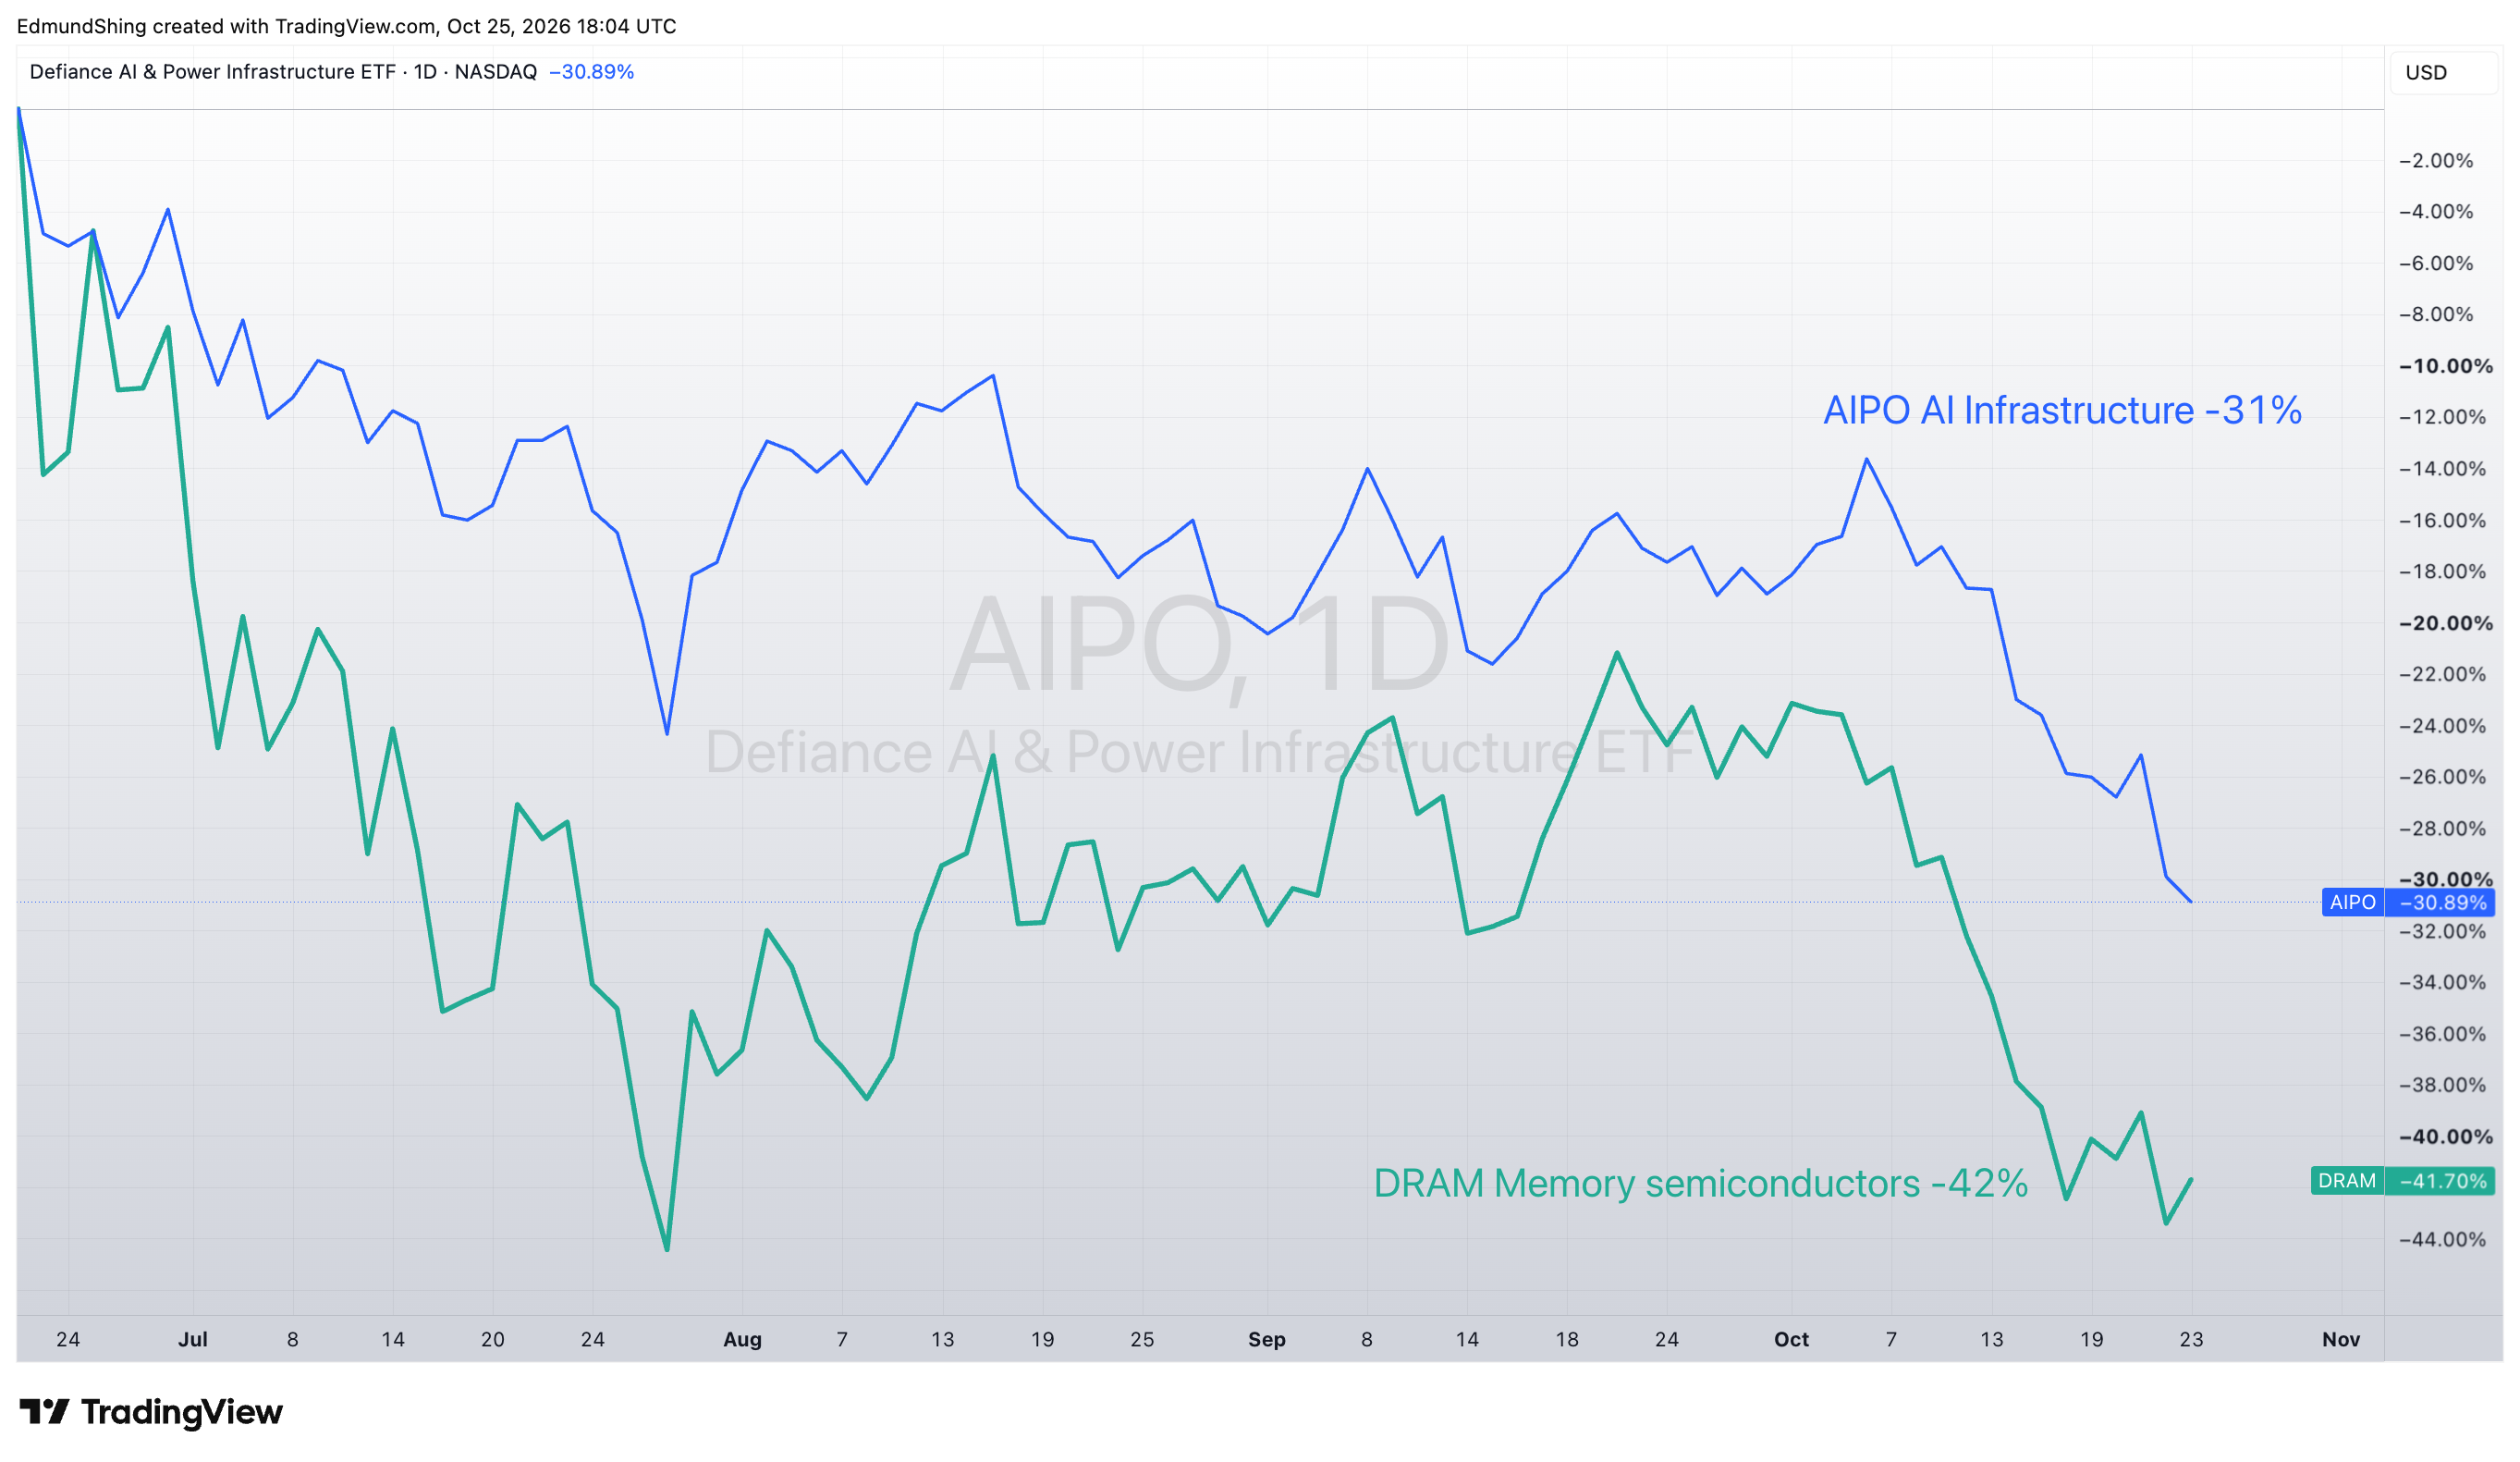
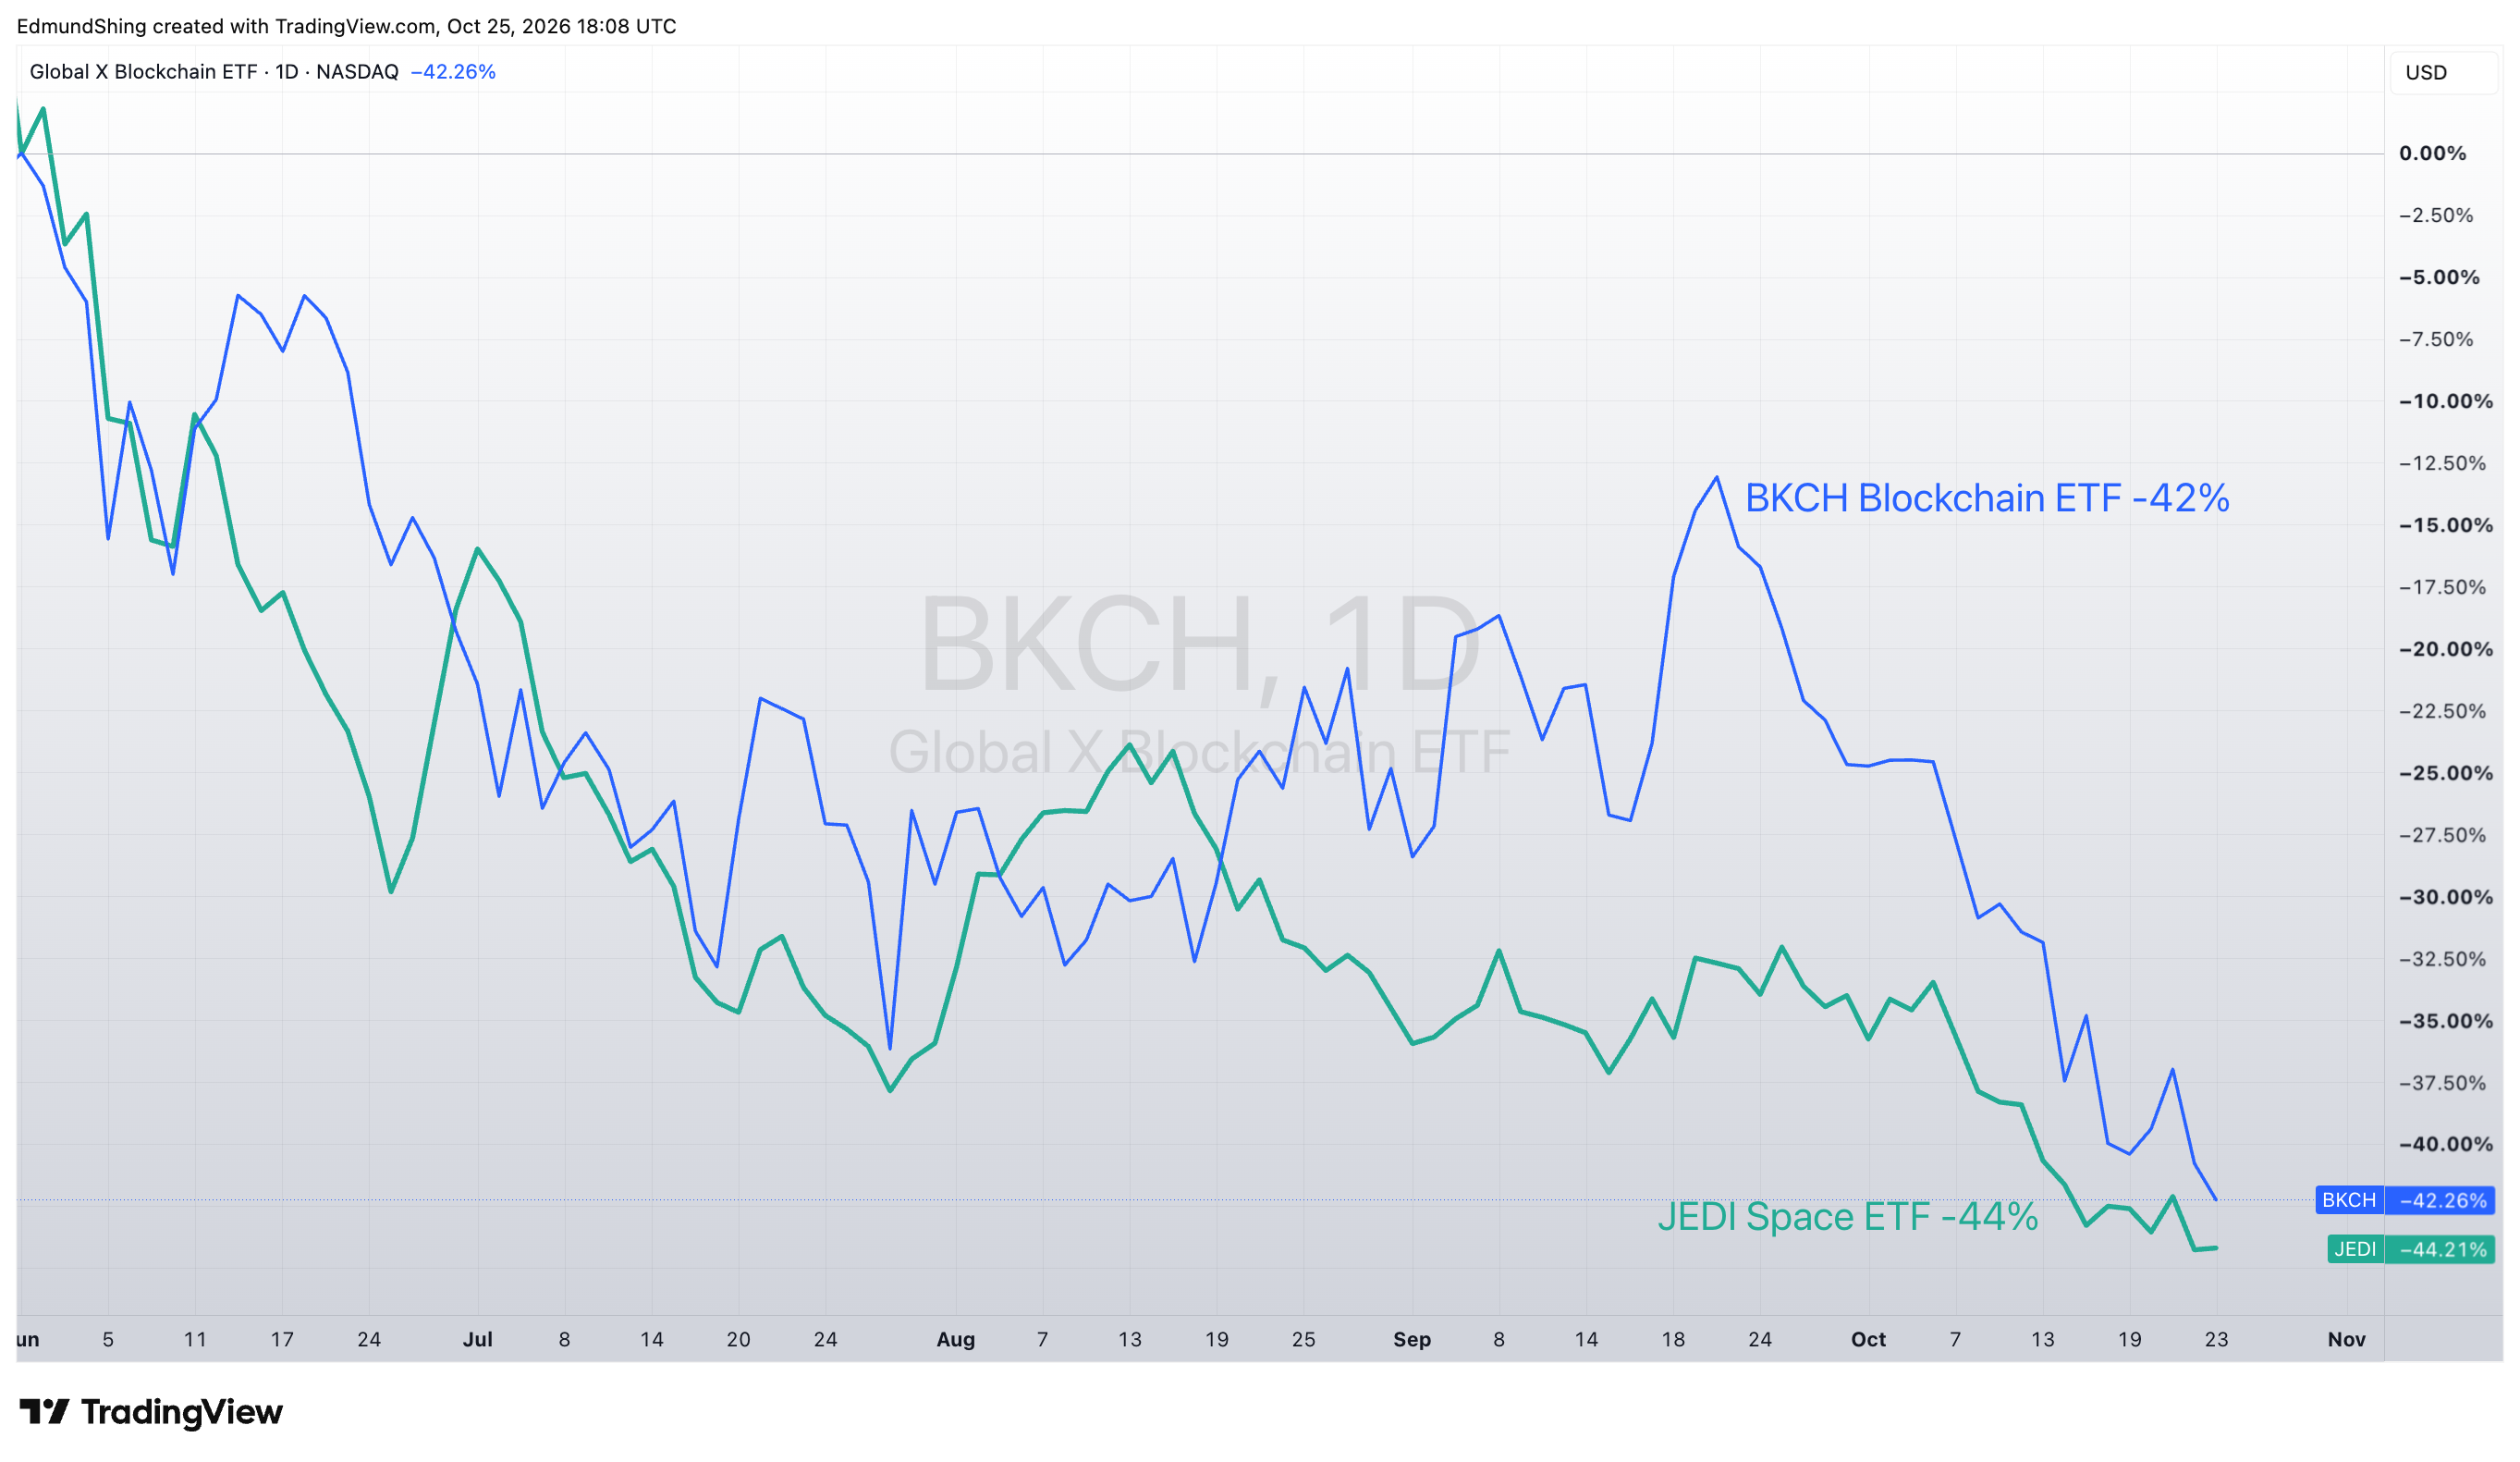
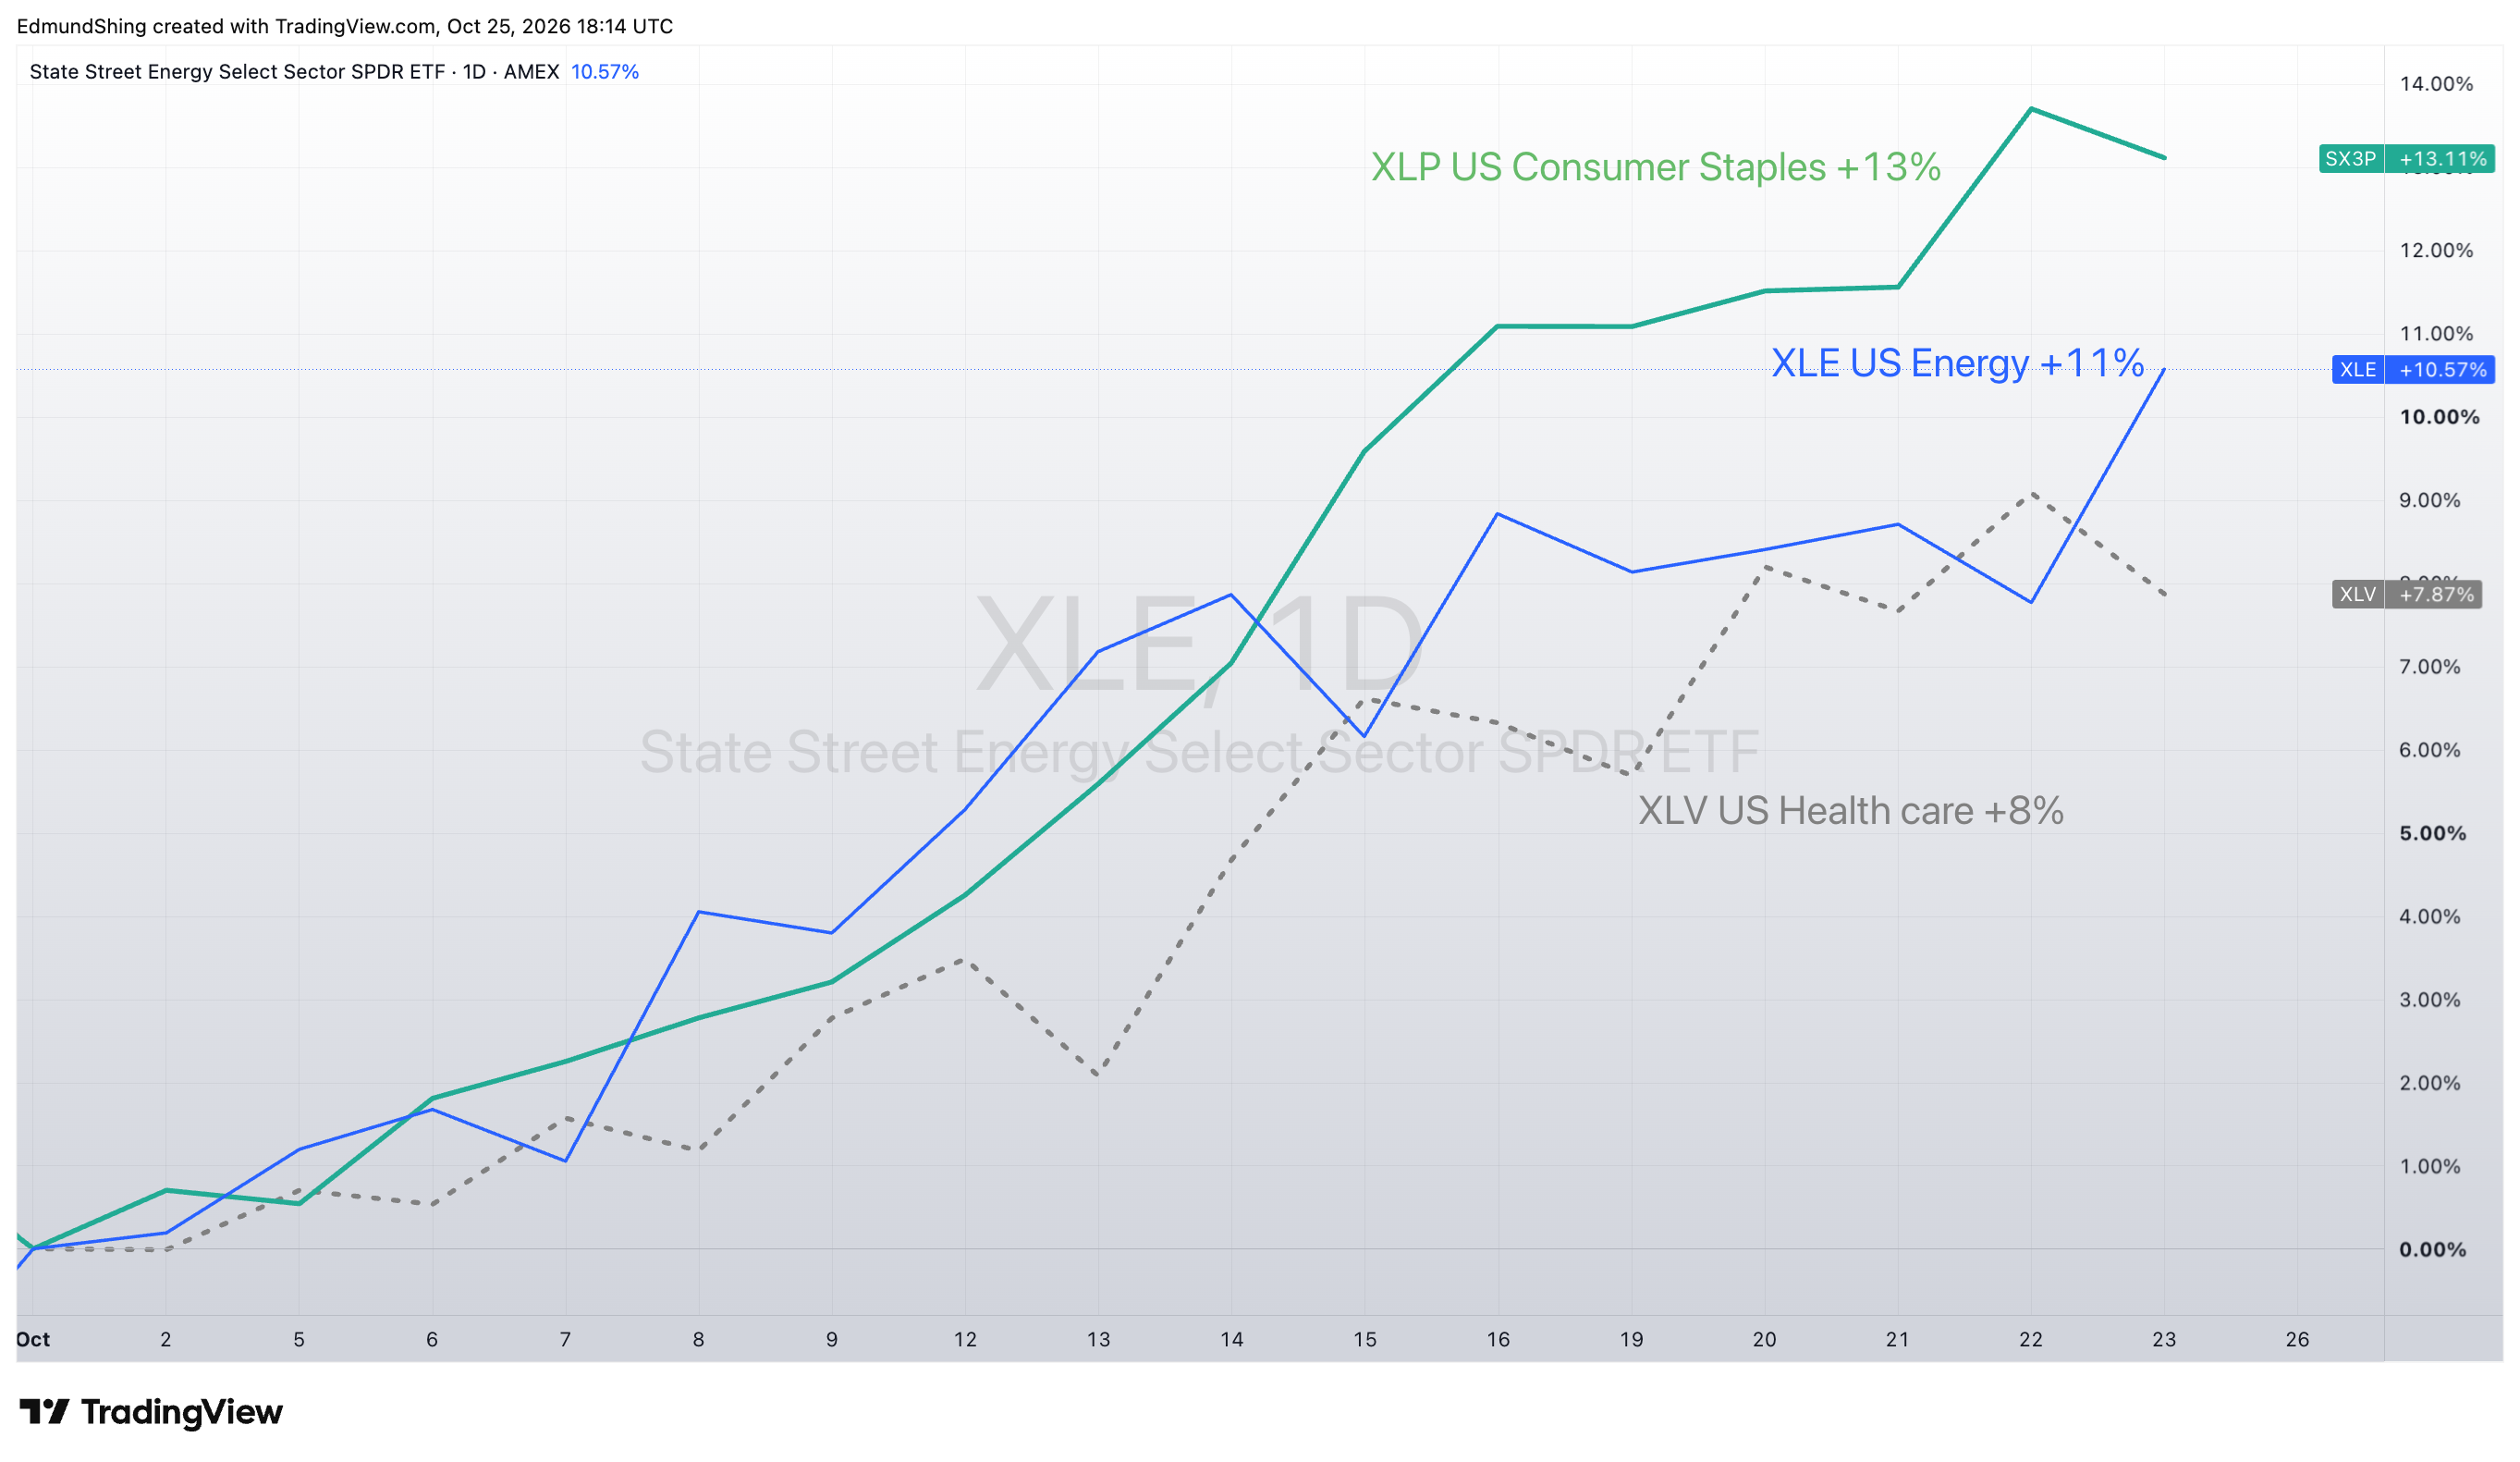
Clearly, this sector rotation back to more defensive segments of the global stock market reflects growing concern over the sustainability of the AI investment boom, with memory semiconductor companies such as Micron and SK Hynix trading at lowly 3x and 5x forecast P/E valuations.
Stock market corrections represent an opportunity given positive seasonality
In many ways, the current correction in many of the formerly high-flying themes and sectors is a healthy reset for the current bull market, as it provides a more modest entry point at lower valuations for patient investors. Despite the apparent strength of the global stock market on the surface, this correction in valuations combined with strong fundamental momentum in earnings growth and a positive post mid-term election seasonal effect should sustain this bull market in stocks for longer,
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

No comments yet
No one has commented here yet! Why not be the first one?