Market Musings 290326: Heads I win, Tails I don't lose

Market Musings 290326: Heads I win, Tails I don't lose
Podcast: Gold and precious metals: update after recent correction
(click on link in title above to listen)In this podcast, Edmund Shing, Global Chief Investment Officer and Philipp Gijsels, Chief Investment Strategist,
discuss the recent correction in precious metals markets, with a particular focus on gold and its long‑term outlook.
Heads I Win, Tails I Don't Lose...
Given that the market volatility remains high in the current context of the ongoing Iran conflict, I wanted this week to look at a number of investment ideas that I think should work more or less well whether there is near-term military de-escalation in the Gulf or not. Hence heads I win, tails I don't lose.Remember, the key variable ultimately is how quickly the Strait of Hormuz is reopened to maritime traffic, allowing for the export of crude oil, oil produces like diesel, Liquefied Natural Gas (LNG), urea (nitrogen fertiliser), aluminium and helium (necessary for semiconductor chip manufacture) to resume.
While everyone is focused on the loss of supply of crude oil to global markets, I think that the greater pressure is actually on LNG markets globally.
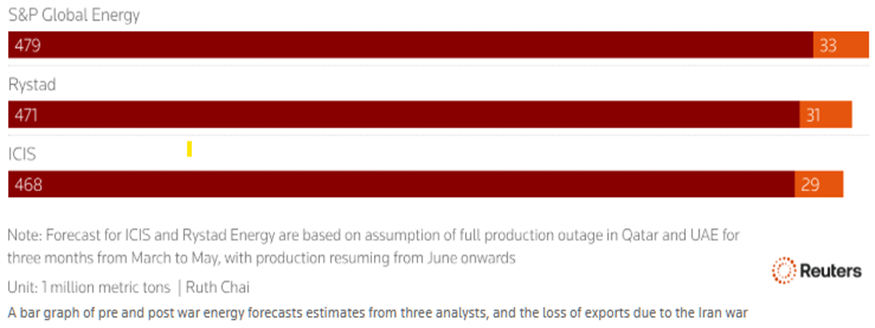
These are the current estimates of the loss of LNG exports from the Gulf as a proportion of total global LNG supply, largely to Asia and Europe.
Nearly 7% of global LNG exports to be lost this year from Gulf
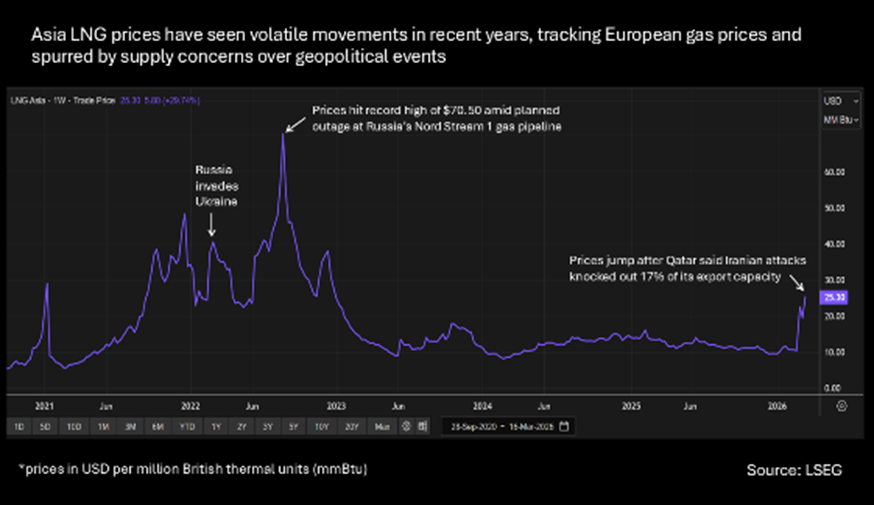
Asian LNG prices at highest since early 2023
Theme 1: US natural gas producers, infrastructure gain from higher exports
Favour North American natural gas producers, as they will be able to export in a much more favourable LNG market over the medium term.
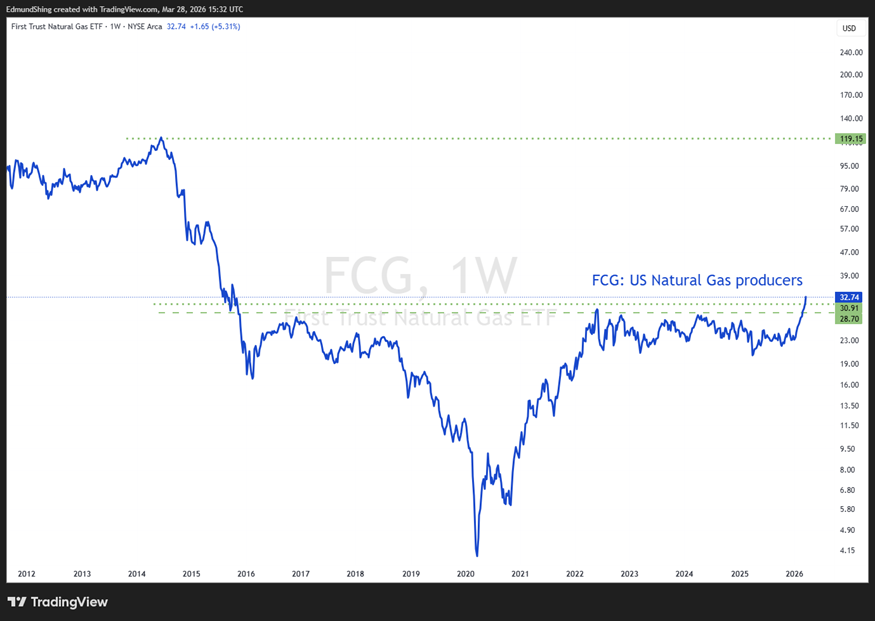
You can see in the chart below how US natural gas producers (represented by the FCG Natural Gas producers ETF in the US) have recently broken out from a multi-year consolidation pattern, exceeding the highs reached briefly in 2022 post outbreak of war in Ukraine.
Favour US natural gas producers
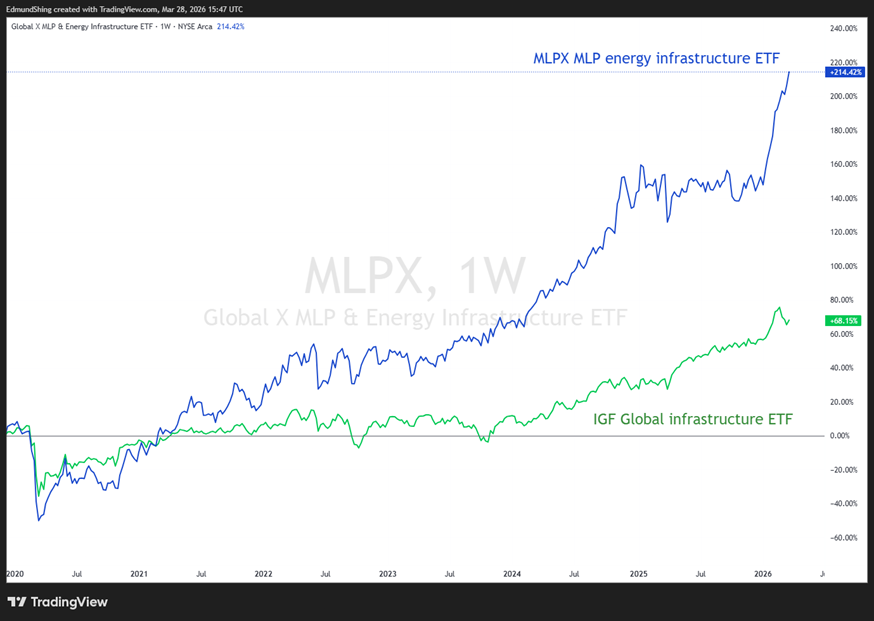
US energy infrastructure (oil & gas pipelines, gas liquefaction terminals) should do well from the higher volumes of oil and gas set for export.
US energy infrastructure has outperformed since 2021
Theme 2: Refiners should benefit from persistently high margins e.g. on diesel
Crude oil is not the only form of oil exported from the Gulf. For instance, Europe only refines 50% of the diesel it consumes, with the other 50% being imported directly from oil-exporting regions such the Gulf.
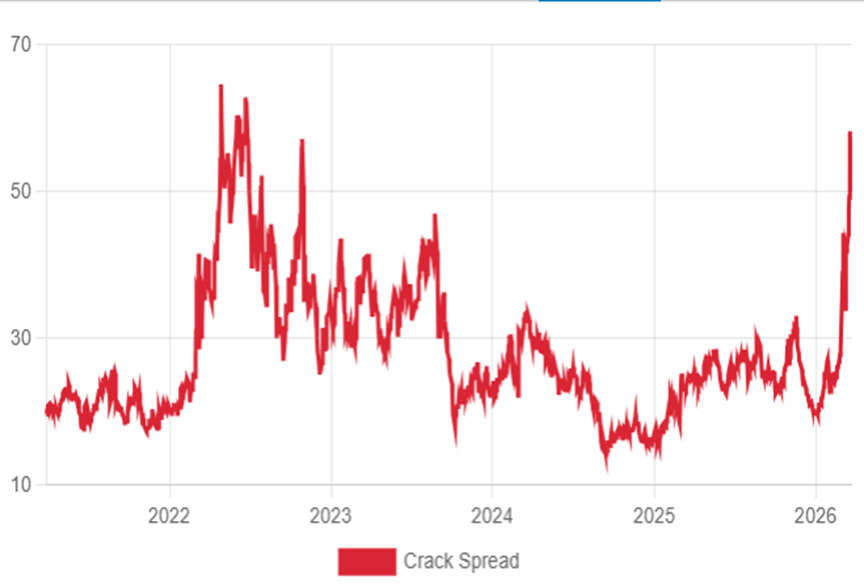
So refiners in the US and Europe should benefit from persistently higher refining margins (known also as crack spreads) given the ongoing shortage of these refined products.
3-2-1 crack spread at multi-year highs, boosts refining profits
Source: Rystad Energy
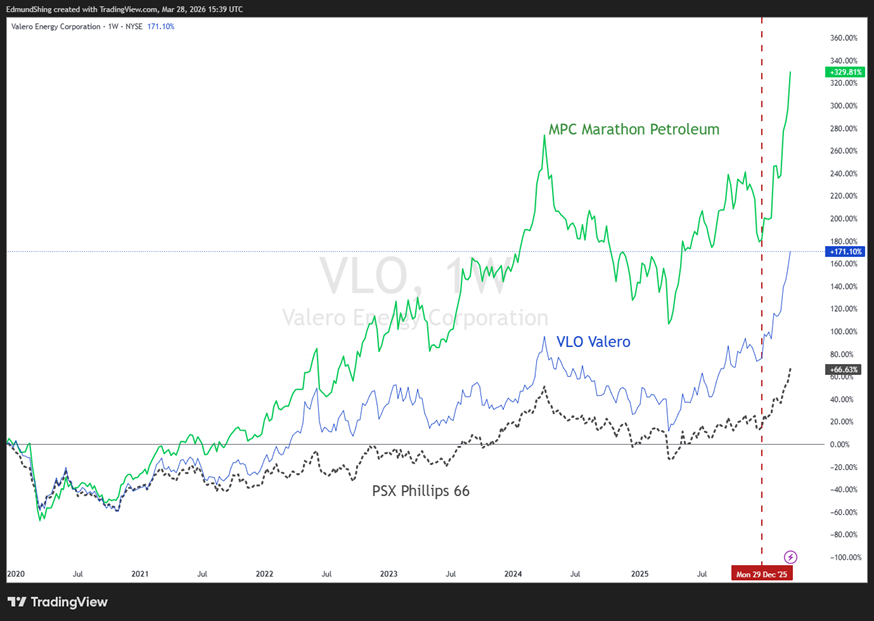
Beneficiaries in the US include Valero, Marathon and Phillips 66.
US refiners have surged in 2026
Theme 3: Maintenance, repair, new exploration to boost Oil Services
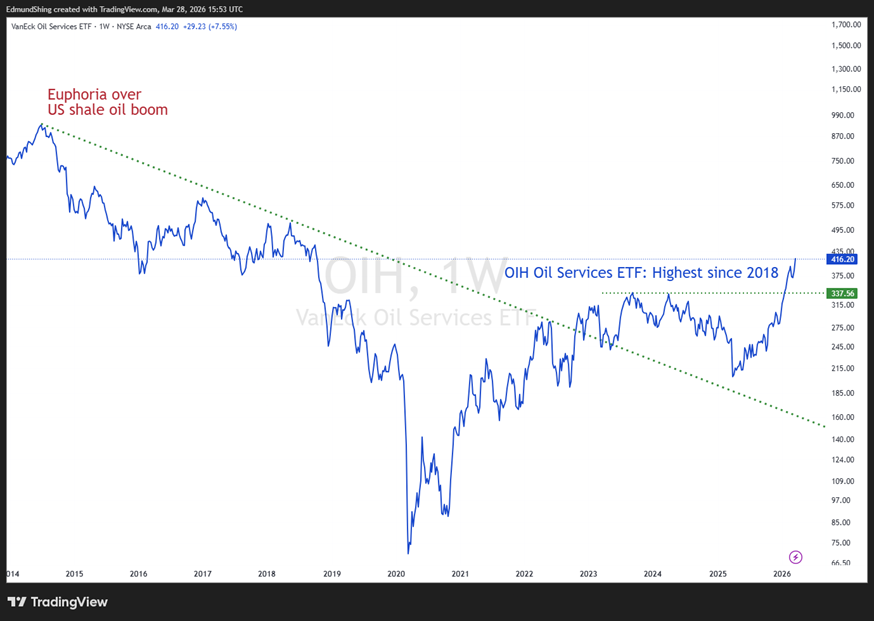
Oil & gas prices should stay sustainably higher than pre-conflict, as a) a higher geopolitical risk premium will continue to be priced into oil and gas prices, and b) as some Gulf production and refining capacity has been damaged and will take potentially years to repair/replace.
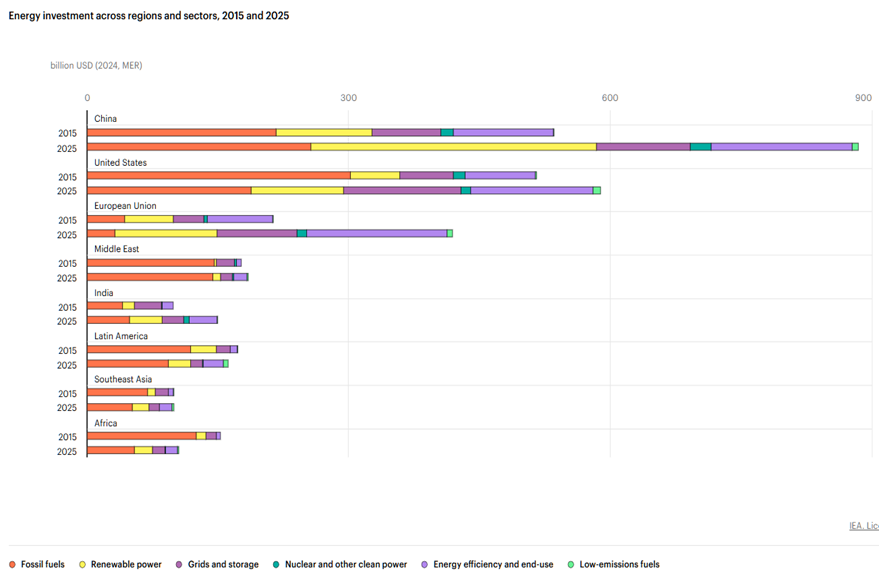
This should incentivise new oil & gas exploration and production, boosting the Oil Equipment & Services sector. Note that since 2015, most countries have spent less on investment in oil & gas , but this should change from this year onwards.
2025 fossil fuel investment lower than 2015 ex China, India
Source: IEA
Oil Equipment & Services: well-placed for new investment
Theme 4: Energy Security: securing non-Gulf oil/gas, Renewables and Batteries
The energy-importing regions of Europe and Asia will need to spend more on energy security, in order to depend even less on supplies of oil & gas from unreliable energy exporting countries such as the Gulf and Russia. This should benefit oil exporters elsewhere, notably Canada, Brazil, Mexico and Norway.
Favour oil/gas exporting countries: Latin America, Canada, Norway
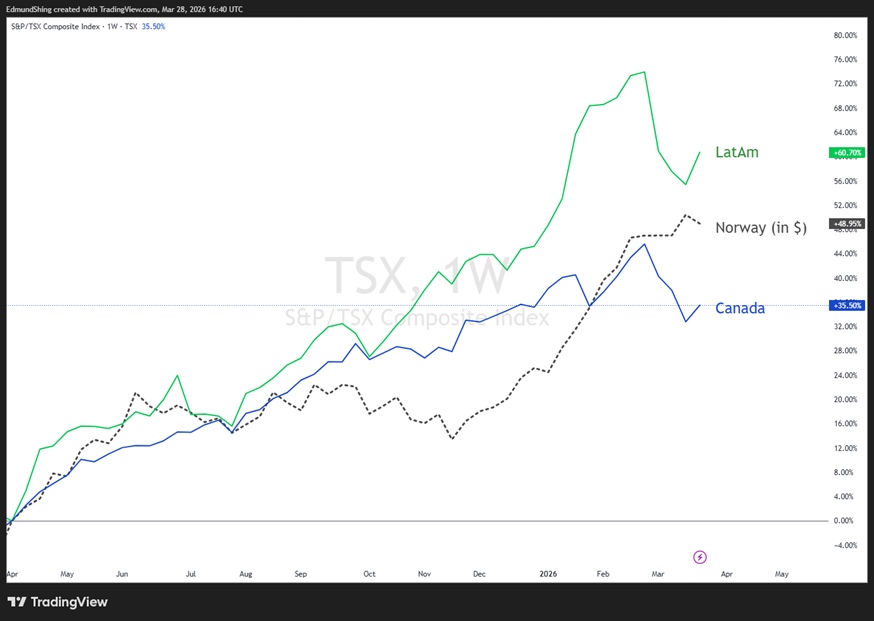
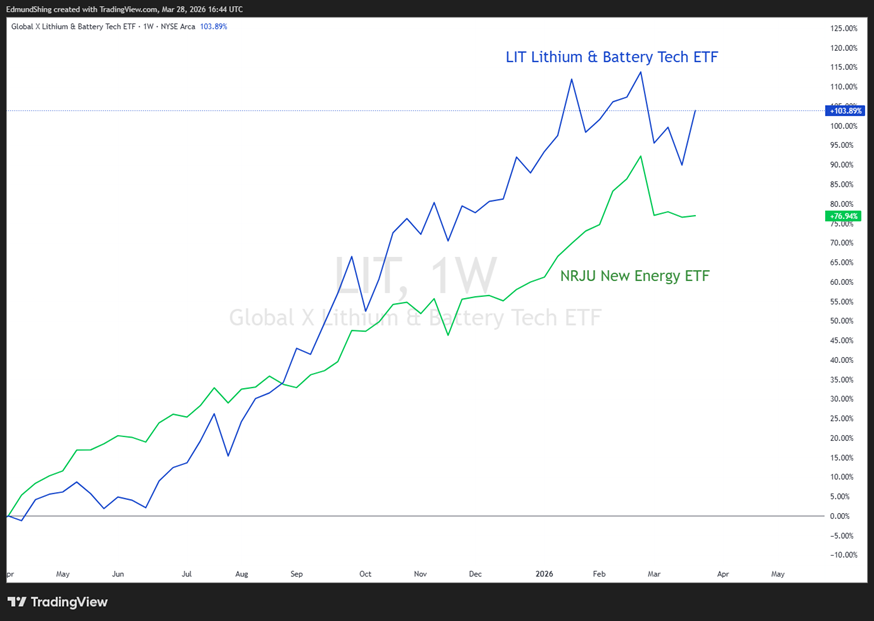
It should also boost investment in nuclear and renewable energy, including in battery electricity storage systems.
Energy security to boost battery storage, renewable energy
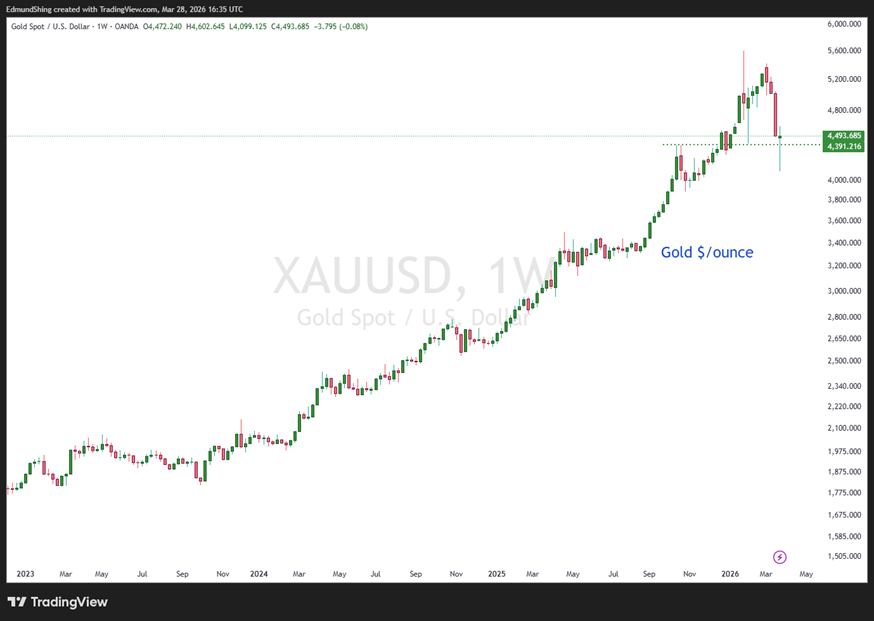
Theme 5: Gold: Finally oversold after 19% drop from peak
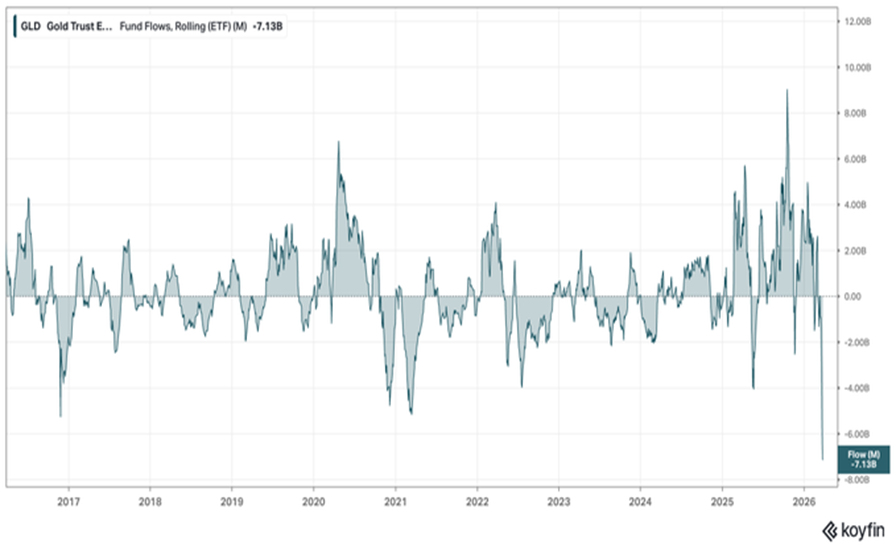
Gold has not acted as a true safe haven asset in March. But at times of extreme pressure and a liquidity squeeze such as we see today, it is common for the initial knee-jerk reaction of investors to sell what they still have profits in to offset losses and margin calls elsewhere. In this case, gold is a clear source of liquidity in the short term.
But this also happened in 2000, 2008 and 2022. In each case, gold sold off by 19%-29% in the short term, but then this gave way to a triple-digit percentage rally thereafter in each case. After the gold price correction of c. 17% in March, gold should ultimately act as a true safe haven and portfolio diversifying asset once again.
Gold: Heaviest selling pressure in 10 years - $7bn
Gold: we maintain a $5500/oz 12m target (+20%)
Theme 6: Commodities: a good hedge against global supply disruption
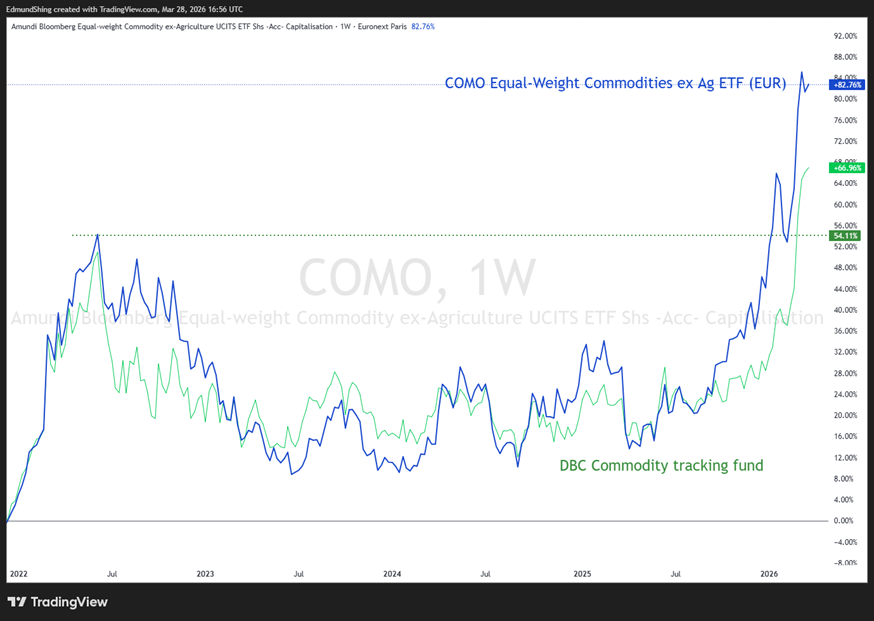
Commodity ETFs have hedged investors well this year so far, with broad commodity ETFs up over 20% in US dollars and euros so far.
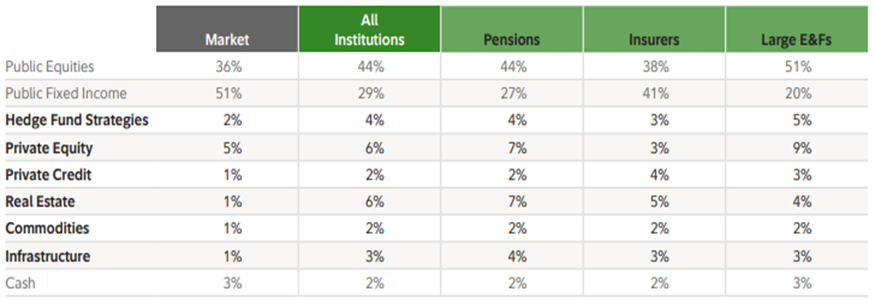
But investors continue in general to hold only very small portfolio allocations to commodities, suggesting potential for greater asset allocation in future particularly for those investors looking to explicitly hedge against the prospect of persistently higher inflation.
Institutional investors: only 2% allocated to commodities
Source: Fidelity
Broad Commodity ETFs exceed 2022 highs
Fingers crossed for some improvement on the geopolitical front in the week ahead,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

16 comments
Hi Edmund, What are the ETFs or companies to buy when the conflict in iran ends for a quick recovery? Thanks
Great podcast on Gold. Quite agree with its conclusion. Thanks .
To Stockopedia the chart on Global X Msci Norway Etf (LON:0IXG) is wrong, a pure staight line as if drawn with a ruler over various time periods, but incorrect !
Hi Edmund,
Great article, if you have the appetite for risk then there is some genuine money to be made. Definitely following theme 4 and 5, probably mention the North Sea as well. The UK political appetite looks to be trending towards punishing the downstream industry compared to upstream.
My entire portfolio since the beginning of the month is made up of oil & gas producers with a gold miner. I wouldn’t recommend my portfolio because the risk management is way out of kilter, the only thing which mitigates the risk is my hypothesis behind my craziness. Just for disclosure my rough weightings today are:-
Moving away from commodities and impact on consumer behaviour, one industry which I am paying attention too is European transport infrastructure in particular Aena SME SA (MCE:AENA) , with the Middle East tourism hotspots being off-limits for the majority, plus they are finalising deals for Leeds/Bradford and Newcastle airports. Obviously there are some risks just to give you one:- demand destruction from the airlines having to pass on the jet fuel bill and killing passenger numbers!
COMO is in Euros, anything for UK investors not wanting currency risks?
hi there, COMG is the same ETF but priced in GBP.
Thanks Edmund
What about Woodside Energy (NYQ:WDS) ? (I hold).
"Australia became the world’s second-largest LNG exporter when Qatar shut down production this month" (copied from an announcement in their news section).
Yes that also makes sense...
Hi Edmund,
Thanks for your weekend work, much appreciated. On gold, we have had the news that the Turkish Central bank sold down some of their gold holding in the last week to help stabilise the Lira and for geopolitical reasons- do you have a sensing if this is an isolated case or are other central banks also selling some gold?
Thanks
Alb
¨Perhaps certain Gulf states have also sold some gold to aid short-term liquidity, but I think this selling pressure will ease soon...
ok interesting...thanks the reply Edmund
Couldn't hear the podcast, the volume was too low.
Sorry about that, will work on the audio quality for next time.
COMG seems another of those funds where the constituents have nothing to do with the title. Main holdings - Amazon, Nvidia, Apple, Microsoft, Berkshire, Tesla, Meta, Home Depot. Doing well though!
I think you have a different comg Roger. If you put COMG in the search box of justetf, there is access to the latest factsheet which show the breakdown. It's all commodities - metals, oil, gas. It is an index though, not individual holdings.