Market Musings 290625: Stocks shrug off MidEast conflict

Market Musings 290625: Stocks shrug off MidEast conflict
Investment Strategy Podcast:
Our 2025 Investment Themes Mid-Year Update
In this podcast, Edmund Shing, Global Chief Investment Officer and Guy Ertz, Deputy Chief Investment Officer, unveil the mid-year update of their 2025 Investment Themes.
Where is the market stress?
Over the last couple of weeks or so, world news headlines have been dominated by the escalation of the Iran-Israel conflict, including the surprise 22 June US attack on Iranian nuclear facilities including the Fordow site.
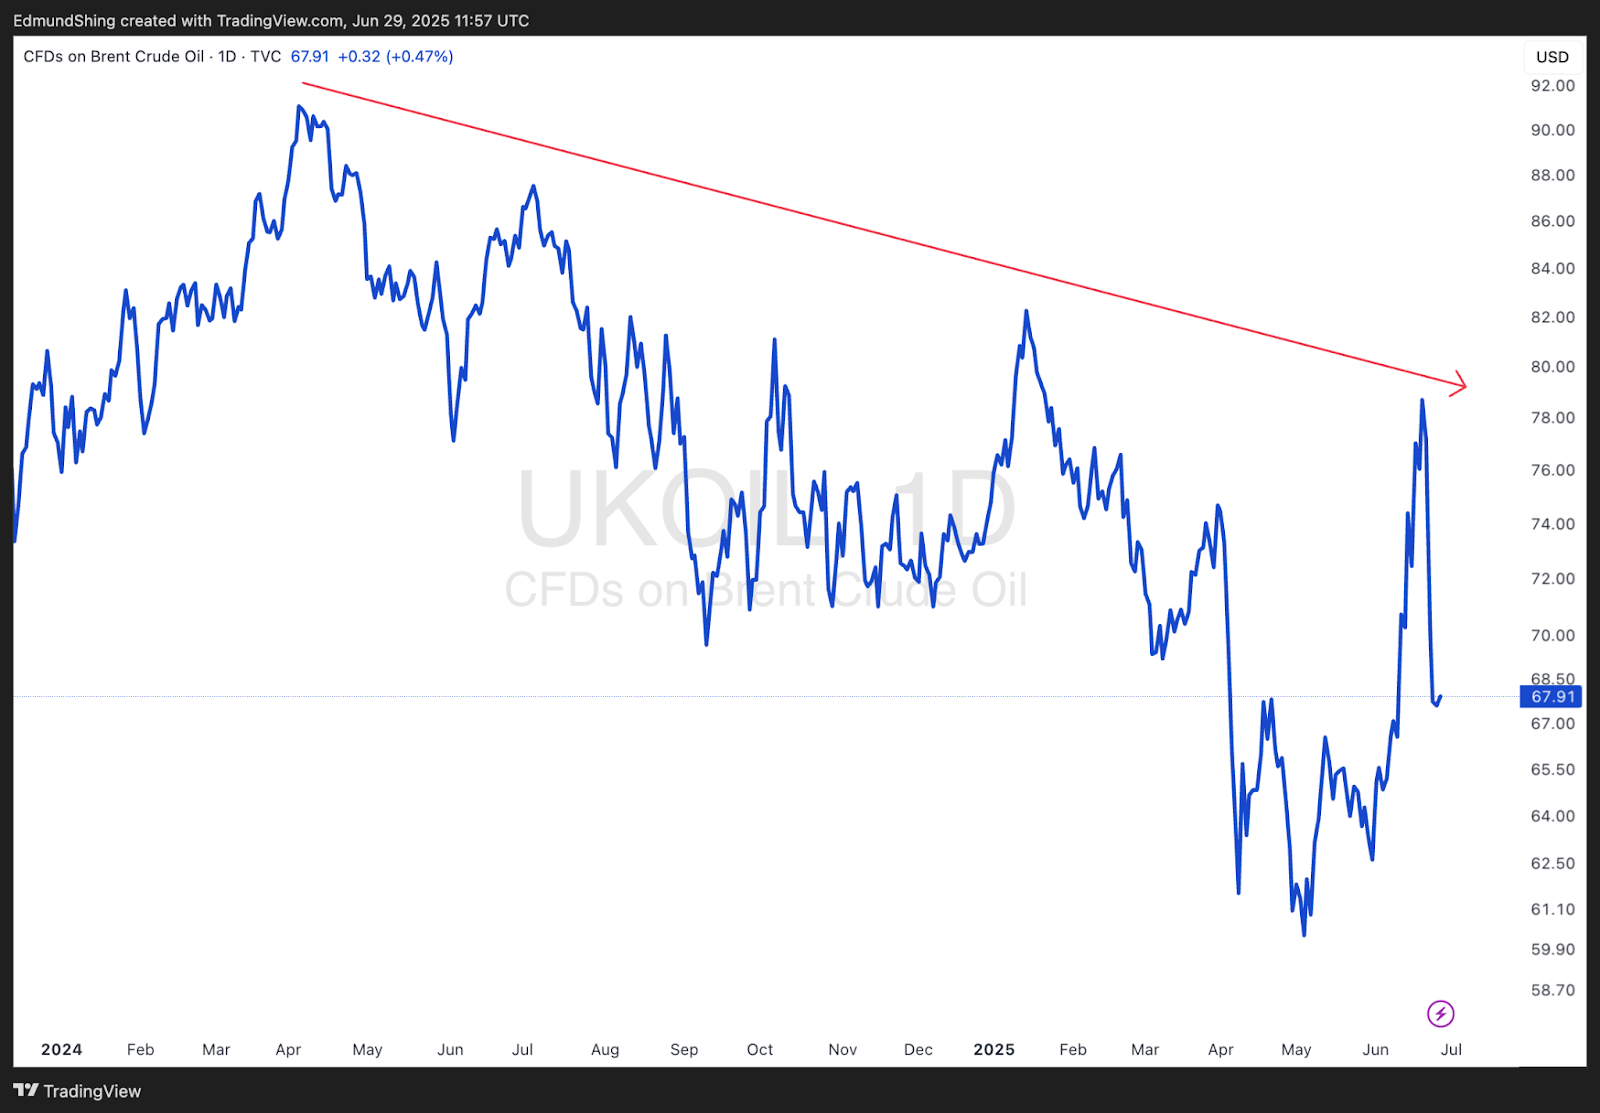
Market reaction to this conflict has calmed in recent days thanks to the announcement of a ceasefire, which though fragile, seems to hold for now. The Brent crude oil benchmark initially rose over 20% to $79/barrel, before then easing $11 to $68. Note that oil prices are thus still far below their levels of a year ago, driving headline inflation lower.
Brent crude oil remains in a long-term downtrend despite the conflict
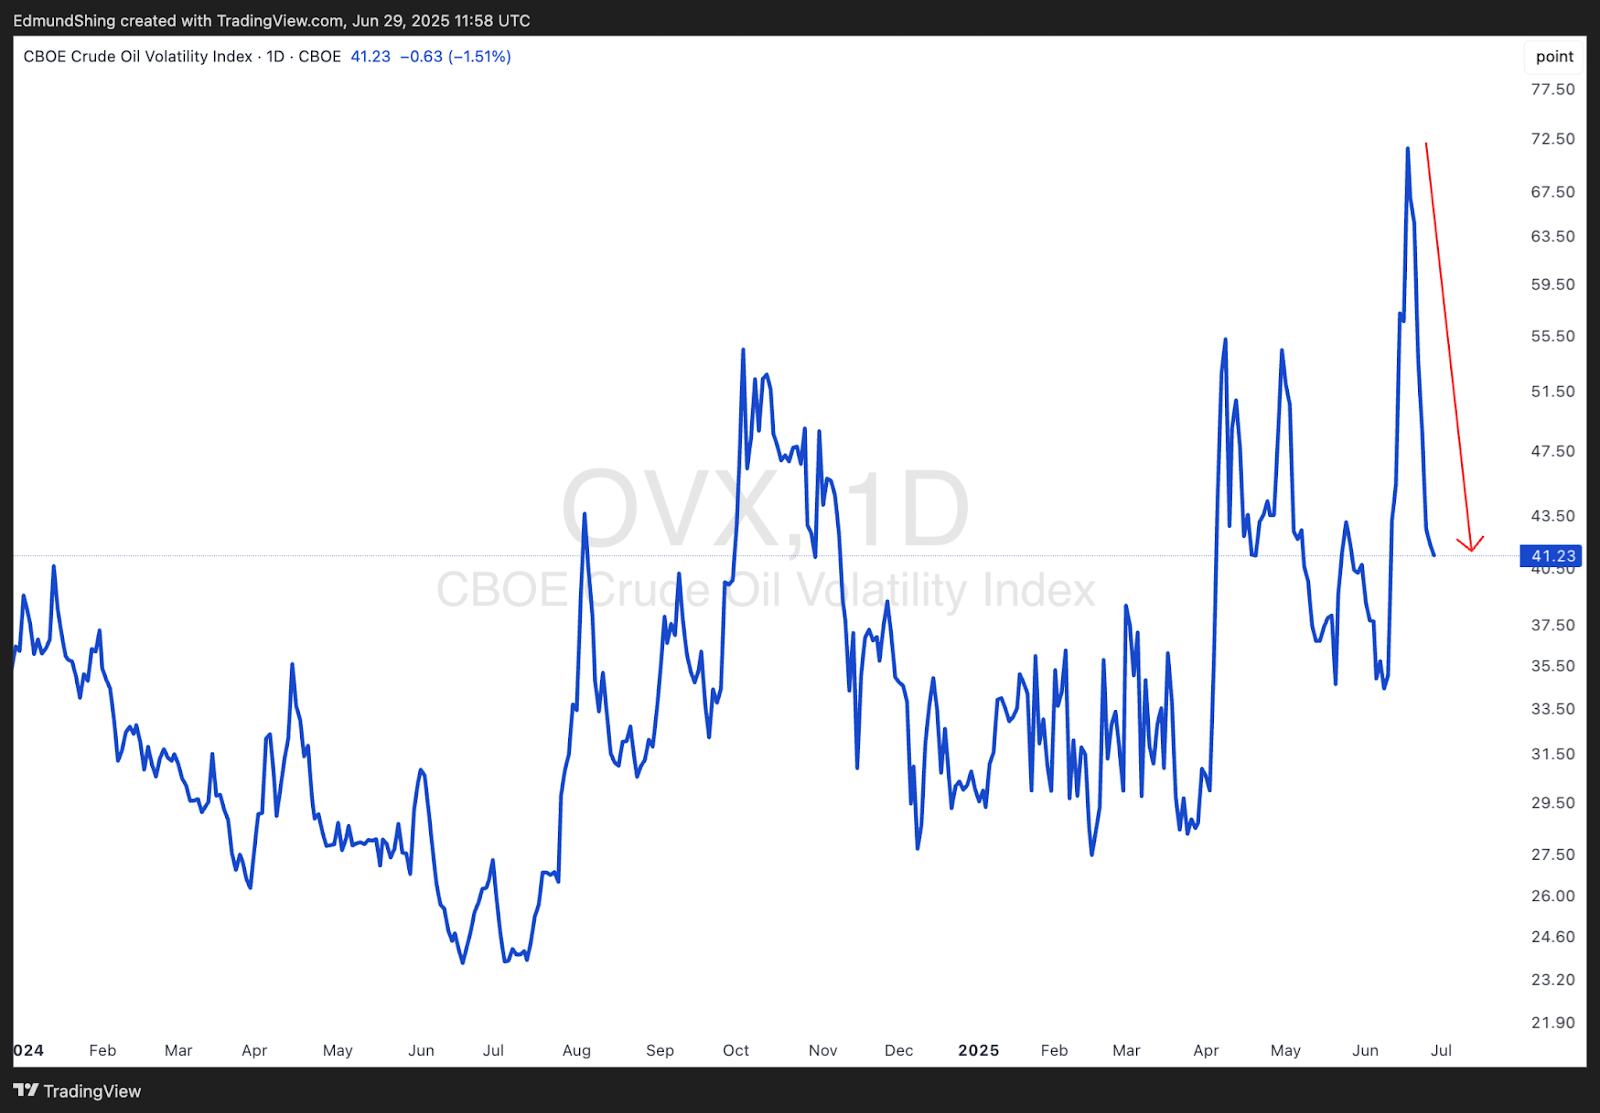
Equally, oil price volatility as measured by the OVX index spiked initially before easing lower…
OVX oil price volatility has eased post ceasefire
Given the very short time that the oil price remained elevated, we should not expect a significant impact from the conflict on petrol and diesel prices at the pump. Hence little long-term impact should be seen either on global economic growth or on inflation rates - this would require oil prices to stay at even higher prices for an extended period, which is so far at least, not the case.
Ultimately, the global oil market remains well-supplied with no major disruption to oil shipments e.g. through the Straits of Hormuz. In addition, Saudi Arabia and the United Arab Emirates together have 6 million barrels/day of oil production capacity that they can bring online rapidly if Iranian oil supplies were disrupted.
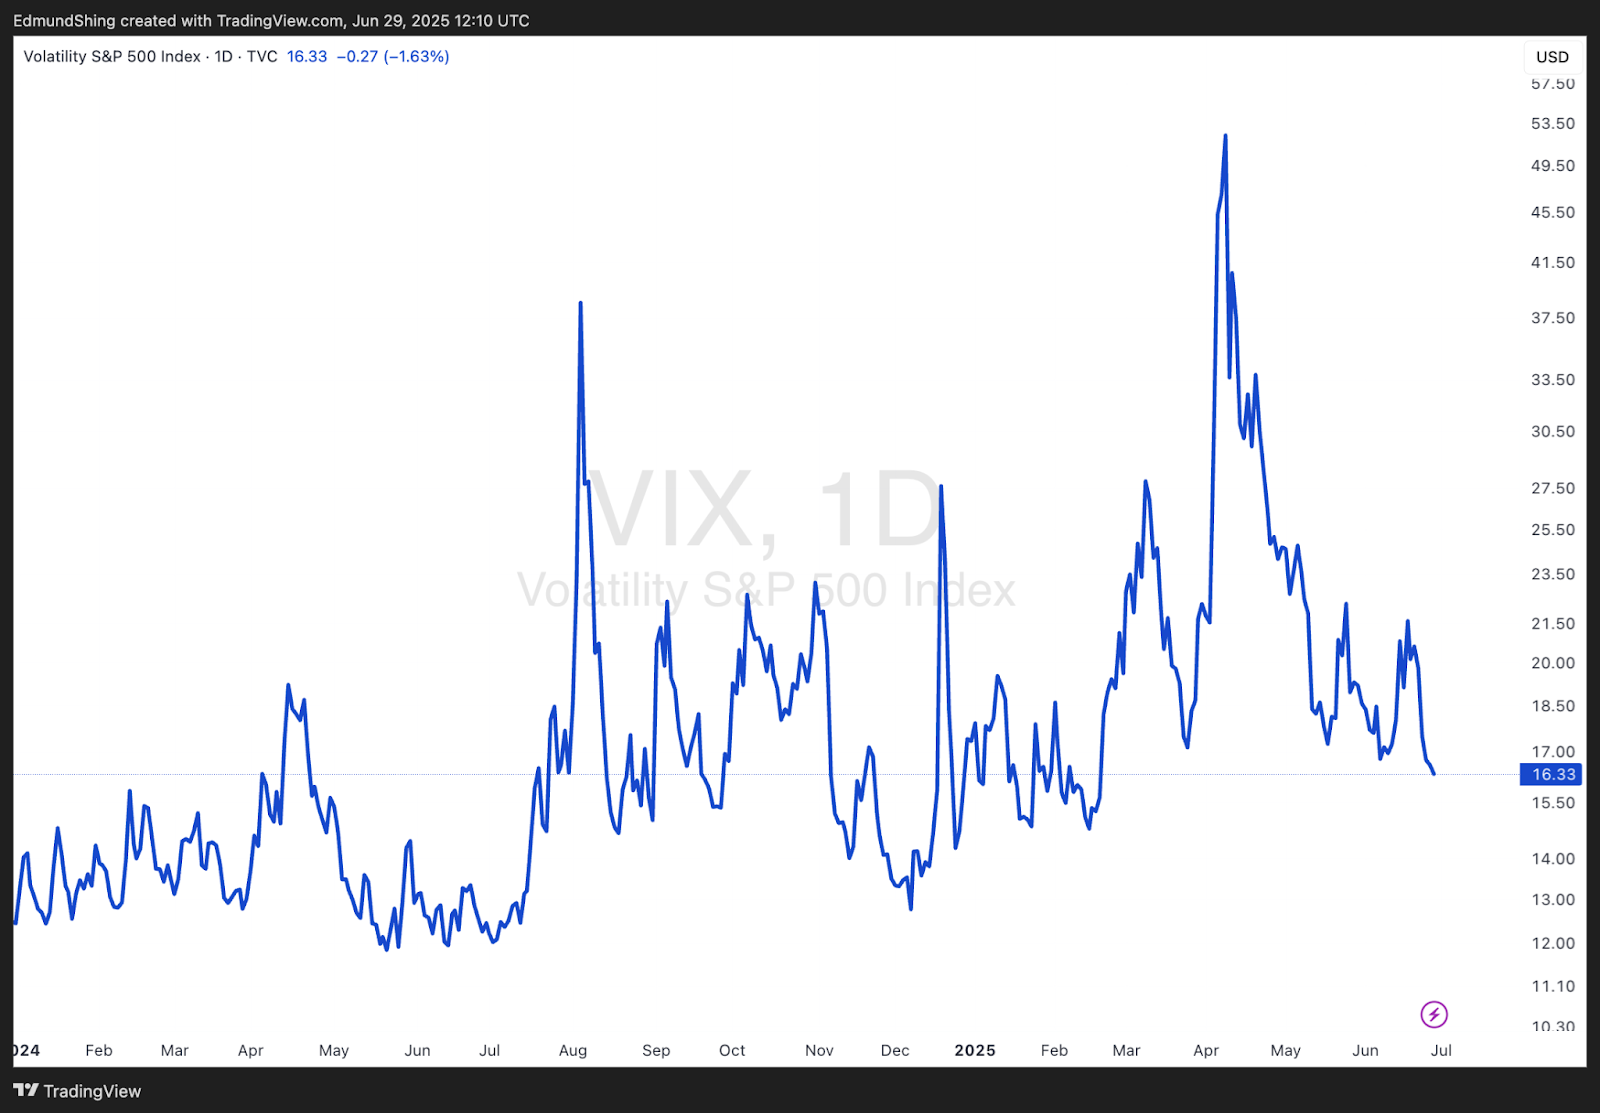
Measures of financial market stress such as the VIX volatility index (for US stocks) and the US high yield corporate bond (credit) spread have actually declined to levels that suggest market complacency - certainly little evidence of higher-than-average risk being priced into these markets.
VIX volatility index declines to 16
US high yield credit spread returns close to year lows at 3%

Rather the opposite - US indices hit new all-time highs!
This week, the S&P 500 and Nasdaq 100 indices shrugged off tariff impacts and the Middle East conflict to reach new all-time highs, propelled by buoyant market liquidity conditions. The Nasdaq bounce from the early pariul lows has been impressive at +31% in just a few weeks.
S&P 500 and Nasdaq 100 indices hit new highs


However, underneath the surface we continue to see shifting market leadership. Of the Magnificent 7, only Nvidia and Microsoft continue to forge new highs, while Tesla and Apple continue to struggle. Other tech mega-caps to lead the way higher include Broadcom and Oracle.
US financials (banks and insurance companies) are also returning to their highs, judging by the strong recovery in the XLF Financials ETF. Banking deregulation is expected to be enacted by the Trump administration, which should boost bank sector earnings and profitability.
US financials to benefit from banking deregulation

But remember, from non-US investors there is still a heavy drag from the weakening US dollar, which touched $1.17 against the euro (+14% in favour of the euro since the start of this year) and $1.37 against the pound this week.
EUR/USD up to $1.17

UK and Japanese stocks also pick up momentum
While the UK and Japanese stock markets have not registered new all-time highs in the past week, they are posting strong positive upwards momentum - worth keeping a close eye on these two stock markets.
Japanese TOPIX index looks strong

iShares MSCI Japan (hedged in euros) ETF also strong

UK FTSE 250 (mid-caps, in red) catching up to FTSE 100 (in blue)

FTSE 250 still has some way to go to return to the 2021 all-time high

It is clear that UK mid- and small-cap stocks look good value, and continue to attract bids from overseas companies and private equity buyout funds.
Finally, keep an eye on the silver price, which last week touched $37/ounce, its highest level in 13 years. It looks well on its way to catching up to the strong momentum already demonstrated by gold, with the all-time high of $50/ounce (hit in 1980 and 2011) back in view. Any further increase in the silver price can only be good news for silver miners, of course…
Silver close to $36/ounce after rising as high as $37 last week

Silver miner ETF has hit resistance, but if it breaks above, could be very promising

Have a good week,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
Question to Ed or anyone in the know lets just say you have an S&P 500 ETF hedged to sterling how well does this actually work in practice.
if the dollar say drops 9% to the £ does the sterling hedging fully offset this ? I've also read that hedging only works short term as contracts are continuously rolled over and expected future declines are priced into the next roll over negating some of the insurance aspect of the hedge.
Again I've no personal knowledge to know if either of the above are true or not but would be keen to hear the thoughts of anyone who understands the above two points better than me.
Regards
Andy
Hi Andy, this article explains how hedged ETFs work: https://www.justetf.com/uk/new...
Thanks pka
Edmund et al Re Silver. Is there a hedged etf in euro or £? Also what is the best option re miners to minimise the impact of dollar decline? My £ version of the ishares Silver etf is suffering currency headwinds. Great data analysis Edmund, as ever.
Hi Snowdrop, according to the JustETF website, there are 9 silver ETFs or ETCs available on the UK stock market. 8 of them are quoted in US dollars. But there is one that's hedged to the Euro, which is the Xtrackers Physical Silver EUR Hedged ETC (Ticker OXA2).
Excellent, thanks