McBride - AGM Profits Warning
Analyst’s view:
When I reviewed this following the last profit warning in June, I was willing to give them the benefit of the doubt, saying:
We take the impact of profit warnings seriously on Stockopedia, as the evidence suggests that the first cut is rarely the deepest. However, in this case, the impact is relatively minor and largely due to cost-pass-through timing. Hence, it makes sense to maintain our neutral view, balancing the possible upside from the current valuation if things go well with the obvious risks if they don’t.
However, this second profit warning is now much more severe, at least for the current year, and the price has risen about 15% above where it was after the last profit warning. Hence, it no longer looks obviously cheap on forward earnings and I think we should be more cautious about the prospects of any short term recovery today. AMBER/RED
That things are tough in this sector perhaps shouldn't be a surprise. Much smaller competitor Potter and Moore (formerly Creightons) was the canary in the coal mine, as its profit warning came earlier this week. The reasons are very similar; volumes are holding up:
McBride continues to see resilient and growing underlying demand for its private label cleaning products, reflecting the compelling value for money proposition for consumers and strength of the Group’s offering. For Q1 FY27, like-for-like volumes, excluding the Eurotab acquisition, are up c. 2% and revenues higher by c. 4%.
But the delays in passing on cost rises to customers are squeezing margins:
However, the volatile geo-political and macro-economic backdrop has persisted, with McBride continuing to experience elevated costs across petrochemical-derived and energy-intensive materials, packaging and haulage. These pressures have endured for much longer than anticipated, requiring further pricing and margin recovery actions beyond those already achieved thus delaying the timing of margin recovery.
What is surprising is how long the delay is in passing on these costs, and the scale of the impact that it is having on margins. It is rare to have a warning of this magnitude in an AGM statement, although they say some now-resolved operational challenges are also to blame:
As a result of the above, the Board now anticipates that recovery of margins towards previous levels will be during Q4 FY27 (previously Q2 FY27). Therefore, the Group currently expects full-year FY27 adjusted EBITA to be between 20% and 25% below current analysts’ expectations.
Helpfully, they quantify the current consensus of £62.9m Adjusted EBITDA. Unhelpfully, they don't give us the EPS impact, and neither Zeus nor Equity Development have updated notes on Research Tree yet. Thankfully, Claude to the rescue:
Revised FY27 diluted EPS after the warning (estimated):
EBITA cut | EBITA (£m) | ED basis | Zeus basis |
−20% | 50.3 | 16.6p (−23%) | 15.7p (−23%) |
−22.5% (mid) | 48.7 | 15.9p (−26%) | 15.0p (−26%) |
−25% | 47.2 | 15.2p (−30%) | 14.4p (−30%) |
Under both sets of assumptions, the guidance implies FY27 EPS cuts of roughly 23–30%, and EPS falls about 1.2 times as fast as EBITA because of fixed interest costs. The midpoint diluted EPS is about 15–16p versus 20.6p in FY26. That would be a second year of falling EPS.
If that sort of impact carried forward into future years, we might expect the share price to fall around 30% today. Perhaps more, as this is now the second major warning:
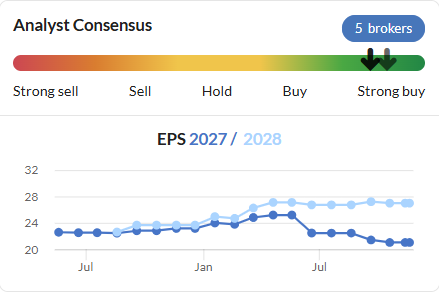
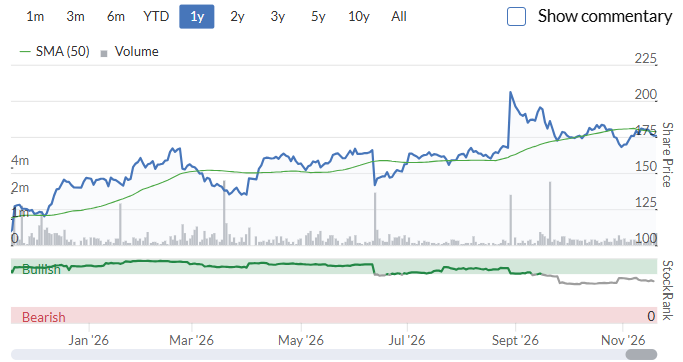
And the market has shrugged off this disappointment:
Partly because these are expected to be one-off factors, and FY28 EPS was held. However, today, the company appear to stop short of declaring that it will be back to normal in FY28:
The Group recognises that the macro-economic environment is likely to remain uncertain in the short term and forward views for input cost development remain difficult to predict, however the Board believes the current margin pressures will resolve over time, and the longer-term strategic direction of the business remains positive.
I wouldn't be surprised to see future years trimmed when we finally get the broker updates.
Valuation:
The other factor that has perhaps supported the share price is the relatively cheap valuation on forward metrics:
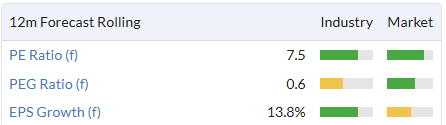
However, that has been based on forward estimates, and today's update puts the forward P/E at a more expensive 11x, with EPS now declining. The more backwards-looking Value Rank is unimpressive:
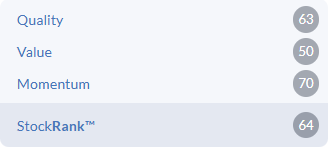
So much of the investment case rests on a strong recovery into 2028, which looks riskier to bet on after today's warning and outlook.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on McBride (1)
Comments here are also visible in the Daily Stock Market Report
McBride (LON:MCB)
yet again the stocky rankings spotted this one kinda coming - dont know how the ranking system does it - but its often spot on. green all the way to september with the ranking taking turn for the worse then and down to 64 now - perhaps less in store?
To be fair to anyone that pays attention thecurrent year eps numbers have been trending down whilst next year was staying stubornly low - so i think the clues were hiding in plain sight that things werenty trending great.
its always double edged sword with companies withn high debt - have a good run and the whole pictuire can transform remarkably - they have been ona bit of a tear for a few years now - but with chunky debt you arent far away from shareprice being trashed - they did manage to get debt down from £164 mill to £105 mill so they hgely derisked tehn buisness - but i see debt went back up £20 mill last year so downward trend did stop. shareprice is back where it was 18 months ago now - so thats always one thing to bear in mind with chunky debt it can make any bad news doubly bad if debt safety net reduces - perhaps slightly surprised negative shareprice reaction is slightly more than it has been pe wasnt over highb anyway though so perhaps thats cvome to teh rescue modest rating ?