Measuring up the LSE: Main market and AIM

London Stock Exchange (LSE) listed companies are not equal in terms of regulation and corporate governance rules. The Alternative Investment Market (AIM) is the least regulated and has performed poorly. Premium listed stocks on the Main Market follow the highest standards and have generated solid returns.
Disaster stories like Globo, Quindell and Blinkx show the scope for corporate wrongdoing on the Alternative Investment Market (AIM). A host of Chinese stocks, such as Naibu and Camkids, have also been dismal failures.
A challenge for investors is that many of these companies appeared to have strong fundamentals. AIM is the least regulated market in the UK and so will always be the destination of choice for fraudulent companies.
AIM has also attracted international companies that are harder for UK investors to follow. The sector exposure of companies on AIM is another factor increasing the risk with an emphasis on areas such as resource exploration.
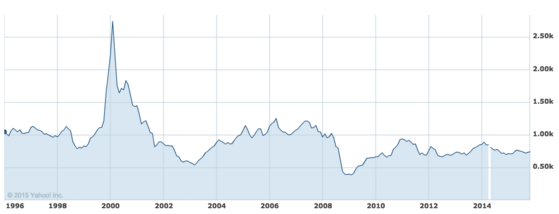
Looking at the long-term performance of the AIM-All Share and the index is below the level it started at in early 1996. The initial value of the AIM-All Share was 1,000 but today, nearly 20 years on, it stands at around 750.
The AIM-All Share index has been relatively volatile and AIM listed companies also tend not to offer a dividend. In terms of individual stocks and there has been a significant dispersion of returns i.e. a few big winners and many losers.
AIM All-Share index since 1996: going nowhere
Source: Yahoo Finance
There are quality companies on AIM with flooring company James Halstead, the budget airline Dart Group and drinks group Fevertree good examples. However, these tend to be the exceptions rather than the norm.
The key question investors need to ask of an AIM company is why has it chosen to avoid listing on the Main Market. A follow-up issue is to find out the corporate governance standards an AIM company has elected to follow.
Investors could have easily have avoided disaster stories like Quindell by avoiding AIM stocks. Quindell tried to move from AIM to the Main Market but was rejected, which highlights the quality threshold for Main Market stocks.
The Main Market versus AIM
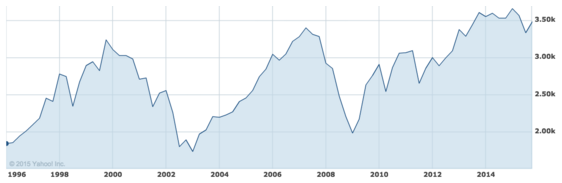
Turning to the LSE’s Main Market and this includes the companies in the All-Share Index. The All-Share has increased from 1,800 in early 1996 to around 3,500 today and paid out a reasonable dividend along the way.
All-Share Index since 1996
Source: Yahoo Finance
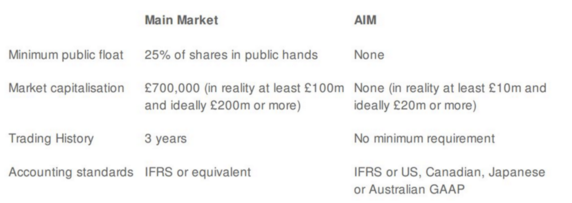
The requirements to enter the Main Market include 3 years of trading history and a sufficient free float of shares in public hands. The regulatory requirements are formalized and include the need to consult shareholders on major issues.
AIM companies, by contrast, are regulated by nominated advisors (Nomads) with this role taken on by brokers. This approach has appeared to be flawed with brokers not keen to cry foul on the companies they oversee.
Key differences between the Main Market and AIM
Source: Withersworld Factsheet 2008
Main Market in focus
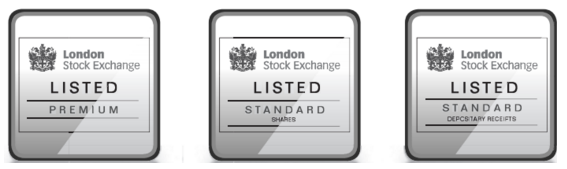
Looking in more detail at the main market and not all the listings are equal with two key categories. These are Premium listed companies (previously called Primary) and Standard listed companies (previously called Secondary).
LSE Main Market types of listings
Source: LSE
Premium listed companies are expected to meet the UK’s highest standards of corporate governance and regulation. They will enter the All-Share index and the FTSE Fledgling index subject to free-float and liquidity requirements.
For UK incorporated companies the free-float requirement for the FTSE Index series is 25%. For foreign incorporated companies the requirement is 50% and they must publicly adhere to UK regulations and the takeover code.
The easiest way to determine if a Main Market listed stock is a Premium listing is to see if it is part of the All-Share index or the FTSE Fledgling Index. A company’s annual report will also state which kind of listing regime it is under.
If a Main Market company only has a Standard listing then investors need to ask why this is the case. A company may have decided not to sign up to UK corporate governance best practice, which is a potential red flag.
Examples of companies that are Standard Listed on the Main Market are PPHE Hotels Group, Avation and Ocean Wilsons Holdings. These companies are all incorporated outside of the United Kingdom.
Summary
It can pay off for investors to have a system that first of all selects the strongest area to invest in. This skews the odds in favour of a good result before any bottom up research on a company has been undertaken.
In the case of AIM stocks the long-term performance of the AIM All-Share has been poor. Individual companies have often given a misleading picture of their financial performance and market position.
This needs to be borne in mind when considering the investment case for an AIM company. However, some companies do follow high corporate governance standards and are only on the AIM market for tax reasons.
On the Main Market it is only Premium listed companies following the UK corporate governance code and regulations. These qualify for entry into the FTSE index series and so can be easily identified.
Standard listed stocks on the Main Market have not signed up to the full UK corporate governance and regulatory rules. This is a potential red flag that needs to be borne in mind by investors.
The bottom line is that not all LSE listing types are equal in terms of regulation and corporate governance. The easiest way to avoid the corporate horror stories is to avoid AIM and look at Premium listed stocks on the Main Market.
This report was produced by Fat Prophets Senior Analyst Andrew Latto
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
3 comments
Interesting that the other junior markets have seen similar issues. The German Neueur market was closed in 2002 on account of the corporate failures. In Spain the junior market (MAB) has been hurt by the Gowex collapse.
Clearly the fraudulent, low quality companies head to the junior markets. This is a self-selection exercise as if everything else was equal firms would prefer to be on the more prestigious main market.
"The initial value of the AIM-All Share was 1,000 but today, nearly 20 years on, it stands at around 750."
By rights, this should give the LSE pause for a bit of introspection. And if that's what you think, then you'd be wrong. According to their website (http://www.londonstockexchange.com/companies-and-advisors/aim/aim/aim.htm): "Welcome to AIM. Where ideas take off. AIM is the most successful growth market in the world. Since its launch in 1995, over 3,600 companies from across the globe have chosen to join AIM."
So apparently it's not a fiasco, but a resounding success, where growth means losing 25% of your dough over two decades.
-- Sighs deeply --
Yes, but they have made a fortune in fees... ;)