Mello Chiswick Jun-26

Notes below from Mello a last month. Perhaps one or two readers can help me out with thoughts on Oxford Technology and B.P. Marsh & Partners (LON:BPM). Super tired from work so one or two details may not be 100%. Bear in mind I'm a long-term, conservative investor who favours closed ended investment trusts and well covered dividend paying blue chips. Note the investment trust links are to the AIC web site (I hope they work). Stockopedia is an excellent resource for individual shares but the detail for investment trusts is better covered by the AIC web site.
Thanks to David and his team for organising another great event, very enjoyable. I have purchased my ticket for November already.
Georgina Brittain
# Long-term portfolio manager at JP Morgan. Currently joint manager for JUGI.
# Interview by David Stredder who is not afraid of asking some direct questions!
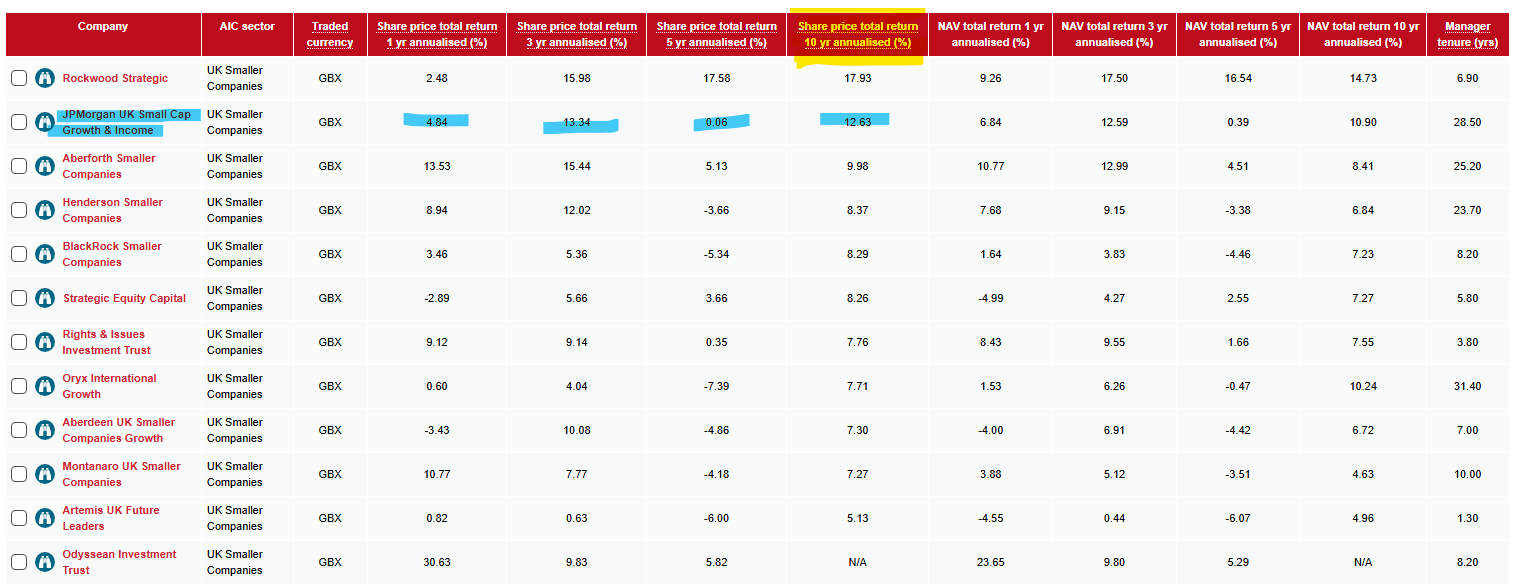
# SSB: JUGI rolls up into the AIC UK Smaller Companies sector. Filtering on mkt cap > 100m and 10 year SP performance gives the following table. RKW was not being managed by Richard Staveley 10 years ago so maybe is not completely comparable. JUGI is second on the list and that gives me confidence that GB is a person worth listening to. Fwiw, I own ASL which is third on the list; I bought a few years back because I wanted exposure to the sector and tend to favour the larger caps.
# Challenging periods ? Covid! Additional funding required for all companies but GB asked her team to try to identify which companies would be around in 2 years time. Jet2 (LON:JET2) is obvious now but not so much at the time.
# Great company v great investment opportunity ? GB is only interested in the latter. Former is only obvious many years latter. Visited Games Workshop (LON:GAW) 20 years ago, IP and cashflow stood out but at the time it was not obvious they would become a FTSE 100 Index (FTSE:UKX) company. ARM Holdings was another, GB invested when it was mkt cap circa £200m. DS said Games Workshop (LON:GAW) were invited to Mello numerous times but declined, said they were too busy running the company! Perhaps the lesson is to invest in the companies that don't attend rather than the ones that do (DS words not mine :-).
# GB bought Applied Nutrition (LON:APN) at float 18 months ago. “Ahead of mkt expectations” plus tie up with Mondelez International (NSQ:MDLZ) which will get them into Walmart (NSQ:WMT) in the US.
# GB likes IPOs & says she has a good track record. But got to get to know companies over time before they float. Profits, cashflows etc. Do mgt under promise and over deliver ?
# GB still owns companies that floated 10 years ago.
# GB tells company founders that as soon as their companies float the company is no longer theirs, it belongs to investors. Also, if they disappoint then they will feel pain. Some take this onboard, others don't.
# Good characteristics of a company IPO ? 3 keys themes: 1.) quality especially balance sheet metrics 2.) momentum 3.) free cash flow yield.
# Takeovers ? Mixed emotions: 30% or 40% upside on the day a takeover is announced but the UK market is losing some great companies. Eg: Renold was bought out too cheaply but CEO said they couldn’t do what they wanted to do with a listing so it went private. Alpha Group (FX Alpha) taken out at a 50% premium.
# Numis smaller companies is the GB benchmark. If a takeover is agreed at a good premium and gives rise to an opportunity to buy into several of the 700 to 800 companies on the Numis Smaller Companies index then in GB's view, that is a good outcome.
# There is still interest in listing from a number of companies but things get in the way eg: Iran war etc. But an increase in listings is a continuing false dawn unfortunately.
# Key rule for GB is to run your winners and cut your losers. GB does not like picking up troubled companies that may turn around and then again, may not.
# If mgt mislead then sell straight away. If nothing looks like happening in the next couple of years then sell and buy something else. An investor can always come back and take a second look without being a holder.
# Question on success rate ? Not sure but 10 & 20 baggers really help.
# Question on housebuilders ? Small and mid cap UK market is astonishingly cheap. We are not making land anymore so housebuilders have to get more expensive at some point eg Bellway (LON:BWY) is on a 40% discount to NAV.
# SSB thoughts: enjoyable discussion, easy to understand as many of the companies have been covered more than once in the DSMR. I could be tempted to switch to JUGI, certainly a number of the current top holdings have good StockRanks and do not appear (at first glance) to be overly expensive.
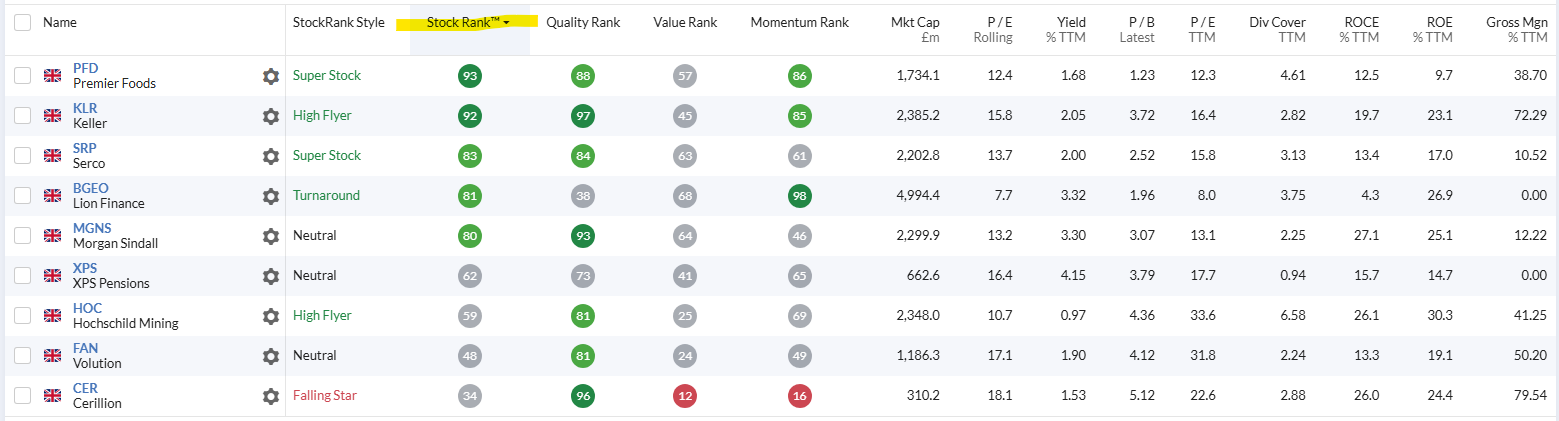
Fwiw, the equivalent view for ASL is as follows....
Brunner Investment Trust
# BUT is a member of the FTSE 250. Included in the Global sector of the AIC.
# 99 years old.
# Family own 25% of the trust. SSB: I didn't know this and this is a positive as far as I'm concerned, similar to a number of other trusts including CLDN which I do own.
# 70% global / 30% UK. # AIC Dividend Hero.
# Leverage is low. SSB: AIC web site says it is currently zero!
# Focused on 20% rapid growth / 60% stable growth / 20% cash cows…. look for moats eg: Visa.
# Dividend chart showing increase or decrease in reserve. SSB: photo didn't come out very well but the 2 takeaways are that Covid was the only significant period when the trust had to use revenue reserves to pay dividends and it has been building those reserves up again over the last 3 years.
# Brunner portfolio has a lower percentage of the more speculative tech versus MSCI All Country World Index.
# Question on Baltic Classifieds Group: it connects disparate sellers with buyers. Low capital to operate this web site.
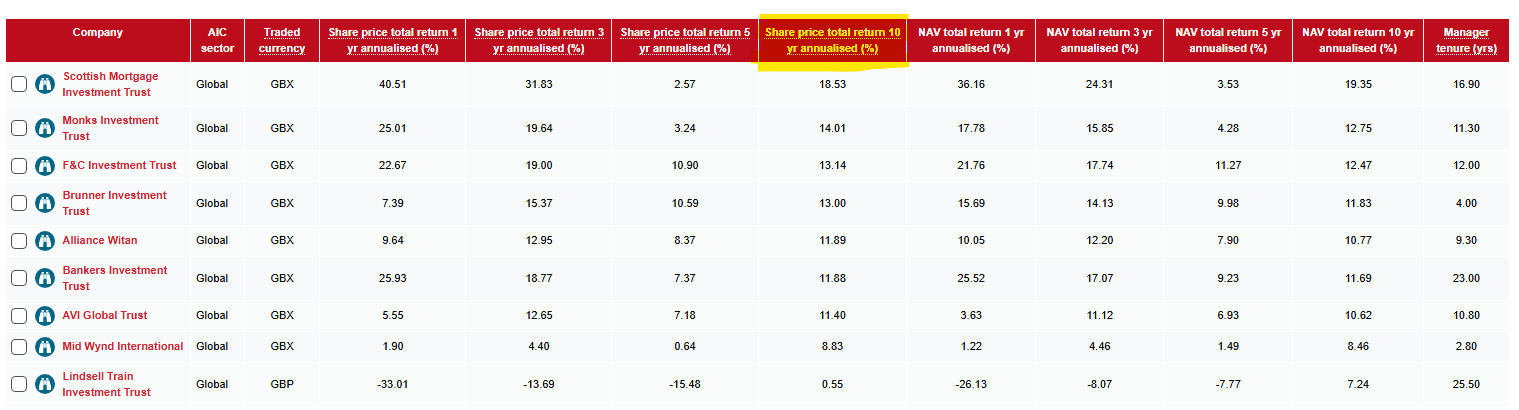
# SSB thoughts: good presentation but I will stick with CLDN and AGT (who presented at Mello last year) for my global exposure. Fwiw, the AIC Global performance table looks as follows. The 2 Baillie Gifford trusts out in front but much more 'aggressive' holdings than the others on the list:
Rockwood Strategic
# Richard Staveley has presented at the last few Mello Chiswick gatherings and seems to be very popular, the conference room is always packed.
# RKW now has a £180m mkt cap. Focus is on a highly concentrated portfolio based on value and momentum along with mgt who have skin in the game.
# RS made reference to the fact that Eagle Eye Solutions (LON:EYE), Vanquis Banking (LON:VANQ) and Restore (LON:RST) were all presenting at Mello over the 2 days.
# Christopher Mills owns 15% of RKW and RS is also a significant holder of his own trust.
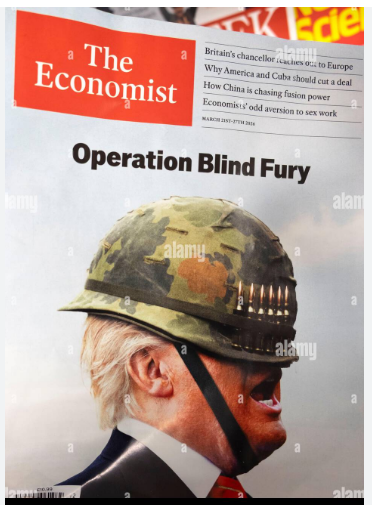
# Donald Trump on the front page of a recent version of The Economist used to sum up some of the geopolitics at the moment. Got a laugh from those who hadn't previously seen it including me.
# Van Elle Holdings (LON:VANL^F26) takeover at +58% premium and Treatt at +48% premium.
# Filtronic (LON:FTC) has been a 34 bagger for the trust.
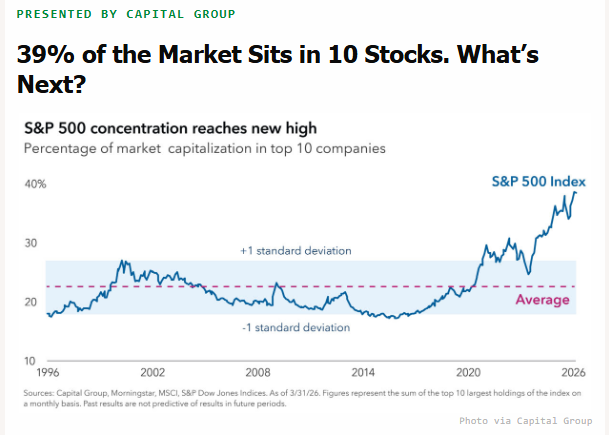
# Markets have a real concentration risk at the moment (reference to S&P 500 Index (SP:SPX).
# RKW currently on 1.2 times sales.
# UK optimism is at it's lowest since 2008/9 and there are lots of bargains available.
# Top 20 as of end of March: 9 holdings are net cash and 50% are AIM listed.
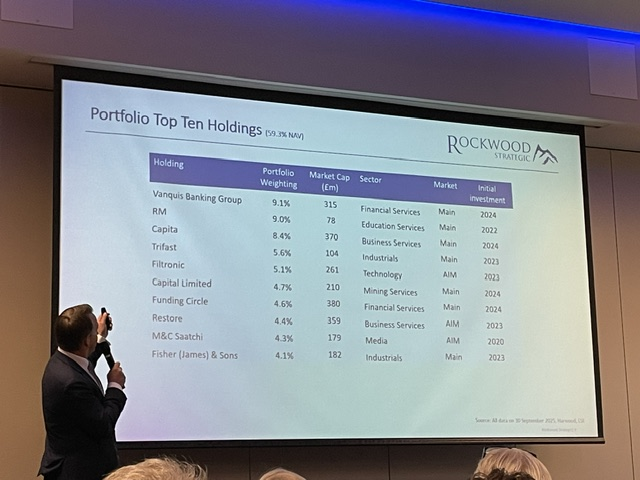
# Capita (LON:CPI): will it double from here ? Cost cuts in progress, pension deficit resolved, compares well against Serco (LON:SRP) for public sector contracts. Lots of short positions currently held by Quant funds. SSB: clearly all discussed prior to this last week's RNS!
# Capital (LON:CAPD): EV to EBITDA of 3 ? "Really ?"
# Videndum (LON:VID): largest nominal investment made by the trust. World leader in media equipment. 6 times EV/EBITDA.
# Stelrad (LON:SRAD): new investment. Leading radiator seller in the UK. 4.7 times EV/EBITDA.
# M&C Saatchi (LON:SAA): board change + net cash + 4.7 times EV/EBITDA.
# Kooth (LON:KOO): mental health services in UK & US. Won contract for California. 73% gross margin. Net cash. 3.7 times EV/EBITDA.
# Overall RKW performance discussed. SSB: RS has been the manager for approx 5 years I think.
# M&C Saatchi (LON:SAA) more likely to be broken up or sold as unlikely to get fair valuation in the market.
# Restore (LON:RST) business for wills, medical records etc keeps going. Very profitable. Used to be on 19 times profits but now on 10.
# Trifast (LON:TRI) at 68 pence.... "completely crazy price".
# Funding Circle Holdings (LON:FCH) did 24m profit last year. Will do 50m this year.
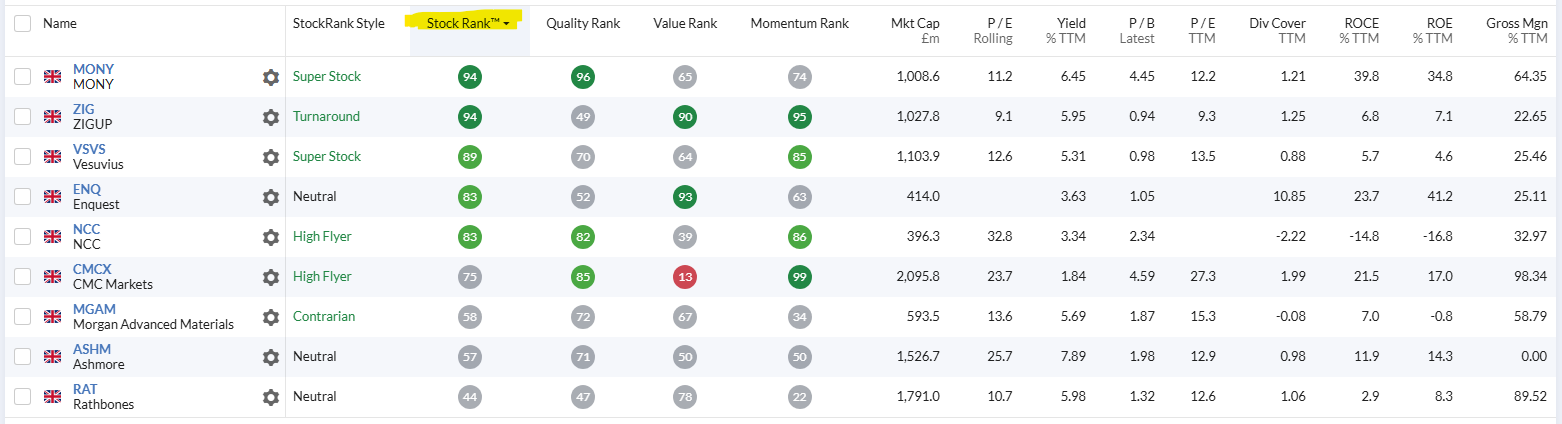
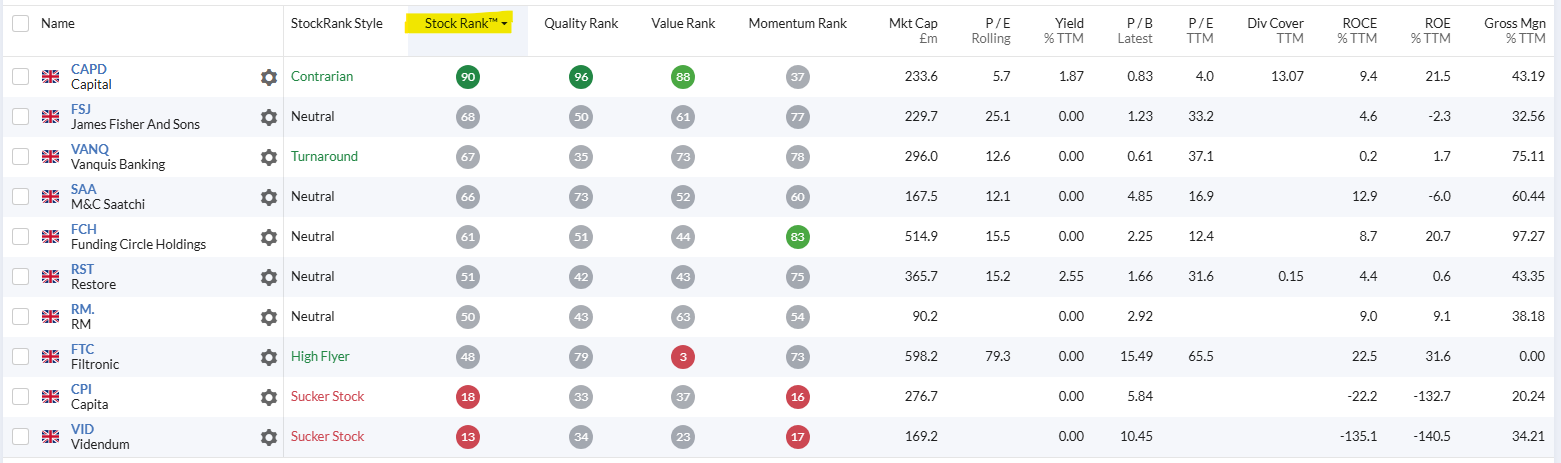
# SSB thoughts: RS is a salesman, no question about that but he is very articulate and his record speaks for itself. Btw, looking at the StockRanks for the current portfolio is odd to say the least:
Ruffer Investment Trust
# Ruffer has 18bn (Sterling ?) under mgt so I am guessing they must have some open ended funds as well as the investment trust.
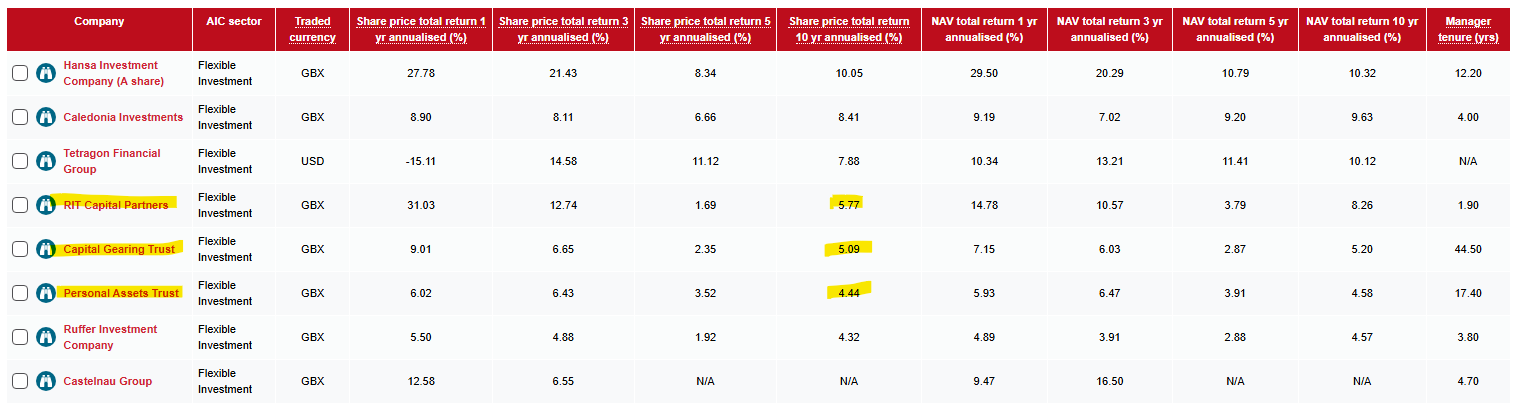
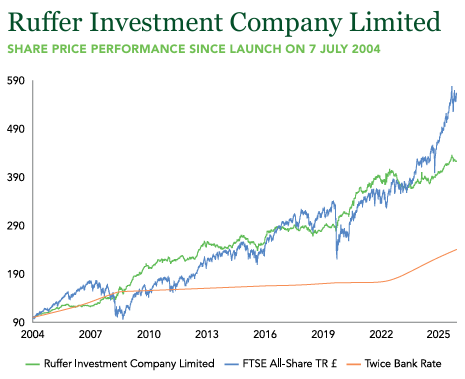
# RICA is the investment trust and the purpose of the presentation. It is listed under the AIC 'Flexible Investment' category which it seems to me is a catch all for any trusts that don't easily fit into the other more specific categories. But really, there are only 3 wealth preservation trusts.... RICA, PNL and CGT. Over a 10 year period, they all have very similar SP performance which IF inflation stays low can be an easy investment decision in the longer term.
# Back to RICA
# Objective is not to lose money.
# Why is Ruffer relevant today ? Inflation protection required because government debt & war has changed the global political & economic landscape.
# Oil shock from Iran war could cause a wave of inflation. SSB: we are not seeing that yet but maybe that is because we are in summer ?
# Protection is hard to find during times of inflation such as we had in 2022/3 post Russian invasion of Ukraine.
# Trump politics makes things more unstable as previously friendly countries (Denmark) have started selling the dollar with US equities & bonds falling at the same time (a first since 1977).
# Ruffer toolkit includes commodity exposure, gold miners, oil (small direct investment + equities related), selective equity themes such as Japan, Europe and UK plus single name opportunities such as Reckitt Benckiser (LON:RKT), Unilever (LON:ULVR) and Barratt Redrow (LON:BTRW).
# Cautious portfolio construction at the moment.
# 2023 was Ruffer’s worst year as the balance between growth and protection was not correct. SSB: I held CGT for a while in 2022 and 2023 and suffered the same performance but I'm not sure it was for the same reasons.
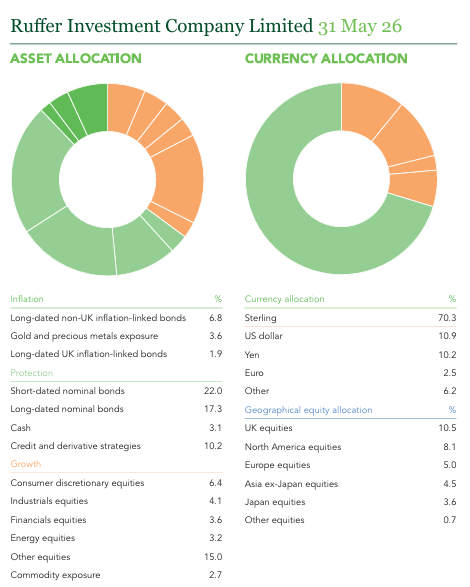
# SSB thoughts: this presentation would not be to everyone's liking because of the defensive nature of the trust (the managers are not exactly stock market bulls at the moment!) but I liked it. The May-26 factsheet has the asset breakdown which is super defensive. Many investors will get FOMO holding this trust when equity markets are racing ahead! The real downside for me as a UK citizen is the holding in UK gilts; it's a times like this I would like to be a little more Norwegian!
Richard Crow (Cockney Rebel)
# Successful private investor who many on Stockopedia will be familiar with.
# Free weekly substack article is a must read at the weekend IMO: Cockney’s Substack | Substack
# 20 year full time investor.
# Focus on recovery plays and identifying chart 'bowls'.
# 2 types of risk: real and perceived eg: Games Workshop (LON:GAW) always delivers but if it doesn’t then the SP will fall (ie: real risk) but if a company has disappointed already then the fear is already built into the SP (ie: perceived risk).
# How to understand risk ? Look at the chart and wait to see a pick-up in the SP. Don’t buy a share which has performed badly and the directors have not changed (leopards don’t change their spots). Need to be patient. Don't average down, average up! Want to see directors buy shares themselves.
# Buy small amounts and see if the recovery picks up.
# Easier to look back at a chart of a recovery play than an IPO that has little chart history.
# RC is looking for a company that hasn’t issued lots more shares ie: important to get a feel for EPS.
# Saga (LON:SAGA) in 2025 was a winner. Signs were there eg: Chairman bought lots of shares as the SP bottomed out ie: it's not always what a company says, it’s what the company does in terms of actions.
# Hays (LON:HAS) latest statement sounds good. CEO has bought shares. Recruitment sector is hated. But AI will not do everything going forward and companies will still need talented/committed people.
# SSB: RC uses AI to do research but I don't recall how he said he uses it, perhaps just a query into ChatGPT or Claude ? Does anyone else who was there recall ?
# Sell strategy: question to ask is whether there is something better to invest in before you sell ?
# RC up +40% on Softcat (LON:SCT) in the last 3 weeks. Calculate forward PE on the basis of recent numbers. Director buying has been strong.
# Good question on when to buy again after the initial buy. Answer along the lines of watch the chart, read the results, ignore broker forecasts and don’t try to buy 100% at the bottom, listen to your doubts as a safety first mechanism.
# Goodwin (LON:GDWN) and Saga (LON:SAGA) got up to 25% to 30% of RC’s portfolio.
# Retailers: RC likes Halfords (LON:HFD) and the new CEO who was previously at William Hill.
# Shoe Zone (LON:SHOE) is risky & illiquid.
# RC currently holds almost 20 shares but would like to get that down to 12ish.
# SSB thoughts: very straightforward presentation and clearly successful but not something I can do whilst I still work full time at a bank. This strategy is something to aspire to though and hopefully one for my future. Bonus: Richard posted his presentation on YouTube so thank you for that, worth watching in full IMO >>> Mello 2026, June 2nd Me on stage
Oxford Technology
# Third time I have seen Oxford Technology present at Mello so my notes are a mix of all 3 presentations. I am intrigued by the discussions but also wary of the illiquid nature of the EIS structure; once invested, I will only see a return if and when one of the underlying investments is sold.
# https://www.oxfordtechnology.com/
# Presenters have scientific backgrounds.
# Oxford Technology was started in 1983 and has maintained a very small team to date.
# Basic investment offering is to get in on the ground floor of (hopefully) the next set of scientific or technological breakthroughs. Clearly high risk on their own but maybe several included in a single fund reduces the risk.
# Nice photo of what can happen if things go well:
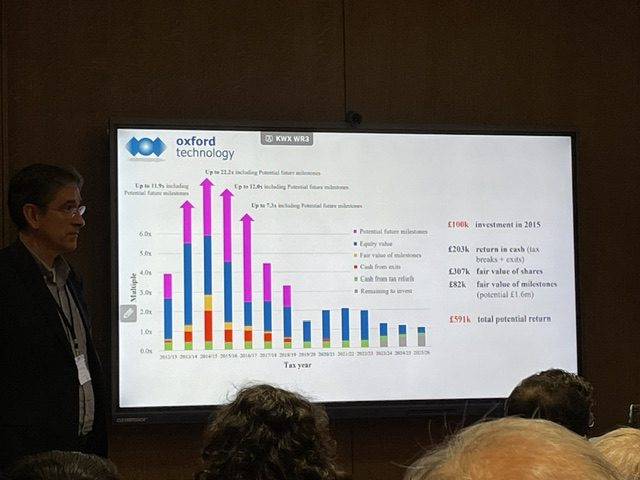
# An investment is in an SEIS for the first year and then an EIS from then on. These vehicles come with tax advantages (30% income tax relief I think is the current benefit). A question was asked around potential changes to tax legislation but nothing had been announced from the government.
# Minimum investment is £15K.
# The fund is based in Henley but plugged into the Oxford scene to try to benefit from (very) early stage businesses coming out of scientific developments (mainly) Oxford University.
# Oxford Tech get approx 1000 approaches every year but typically only make 5 or 6 investments. Not specifically mentioned but it appears that investments are made in a Dragon's Den style ie: entrepreneurs are looking for cash to get their businesses going, Oxford Tech are looking for BIG gains (eg: Organox was a 55x return).
# Oxford Tech look upon themselves as activist investors in terms of helping entrepreneurs develop their businesses and then look for lucrative exits.
# Failure rate is approx 20% but the fund only needs "1 in 10 to work to get a decent return".
# Average maturity for any single investment is 10 years.
# Recent development is that fewer investments are coming from the Oxford area because (in the view of the presenters), there are some over-inflated views coming from PHDs.
# Stating the obvious but the US is the market to hit for large gains.
# Various investments were discussed:
# Refeyn: mass photometry to analyse biomolecules.
# ThermoTraumaPort: development of heating in stretchers to reduce deaths when soldiers are being evacuated from the battlefield; apparently, more soldiers die from hyperthermia when waiting for evacuation from the battlefield than die from their original injuries.
# Metacarpal: development of a body-powered bionic prosthetic hand.
# ENV Energy: development of cobalt-free, nickel-rich cathode materials for longer lifespan batteries.
# SSB thoughts: I was impressed by the presentations and by chance back in November, Lucius Cary (MD) was sat next to me at a later presentation and so I took the opportunity to chat afterwards; very articulate and open on the risks, clearly motivated by past gains. If I had to put a 3+/3- on this potential investment, would summarise as follows....
3+
# Good track record.
# Tax advantages (although this shouldn't be the basis of an investment).
# Better to investment in a set of early stage, high risk ventures in a fund rather than individually; anyone remember Torotrak from 25+ years ago ? :-)
3-
# Very illiquid and as a result, high risk. When asking for any literature from Oxford Technology, they do have a warning in place that asks if investors are prepared to lose 100% of their investment.
# I have found it difficult to get hold of any league table type stats but this maybe my inability to navigate the EIS environment. I have found emails from the Wealth Club useful.# No different to myself, the mgt team are not getting any younger so there appears to be some individual mgt dependency risk there.
# For myself, I will do some more reading as I'm interested but don't have 15K to lose!
SEIS and EIS Funds Investing in Technology Startup Opportunities | Oxford Tech
Enterprise Investment Scheme and Seed Enterprise Investment Scheme: 2026 - GOV.UK
Thank you: Your free EIS factsheet
BP Marsh
# I was keen to attend after reading the Graham Neary write-up a few months back. The sector, discount to NAV and yield all appeal but I wonder if I have maybe missed the boat ?
# Presentation was in one of the smaller rooms but difficult to hear. The CEO did not use a mic and did not speak very loudly. No one said anything so I thought maybe it was just me and concentrated a little more. I should have said something, it's not like me to be so shy and retiring!
# Nice graph showing an increasing NAV.
# Calibre of the NAV has improved.
# Good question on failure rate: answer 5% to 15%.
# SSB thoughts: so my notes are very limited here and probably something to do with the fact I was struggling to hear the presentation well. I clearly need to do some more reading but based on the RNS history and the NAV breakdown below, my question is what do the underlying companies actually do ? Specifically Pantheon which is almost 30% of the NAV ?
The description in the latest financial report is helpful....
B.P. Marsh & Partners Plc is a United Kingdom-based specialist investor in early-stage financial services businesses. The Company invests in various business, including insurance intermediaries, financial advisors, wealth and fund managers and specialist advisory and consultancy firms. The Company invests amounts of up to £5m in the first round and takes an approach to investment structures, reviewing companies ranging from start-ups to those that have developed to the next stage of growth. Its active investments are in the insurance intermediary sector. Its Insurance Intermediary investments are separated into two areas, including insurance brokers and underwriting agencies/managing general agents (MGAs).
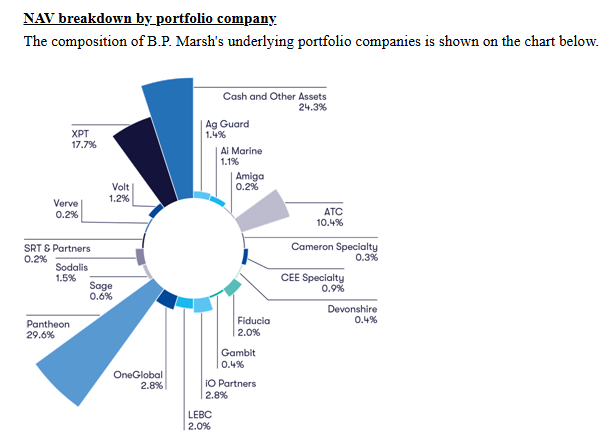
The following was disclosed in the most recent results RNS....
Follow-on Investments and Funding During the Year
Pantheon Specialty Group Limited ("Pantheon") - UK+ 26.1 pence NAV per share change in the Year
Since the Group's original investment in Pantheon in June 2023, when it subscribed for a 25.0% stake, the business has been a stand out performer in the portfolio.
Over the financial year to 31 January 2026, the Group made one further equity investment in Pantheon.
In June 2025, the Group acquired a further 2.0% Cumulative Preferred Ordinary equity stake in Pantheon from members of Pantheon's management team for cash consideration of £5.5m. Following completion of the transaction, the Group's total shareholding in Pantheon increased from 37.0% to 39.0%.
The transaction involved the purchase of shares from members of Pantheon's management team, enabling them to realise a portion of the value created in the business while continuing to retain a substantial majority interest and remaining fully aligned with the future growth of the company.
Since the Group partnered with management to establish Pantheon, the business has delivered a strong financial and operational performance, developing into a leading independent broker in the London insurance market.
Given this continued progress, the Group considered it an attractive opportunity to increase its investment in Pantheon, supporting a deserved partial liquidity event for management while further increasing its exposure to a high-growth business with significant ongoing potential.
Date of initial investment: June 2023
31 January 2026 valuation: £106,990,000
Cost of Equity: £27,300,025
Equity stake: 39.0%
The web site is nice but doesn't provide that much detail: Welcome to Pantheon Specialty
From the B.P. Marsh & Partners (LON:BPM) RNS in May, 89% of B.P. Marsh & Partners (LON:BPM) revenues are non-UK, no issue with that, it's clearly a global business. But I think it's important to understand the valuation of the NAV is 100% IFRS 13 Level 3 (ie: inputs for the asset or liability that are not based on observable market data). This is the only technique that can be used but I think it's important to understand the valuation methodology is the same as that used for private equity trusts such as HgCapital Trust (LON:HGT) and Oakley Capital Investments (LON:OCI) . If I were to buy this, I have to accept there is a lot about the business I don't know (and I am reliant upon the skill of mgt to make decisions and deliver positive returns) plus the NAV is based on a series of assumptions rather than similar market data. No criticism of the business or Graham's article intended. It's pretty clear to me that the success of the company is based on mgt's ability to develop each business opportunity. You could say the same about every business but I think it's more definite for B.P. Marsh & Partners (LON:BPM).
So what is my 3+/3- on B.P. Marsh & Partners (LON:BPM)....
3+
Solid history, mgt appear to have a decent track record.
Currently on a 33% discount to NAV.
Mgt have recently bought more shares but always difficult to know how much of their personal wealth the shareholdings represent.
4.30% yield but this is not the long-term objective of this investment.
3-
There is a lack of detail on the underlying investments which are illiquid in nature ie: IFRS 13 level 3. But no different from any private equity investment trust.
Very dependent upon a few people at the top of the firm staying engaged and motivated.
Happy to hear other views. Maybe I am unduly cautious after HgCapital Trust (LON:HGT) suffered a sell-off earlier this year; I would put this trust in the same category as B.P. Marsh & Partners (LON:BPM) ie: private equity and very dependent on a few senior mgt.
BlackRock Frontiers Trust
# Emily Fletcher is a co-manager of the trust and presented. She has been at BlackRock for 18 years and I think she said she has been involved in the trust for almost all of that time.
# Important to note here the MSCI terms 'Emerging' and 'Frontier' refer to the operation of the country stock markets and not GDP per capita or any other economic measure. Also, for the purpose of this trust, it invests in both eg: Vietnam has just been upgraded from Frontier to Emerging but Vietnamese companies remain in the trust.
# EF presented a map of the world to confirm the countries that are covered. I can't find that in the latest reports but the following country allocation does the job almost as well. Important to note the trust does not invest in the top 7 EM markets (China, India, Brazil.... I didn't get the full list).
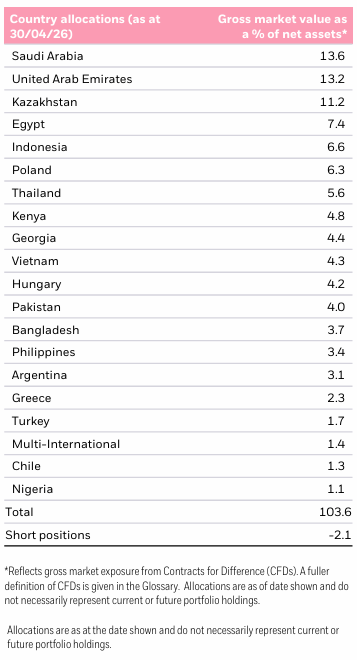
# These countries are under researched and that lack of analyst coverage makes it an easier space to make alpha.
# Unfortunately there are no economies of scale. The team have to go on lots of trips in order to understand the economic situation and to meet companies.
# Often a positive correlation between equities and bonds in many of these countries.
# Investment trust structure helps for the usual reasons ie: if investors want to sell, the trust trust allows them to do that straight away so no need for the team to distracted by buying and selling volumes.
# Frontier markets offer a multi decade growth runway due to low levels of debt, improving infrastructure and often young populations.
# Lack of local investment and so opportunities exist for foreign investment.
# Average holding has a PE of 9. This metric really has not changed since launch in 2010.
# Overlooked markets with surprisingly low volatility but very cyclical.
# Very low daily volatility.
# Many of the companies are viewed as blue chip for each country locally.
# Chile and Bangladesh are both in the trust but the difference is stark!
# A number of countries said in 2012 they were going to run a fiscal deficit and therefore were not so investable eg: Kenya. SSB: given Kenya is 4% of the current portfolio, I assume that situation changed.
# Banks rated at 2 times earnings in Kenya and Kazakhstan (18% yield!). But Thailand has historically traded at 30 times earnings v Korea at 10 times. Why ? Not conclusive. Again, local factors.
# Nigeria was 15% of the portfolio at one point. Came right down to 0%. One trick pony: oil.
# Motor insurance in Saudi is becoming big due to legislation. Only 60% of drivers have insurance.
# Low cost carrier is the latest investment in the UAE.
# Only 60% of people have bank accounts in Egypt.
# Cement company in Pakistan is starting to become a conglomerate as foreign companies exit.
# The trust does not hedge currency risk.
# No private holdings.
# Vietnam has been the star performer. It has been on an amazing run.
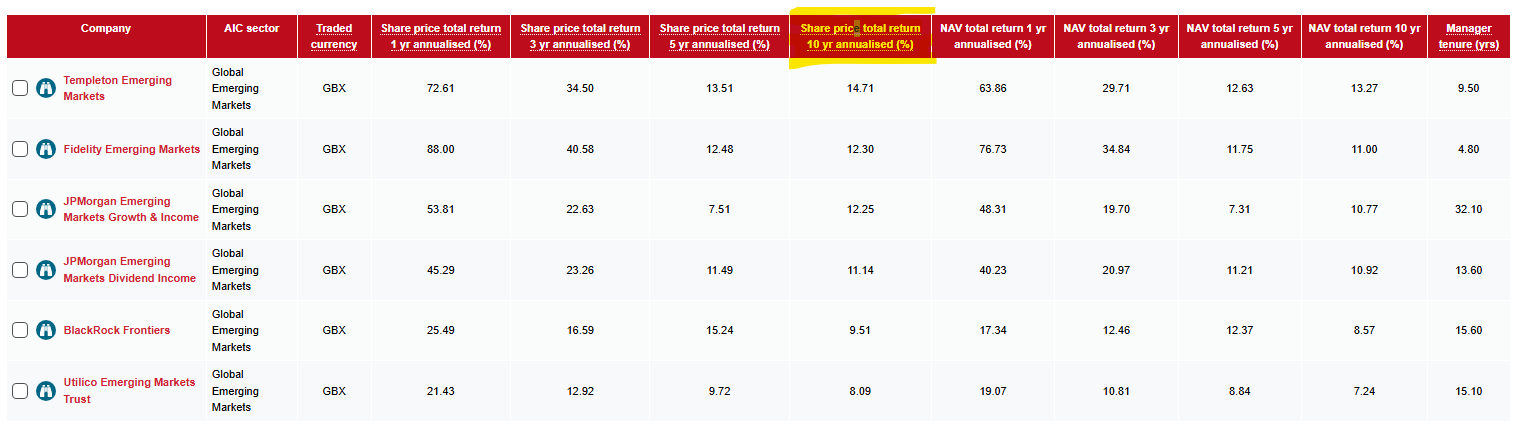
# SSB thoughts: I am familiar with quite a lot of investment trusts but BRFI was not one of them until I attend Mello. VNH has been a good performer in my portfolio for a few years thanks to Vietnam being discussed here and on a previous site so I can see the benefits of investing in frontier/emerging markets. How does BRFI stack up against alternatives in the same AIC sector ? Looking at trusts with a mkt cap > 250m and filtering by 10 year SP performance, TEM seems to be the best performer but it's important to note it does include the largest countries in it's portfolio, particularly South Korea so that almost certainly explains it's performance. There is clearly a massive difference between South Korea and Kazakhstan! But the key point here is that I now have an interest so will spend some time investigating some of these trusts.
# I liked the discussion around EM in general in the one of the most recent IG podcasts; listen from about 50 minutes. I was originally interested because of the underperformance of India but it was the details around China that really surprised me.
Capital Gearing Trust
# Christopher Mills of Harwood Capital was in the main theatre at the same time as Alastair Laing of Capital Gearing in a side room. In the past I have held (and lost money) on both North Atlantic Smaller Companies Investment Trust (LON:NAS) and CGT but I decided to attend the latter because I like the efforts to communicate with current and potential shareholders and I also recognise the fact that I held CGT during a year (2022/3) when both equities and bonds suffered which is unusual. CGT also had administrative issues around maintaining it's discount to NAV until they were able to free up a reserve account and increase the buybacks. This might sound unfair but I contrast this with the poor way in which the North Atlantic Smaller Companies Investment Trust (LON:NAS) annual report is written giving shareholders a minimum of information on holdings; North Atlantic Smaller Companies Investment Trust (LON:NAS) is almost a family office type vehicle and CM has compounded brilliantly over the years but recent performance has been average and the trust is not a member of the AIC which I find odd.
# Another reason I decided to attend this session was because at a London Investor Event, I joined a small group outside one of the main rooms to listen to an informal discussion with Peter Spiller (3 down years in 44 I think his record is ?) and everything he said made sense, even if it was a little dull. Finally, the excellent weekly Pension Craft email alerted me to the following chart showing how concentrated the US market is.
# So decision made, I attended the CGT presentation cheerfully named 'Is it just me or is everything a bit crazy ?'. Such a shame there were only 20 people in the room, this should have been in the main theatre but unfortunately people generally don't pay to attend an investor event to hear the downside of the markets!
# Didn't know if I was going to get a copy of the slides so I took a few photos, apologies if I got the back of someone's head!
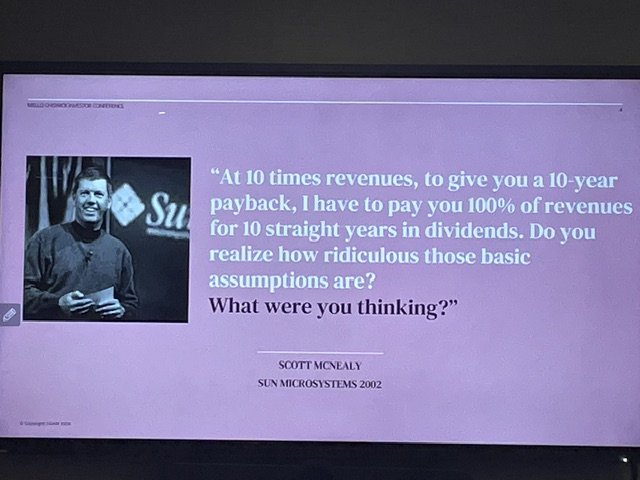
# Sun Microsystems quote highlighted how expensive some shares got during the TMT boom.
# S&P 500 Index (SP:SPX) trades at the highest multiple for a long time.
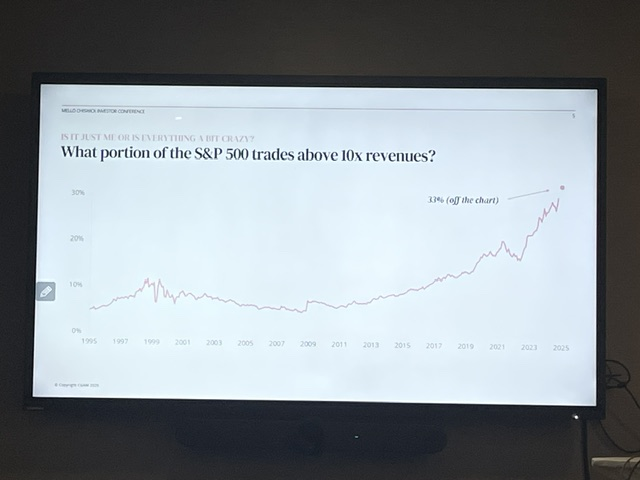
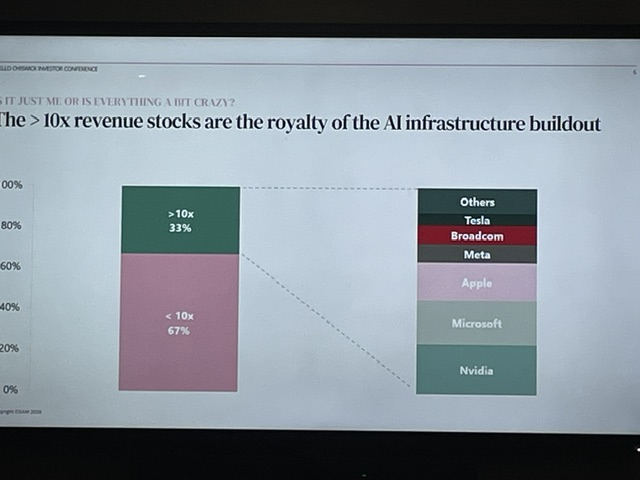
# USD 1trn deployed by the top 5 tech companies in 2026. "They are becoming infrastructure companies with uncertain revenue streams". Space Exploration Technologies (NSQ:SPCX) is a loss making share. Anthropic (Claude) is looking for a USD 1trn valuation. And Open AI (Chat GPT) will follow. "So something unusual is going on...."
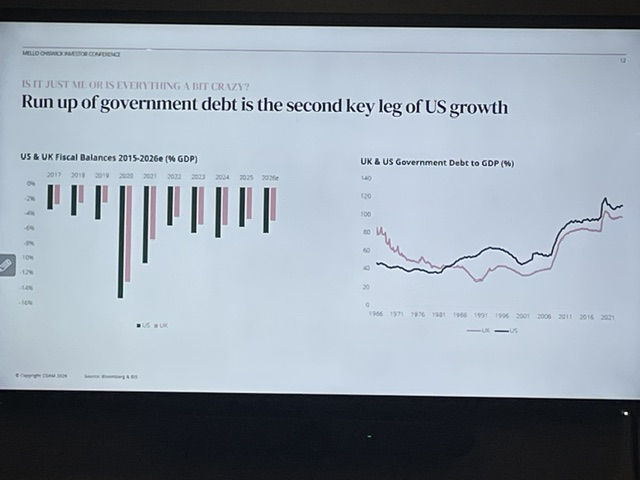
# Backdrop is huge government debt. And now much higher oil and gas prices (SSB: although these have come down quite a bit despite the conflict in the Middle East).
# Forward PE is not a favoured measure for Capital Gearing. Catalyst for trouble on the equities market: domestic politics, geopolitics, slowing economy from higher energy prices, bond market weakness (Jamie Dimon) ? These are the reasons why CGT holds a number of short dated inflation linked bonds.
# SSB thoughts: I buy a monthly amount of MWEP and CGT as a very dull and boring way of increasing exposure to the cheaper end of the equity market whilst hopefully getting some fixed income protection. We will see how this works out.
I recently swapped emails with a very helpful contact at the AIC who made me aware of this article on the trust:
Latest fact sheet shows the current mix of conservative holdings, similar to RICA with 60% invested in bonds. The 2 down years are very clear. I calculate the 5 year annualised SP return at 2.4% which is poor but the 10 year annualised SP return at 5.3% which beats inflation and provides a decent return until better value in the market returns. I'm certainly think about buying into this trust again.
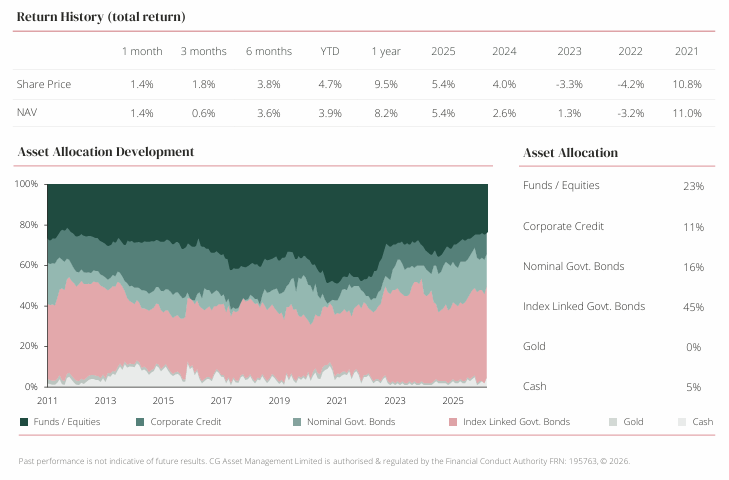
Note most of the bond holdings are relatively short dated.
And I would recommend the recent podcast interviews with Jeremy Grantham as similar thinking:
Vin Murria ('Queen of Tech') and David Hornsby (Former CEO of Ideagen)
# David Stredder interview. No specific investments discussed, more a general conversation about what works well in business.
# VM: “business is about common sense”. SSB: Lord Lee says something very similar about investing.
# VM: someone told VM that she was fortunate to be involved in something that she was good at and liked so early in her career ie: early 20s. And she has been doing it ever since.
# DH: politics changes but business stays the same. Growing free cash flow is the most important thing.
# VM: get involved in vertical software that means you own the market. Focus on customer care. Are these things barriers to entry ? If yes then that makes a great business.
# VM: only invests in stuff that she really understands so that she can help if need be.
# VM: bought 85 businesses in 30 years, almost all from founders. Ability to improve those businesses came because she was not emotionally involved and could step back and look at things objectively.
# VM: does not like what AI will do for society but will create fantastic opportunities. Best way of understanding this is by trying to break existing businesses and then understanding how AI can run those businesses better. But UK needs to get on the front foot and embrace AI the same way the America has done.
# DH: need to understand how AI will impact SAAS businesses over the next 20 years, not just next year. Owns some shares in Anthropic and thinks it’s a great business. Claude is frighteningly good at certain tasks. SSB: the US Government a couple of weeks back told Anthropic to disable Fable 5 for foreign nationals with the company taking it down completely saying it was "too powerful". I understand it is now available again but you do wonder where this whole AI thing is going.
# VM: deterministic v probabilistic systems. AI is more likely to help the former than the latter.
# SSB thoughts: enjoyable. Some of the AI comments pushed me to start doing some research and there is a ton of stuff on YouTube about coding with Claude. How to get involved to push up my account ? I will have to give that some thought.
Merchants Trust
# I'm unhappy with the performance of EDIN and so was looking to sell and invest the proceeds in LWDB as I have always liked what Laura Foll has had to say on the sector and the trust. But LWDB usually trades at NAV so was happy to listen to Simon Gergel talk about MRCH as a possible alternative.
# Invests in UK large caps.
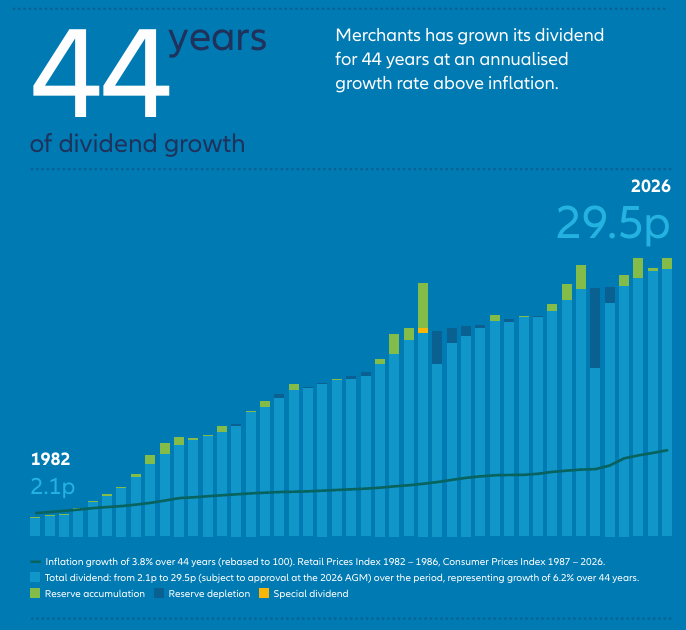
# 4.9% yield. Dividend hero: 44 years of dividend increases.
# 4% discount to NAV as at Mello date.
# 40 to 60 stocks.
# Tends to be quite contrarian whilst keeping in mind cyclical v defensive.
# Highest yielding stocks have performed well over the last 20 years.
# Cashflow (and not profits) is one of the best measures of a company.
# But how will companies perform over the next 20 years ie: structural changes eg: tobacco ?
# 3 reasons to sell: 1.) revaluation 2.) investment case changes ie: got it wrong 3.) better opportunities elsewhere (note housebuilders mentioned).
# Hikma Pharmaceuticals (LON:HIK) is a diversified global pharma company with high margin growth engines.
# Half the portfolio is in FTSE 100 Index (FTSE:UKX) because so many opportunities in mid caps over the last year.
# Currently more bias to domestic, cyclical stocks.
# Nice chart on dividends c/w reserves that I am pretty sure I found in the last annual report....
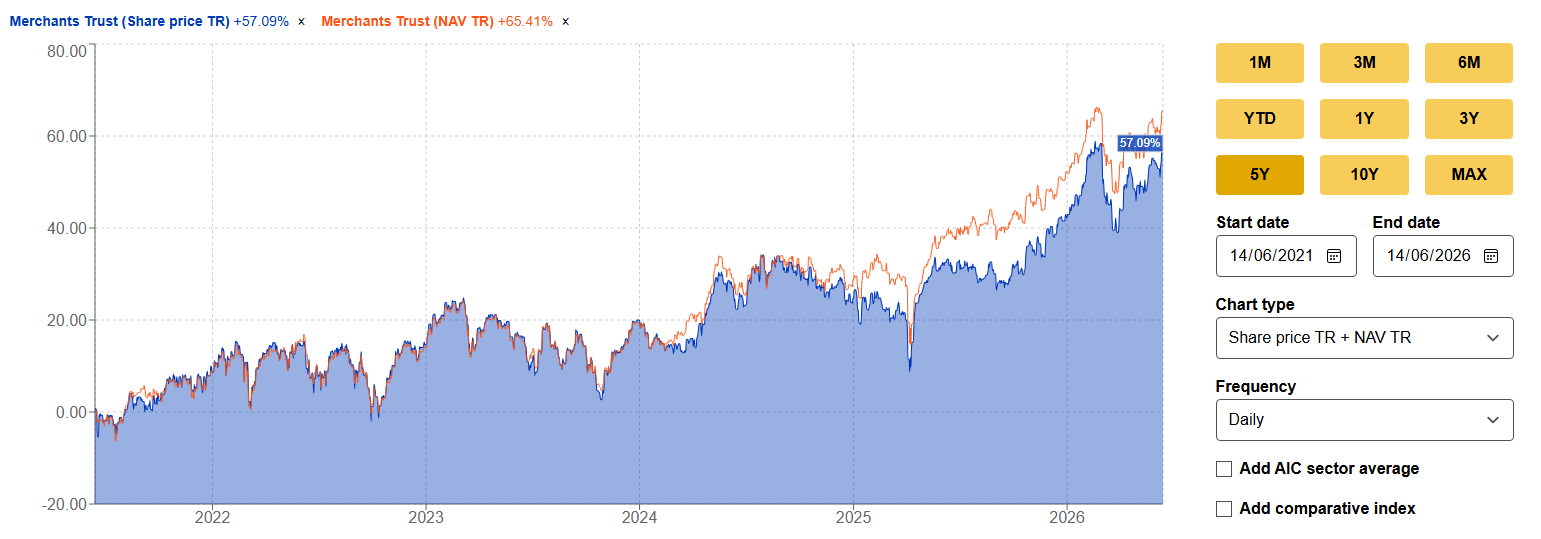
# 10 year NAV and SP total return chart that I can't find but when I look at the AIC web site, I see the following....
# Question about level of gearing (currently 8%). Answer was cost of debt is 5%.
# I asked about his current tenure and future plans. Answer was SG has been the manager for 20 years and has no plans to go anywhere. He enjoys what he does. Mgt team of 3.
# 20 years of dividends have paid for the shares.
# Market outlook: UK is cheap especially mid caps, economy is not much different to European neighbours, debt is better than France, Italy and Canada in G7, outflows have been relentless, benefits of decreasing interest rates yet to be felt in the wider economy. FTSE 250 Index (FTSE:MCX) is trading below its long term average valuations. Most of the UK market is owned by foreign investors who are not obliged to own it.
# 50 to 60bn spent on buybacks in the uK market. SSB: I don't recall the timescale but reading this now, I am assuming last 10 years ?
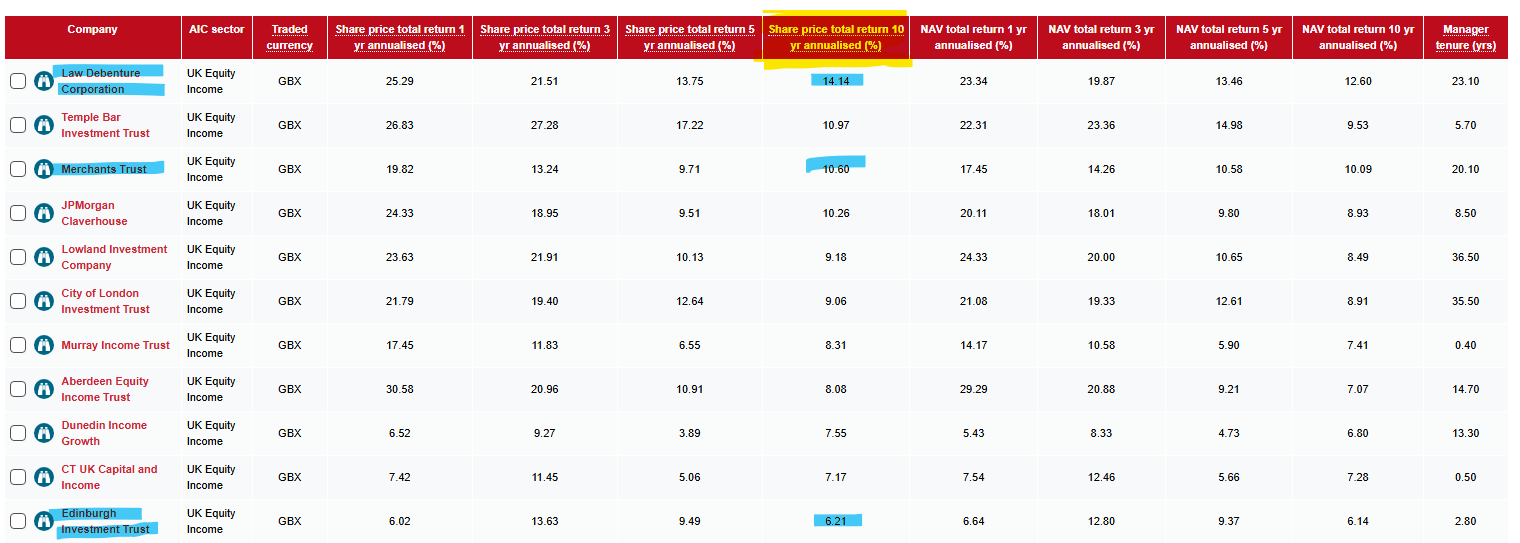
# SSB thoughts: session was well attended and the room was full as far as I can remember. How does MRCH stack up against others in the same sector ? Answer is consistently better than EDIN although the latter has been through 3 different managers over the same period of time as I am looking at below. Another thing I also no understand from a recent Money Makers podcast is how much of the FTSE 100 Index (FTSE:UKX) is foreign owner: answer is 58%! I was staggered it was this high, does this make FTSE invested trusts more vulnerable in a sell-off ? I am almost certainly selling EDIN and buying one of the better options in the same sector, probably MRCH given the thinking at Mello and the current discount to NAV.
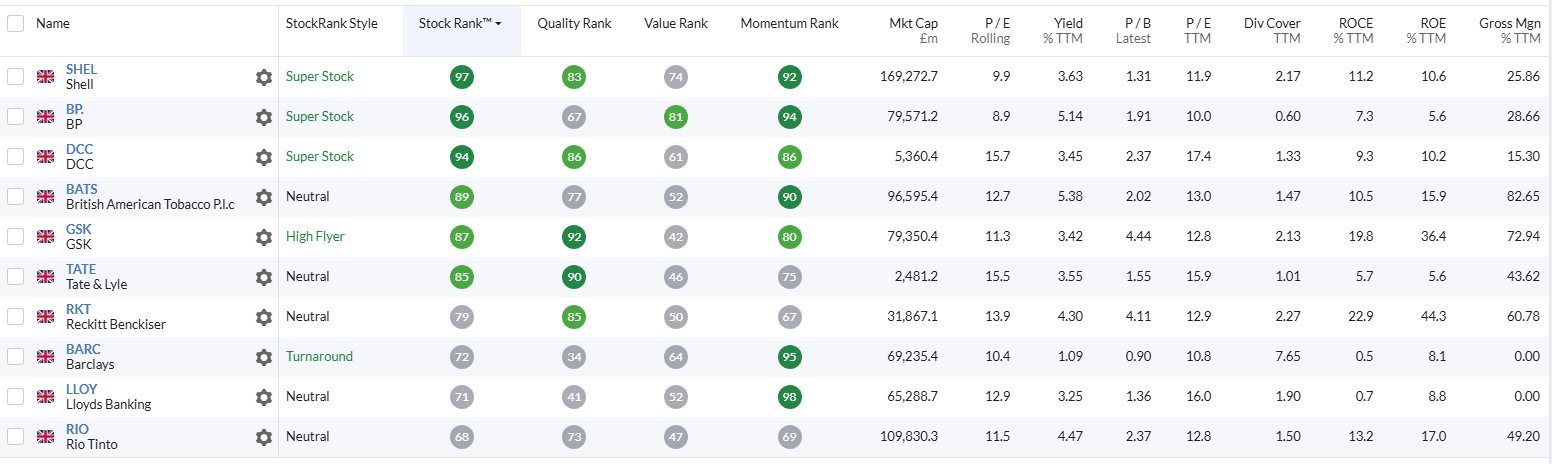
MRCH top 10 holdings (which account for 40% of the total trust NAV) have some pretty decent StockRanks....
Max King
# I was always going to attend this session, really enjoy the Money Makers podcast interviews with Max King, lots of ideas and always brings listeners back to the basics.
# Now is the easiest time to make money in the market, just ignore the media! SSB: note the complete opposite of Jeremy Grantham!
# The doomsters predicting the end of the world…. they are looking forward to it, they won’t be affected and they will come back with another prediction soon :-)
# Rising bond yields face not just risen because of inflation but because they were at a 5000 year low and were unsustainable. SSB: 100% agree and it will be a problem for the UK regardless of which political party is in power. QE was supposed to be a one-off re-capitalisation of half a dozen bank balance sheets, not a lifestyle choice for 10 years. Doh!
# UK market shows outflows but that is fine for good quality shares and trusts.
# GBP 872bn in UK ISAs. Two-thirds of it in cash!
# Savings rate is double the long term average.
# Government debt is high but household and corporate debt is smaller.
# Investment trust discounts have fallen because of buybacks ? SSB: the jury is definitely out on this one.
# Equity trust discounts down to 6%.
# TMPL, SMT and EGL (I think I have the correct Ecofin trust) have gone from buybacks to issuance.
# Trusts outperform open ended funds 80% of the time.
# Lessons for investors in trusts:
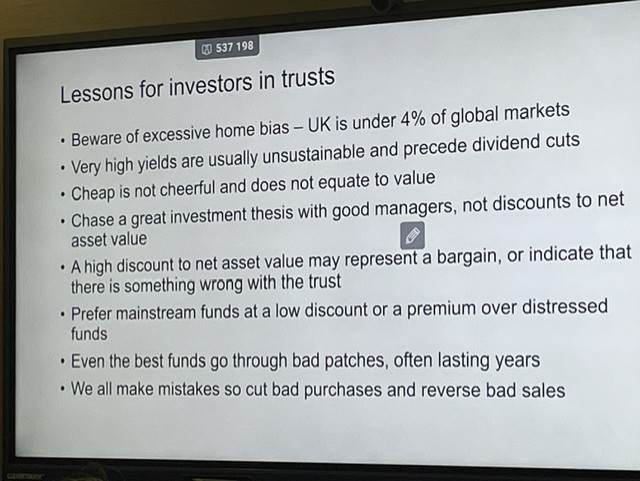
# Focus on quality and not cheapness. SSB: 100% agree because then I don't have to keep turning my portfolio over. I'm looking forward to the calendar year when I don't spend a single penny with my broker! Will that ever happen ?
# The problem with low risk companies is that you haven’t seen the risk!
# MK sold III last year (by luck). Then came the announcement that the Dutch retailer Action LFL sales were disappointing.
# Vietnam trusts oversold by their companies: they focus too much on the economy rather than the companies themselves.
# MK hopes everyone bought SMT 10 years ago! And so no need to buy now.
# The trend is your friend: October 1987 is a blip that is barely recognisable on a chart now.
# EM earnings have been strong but yet are lowly rated. SSB: this is exactly what I wanted to hear after the BRFI presentation!
# Black swan events are much rarer than you think, most events are foreseeable if you look hard in the right place.
# “A desk is a dangerous place from which to view the world”…. John LeCarre.
# Conclusions....
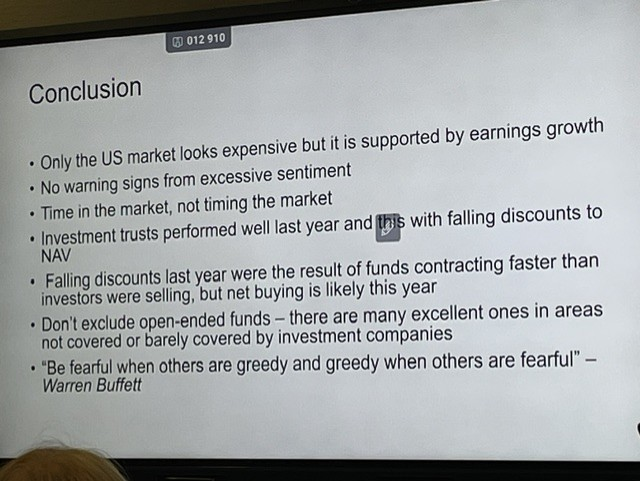
# SSB thoughts: this was in one of the side rooms but every seat was taken. Very enjoyable session an a reminder to investors like me who want to keep it simple: stick to some basic rules and buy quality off my watch list.
# Recent Money Makers podcast interview with MK repeated a number of points made at Mello: https://tinyurl.com/yc6t4mvm
John Lee
# Main theatre, packed.
# No new joke unfortunately!
# 2 key messages to be a successful investor: common sense and patience. Most lack the latter! Opportunities arise and it’s patience that allows us to take advantage.
# Secondary banking crisis in 1974 allowed investors to buy quality companies yielding 20%. Prices rose dramatically from this point. SSB: JL talks about 1974 every time he speaks at Mello so I decided to do a little research; the following is quite good and I'm motivated to try to dig further: https://tinyurl.com/mutsfzcd
# Never borrow money to buy shares, it’s just too dangerous.
# Anomalies on the UK market: M&G (LON:MNG) on a 10% yield was crazy and now yields a more sensible 6%. JL has sold a chunk of his holding. This has now gone into Primary Health Properties (LON:PHP). Which currently yields 8% but JL thinks should be 5%. SSB: I added to my holding of Primary Health Properties (LON:PHP) post Mello, that (I think) was an easy decision.
# Duke Capital (LON:DUKE) yields 11%. Another anomaly.
# There is a gap between the value of the brands and the mkt cap for PZ Cussons (LON:PZC).
# Jet2 (LON:JET2) is on a PE of 6. Good history of operations. Temporarily impacted by Iran but we should be looking at 3 years ahead noI 3 weeks (Georgina Brittain said the same thing at the start of the day).
# Housebuilders. Government is almost certain to give some sort of boost to such an important sector of the economy. SSB: if there isn't a change of PM & Chancellor again :-)
# "M" Estates at a 50% discount: I couldn't quite catch the name so maybe someone could fill this in for me please ?
# Town Centre Securities (LON:TOWN) is another good example of quality at a discount price.
# Project Burgundy is a placing by Portmeirion (LON:PMP) to bring in new capital. New mgt team. JL has subscribed. SSB: almost certainly commented on in the DSMR but I don't follow the company so apologies if I have the wrong project name here.
# Venture Life (LON:VLG) has acquired a US women’s health company.
# Most recent mistake: bought Secure Trust Bank (LON:STB) which was then hit by car loans issue. JL sold at a loss & then the drop was reversed!
# Recently bought Pebble Beach Systems (LON:PEB) on the back of the contracts with Bloomberg etc.
# Q&A followed which to JL's credit he tries to answer any question that is fired in his direction. Was he really a politician in a former life ? :-)
# As a Goodwin (LON:GDWN) shareholder, JL was shocked at the unnecessary RNS back in March. Lost tenders is surely just part of normal business ? Why was it so negative and why don’t they employ a PR team to do this ? JL still onboard but recent events should have been handled better.
# Question asked about Space Exploration Technologies (NSQ:SPCX). JL responded by saying be careful about recent trends eg: renewable trusts issued a few years back have not performed well on the whole.
# Top 3 holdings: Concurrent Technologies (LON:CNC), PZ Cussons (LON:PZC), Hollywood Bowl (LON:BOWL), Venture Life (LON:VLG), Portmeirion (LON:PMP). SSB: that is clearly 5 names and not 3 but that is what my notes say.
# Does not invest in ETFs or investment trusts. Admittedly has missed out on US tech but likes to be in UK companies where he can understand the detail.
# Would like to see oversees holdings banned from ISAs going forward. Why should the UK provide a generous tax break on overseas holdings ?
# JL knows a number of people watch the Westminster register of members interests for his buys and sells. 5%. SSB: I added to my holding of Primary Health Properties (LON:PHP) post Mello, that (I think) was an easy decision.
-------------
The following notes are from Mello back in Nov-25. I didn't have time to fully write up and share my notes then as there was too much going on.... work, family, scaffolders, roofers, plumbers and then Xmas, take your pick! Anyway, fwiw, here are my notes. You need to bear in mind they were correct as of Nov-25 but may no longer be 100% relevant now.
Polar Capital Technology Trust
# Ben Rogoff is the trust manager and has presented a number of times before at Mello.
# Polar Capital Technology Trust (LON:PCT) was launched in 1996 >>> https://www.polarcapitaltechnologytrust.co.uk/
# Now looks at everything through an AI lens [SSB: this must be incredibly difficult as the AI story seems to be developing every day!].
# Bessemer Steel example is again used to explain how whole industries are changing as a result AI.
# USD 5trn global cost of wages is the prize.
# AI is starting to problem solve.
# But is capex spending a problem ? BR explained tech capex is currently 1% of global GDP v railroad capex which was 5% of GDP at a similar stage of development.
# Agentic AI is the next big step ie: AI systems composed of agents that can behave and interact autonomously in order to achieve their goals.
# AI is scaling 5 times faster than Moores Law [SSB: I have no idea how this is known or calculated].
# There were 7 drawdowns in the Nasdaq market between 1994 and 1998 before the TMT bubble burst in early 2000.
# SSB thoughts: I don’t own Polar Capital Technology Trust (LON:PCT) or Allianz Technology Trust (LON:ATT) on valuation grounds but I have missed out on a clear long-term bull market. Is it too late to drip feed small amounts into Polar Capital Technology Trust (LON:PCT) I wonder ? The following list are the risks that I see:
# Capex spending that doesn’t create any value and therefore needs to be written off to the P&L, thereby depressing earnings. All TBC of course.
# Energy costs related to data centres.
# Debt and equity funding between different tech companies is difficult to keep up with.
# I wanted to ask a question on how good Chinese tech is but didn’t get the opportunity. Certainly the 10m price tag often quoted for DeepSeek is not correct. 10m was the last stage of development, not the total cost. But Chinese tech is good, no doubt about that so there has to be some risks to the US holdings in Polar Capital Technology Trust (LON:PCT).
Rosemary Banyard
# Discussion with David Stredder who is always good at asking open question and drawing worthwhile information out of people like Rosemary who have been around for ages and know things worth knowing. The purpose of the discussion was look st the annual reports which are the best and why.
# RB is focussed on things she likes and noted a few off the top of her head: Games Workshop (LON:GAW), black and white situations, clear and honest commentary (she particularly drew the distinction between CEO comments versus 'ghost writer' comments), prudent accounting which can clearly be seen on the balance sheet with low levels of goodwill (ie: prudent accounting) and a focus on the same numbers every year (eg: subscriber numbers x annual subscription which is an easy metric to track year on year and makes it easy to understand recurring revenues).
# RB says reading annual reports for small caps puts you at an advantage over almost everyone else because virtually no one reads them! SSB: this is quite shocking seeing as (if an investor has time), reading the reports is free! But it's so much easier to read the first few lines of an RNS and come to a quick conclusion, I have done it myself!
# Some annual reports hardly change year on year. there are good AI tools available to check this.
# Always interesting to compare statutory v adjusted earnings. If a big gap then why ? Too many adjustments usually means mgt want to hide something. If in doubt, follow the cash!
# The following were the examples that RB talked through....
J D Wetherspoon (LON:JDW)
# 2025 annual report was short and to the point: 83 pages.
# https://tinyurl.com/fs7c975k
# Colour but no photographs of the board ie: no egos.
# “Long term mindset” in terms of listing the number of pubs now (794) versus 2016 (926) v 1984 when they started (1) ie: super simple layout, same as Berkshire Hathaway (NYQ:BRK.A)
# Talks about the number of new pubs opening and importantly where eg: Bath and Edinburgh where they have not existed before.
# Tim Martin owns 25.8% of the listed equity.
# Staff own 9.3% mainly as a result of staff bonuses which refers to staff retention.
# J D Wetherspoon (LON:JDW) owns 73% of freehold assets last valued in 1999.
# Commentary makes reference to economies of scale and latest issues eg: employer NI increases.
# Zero goodwill on the balance sheet. SSB: I work as an accountant for bank and know how much discipline it takes to write off the costs of acquisitions to the P&L when potential bonuses are based on P&L.
Next (LON:NXT)
# 51 pages of utter clarity [SSB: the annual report is actually a lot longer than 51 pages but the CEO review is what I am guessing RB was referring to, and indeed it is written in a very straightforward language].
# https://tinyurl.com/34dr6anh
# Long term again as makes reference to Simon Wolfson 34 years of service, 24 years as CEO.
# No director photographs.
# The business is turning from a high street shop into a factory business. SSB: this is true as only the flagship stores remain on the high street.
# Compound growth rate chart showing CAGR of +16%.
# Common sense commentary eg: 1bn profit mark not a cause for celebration as profit per share is the important metric. SSB: someone should tell the current and past government that GDP is a worthless stat, it's GDP per capita that matters!
# Zero goodwill on the b/sheet.
S&U (LON:SUS)
# Coombs family owns 45% of shares worth £103m today.
# 2025 annual report was 96 pages long.
# https://tinyurl.com/3cn6tztk
# Not afraid to challenge financial directives eg: “the ratio of regulators to workers in the City of London has risen 4 times since 2011, having previously multiplied by 40 times since 1980”.
# Plan speaking: “average PE for the sector on the USA is 9.2, in the UK it is 6.2”.
# Provisions made across the group of approx 20% of loans made versus 10% of loans actually going bad so very conservative.
# SSB thoughts: super enjoyable session and it is only now, looking back on my notes that I recall how straightforward and transparent the discussion was.
Smithson Investment Trust
# This trust has since converted to an open ended fund. Invested in global small caps that have high quality characteristics.
# Simon Barnard presented and I thought he was very good. Clear in presentation and not flustered when asked about the transition from closed ended investment trust to open ended fund. He was also heavily invested in the trust at the time.
# The reason I mention this presentation is because I was fortunate to get 10 minutes with SB And a few others after the meeting. I asked about the open ended fund and SB insisted he doesn’t expect to have to recruit any more people to handle investor buys and sells as a result of becoming an open ended fund going forward.
# I asked about his interaction with Terry Smith. The answer was SB doesn't speak with Terry Smith that much, there is a 'formal' meeting once a year to look at the results and go through the positions. Otherwise, TS is in London every couple of months but typically only "hello" and "goodbye" in passing. SB will email TS when opening a new position or closing an existing position entirely and typically the answer that comes back is “ok”.
# The trust had a team of 4 split between Europe and America with 50% of the holdings in the latter (versus 66% benchmark). It's worth checking but I should imagine the open ended fund has similar holdings, there was no indication they would change that much. I really don't follow open ended funds that much so please check if you are thinking of investing.
# Very politely, SB asked what I invested in. I explained mainly investment trusts where the NAV is understandable (ie: I don't like too much IFRS 13 level 3 as the NAV is very open to interpretation) and good quality blue chips that are paying dividends. I have learnt to follow this method through painful blue sky guesses way back when and also quality discussion with subscribers on this site. SB nodded and maybe through asking this type of question again and again, he gets feedback in terms of how risk sensitive retail investors are; I'm guessing a little here but took a good view of SB away because of how he conducted himself afterwards.
Judith MacKenzie
# David Stredder fireside chat format.
# JM is with Downing Investment Mgt, focused on AIM.
# Looking for shares with mkt cap <500m.
# LSE consultation on AIM in April but no results yet [SSB: I don't follow AIM closely but the following looks relevant: https://tinyurl.com/3mfsrke8]
# Uncertainty around the budget “so annoying”. Politicians don’t understand the market, it doesn’t just fix itself. Pension investment in the London market is now down to 4%. SSB Jul-26: change of PM and Chancellor and the uncertainty continues, the UK is too focused on the short-term.
# JM also critical of the LSE lack of action.
# David Stredder asked if any hot tips ? [SSB: clearly not so hot given we are now in March!]
# Ramsdens Holdings (LON:RFX): northern demographic, inventory turnover, net cash. SSB Jul-26: now in a takeover situation.
# Inspecs (LON:SPEC): chair is a big shareholder. Downing went public on trying to get the chair to re-balance the board. There is value but it may take an international player to realise cost savings etc. In the self help bucket.
# Springfield Properties (LON:SPR): JM lives in the north of Scotland & demand for housing north of Inverness has risen massively due to infrastructure projects. Debt down from 49m to 26m. SSB: also recently covered in Stockopedia article.
# 2 or 3 reasons why AIM shares investments go wrong. Typically buying at the wrong time. Zoo Digital (LON:ZOO) bought & sold when the writers strike in Hollywood was on, sold at a loss quickly. Accounting re-adjustments or outright fraud are difficult to see in advance eg: Conviviality Retail.
# JM annoyed at institutions not voting. This is typically due to the fact Compliance Departments get consulted and want to be seen to take a specific view and then don’t vote. Every single shareholder should get the option of voting & then vote! [SSB: my broker has started making votes available to me online and I now take up the opportunity to do so].
# JM pretty sure there will be cash ISA reform [SSB: we all now know this happened!].
# Can't get any significant stock in Goodwin (LON:GDWN). Site visit a year or so back and it was probably one of the best visits ever. The family do not fret over the SP, they are concerned with running the company as well as they can. The SP will take care of itself.
# SSB thoughts: enjoyable and a very easy listen. It's worth attending these sessions just to hear these types of opinions, they don't get repeated in the press or officially released documents.
AEW UK REIT
# Laura Elkin presented. I think she said she has been the trust manager of AEW UK REIT for 10 years.
# Unchanged strategy for 10 years ie: UK property development and management.
# LE: "we are stock pickers, asset managers, property geeks".
# Sector agnostic value investors working through the market cycle.
# Focus is on buying high income opportunities.
# Looking to buy towards the bottom of the cycle.
# Currently 34 assets and 130 tenants.
# Initial yield and reversion yield are both good.
# Vacancy rate is 6.3%. Don’t want to see this at zero because rental growth opportunities don’t arise if zero.
# 10 year NAV return improved over the peer group around March 2020. SSB Jul-26: I don't recall if this was related to the start of Covid.
# 38% premium sale price achieved [SSB: thinking back, presumably, this is +38% over and above the latest quoted NAV].
# 92% dividend cover from rent. Trust is using proceeds from sales to top up. SSB: so a higher risk strategy compared with other REITs but they do seem good at buying property, developing it and increasing the NAV.
# Commercial property market has not really recovered since Truss budget in late 2022. SSB: I bet every other politician that ever made a mistake can't believe their luck that poor Liz Truss picks up the blame every time :-)
# Current strongest buying opportunities in high street retail and leisure.
# Need to be selective in terms of what to buy eg specific Next (LON:NXT) stores that are trading strongly.
# +40% uplift in rent on a single property in Sheffield.
# Only 2 purchases so far in 2025 so very selective. Looking for tenants that are trading strongly in affluent areas.
# 7.5% dividend yield.
# Highest sector weighting is industrials (37%).
# Good question on retail. Answer was retail is bombed out. The decline in prices has been indiscriminate.
# SSB: very good presentation. This was available on a -30% discount back in 2020/21 when everything was in lockdown. Well done to any subscribers who picked this up back then, picking up a great yield backed by very competent managers. Now trading at a small discount to NAV, there is much greater risk that capital losses could offset the 7% yield. 175m mkt cap but I don't see this being acquired by a bigger trust due to the deliberate stock picking by the managers. SSBJul-26: indeed, AEW UK REIT is looking to acquire alternative Income REIT. From my own investing perspective, I look at AEW UK REIT at being a possible future buy, just for the dividend.
Different Perspective Podcast with Hugh Hendry
# I was going to attend this but was tempted by a second viewing of Oxford Technology.
# Session was made available on Apple podcasts so I got to listen to it in the gym at a later date >>> https://tinyurl.com/yh3tt4wd
Ed Croft Page
# I was tired by this stage so stopped taking notes (sorry Ed, nothing to do with you or your presentation, I always enjoy listening to your consistent themes and the way you back up your arguments with stats).
# When I listened to the following podcast whilst at the gym I thought it definitely reminded of what was said at Mello. Definitely worth a watch / listen >>> https://tinyurl.com/yb77mhvv
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
6 comments
Thanks for the detailed notes writeup!
I was there too at Mello and it was good to see notes from some of the sessions that I missed.
S&U (LON:SUS) also stood out for me in terms of its transparent and straightforward presentation. Not quite sure about their growth strategy though.
Thank you very much for sharing your very comprehensive notes. Some companies in your list that I hadn't considered before but will do so now.
ShoeShineBoy has superbly set the scene so very happy to announce that the Mello Team have now launched Mello London, taking place on the 17th & 18th November. Early bird tickets on sale now and full event details are here: https://www.melloevents.com/mellolondon2026
For those who haven't been before, Mello is a two-day investor event that's built around what we feel matters most to investors... getting direct access to company management teams, learning from some brilliant keynote speakers, and spending time with other serious investors to share ideas or just talk investing in general - something you don't typically do down the pub or in your usual social circles!
To those of you who have been to Mello conferences before (many have attended double digits since the first in 2014), the team will of course try to improve on our Mello2026 and MelloBirmingham events earlier in the year. If you have any companies you would like us to bring along, any panels that may be of interest or areas of investing you would like Mello to cover, please do drop your suggestions below.
Richard Staveley Rockwood Strategic (LON:RKW) & Lord John Lee will be returning to our keynote stage. A handful of our other investing heroes and respected fund managers will be on our Mello Theatre stage. Again, 50+ quality companies will be delivering investor presentations and exhibiting in our main hall (scroll down our Mello London page to see the companies that were on show at our Mello event in June).
As the formal presentations wrap up, and just before investors start to relax in to the evening chats, we will have our ever-popular BASH (Buy, Avoid, Sell, Hold) panels featuring investors such as Richard Crow, Jamie Ward, Paul Scott, Mark Simpson, Lord John Lee and more. The Mello Team will be pulling out all the stops to make this as great a Mello event possible. I hope to see as many of the Stockopedia community at the event with us...
Important to note, tickets are on early bird for few more days until 4th August, making it just £69 for a one day pass or £99 for a two day pass... Booking early particularly helps us with event planning and making Mello as smooth an event as possible! Investors can save up to £100 by booking early and our MelloMembers receive a further 30% discount.
If you miss the early bird, use code Stocko25 for 25% off General Sale & Final Release tickets: https://www.melloevents.com/mellolondon2026
See you in November for Mello London, it is going to be an excellent two days for investors - Mello really is a very open and welcoming investor community so do join us!
David
Great write up SSB. It is good to get a reminder of what was said and to potentially go back a couple months later and see what has occurred since.
I attended a lot of these as well and the quality of presentation on every session was outstanding.
I hope Novembers line up is as good, and must book my tickets.
I think the missing company in Lord Lee's presentation may have been Mountview Estates (LON:MTVW) but not 100% certain.
On B.P. Marsh & Partners (LON:BPM) I too was a bit underwhelmed after their presentation - it is clearly a more complex company than I had thought and as a result of it being more complex and its NAV a bit more open to "interpretations" I decided to sell out, having bought into it last year. However, there were so many good ideas from the two days I had plenty of other options to invest the capital. In fact, my watchlist is still brimming with stuff I want to do more research on, but I also need to keep reminding myself that ETF's & Investment Trusts need to remain 70% plus of my PF and not to overexpose myself to UK Smaller Co's.
Excellent write up SSB and so pleased you enjoy these conferences and then take the time to do this...
Just a reminder to everyone that we have already launched the H2 MelloLondon conference which will be on the 17th and 18th November in Chiswick again and we are building up an even bigger programme as these events are selling out....Already 37% of the Early Bird first release tickets have gone in the first three days on sale so do not leave it long to get one and save £100 by booking early. That helps our team build up the programme and set up the excellent speakers in the knowledge that we have huge audience for them. Here is the webpage....
https://www.melloevents.com/me...
Amazing effort. Thanks so much.