Mineral Resources: A large cap focused of getting larger

It’s not everyday that you see an $8B company double in size over 6 months.
And so it is the case with Mineral Resources (ASX:MIN) who from their recent lows of $42.89 in July 2022, has risen by over 100% to now be $88.35 and a $16.6Bil company.
Mineral Resources for those may not be aware is a diversified resources business with interests crossing:
Lithium (World top 5 lithium producer)
Iron Ore (Australian top 5 iron ore producer)
Mining Services (MIN is the world’s largest crushing contractor)
Energy (Largest landholder of gas acreage in Perth and Carnarvan basins)
The success of MIN has led to long-serving MD Chris Ellison to be elevated onto the front pages of the financial press as a pin-up boy for the industry. While this is traditionally a point where I get nervous, Mr Ellison has not sought the limelight, rather the light has found him through the extraordinary numbers they have produced.
As with any company who experiences such rapid rises we need to, first congratulate holders, but then also ask ourselves from this point what are the likely prospects of MIN moving forward and how does the company stack up overall as a potential investment opportunity.
StockRank ™
It may come as a surprise to some that a company with a market cap touching $10B could have an overall StockRank score below 70. We will discuss that now.

Obviously the 92 for momentum stands out. Not only because of the extraordinary price rise, but also for the fact that analysts had been upgrading their forecast EPS for the company for the past 12 months.
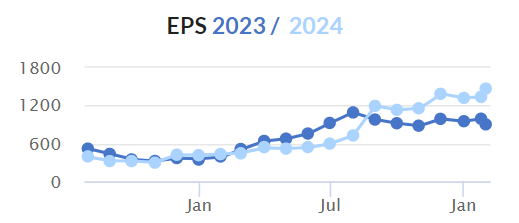
However it should be noted that for the FY23 forecast (the darker line), EPS forecasts have actually moderated somewhat since July, and even after their most recent quarterly (which I will discuss in a moment) there has been a slight downgrade again. Fortunately FY2024 doesn't seem to have been affected and MIN continues to maintain its solid earnings momentum trajectory.
Price too has obviously been on a strong trajectory reflecting the business trajectory of the past 12 months. The price pullback in December may have unsettled a number of investors, however the recovery has been swift as some investors took advantage of the price weakness.

But excluding the up and downs, on a relative basis MIN has deservedly been one of the best price performers of the past 12 months earning green circles aplenty under the momentum scoring system.

But the immediate question to be raised is what about the other two factors? Quality and Value?
Quality
Quality is slightly below 80 on account of a weaker than average Health Trend (Piotroski F-score). More specifically debt has been rising, cash flow is getting thrown into capital expenditure and all while last year the price of iron ore fell.

While some of these issues are temporary such as the iron ore fall given prices have rebounded since their lows, the themes of expansion are not. Investors should be aware that this is a company in a hurry so cash spend will likely remain high.
Acquisitions
This progressive behaviour is no better exemplified than by the announcement that it is to acquire all of the fully paid ordinary shares in Norwest Energy NL (ASX:NWE) that it does not already own to consolidate the Lockyer Deep’s project ownership following recent exploration success (it had a 19.9% interest in the business).
It even made a cheeky play at another WA Gas play Warrego Energy (ASX:WGO) where it acquired 19.17% interest in the business during a time when Strike Energy (SRK) and Hancock Energy are also battling for WGO shareholder affections. Even if MIN misses out, there is still a healthy gain expected as much of the accumulating was completed at much lower prices. MIN has a significant interest in the Perth Basin and they are not collecting handbags (this was in reference to a comment made in the analyst call) so it will be interesting to see what happens there.
The company has a long history of entering JVs first before making a full play as they wish to see whether any business is a good fit first before they heavily commit. It has no problem paying more for an asset if it is sure it has de-risked the return.
Despite the aggressive growth plans, MIN are profitable and the recent turn to favour in the commodity prices it works with will hopefully aid the Quality score when they report on 24th February
Value
As far as Value goes, this too is a little short term. An EV/EBITDA of 18 on a mining stock deserves a raised eyebrow in any situation. While current metrics look stretched, the iron ore commodity cycle worked against it last financial year. However when you look at estimates, including the expected +492% EPS Growth next year you can see how Value as a metrics is in a state of flux relative to commodity cycles This is traditionally always the case and is one of the reason many Value Investors choose to stay away from Commodity Stocks despite how at times they look extraordinarily cheap eg Coal stocks.
One of the other factors which keeps supporting the price of MIN is the discussion that MIN may be looking to split the business in two, separating out the Lithium business from the Iron Ore, Energy and Crushing business. Why would this make a difference? Within analyst circles we often consider Sum of Parts valuations as some of the more valuable/optimistic in terms of price valuation setting.
The theory is that the sum of parts of a business, which has multiple different divisions, when added together as separate standalones is often seen as more valuable than the whole. If that theory rings true, the two businesses, rather than just the one, will be worth more in total and therefore the elevated valuation currently would be more justified.

To close off on the StockRank ™ discussion , and to provide some context, though the previous annual result saw the score dip below 80 for the first time in a while. The company has a strong history of greater than 80 StockRank score. Hopefully when their next set of numbers are analysed within Stockopedia that trends of above 80 score returns.

Their latest quarterly
With mining stocks we receive quarterly updates on how the business is tracking. The good news is that analysts will capture this information and include it in their estimates which ultimately filter through into Stockopedia.
However it is recommended that for any mining investor you read this report (at least the first few pages) in order to glean a more thorough understanding of what is going on within your business. As this was the second quarter report it is also particularly pertinent as the two quarters (September and December) will drive the first half year result and often a guiding statement is made in the 2QT (and 4QT) updates.
In this latest update MIN posted a steady performance overall for the quarter. Though pricing received was good, on balance operationally it was more on the slightly disappointing side. Much of the disappointment stemming from the Mt Marion Lithium operation (located 40 km south-west of Kalgoorlie) .
Over the quarter spodumene production from the Mt Marion operation came in at 121kt (which was below expectations and the pcp) and resulted in shipment volumes also coming lower than anticipated at 116kt. Further the work to expand Mt Marion to annual production of 900kt has been pushed back slightly to July on a delay in processing equipment and tight labour.
The delays meant the company was forced to cut production guidance to 250-280kdmt (from 300- 330kdmt) and also increase expected costs.
On the positive side, the ramp up of Wodgina continues to progress smoothly with lithium spodumene concentrate production of 92kt. The project remains on track to achieve FY23 shipped guidance of 190-210k dmt (MinRes 50% share). The company has said that all three plants at Wodgina have been commissioned, although only two are operational until mining volumes pickup post the Stage 2 cutback (mid-2023) - this was something that was discussed in the analyst briefing call afterwards which you can access the transcript here if you are interested. .
Further the company recorded its first Lithium Carbonate sales for the quarter, another milestone and revenue generator for the business.
The Iron Ore business also saw the benefit of a return to more positive pricing. It was able to realise an average price of USD$97 per dry metric tonne which was 33% higher than the previous quarter. This was pleasing given the quarter on quarter Production growth achieved by the business from both the Yilgarn and Utah Point operations.
The company continues to work on getting the 30+ year Onslow Iron project online with production expected to commence in the later quarter of this year. We also got to see some photos of progress including the construction of a runway that has A320 aircraft capacity.

Lithium boom - can it continue?
The question everyone wants to know - While MIN provided no real guidance on this - they did highlight that they will be in the thick of it.

Source: MIN AGM
According to the company, MIN produces 29% of the world’s total hard rock lithium supply and the sales forecasts for electric vehicles remains strong so they are confident that from their perspective, things will continue as is for the moment.
Dividend
One pleasing factor is that the company pays a solid dividend and that will likely continue next period. Historically, when it can, the company has maintained a payout ratio of 50 percent of Profit After Tax.
On forecast estimates at the moment that will likely result in a yield at around 4% Fully Franked. Though Free Cash Flow was negative in the full year to 2022 as discussed, the rebound in pricing will likely see the company continue to support this policy in the new financial year.
Conclusion
There are not many large cap miners who have the future production profile growth that MIN possesses. While the Lithium, Iron Ore and Gas prices will play a significant role in the direction of the stock price from here, when it comes to the factors it can control (ie lifting production) the prospects look solid.
Coupled with that is the excitement around the corporate activity it has been undertaking and there is a lot to keep investors on the edge of their seat.
____
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
The author holds interests in the following stocks mentioned in this article: MIN. This position can and will change at any time without notice.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
Good report thanks
You're welcome jabconsl. Glad it was of value. Ta.
Valuable , especially leading into reporting period. Thanks Elio
Thanks for the feedback Sagie_5!