Mining for value gold

The recent surge in gold prices has brought a renewed interest in the sector from investors, and it is leading many to learn new terminology and concepts that don’t apply to non-mining sectors. There is a popular joke that a gold mine is a hole with a liar standing at the top. There is perhaps an uncomfortable truth to this, as it is impossible to know what is truly underground without digging it up. Faced with having the wool pulled over their eyes too many times, investors and banks now demand that mining companies provide independently compiled reports that model the underground gold-bearing structure [such as those compiled to the industry standard Australian "Joint Ore Reserves Committee" (JORC) Code].
Exploration activity usually starts by taking electromagnetic surveys, followed by soil samples or rock chips in areas that look similar to previous gold finds. Promising areas are followed up by drilling holes intended to intersect the mineralisation. The more holes that are drilled, and how tightly spaced they are, give greater confidence in the underlying gold-bearing structure. However, there is still uncertainty, and the independent reports reflect this by providing the amount of resources that may be present in different categories, of increasing confidence:
- Inferred: Lowest confidence. Only general geological information; significant uncertainty.
- Indicated: Moderate confidence. Quantity and grade are reasonably well understood.
- Measured: Highest confidence. Quantity, grade, and continuity are well established.
Then there is the issue of whether these resources can be profitably extracted. In order to finance a mine, investors demand a Feasibility Study, which models the economics. Resources that are considered economically extractable are known as reserves, and are reported in two categories:
- Probable: reasonable but lower confidence in extraction feasibility, or with economics, preliminary feasibility studies.
- Proven: highest confidence in extraction feasibility and have been economically evaluated.
Whether a mine gets built or not depends on what is known as a Final Investment Decision. Those putting up the money will consider if the possible financial reward generates an acceptable return compared to the risk they are taking and how that return stacks up against other opportunities.
When considering this process, it struck me that this same probabilistic approach could be applied to Value Investing. Investing is a process wrought with uncertainty, where returns are based on an uncertain future. An investor's skill is in managing that uncertainty in order to profitably extract value. Value investors start with a general idea of where value may lie. They drill down into the fundamentals, developing a greater confidence in the level of undervaluation. They then have to understand if that undervaluation can be turned into a profit, avoiding so-called “Value-Traps” where the gap between price and value never closes. Finally, in order to invest, they have to weigh up the risk-reward against other opportunities.
Initial Scoping Studies
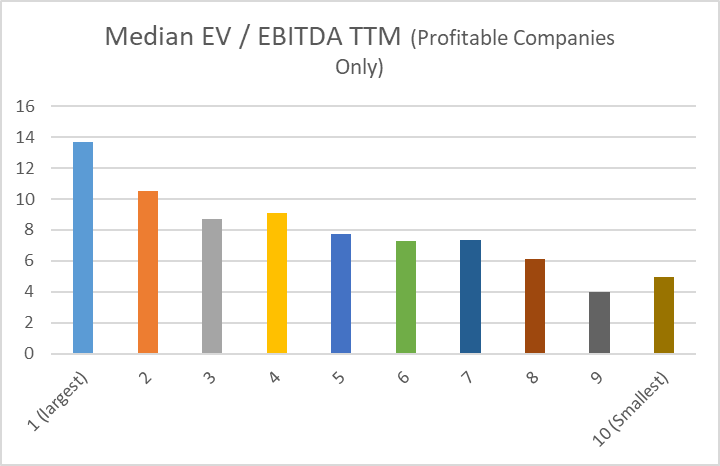
Miners don’t just drill randomly. They use geological knowledge to look for places they think gold is likely to be found in economic quantities. Value investors can do the same and look where undervalued stocks are most likely to be to be found. In the UK, this may well be profitable smaller stocks (or at least anything below the largest 150 companies) as my favourite chart at the moment shows:
Value investors may also want to consider where the most hated stocks in the market are at any one time. In the Dotcom Bubble in 1999, old-world stocks that were so hated that they had become incredibly cheap and generated strong returns even as the broader indices delivered strongly negative returns. At the moment, it may be stocks that everyone thinks will be disrupted by AI that no one wants to hold at any price.
Possibly Undervalued
Going from a broad idea of where value may lie to generating specific targets, gold miners take rock chip samples or do initial drilling. The value investor will typically use tools such as the Stockopedia Stock Screener to do their initial drilling. Investors can use simple screens based on known Value factors. For example, smaller companies that are profitable and trade at a discount to Tangible Book Value are possibly undervalued.
Equally, companies that are on a relatively low EV/EBITDA and have recently grown EPS are possibly undervalued.
Investors can use these types of screens to generate a list of targets: companies that are possibly undervalued.
Probably undervalued
To determine if an initial gold find is large enough, there is no substitute for further drilling. Likewise, investors will need to drill down into the fundamentals of these businesses in order to conclude that they are probably undervalued. These are the sort of things they may consider:
Financial Strength: It is essential when looking at cheap stocks to ensure that the business survives to benefit from any eventual recovery.
Earnings Power: An undervalued business should be able to generate substantial profits from its operations over the long term. That doesn’t mean that it will do so every year and in all market conditions. Looking at longer-term trends to identify a business suffering from a short-term and fixable blip in earnings may be the key to getting a bargain.
Cash flow: Cash is king, they say. It is cash flow that enables companies to fund capital projects to grow the business or make returns to shareholders. Investors should be wary of businesses that report profits but where that never turns into cash flow.
Assets: Finding a company at a discount to its net tangible assets can signal a great value opportunity. Typically, these will be going through a challenging period for profitability, yet the upside will be considerable if those assets can be made productive again. However, not all assets are created equal. Liquid assets, such as cash and working capital, may be more readily realised. Freehold property may be undervalued on the balance sheet, adding to the case for undervaluation. There is often no substitute for drilling down into the details with an asset play.
The Stockopedia StockReport can be an excellent drilling tool for this stage, as it allows investors to drilldown to the fundamentals of a business quickly and easily.
Feasibility studies
Not every gold find is commercially viable. Grade, location, depth and political factors all feed into making the difference between a commercial enterprise and a nice story. For Value Investments, almost all gains come from improving returns on capital in the underlying businesses. This may come from better management, cost-cutting, new sales initiatives or simply the natural economic and market cycles. However, the management of some companies appear resistant to making the necessary changes to improve their fortunes. We often call these Value Traps, as they remain undervalued for far too long to be successful investments, yet the apparent undervaluation traps the investor in them.
Value Traps typically have one or more of the following characteristics:
- A lack of ambition – they are often smaller companies, and they want to remain small.
- Slow pace of change - especially when it comes to deploying capital into higher-return areas.
- High board pay – if the board are much happier paying themselves a bonus rather than returning excess capital, they have little incentive to shake things up.
- Poor shareholder communication – they treat their owners as a nuisance rather than an asset.
- Controlling shareholders – obvious undervaluation will attract shareholders wanting to agitate for change. However, if a large shareholder controls the company, this makes forcing change impossible.
Investors should filter out these types of companies, no matter how compelling the level of undervaluation first appears.
Final Investment Decision (FID)
The decision to invest in a mine takes into account all the possible factors, not just the size of the gold reserves and will include all aspects of funding. Likewise, a decision to invest in a value opportunity will not just be based on the level of undervaluation, but other factors should come into play:
- Risk: Some companies are undervalued because they operate in very risky places or have products that are especially vulnerable to political risk. Investors don’t need to weigh up the level of undervaluation but the risk-reward ratio.
- Quality: All things being equal, investors will prefer undervalued companies that are higher-quality.
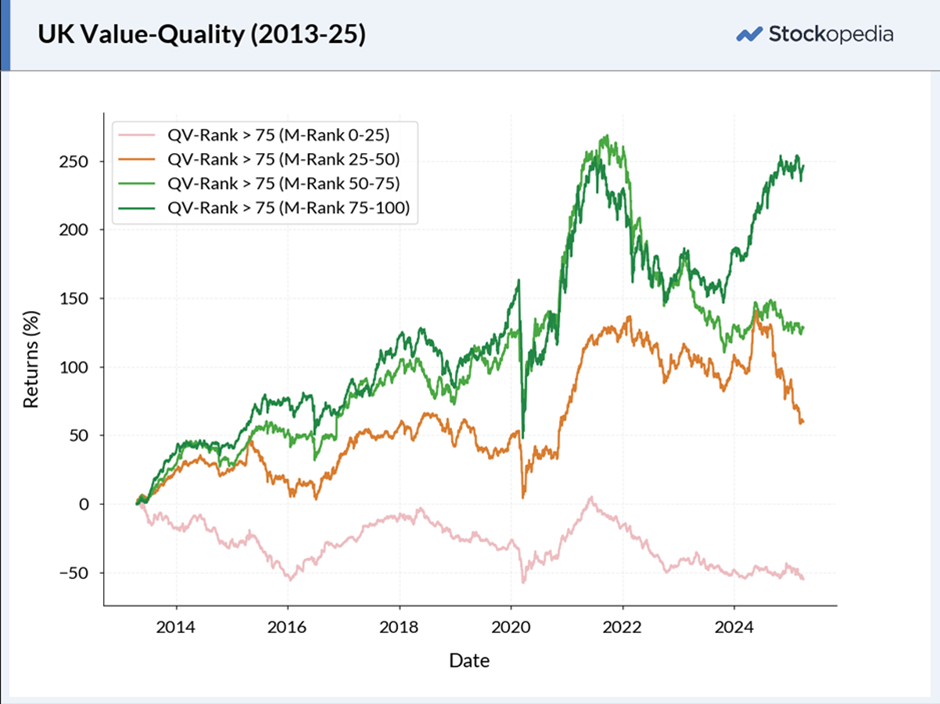
- Momentum: I love cheap, high-quality stocks. However, there is a chart that throws a spanner into the works. There are times when only looking at Quality-Value does well. However, over the very long term, buying into stocks where the Momentum Rank is very low is not a great strategy, no matter how compelling the undervaluation appears.
- Outlook: The Stockopedia research into profit warnings shows that a short-term miss often presages further warnings or share price weakness. An unusually large H2-weighting can also indicate that a company is going to struggle to make the numbers.
- Portfolio Management: When buying into an undervalued business, investors need to consider how that sits within their overall portfolio. The reality is that sometimes whole sectors are undervalued, and investors may be tempted to hold many similar opportunities. This may make sense, but investors should not be blind to the risks that holding many investments exposed to the same economic factors presents.
When it comes down to it, when to buy can be as important as what to buy, and these factors will help investors decide on the right time to invest in undervalued opportunities and how much to invest.
Further Drilling
When a gold miner enters production, they often do so with around a decade of reserves to support the production profile. However, that doesn’t mean a mine closes after 10 years. Mineralisation often remains open at depth, and close-by “satellite” resources may be available. Miners keep drilling to add resources and reserves during the production phase. Value Investors would benefit from the same approach. We don’t need to know everything about a company to invest. Indeed, I have known some investors who spend so long researching an obvious undervaluation that the valuation gap closes during their research period!
Once an investment is made, we shouldn’t stop drilling into the fundamentals. Understanding a company better may give greater confidence to increase position size (although overconfidence can be a risk here). Conversely, information may come to light that undermines the original investment case. This is one area where investors have an advantage over the miners. While a gold mine in production is there until production ceases (or it gets nationalised!), investors can sell and move on to better opportunities.
A Corollary
While I have been using the example of Value Investing in this article, the same principles of moving towards greater certainty during the investment process apply to other forms of investing, such as Quality. I could have easily started with a screen looking for companies with consistently high returns on capital. Drilling down would involve assessing the size and sustainability of the economic moat of a business to identify which companies are most likely to be quality compounders. FID would occur based on finding a business available at an acceptable price. By following the process that gold miners use to find and fund economic mines, all types of investors can make a mother lode.
May we all find investing gold in 2026!
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

17 comments
Great article ! Could you make the screens into 1?
Thanks M B3,
It seems that there is actually two different types of stocks that get taken over (actually four if you include the different options for high levergae and net cash for each screen) so I don't think it possible to combine screens without ending up with such a vague screen that generates a lot of screen results (i.e. too many to research fully).
Cheers,
Mark
Thanks
Thanks for running the numbers on momentum. It is a particular temptation of mine to be contrarian in that way.
Thanks Mark for the interesting article. You mentioned and I quote "At the moment, it may be stocks that everyone thinks will be disrupted by AI that no one wants to hold at any price." I have seen some stocks fall significantly due to this precise reason. I did search on Gemini and these UK stocks came up as being one of the most impacted: Rightmove (LON:RMV) , Auto Trader (LON:AUTO) , Future (LON:FUTR) , MONY (LON:MONY) , Pearson (LON:PSON) ; Reach (LON:RCH) and WPP (LON:WPP) . I am invested in Future (LON:FUTR) and it looks so cheap on a fundamental basis and hopefully will re-rate significantly if reality is not as bad as this AI disruption narravite seems to suggest.
Hi Alok,
I like the use of AI to work out the most affected by AI, there feels a certain irony to it!
I agree on Future, and also have been adding there. It jumped up on reasonable results, and since then has just continuously sold off. Given the high volume yesterday after the initial ex-dividend drop, I wonder if an overhang has just cleared?
You have a forward P/E of less than 4, with 95% conversion to FCF guided, which they are using to buy back shares. Plus an AI part of the business that is already generating revenue. I think it takes a lot more disruption than we've seen so far to make this business dead in four years, which is what the market is pretty much pricing.
Mark
I would (LON:RWS) to you're list. I agree the disruption will lower and slower than thee market thinks.
I agree. Although Gemini didn't higlight this stock but I understand the market narrative is that AI will disrupt their business model. I own this stock and has addded more recently.
Thanks Mark for this very useful piece. I have already applied the principles this morning and now feel much more confident and assured regarding an investment decision I had planned to action today.
Glad you found it useful :-)
There have been some very useful articles recently on Gold and other precious metals. As usual with the Stockopedia indexing system, these are not easy to find as threads get older and content lost.
I notice that there are TAGS at the bottom of the article, which in this case are- VALUE INVESTING, FOLIO MANAGEMENT and STOCK SCREENING. Nothing about the subject of the article, Gold.
Would it be possible to add a GOLD/PRECIOUS METAL Tag - or something to that effect? If so, would it possible for authors to go back in and edit their tags in retrospectively include a new Tag?
This would help fill a gap where an article is a specific subject, but covers number of Stocks. It would also help with finding the more interesting etfs that are mentioned, but difficult to find or remember outside the article.
Any thoughts?
I agree the tagging system isn't always the most useful, I'll take this back to the content team to discuss. Thanks for raising it.
I am not very active here at the moment but my thinking is that it would be much better if the user could add his own tag and or bookmark an article or even a comment and bookmarks would then appear in their account.
Regards
Michael
Totally agree. It's often impossible to find past articles. The search feature is dumb.
OK Mark, you have given us some analysis of the market but the conclusion has to be suggesting some companies you would consider in light of your analysis! I have decided on AMRQ as they are just entering production and the FY forecast is excellent. Needless to say Donald Trump is the concern in light it being in Newfoundland. I have decided all the hype is overrated and will continue to hold. Any other rsuggestions?
Hi dereksp,
I'm not sure you have completly understood where I was going with this article. It was about applying the process that gold mining companies use to find gold and plan mines, in order to find intersting investments in all market sectors. It wasn't about only finding investing ideas in the gold sector. You can check out my article on gold producers here, if that's what you are after.
Amaroq may have attractions as a miner, but perhaps not as a Value or Quailty investment unless they have a bit longer production under thier belt, if you look at the StockRank:
If you are intersted in using this process in the wider market I did create a couple of screens where the valuation metrics would be a good starting point. Here are the top ranked companies from these screens:
Only one of these companies actually produces gold, though!
HTH,
Mark
Gold is just so elusive!