MMS: Benefiting from government policies

McMillan Shakeseare (ASX:MMS) was one of the inaugural stocks picked for the NAPS Australia and New Zealand portfolio at the start of the year. At the time it had a StockRank of 98. Since then it has been the third best performing stock in the portfolio with a return, including grossed up dividends, of 39.8%. If the NAPS portfolio was to be prepared today, it would still make the grade. It has a StockRank of 96 and its prospects remain bright.
McMillan Shakespeare operate across three segments:
Group Remuneration Services
Asset Management Services
Plan and Support Services
Asset Management Services is the biggest contributor to revenue at about 58%, but not the biggest contributor to profits as it operates on tight margins. This business is about providing vehicle fleet management as well as an asset finance aggregator. The latter involves providing access to a panel of lenders for finance brokers.
Group Remuneration Services contributes about 36% of revenue. This business involves salary packaging and novated vehicle leasing.
The vehicle leasing industry has witnessed some unusual effects in recent times. Firstly, new car sales have started to pick up over the last 12 months following a steady downtrend for the past few years. This was exacerbated by reduced production in the early part of the pandemic.
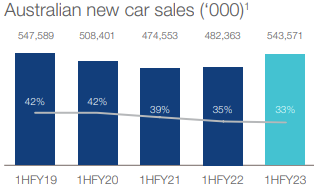
Source: McMillan Shakespeare Limited (MMS) Interim Results Investor Presentation, 22/2/2023
The lack of new vehicle supply has led to used vehicle prices reaching record levels. The drop in new car production at the start of the pandemic has now created a shortage of three year old vehicles adding further upward pressure to used car values.Used vehicles prices remain very elevated although they have come down from the peak as shown in the used car sales price chart below which compares how used car prices have tracked since the start of the pandemic and also contrasts it with the experience of the GFC.
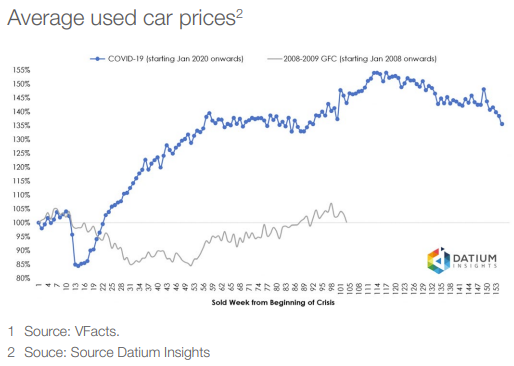
Source: McMillan Shakespeare Limited (MMS) Interim Results Investor Presentation, 22/2/2023
And then there is the electric vehicle (EV) effect. Recent changes to fringe benefits tax for electric and low emission vehicles have made it far more attractive to lease these types of cars. As the chart below shows they are rapidly growing in their significance to the lease book.

Source: MMS Investor Session, 1/5/2023
The graphic below shows just how much more attractive it is to lease an EV. A $66,000 Tesla effectively costs about the same to own and operate as a $40,000 Mazda. This has made EVs a far more competitive option.

Source: MMS Investor Session, 1/5/2023
The third segment is Plan and Support services. This is relatively small at 8% of revenue, but is growing strongly with revenue growth of 20% in the first half. This segment provides services to participants in the National Disability Insurance Scheme (NDIS) who require assistance with managing their plan.
There are about 573,000 people receiving NDIS support at the moment and 58% of them require plan management (the others are self managed). MMS is the second largest provider in this fragmented market with 5.1% market share.
McMillan is a high quality business with a Quality Score of 90. Aside from a hit during the COVID panic of 2020, their revenues and profits have been very consistent. The Health Trend of 6/9 is only dragged down by a deterioration in the debt position. Gearing levels are quite high with net gearing at 83%. This includes $206 million in bank debt offset by $113 million in cash.
McMillian has been able to generate strong returns with return on equity now 33%. They have also been increasing their dividend payments at a high rate and underwent a $90 million buy back in the first half. Dividends are fully franked.
The high returns on equity and capital management have led to a strong appreciation in the price. The Momentum Score is currently 94 following a 94% rise in the price over the last 12 months.
Of course this strong run up in price has had the opposite effect on the Value Score. It has declined recently, although is still a very respectable 72. A forecast PE ratio of 15 is low for the industry, but about average for the market.
Revenue growth and earnings have been steady but not exceptional. Right now there are some tailwinds in the areas of EV leasing and the NDIS, but both of these rely quite heavily on favourable government policies. Regulatory risk is currently working in their favour but that could easily change. For example the NDIS budget is growing at an unsustainable rate and the program is likely to undergo significant changes in the coming years.
Overall the stock looks attractive on many fronts, but things to keep a close eye on include debt levels as well as the revenue and earnings growth.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?