More ways to profit from director trading

Last week, I wrote about director trading and how investors can profit from a legal form of insider trading. We explored how firms are required by law to disclose any trade made by a director. Investors can piggyback directors’ transactions and follow the ‘smart money’ — i.e. insiders who have intimate knowledge of a company’s future prospects. Disclosure rules help level the playing field between private investors and figures like Gordon Gekko, the fictional financier from Wall Street, who famously quipped, ‘If you're not inside, you're outside!’
As a general rule of thumb, a director buy is a bullish sign. Conversely, a director sell is a bearish signal. Of course, every answer sparks a new question. There are always exceptions to the rule. Readers rightly pointed out cases where a director buy was followed by a declining share price. I was reminded of the old adage: “Never cross a river that is on average 4 feet deep.”

Averages and general rules can be misleading in individual cases. What we need is a lens to look under the bonnet and gain a more nuanced understanding of the data behind the aggregates. The trick is to do this without getting bogged down in excessive detail.
This is where diversification and base rates both come in handy. Diversification, they say, is the only free lunch in investing. Base rates allow us to extract meaningful signals without drowning in detail. By diversifying across good base rate stocks, investors can navigate the treacherous waters between detail and abstraction…
The less I know, the better
In the stock market, detail can be a curse. Investors are bombarded with an overwhelming swarm of news and media hype. Without a way to filter out noise, investors risk becoming like Jorge Luis Borges’ character, Funes the Memorious, who could recall everything he had ever seen — every detail, every moment, endlessly stored without the ability to filter or forget. Funes became blinded by information, unable to generalise, abstract or function. He died a young death. What he really needed was base rates — statistics which abstract away the noise and give the signal.

In investing, base rates could refer to the probability that a particular class of stock will outperform the market. James O'Shaughnessy explains the concept in What works on Wall Street. Imagine a town where 70% of the population are lawyers and 30% are engineers. (My worst nightmare!) If we randomly select a citizen—let's call him Dave—statistically, he is more likely to be a lawyer. However, research shows that when given descriptive details—such as 'Dave enjoys carpentry, LEGO, and maths'—people tend to assume he is an engineer, even though the base rate (70% lawyers) suggests otherwise.
In reality, we improve our accuracy by focusing more on base rates and less on descriptive characteristics.
Director deal base rates
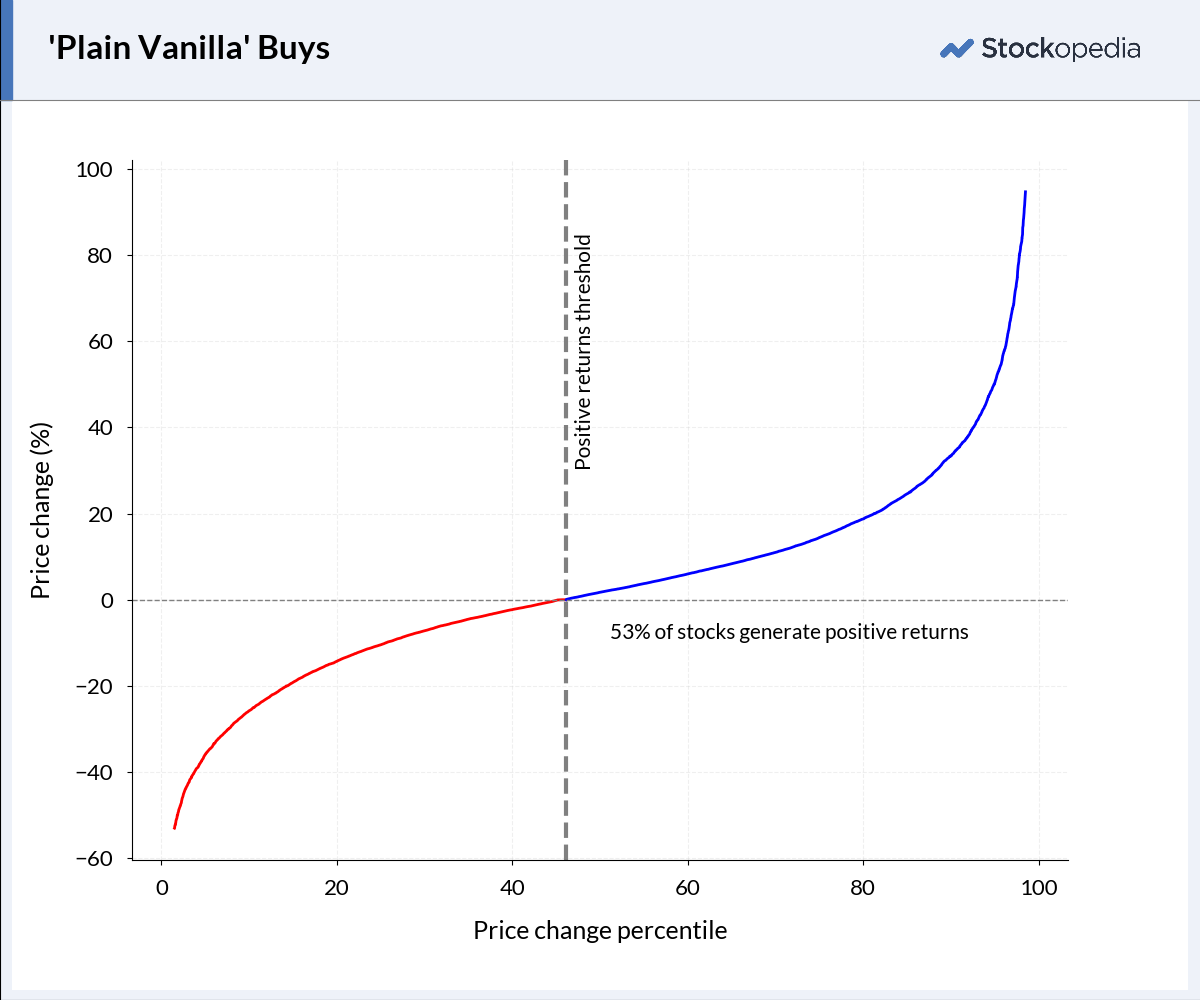
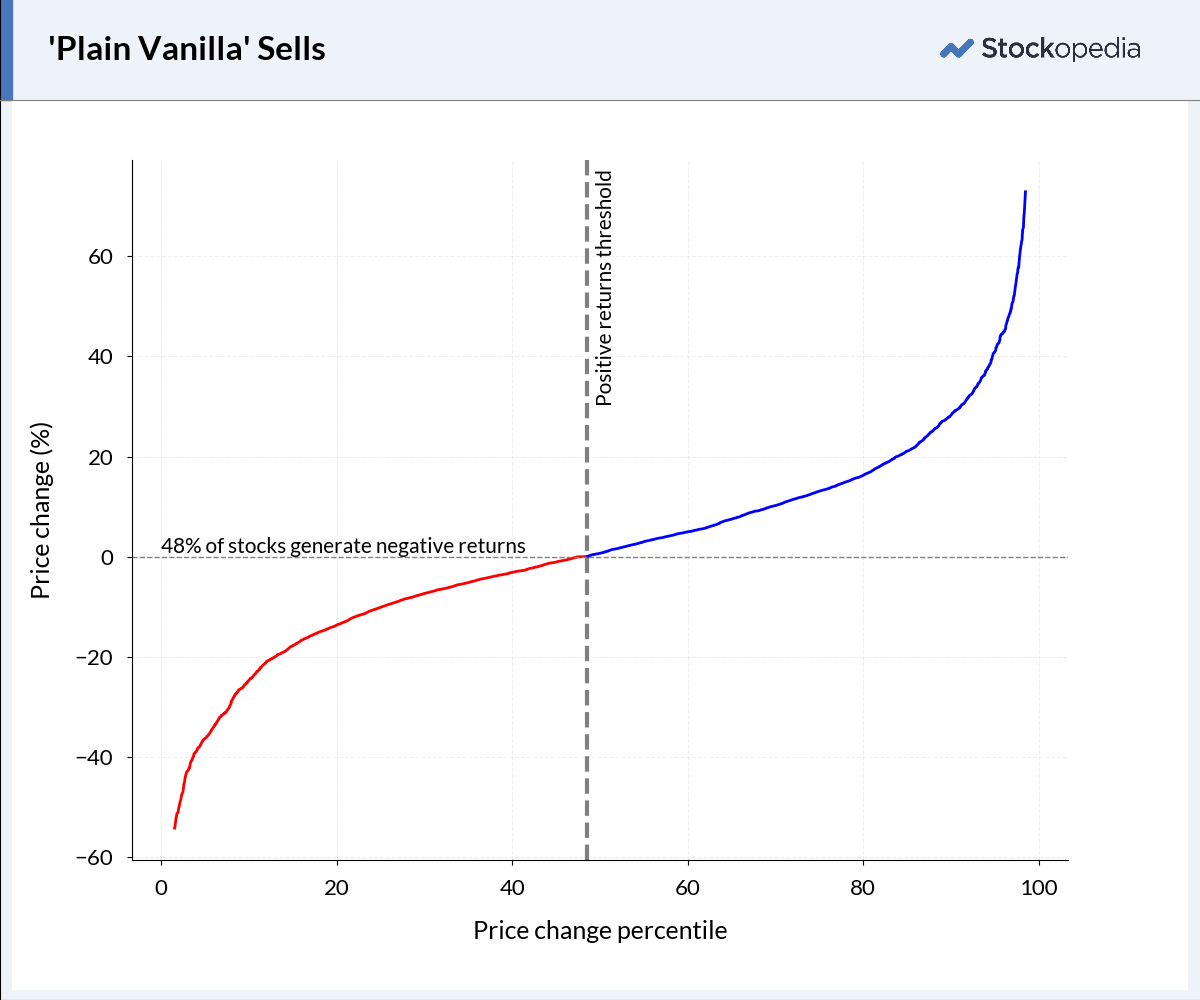
The base rates for director deals are as follows. There is some signal in ‘plain vanilla’ director buying and selling, but the odds are close to 50-50. I use the term ‘plain vanilla’, because I did not add any criteria around the StockRank, the director’s job title, or the extent to which the trade was a ‘material’ trade — i.e. represented a large proportion of market cap.
When a director purchased a stock, it had more than a 50% chance of being a winner, meaning its price was likely to rise over the next 100 days. Similarly, when a director sold a stock, the chance of it being a loser was around 50%. This is interesting, but you might be better off flipping a coin….
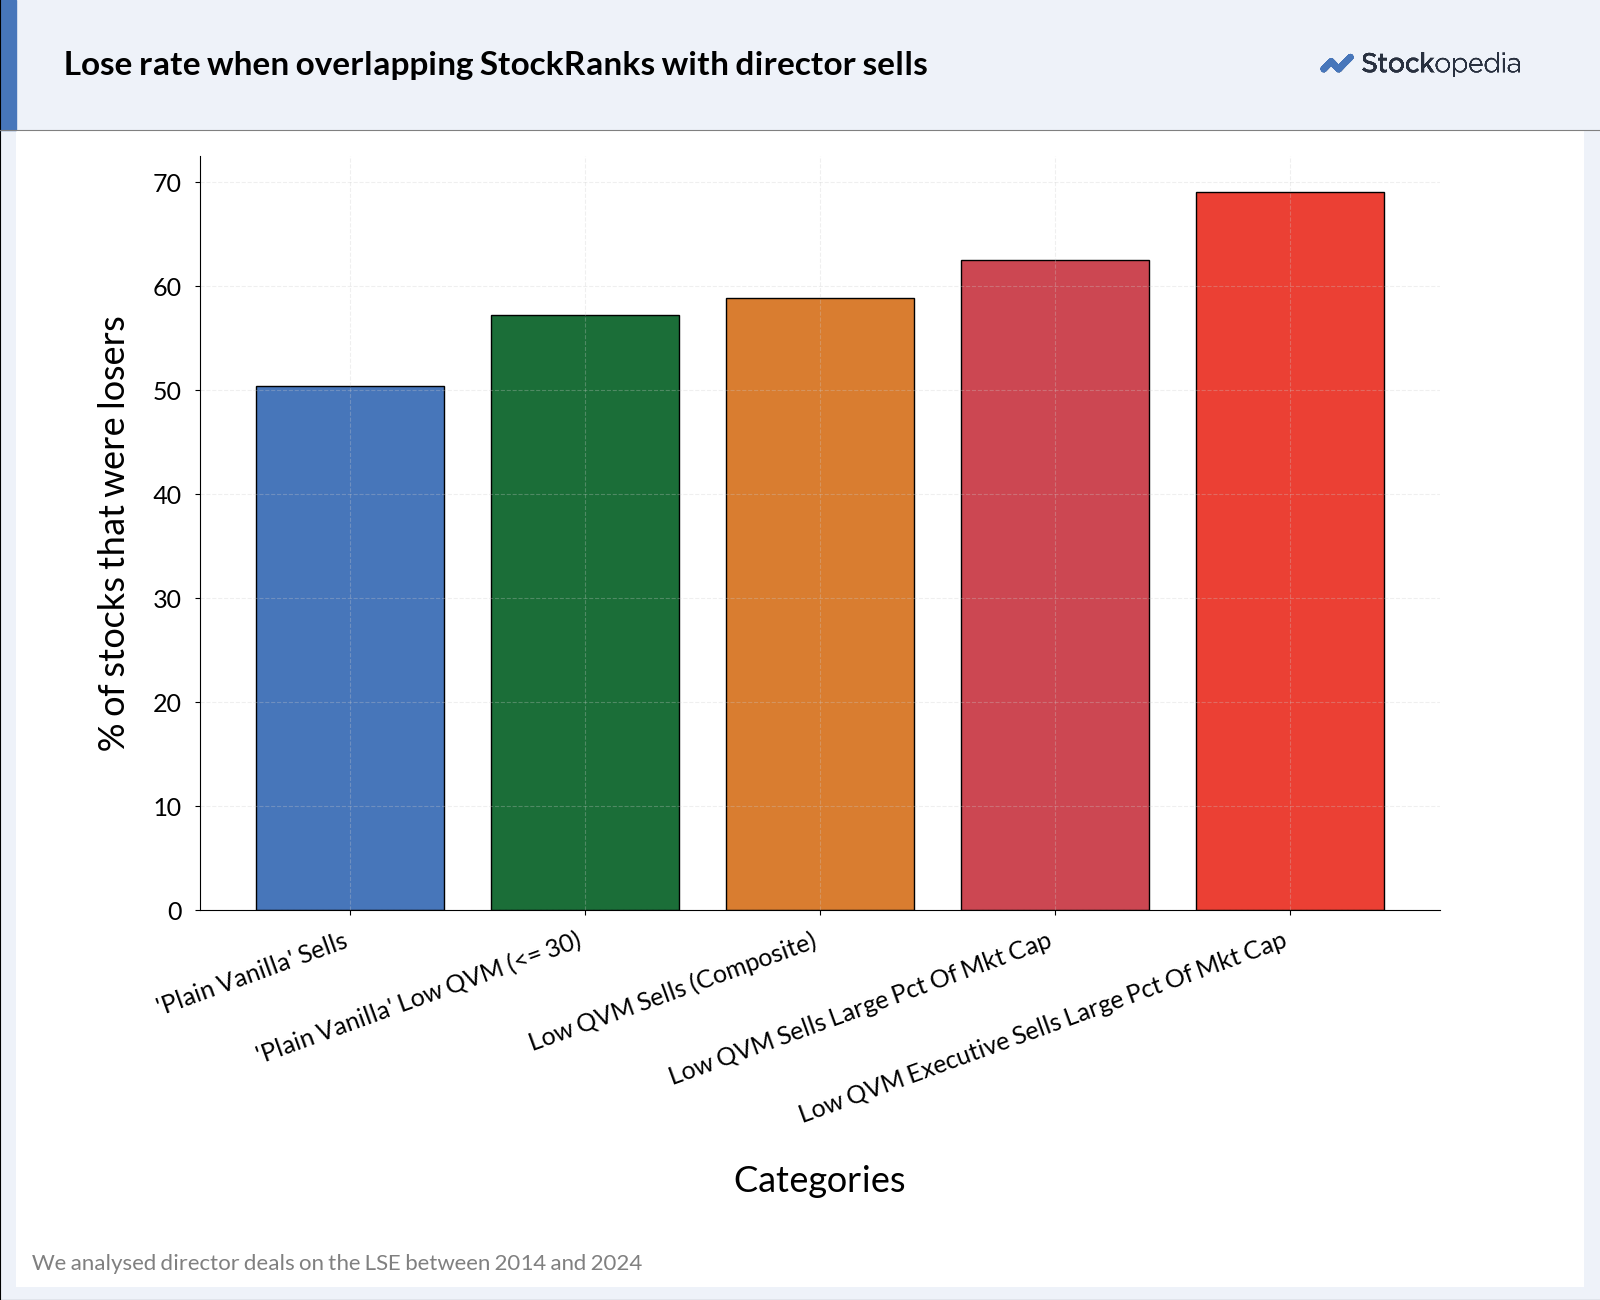
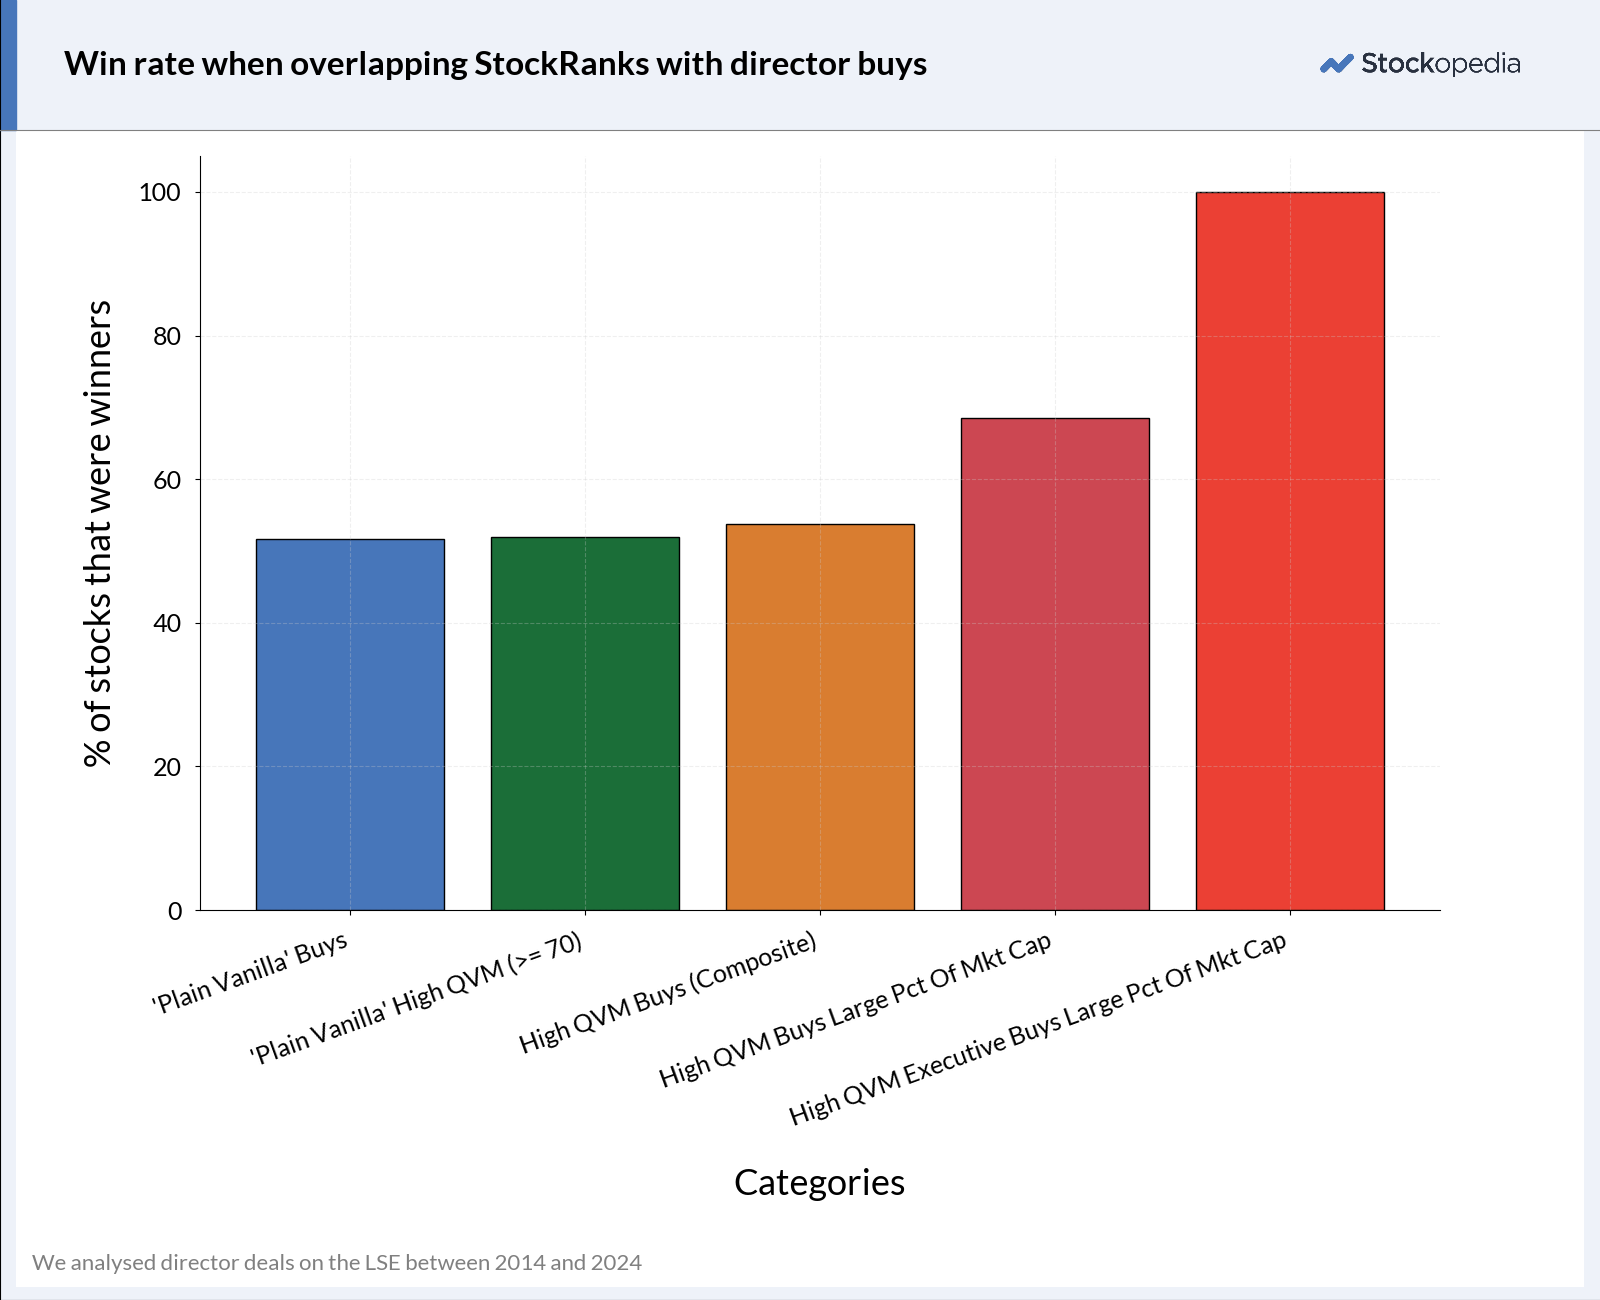
If you don’t want to flip a coin, you could improve the base rates by applying increasingly selective criteria and overlapping director trades with StockRank data.
- On the downside, a stock was more likely to generate negative returns if it had two traits: directors were selling and the stock was a low StockRank company.
- On the upside, companies were more likely to outperform if directors were buying and the stock was a high StockRank firm.
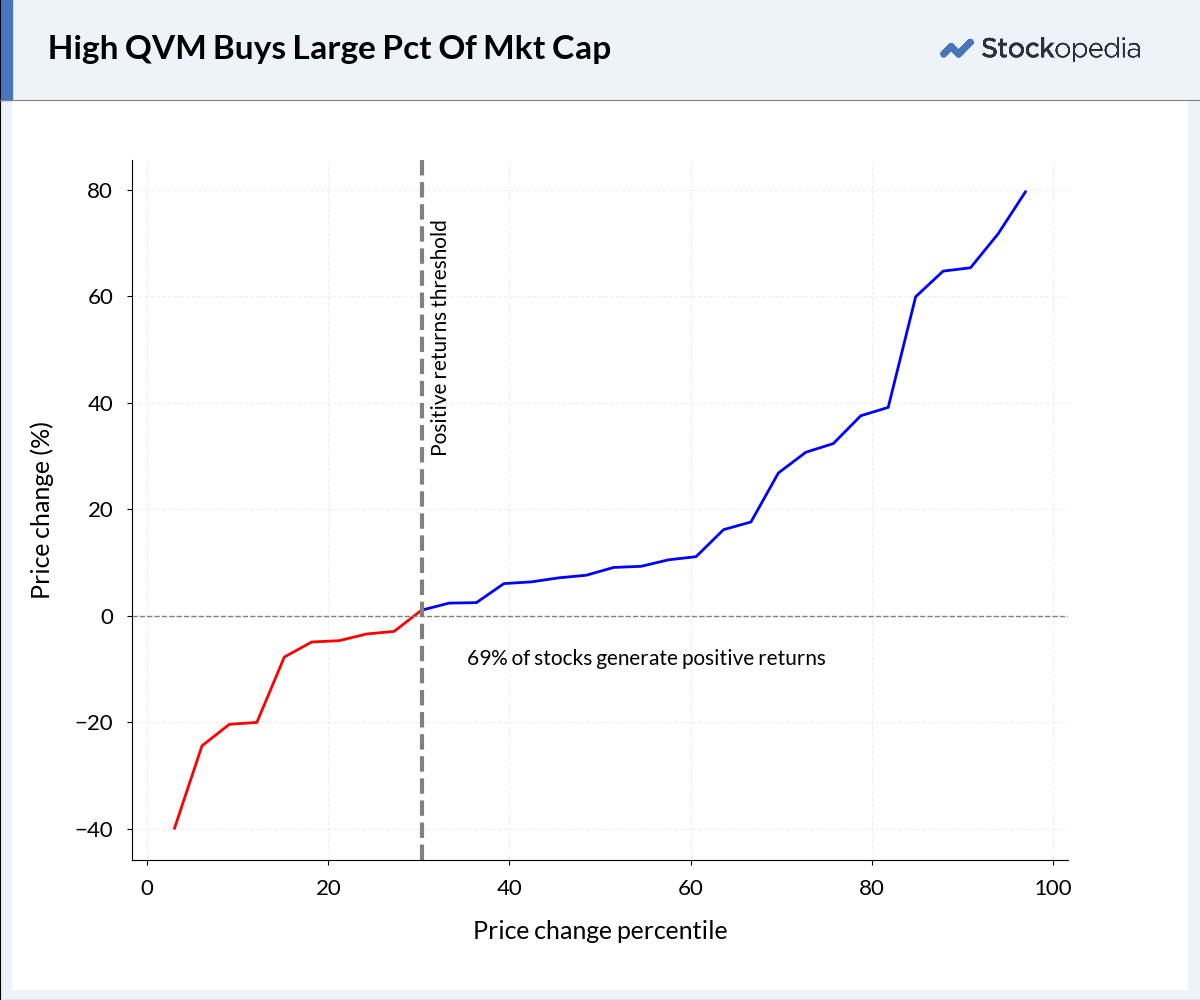
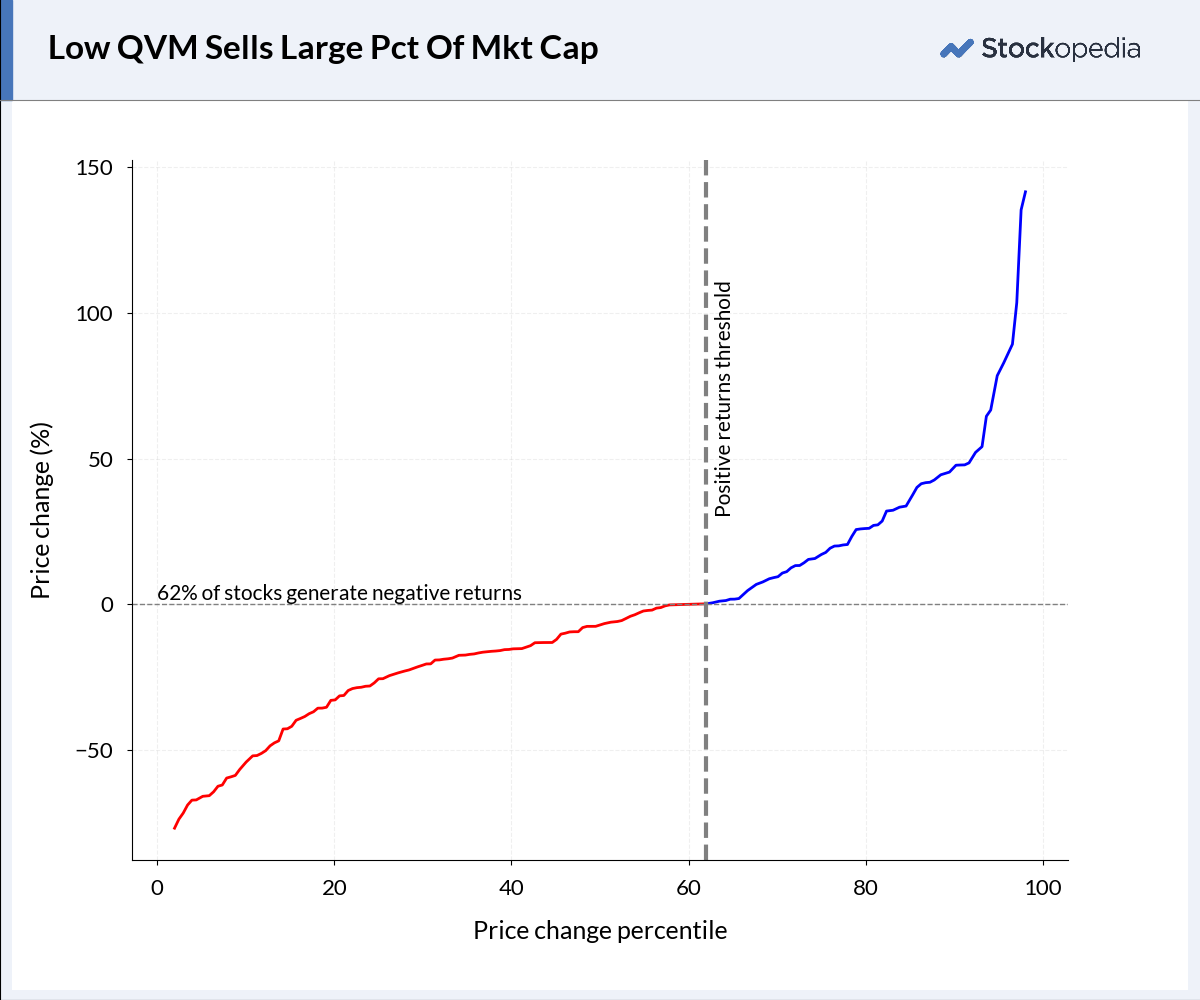
The base rates improved significantly when applying more filters, around who was trading and around the ‘materiality’ of trades. The odds of picking a winner were greatest if executive directors — CFOs or CEOs — were buying high QVM stocks in transactions representing a large proportion of market cap. The inverse was true on the sell side.
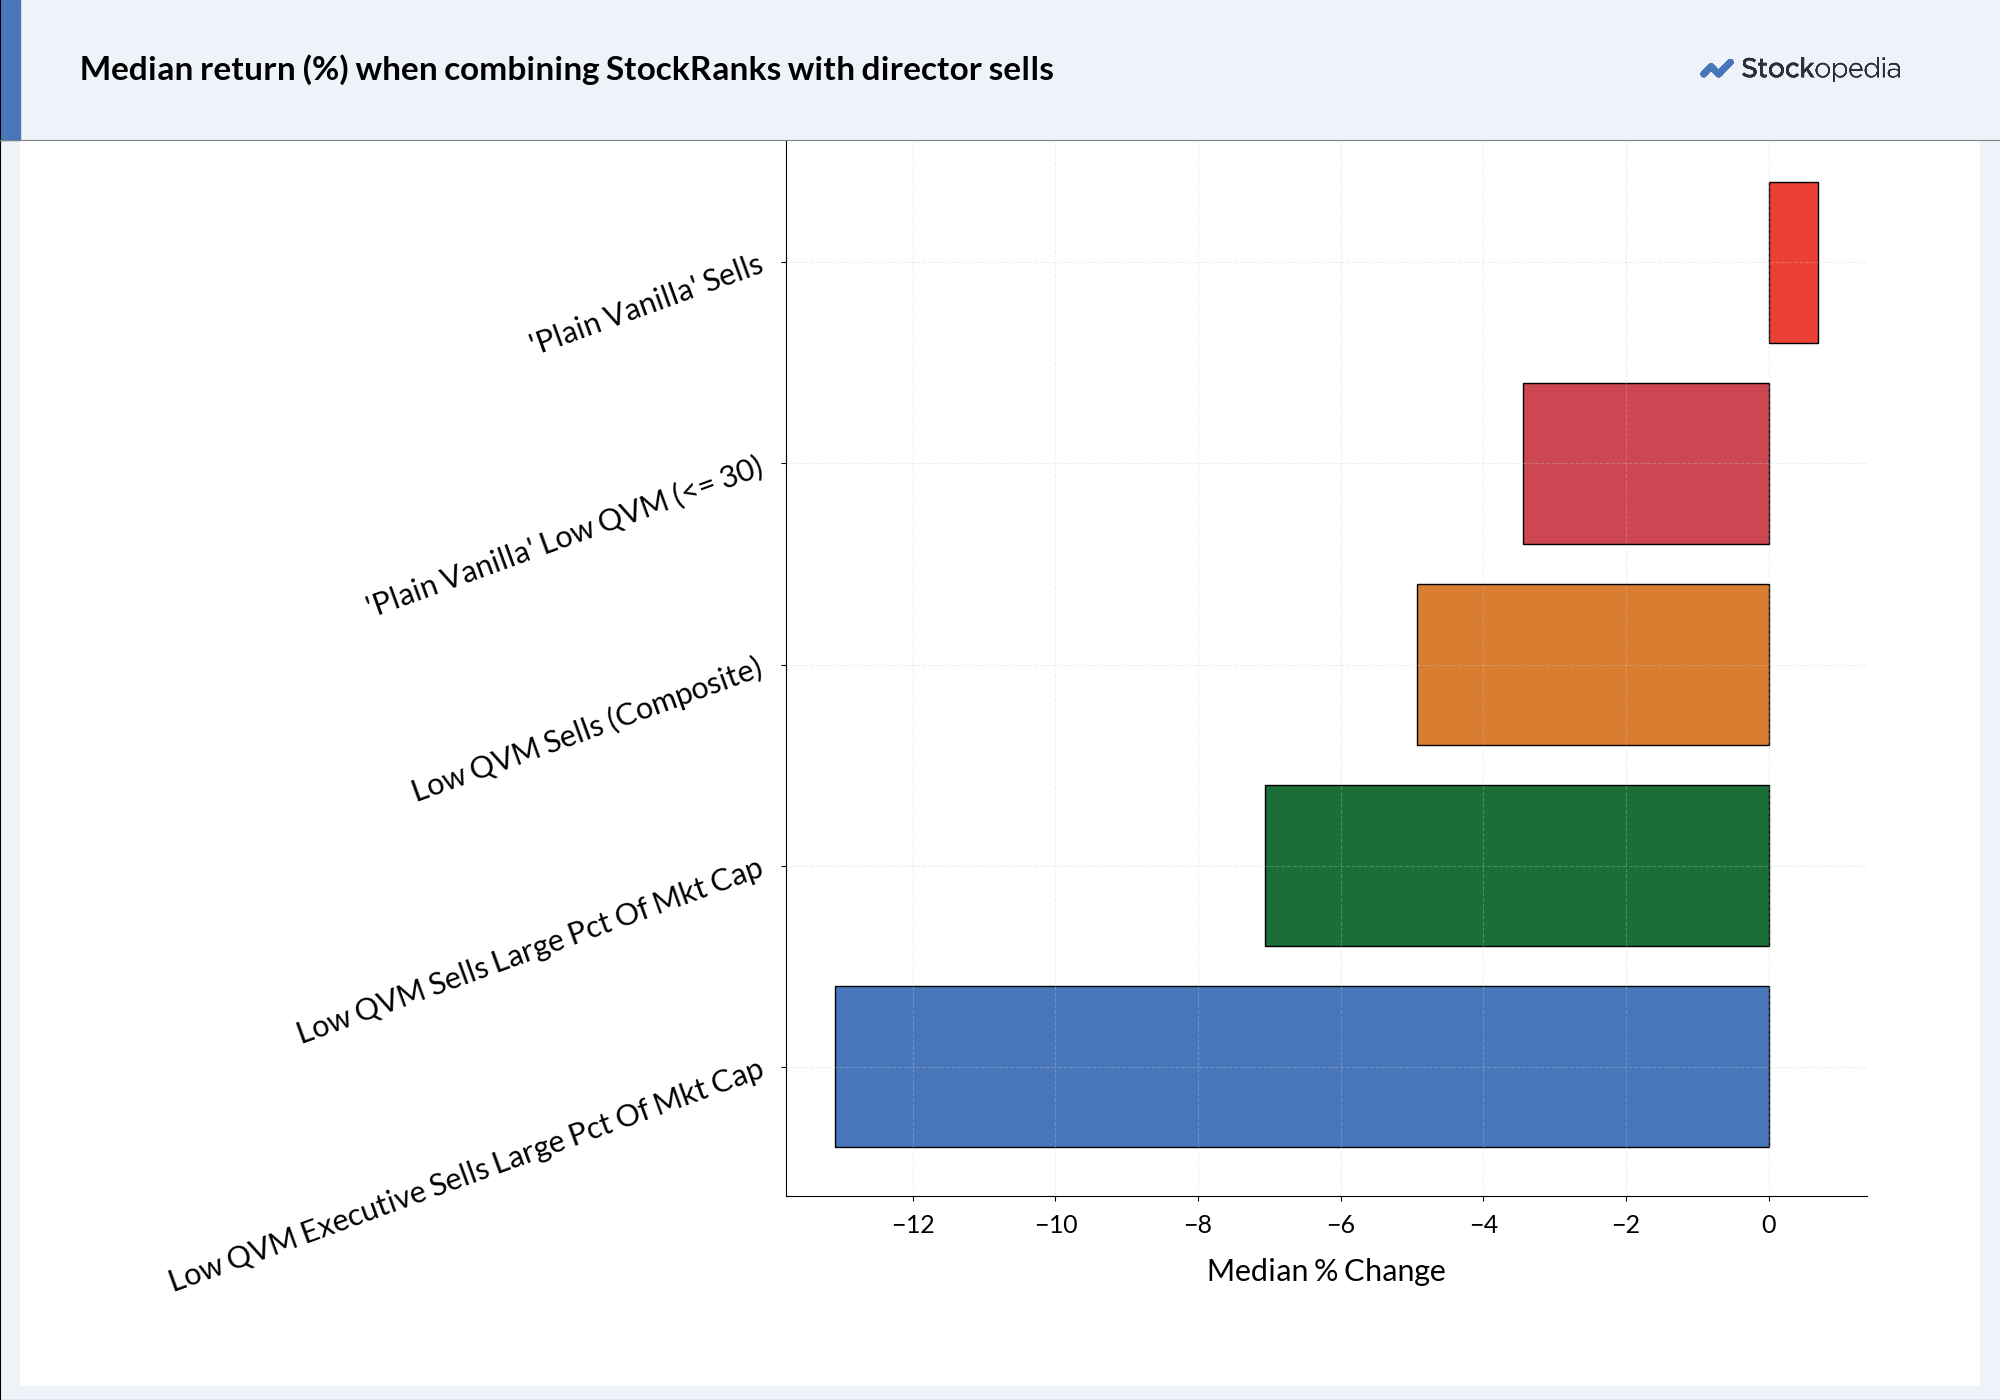
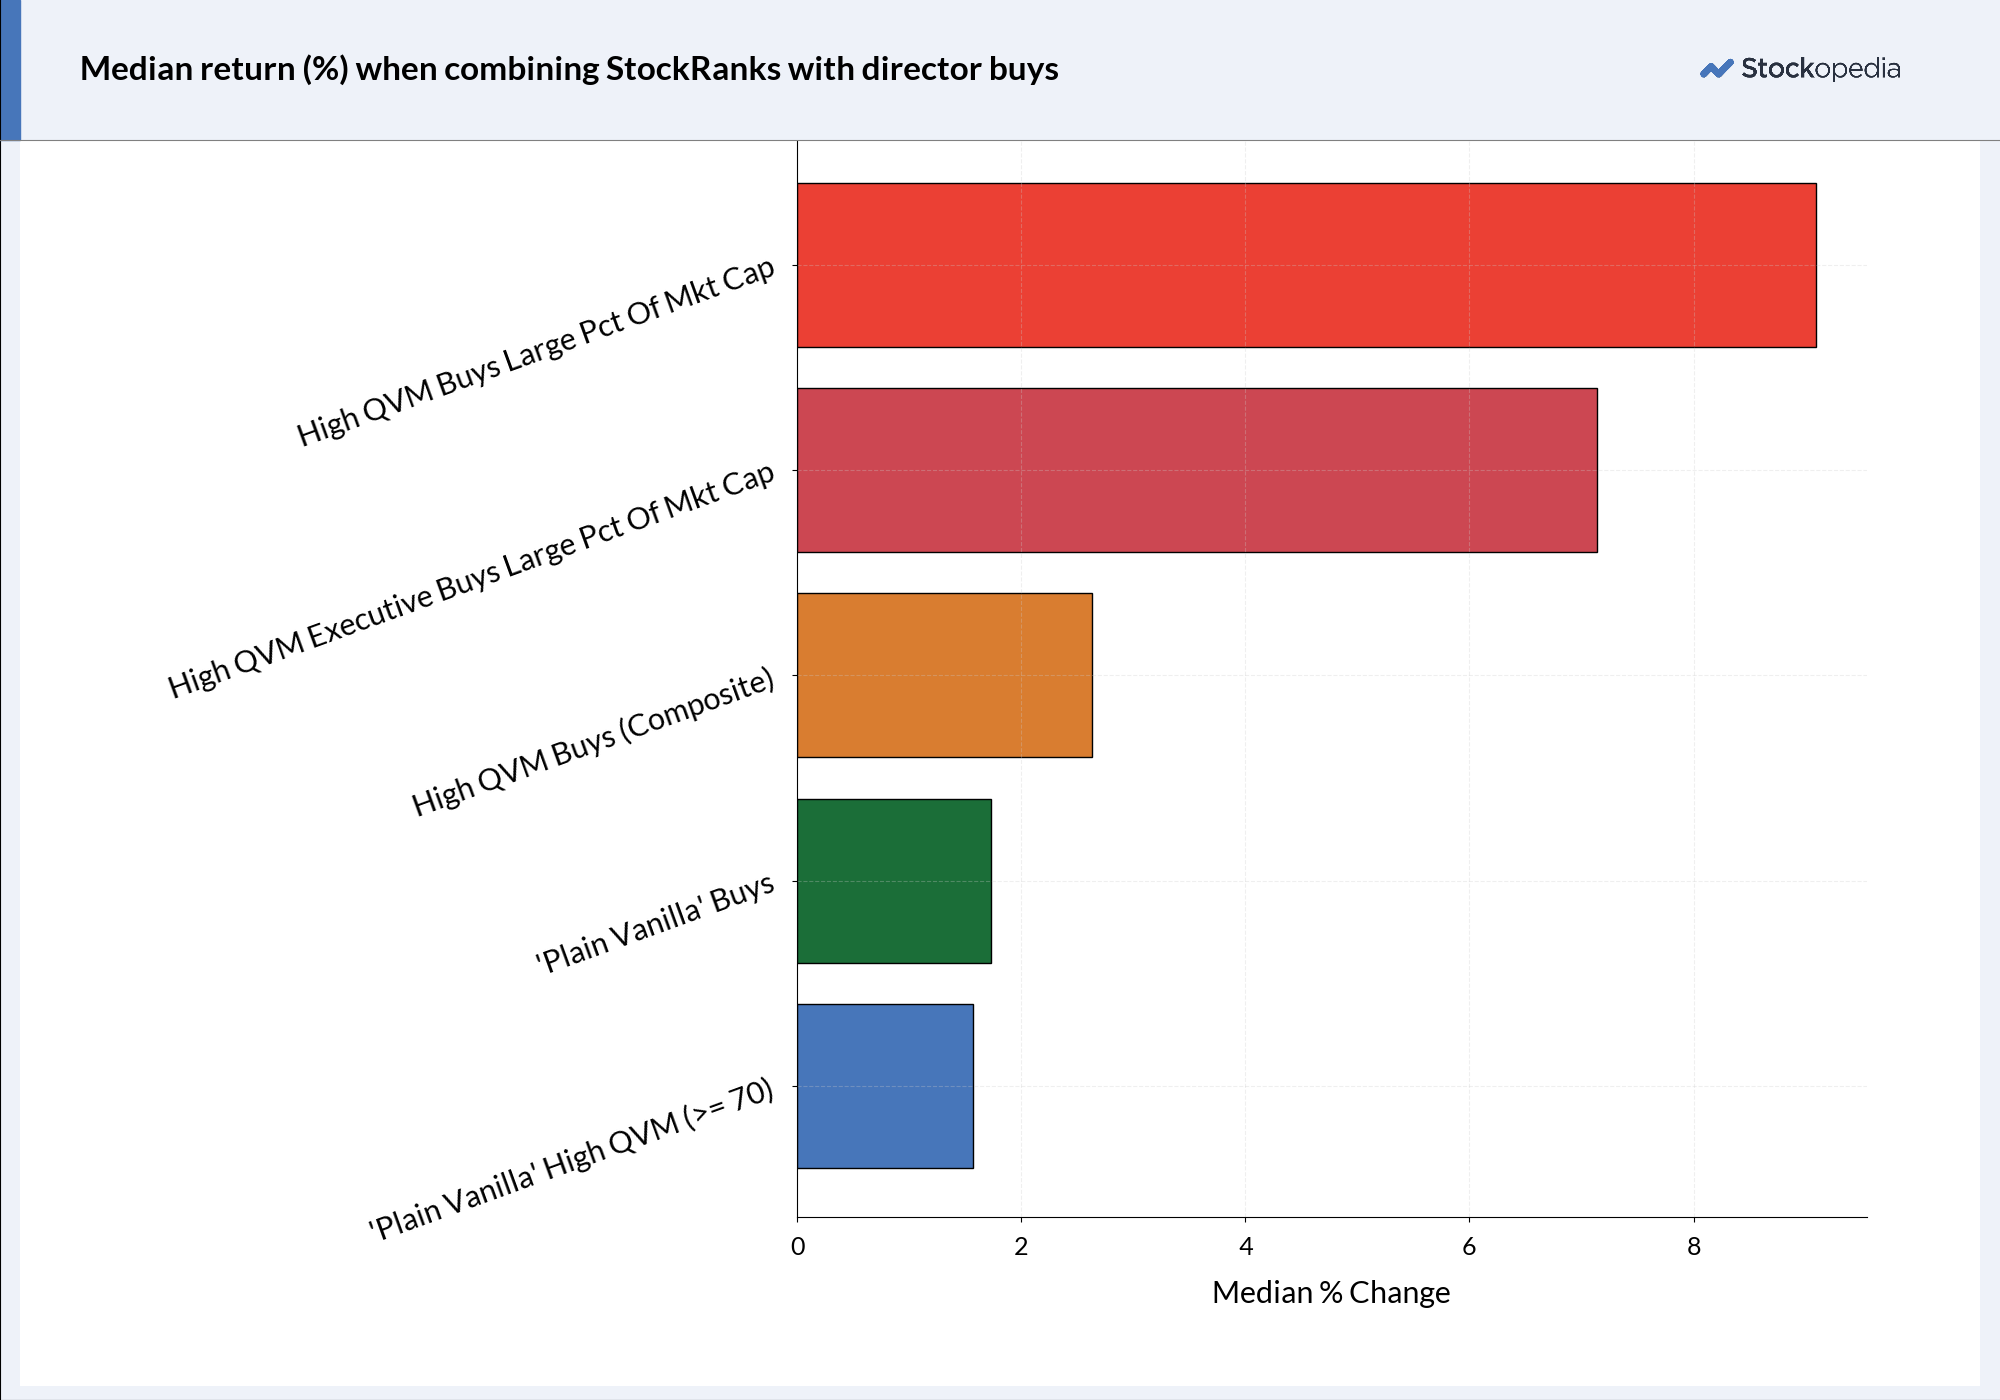
The general picture is that a composite approach works best, not just with director trading, but with investing in general. Last Christmas, I made the case for ‘overlapping value’ (see here). Companies are more likely to outperform if they are cheap across several valuation metrics. This is because different investors use different valuation metrics. A bargain opportunity becomes more apparent to a broader range of investors when multiple metrics align with the same bullish signal.
Our inspiration for the composite approach came from James O'Shaughnessy, who observed that different metrics perform better during different periods. Since investors can’t predict which metric will outperform next, it’s more effective to use a composite score that incorporates all relevant factors, ensuring exposure to every potential driver of returns.
Looking under the bonnet
Base rates are useful. They help us get the big picture right. For instance, they tell us that ‘plain vanilla’ director buys are likely to underperform director buys representing a large chunk of market cap. But base rates only tell us part of the picture. We risk falling into the trap of assuming that all stocks with a certain profile will behave identically. The reality is that you can still pick a losing stock if the base rates are on your side…
The base rates suggest it is better to avoid director sells, particularly material sells in low StockRank stocks. Nevertheless, some director sells do outperform…
The only free lunch is...
Investors may find themselves caught between a rock and a hard place. It is important to look at the detail behind aggregate statistics, because some stocks with the ‘profile’ of a winner actually do underperform. It is equally important not to get bogged down in noise — remember Funes the Memorious! This is where diversification plays an important role. By diversifying across a range of strong base rate stocks, we can switch off from excess information and let the let the laws of probability do their work.
The question is, how much diversification is enough? The maths is simple…
Consider high StockRank stocks that directors are buying in material size transactions…
There were 24 winners and 11 losers. If an investor picked one stock at random, they’d have a 31% chance of picking a loser - i.e.
11 / 35 = 31%
If they randomly picked 2 stocks , the odds of them both being losers drops below 10% - i.e.
(11 / 35) x (10 / 34) = 9.2%
Once you get to 4 stocks, the odds of all stocks being losers drops below 1% - i.e.
(11 / 35) x (10 / 34) x (9 / 33) x (8 / 32) = 0.6%
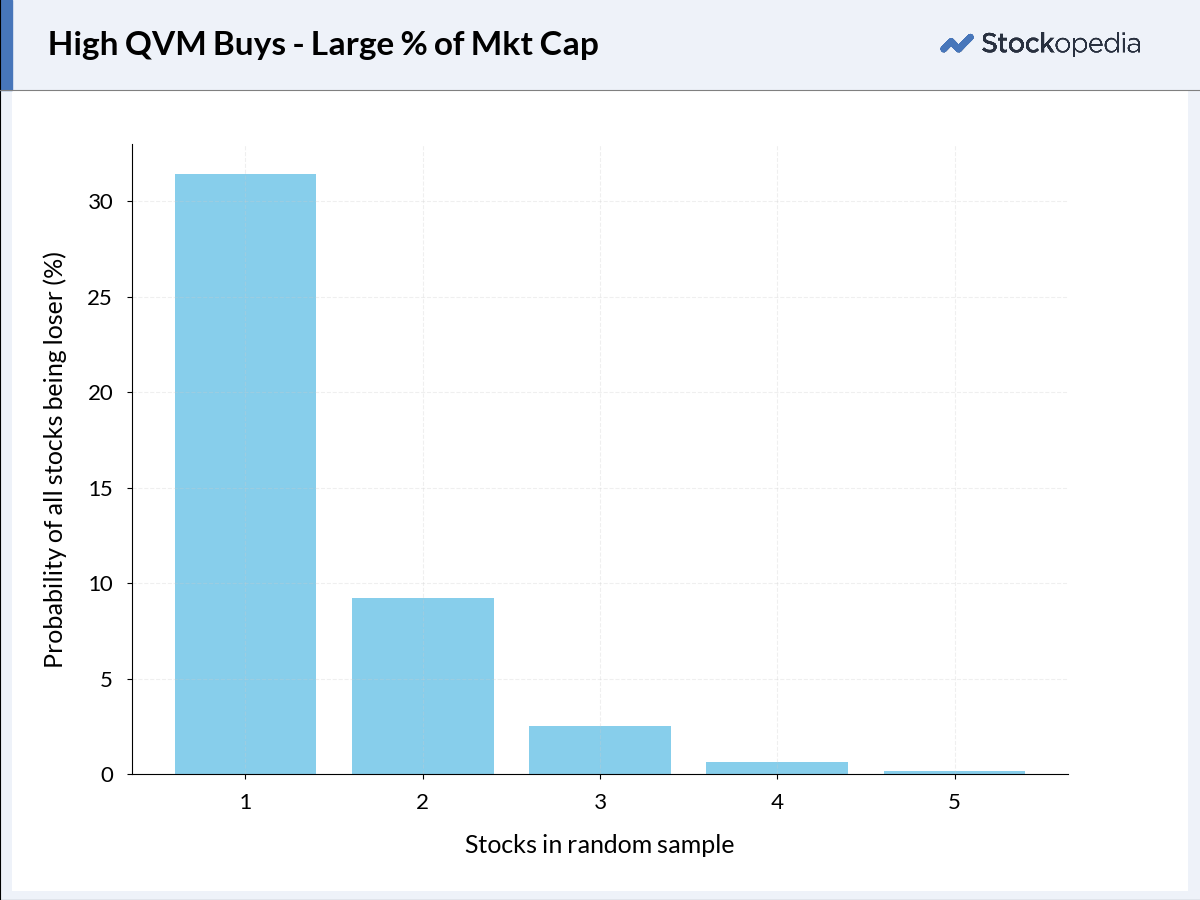
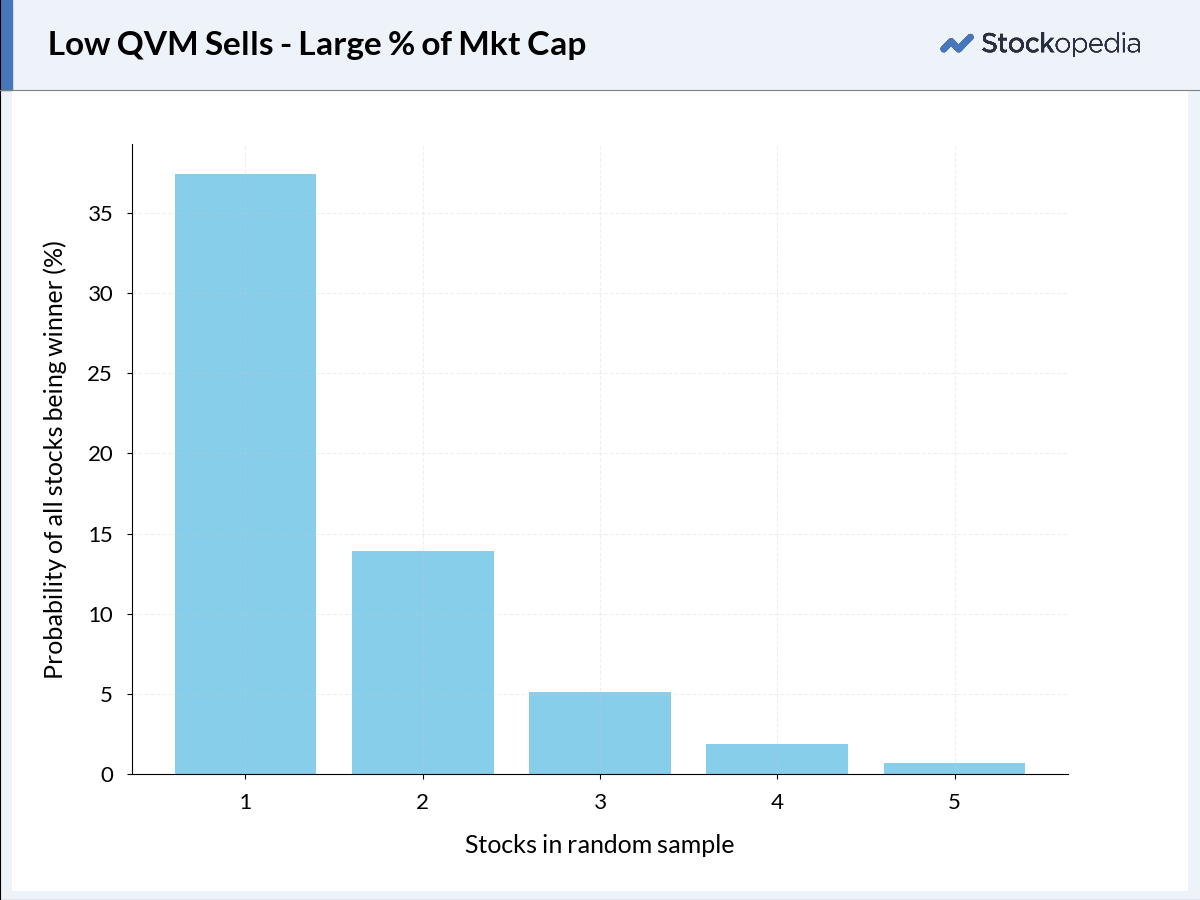
I appreciate that 35 stocks is a small sample, but a similar trend persists if we look at the sell side, where there were 211 material sells in low StockRank stocks.
Key takeaways
Director trading can provide useful investment signals, but a deeper analysis is needed to separate noise from meaningful trends. While director buys are generally bullish and sells bearish, base rates show that applying additional filters—such as StockRank, trade materiality, and the director’s role—improves accuracy. A composite approach, combining multiple valuation metrics, enhances decision-making.
Diversification is key to managing risk, as spreading investments across high-base-rate stocks reduces the likelihood of losses. Investors must balance detail and abstraction, avoiding the trap of information overload while leveraging probabilities to improve outcomes.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

6 comments
B.P.Marsh, BPM, is a stock I owned. I noted on 12 December that there was a large number of directors who all sold heavily. But the share price had not dropped. So I held. But over the next six weeks it dropped significantly and had lost momentum. So I sold at a loss and bought SUP which is already in profit.
Lesson learned.
B.P. Marsh & Partners (LON:BPM) There was a lot more director selling in January. What with that and the forecasts, put me off me buying, even after the fall.
To my shame I believe I wanted to buy M P Evans (LON:MPE), because when I went to sell I couldn't believe I bought a share with that chart. And the stock rank was equally good. Both were on my 'to buy' list.
Does anyone know what’s the best way to get an alert/trigger when a director purchase is announced? I usually find out after the share price has already moved
Hey,
Good question.
In some cases, the price continues to drift upwards after the initial spice (see here, the section title 'Don't worry about missing the bus').
We can overtime extend the product so you get alerts on director trades. Watch this space!
Excellent article.