MTI Wireless Edge - In line results, but a high rating for a historically low-growth plodder
Analyst’s view:
It is certainly possible that current Middle East conflicts will eventually lead to an acceleration of sales and profits at MTI Wireless that is beyond the current two-year forecast window.
However, the company has been telling us this story of tailwinds accelerating growth for at least the last decade that I have been following the company. Outside the Antennas division, I see absolutely no evidence of this supposed strength showing up in the medium-term financial numbers.
The company deserves some credit for its stability, having navigated the tricky COVID period with little noticeable downturn in trading. As a family-controlled business, it seems run in a way that minimises the chance of big losses rather than maximising upside potential. This approach may appeal to some investors. However, my main issue is the current market rating. At 14x forward P/E with mid-single-digit medium-term EPS forecasts, the company looks overvalued for a business with a history of plodding along, despite around 12% of market cap being in net cash.
The bright spot is the Antennas division, and it could be argued that growth here helps make the company look more fairly valued on a sum-of-parts basis. However, the margin improvement appears to have stabilised, and the company now relies on winning and delivering future orders to sustain that growth.
The algorithms still like the company because of its favourable rating compared to other companies in the technology sector and its strong RoE. However, with little sign that the company can capitalise on that RoE to generate high future growth, and with a Momentum Rank flashing warning signs, I think we should take a more cautious view.
Up 1% at 62p - Q3 2026 Financial Results and Trading Update
MTI Wireless Edge is delivering what shareholders like to see - revenue growing, profits growing ahead of revenue and those turning into cash:
- Revenue up 9% to $41.2m (9 months 2025: $37.8m)
- Profit before tax up 10% to $4.3m (9 months 2025: $3.9m)
- Earnings per share (basic) up 7% to 4.60 US cents (9 months 2025: 4.31 US cents)
- Strong cash conversion lifted net cash to $8.95m at 30 September 2026 (30 September 2025: $6.40m)
The real bright spot in this quarter is Mottech, their water managemnet division, which supplies software and systems that provide irrigation and municipal water control using third-party controllers:
Revenue increased by 22% and operating profit increased by 60% compared with the same period in 2025.
Antennae sales were down 11% in the 9-month period versus last year, although they flag that recently won defence contracts are now converting into revenue. MTI Summit saw revenue grow 12% and they again flag defence-related orders as the core driver.
Outlook:
It should perhaps not be surprising that a company mainly supplying the Israeli military in its defence segment should be doing well in a period where Israel is conducting at least three wars of varying intensity.
The CEO is keen to point out that the strength here is not entirely driven by defence sales:
While increased demand for defence-related products is a clear tailwind, it is particularly pleasing that our water management and 5G-related activities continue to contribute strongly. This breadth of communications and radio frequency expertise across multiple sectors is what makes the Group resilient over the long term.
Forecasts:
While the company says it is "in good shape", it doesn't say it is trading in line with expectations. However, their broker Allenby says:
Unchanged FY26 forecasts assume a flat Q4 revenue performance but some margin improvement. This appears very achievable given the healthy backlog and outlook.
In line is 5.9m PBT, up 8% on FY25, although EPS is forecast to decline slightly to US5.83c this year, before rising 7.4% to US6.26c next year.
Longer-term perspective:
The company has a compelling story of being positioned for growth, driven by the tailwinds of increased defence spending, water shortages, and 5G roll-out. The problem is that they have been telling this same story of tailwinds for the decade or so that I have been following the company. The long-term track record of growth is lacklustre:
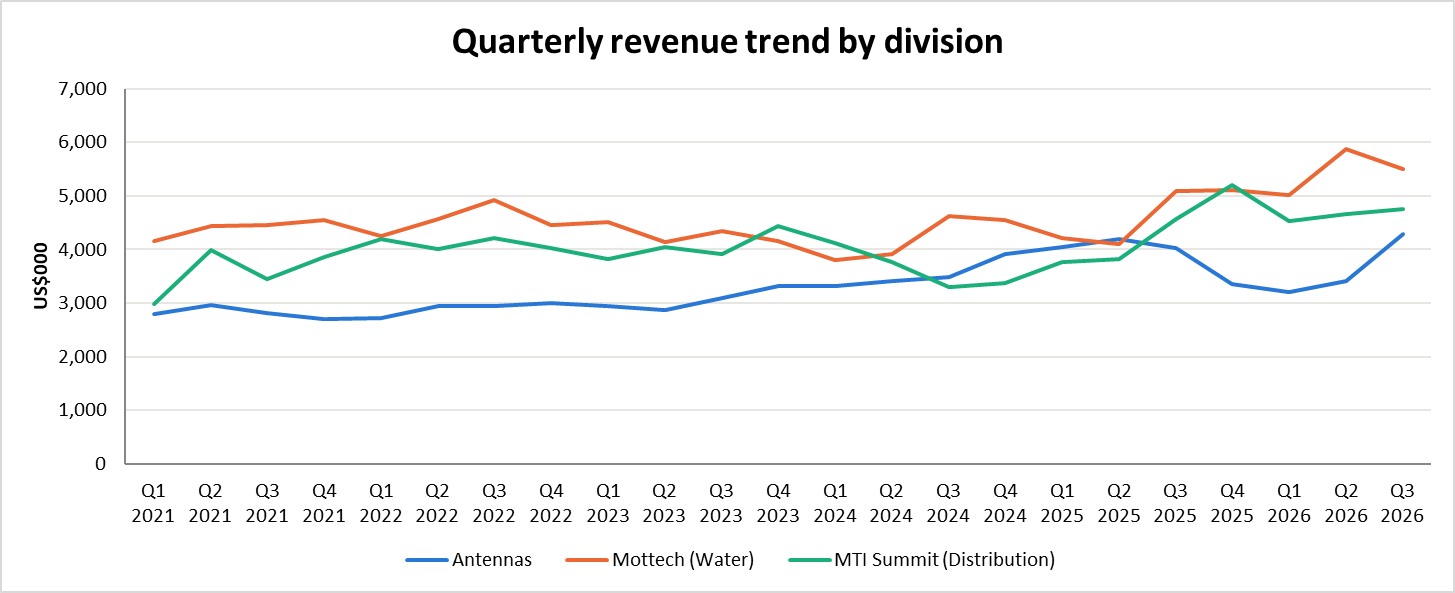
Group revenue has grown at a CAGR of just 3.9% based on the line-of-best-fit to this data over the last 5 years. Mottech and MTI Summit came in at just 2.1% and 2.7% CAGR, respectively. However, Antennas was more impressive, with 7.7% CAGR revenue growth over this period.
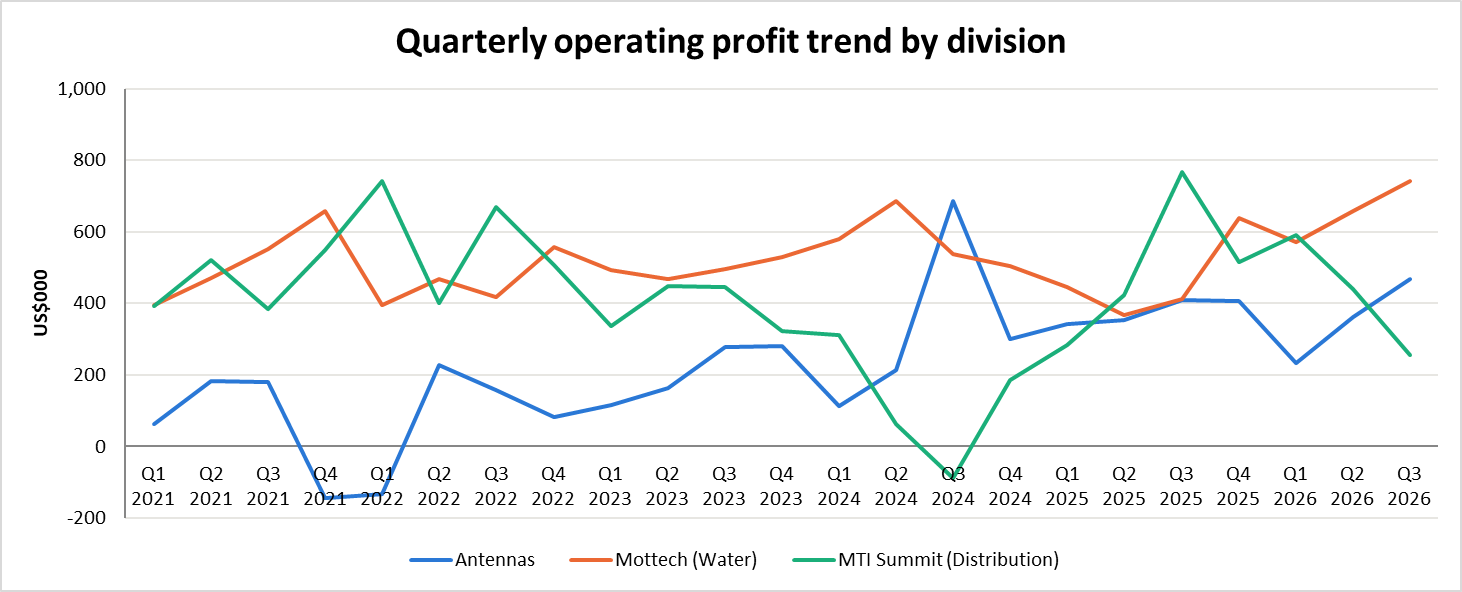
Quarterly profits are understandably noisy. However, I see little sign that MTI Summit and Mottech aren't cyclical businesses bumbling along, with Mottech happening to have a cyclical up-quarter and Summit a down one:
Antennas has again been the bright spot over the medium-term, with margin enhancement combined with the higher revenue growth leading to more rapid operating profit growth:
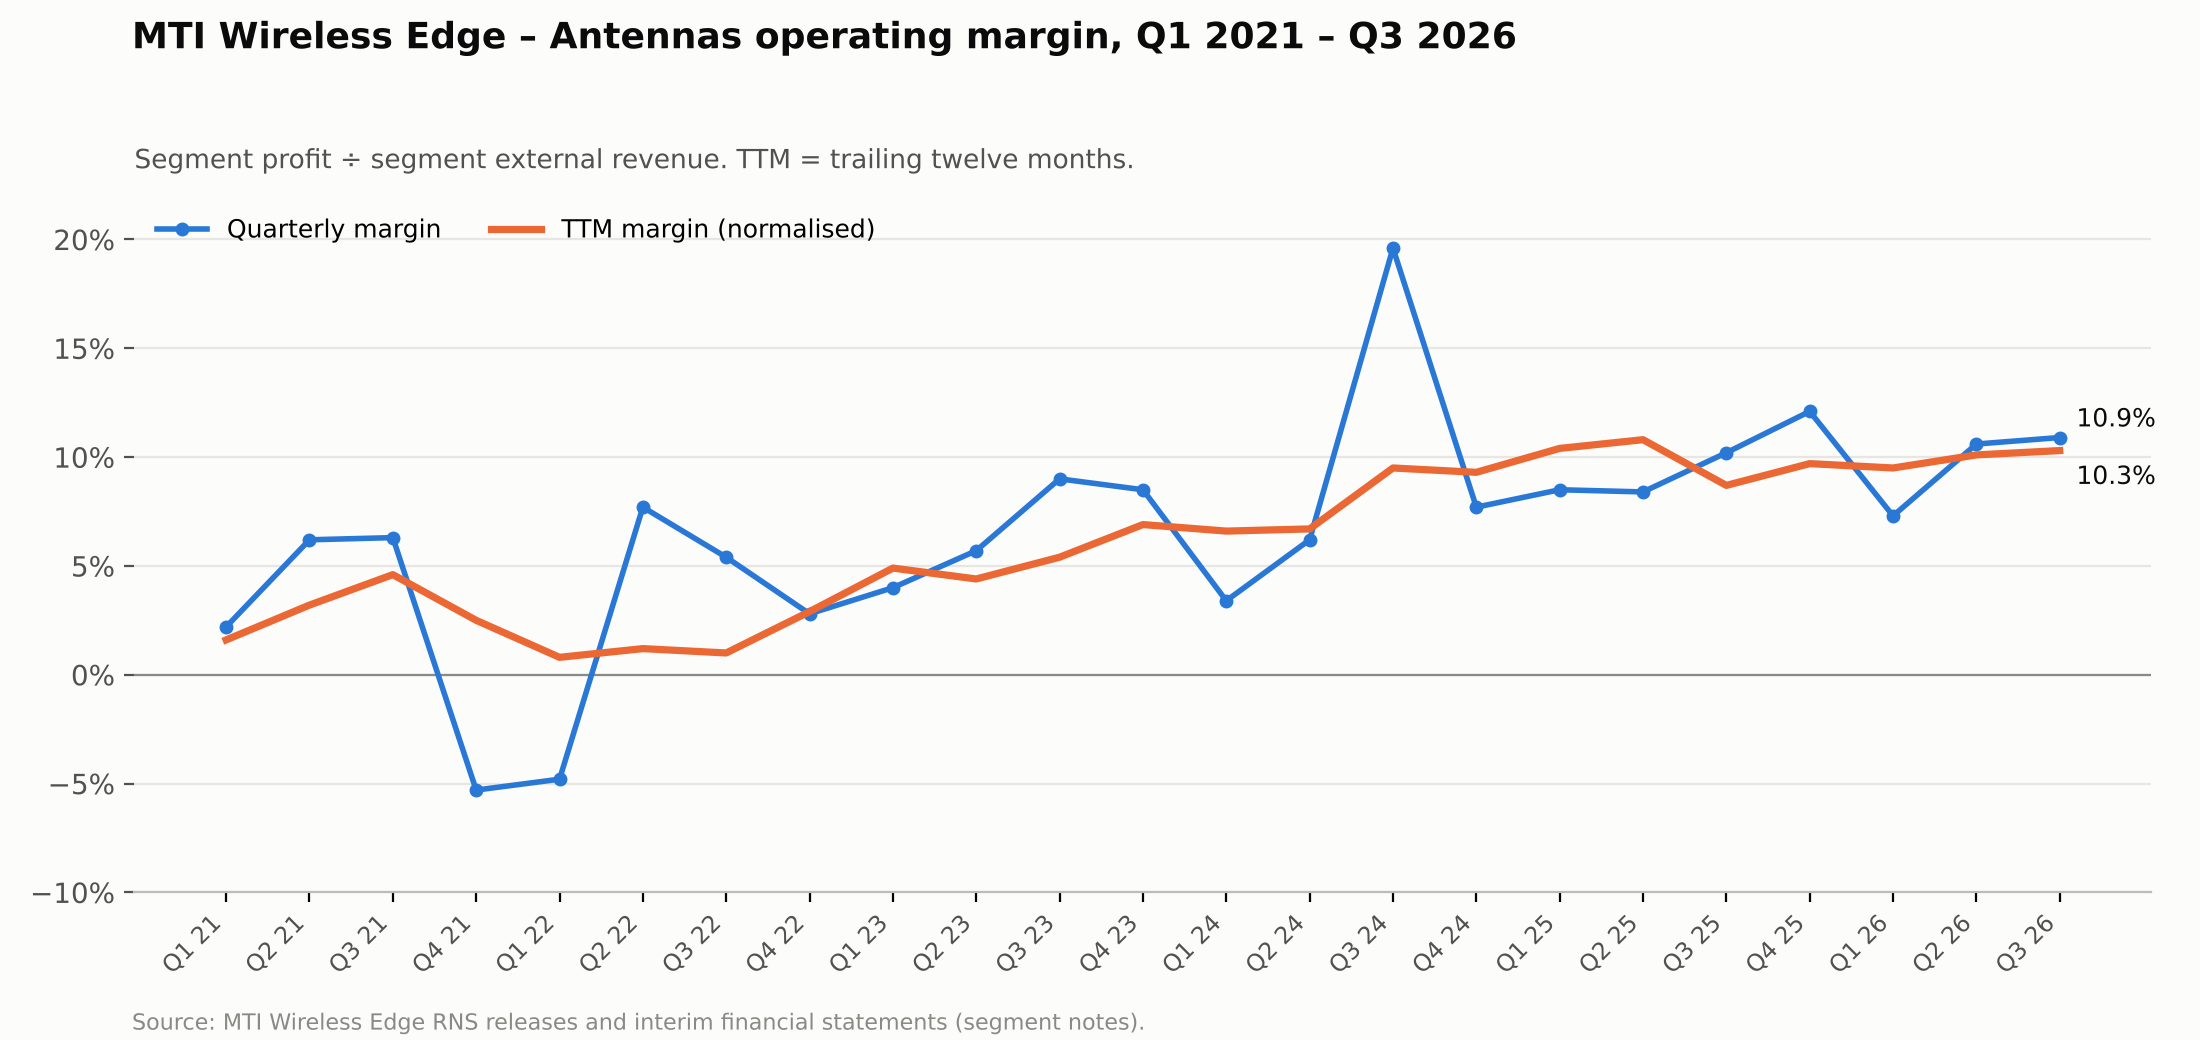
The company attributed this to a shift toward higher-margin military antennas and its ABS 5G backhaul product, and away from legacy commercial antennas. The new mix has held up so far. In 2026, Antennas revenue fell year on year because of slower Indian 5G orders. Even so, the margin stayed around 10%, and Q3 2026 came in at 10.9% as April’s defence contracts began delivering. However, the rapid expansion of margins over the last few years appears to have largely stalled, so future growth is dependent on revenue growth holding up.
Valuation:
While the company may not compare particularly favourably to other UK small caps on its multiple, it does look cheap compared to other defence and technology companies:
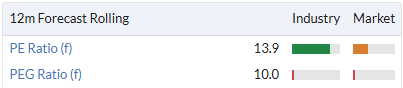
The problem is that this multiple still looks excessive for a company with a history of low growth and medium-term forecasts showing mid-single-digit EPS growth, as the very high PEG ratio implies.
A sum-of-parts valuation may show better value, with the faster-growing Antennas Division allowed to shine. A quick sense check with Claude suggests that Antennas could be valued higher, around 12x EV/EBIT compared to 8-10x max for the low-growth divisions. However, this is still the smallest division in terms of operating profit, meaning that the valuation impact isn't huge.
The net result is that even on these more aggressive valuation methodologies, Claude suggests that:
The sum of the parts comes to about 60p a share using growth-implied multiples, and about 65p using peer multiples. Against Friday’s close of 61.5p, that suggests the market is pricing MTI roughly fairly.
Stock Ranks:
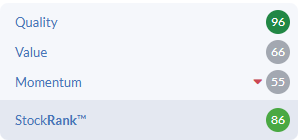
The Value Rank reflects that balance between being in an industry with tailwinds behind it and an overall lack of growth:
Reasonable and rising RoE figures, combined with financial conservatism, mean that the Quality Rank is particularly strong:
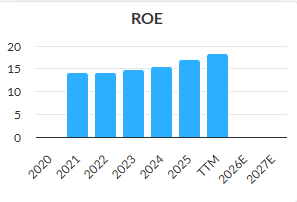
However, high RoE is meaningless unless a business can deploy fresh capital at similar rates to generate EPS growth, something the company appears to be struggling with.
That declining Momentum Rank should also give pause for thought. With overall trends reversing and the company not yet trading at a level where valuation may provide support, there are signs we should be cautious here, despite the high overall Stock Rank.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
Discussion on MTI Wireless Edge (0)
Comments here are also visible in the Daily Stock Market Report
No one has commented here yet! Why not be the first one?