MTS: A high quality defensive stock

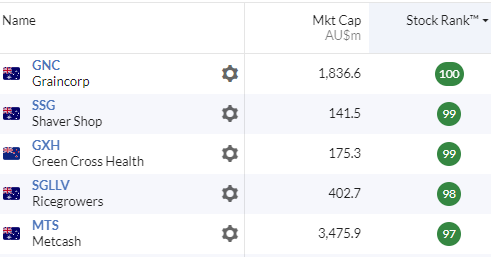
Metcash (ASX:MTS) is currently the fifth highest ranked consumer defensive stock. It is a food, liquor and hardware business. They are primarily a wholesaler, distributing products to independently owned retail stores across the country. These include supermarkets under the IGA brand, a range of liquor stores such as Cellarbrations and hardware stores like Home Hardware and Mitre 10. They have over 5,400 stores in their network.
In the current economic environment, high inflation and interest rates are leading to uncertainty regarding the outlook for consumer demand and economic growth. This has seen the Consumer Cyclicals sector decline, with the S&P/ASX 300 Consumer Discretionary index falling 3.3% since 15 May. The S&P/ASX 300 Consumer Staples index has declined a bit less, falling 2.5% over the same period. Metcash is part of the Consumer Staples sector as it provides goods that are more essential than discretionary.
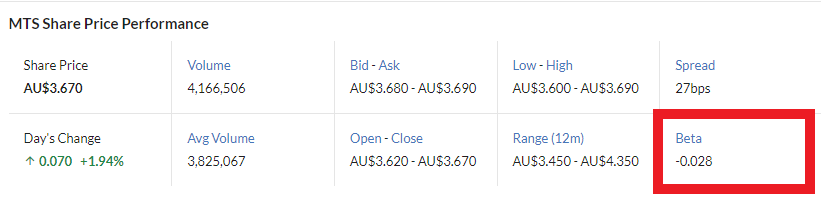
Consumer defensives (or staples) are generally considered to be less volatile and more resilient during tough economic times. Beta is used as a measure of volatility. A beta of less than one means that a stock is less volatile than the market. Metcash has a beta very close to zero which means that it shows almost no correlation to the market as a whole. This defensive quality can be helpful when constructing a portfolio during times of uncertainty.
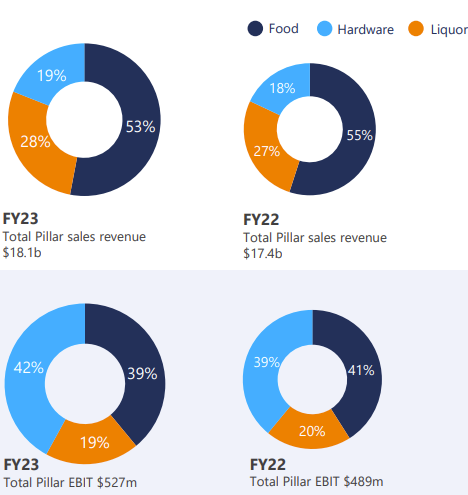
Wholesaling of consumer goods is a low margin business. EBIT margins for FY23 were:
Food 2.1%
Liquor 2.1%
Hardware 6.5%
Food is the largest segment in terms of revenue, and hardware is the smallest. However hardware rises to the top when considering the contribution to EBIT due to the higher margins.
Source: Metcash, FY23 Full Year Results Presentation, 26/6/23
Their financial year ends 30 April, so their annual results were just released towards the end of June. The results were generally strong. Sales grew by 4.2%. Underlying EBIT increased by 8.1%, operating profit by 5.5% and reported net profit by 5.5% also. The company achieved record sales, EBIT and NPAT on the back of all divisions performing well.
Management also flagged that in the first seven weeks of FY24 they have witnessed strong sales growth and believe they are well positioned for continued growth on account of a larger platform, which is more diversified and stronger.
They are continuing to invest in the business with significant amounts of capital expenditure as well as some acquisitions. A lot of this investment is around using technology to make their distribution system more efficient thereby improving their competitive position. They are also investing in their digital strategy both for B2C and B2B. Woolworths currently has the strongest online shopping presence and this gives them an advantage with less affluent shoppers who tend to use online as a budgeting tool.

Source: Metcash, FY23 Full Year Results Presentation, 26/6/23
The strong StockRank is supported by a Quality score of 84. The Piotroski score is a very healthy 7/9 and the Return on Capital of 15.3% and Return on Equity of 24% are very strong. Long term return on capital is 9.9%.
The long-term outlook for supermarkets as well as hardware is positive, supported by population growth. In the short-term, Metcash will benefit relative to some stocks in that the goods it supplies are of an essential nature, rather than more discretionary products. However in terms of supermarkets, it tends to charge higher prices and therefore with consumers currently becoming more value conscious they may feel some competitive pressure, particularly from Aldi. Management noted that they are seeing some movement towards shopping for value.
One of their objectives is to reduce the gap between their prices and competitors' prices. The graph below shows that this has generally been trending in the right direction when compared to Coles (ASX:COL) and Woolworths (ASX:WOW).

Source: Metcash, FY23 Full Year Results Presentation, 26/6/23
When comparing the Quality of Coles, Woolworths and Metcash, we can see that Coles is the leader with a score of 96, followed by Metcash with 84 and then Woolworths with 73. Woolworths is dragged down by the lowest Return on capital and the highest leverage. Coles has the best margins and Return on equity.
However when comparing the three from the perspective of a value investment, Metcash is the clear winner. It trades on much lower valuation multiples than its rivals. Its forecast PE ratio is 12 compared to 26 for Woolworths. Metcash, Coles and Woolworths have Value Scores of 82, 58 and 39 respectively. Metcash also pays significantly higher dividends with a current dividend yield of 6.1% fully franked.
Metcash’s share price has trended down over the last six months, in line with the general negative sentiment towards retailers, however the fundamentals of the business have not deteriorated. Indeed the business is continuing to generate solid returns as reflected in the Quality score. This decline in price has led to an improvement in the Value metrics. Should there be a significant economic crunch, Metcash are not immune, but they are in a much better defensive position than many stocks. When compared to its closest competitors, the fact that its Value score is so much better, provides for a margin of safety.
Important Information: Stockopedia Ltd ABN 39 757 874 670 UK business registration number 0637267 (“Stockopedia”) is an Authorised Representative of Daylight Financial Group Pty Ltd ABN 77 633 984 773 (“DFGPL”) which is the holder of an Australian Financial Services Licence (AFS Licence No. 521404).
Information in this commentary is current as at date prepared unless otherwise stated. However, please bear in mind that investments can go up or down in value, and that past performance is not a reliable indicator of future performance. For more Important Information please refer to the Disclaimer section of this website.
This communication may contain general financial product advice. It has been prepared without taking into account your personal circumstances, and you should therefore consider its appropriateness in light of your objectives, financial circumstances and needs before acting on it.
If our advice relates to the acquisition or possible acquisition of a particular financial product, you should obtain a copy of and consider the Product Disclosure Statement (PDS) before making any decision.
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
No comments yet
No one has commented here yet! Why not be the first one?