Multibaggers - what a new US study confirms about our UK findings

You may remember our 2023 analysis of the top ten UK multibaggers of the last decade. Now there’s a fresh, data-heavy paper - *The Alchemy of Multibagger Stocks* by Anna Yartseva - a Birmingham City University academic - that analyses US stocks across many of the same dimensions.
In summary, the US evidence marries up very well with what we saw in the UK.
What the US study says
Yartseva built up a 2009–2024 dataset of 464 ten-baggers (stocks that rose greater than 10x and were still greater than 10x at the end of the period). She then tested what actually drove those returns by creating 36 portfolios split by size, value, profitability and investment characteristics.
Key insights
- The best performing multibaggers started small, with an average market cap $348m in 2009.
- Multibaggers, regardless of starting size, benefited from low valuations (the average forecast P/E was only 11x at the start).
- Through their runs, the average multibagger compounded its growth at high rates: revenue at an 11% annualised rate, operating profit at 17%, and EPS at 20%.
- Across the set small size, relative cheapness, high profitability, and aggressive capital investment led to stronger returns.
- The paper also re-states our multibagger equation : EPS growth + P/E Multiple expansion.
The chart below shows the 464 multibaggers split into 36 buckets by their characteristics and their “next year price returns” accordingly. It’s worth trying to understand the dimensions. On the right are cheap stocks (Value High), with splits across robust or weak profitability and conservative or aggressive investment.
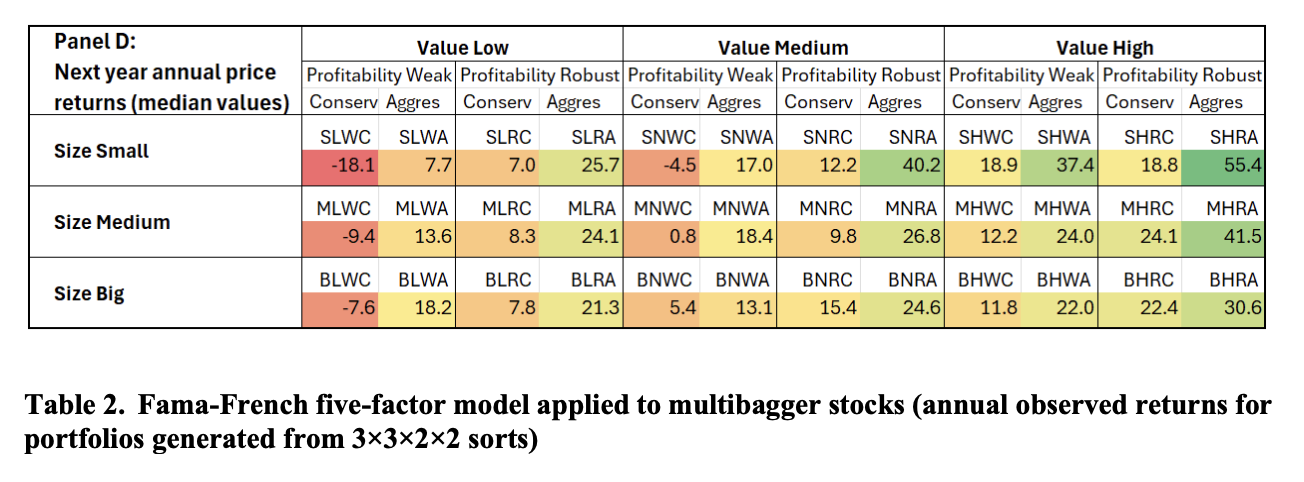
You can see at the far right that the very best returns were in undervalued small caps with high profitability and aggressive investment.
A simple guardrail emerges. Be very wary when a multibagger you own shows lower profitability and stops investing, especially if it’s at a moderate or premium valuation. That’s when drawdowns are going to hurt.
How this echoes our UK top-ten work
In our UK study and masterclasses we emphasised five “financial engines” for multibaggers:
- Sales growth runway - winners found new geographies, products or channels (e.g., Games Workshop’s international and licensing push).
- Operating leverage - i.e. revenues up, profits up faster. We showed how many of the UK top ten expanded operating margins through their run.
- High and rising ROCE - the true engine of compounding: multibaggers reinvested their profits at high rates of return and maintained those high returns.
- Strong cash conversion - cash is needed for self-funded growth: self funded cash beats borrowing or raising funds to expand.
- Room for a P/E multiple re-rating - a low P/E at entry provides a rocket fuel to the share price when ratio expands.
The US paper’s “small + value + profitability” recipe sits comfortably with this general playbook.
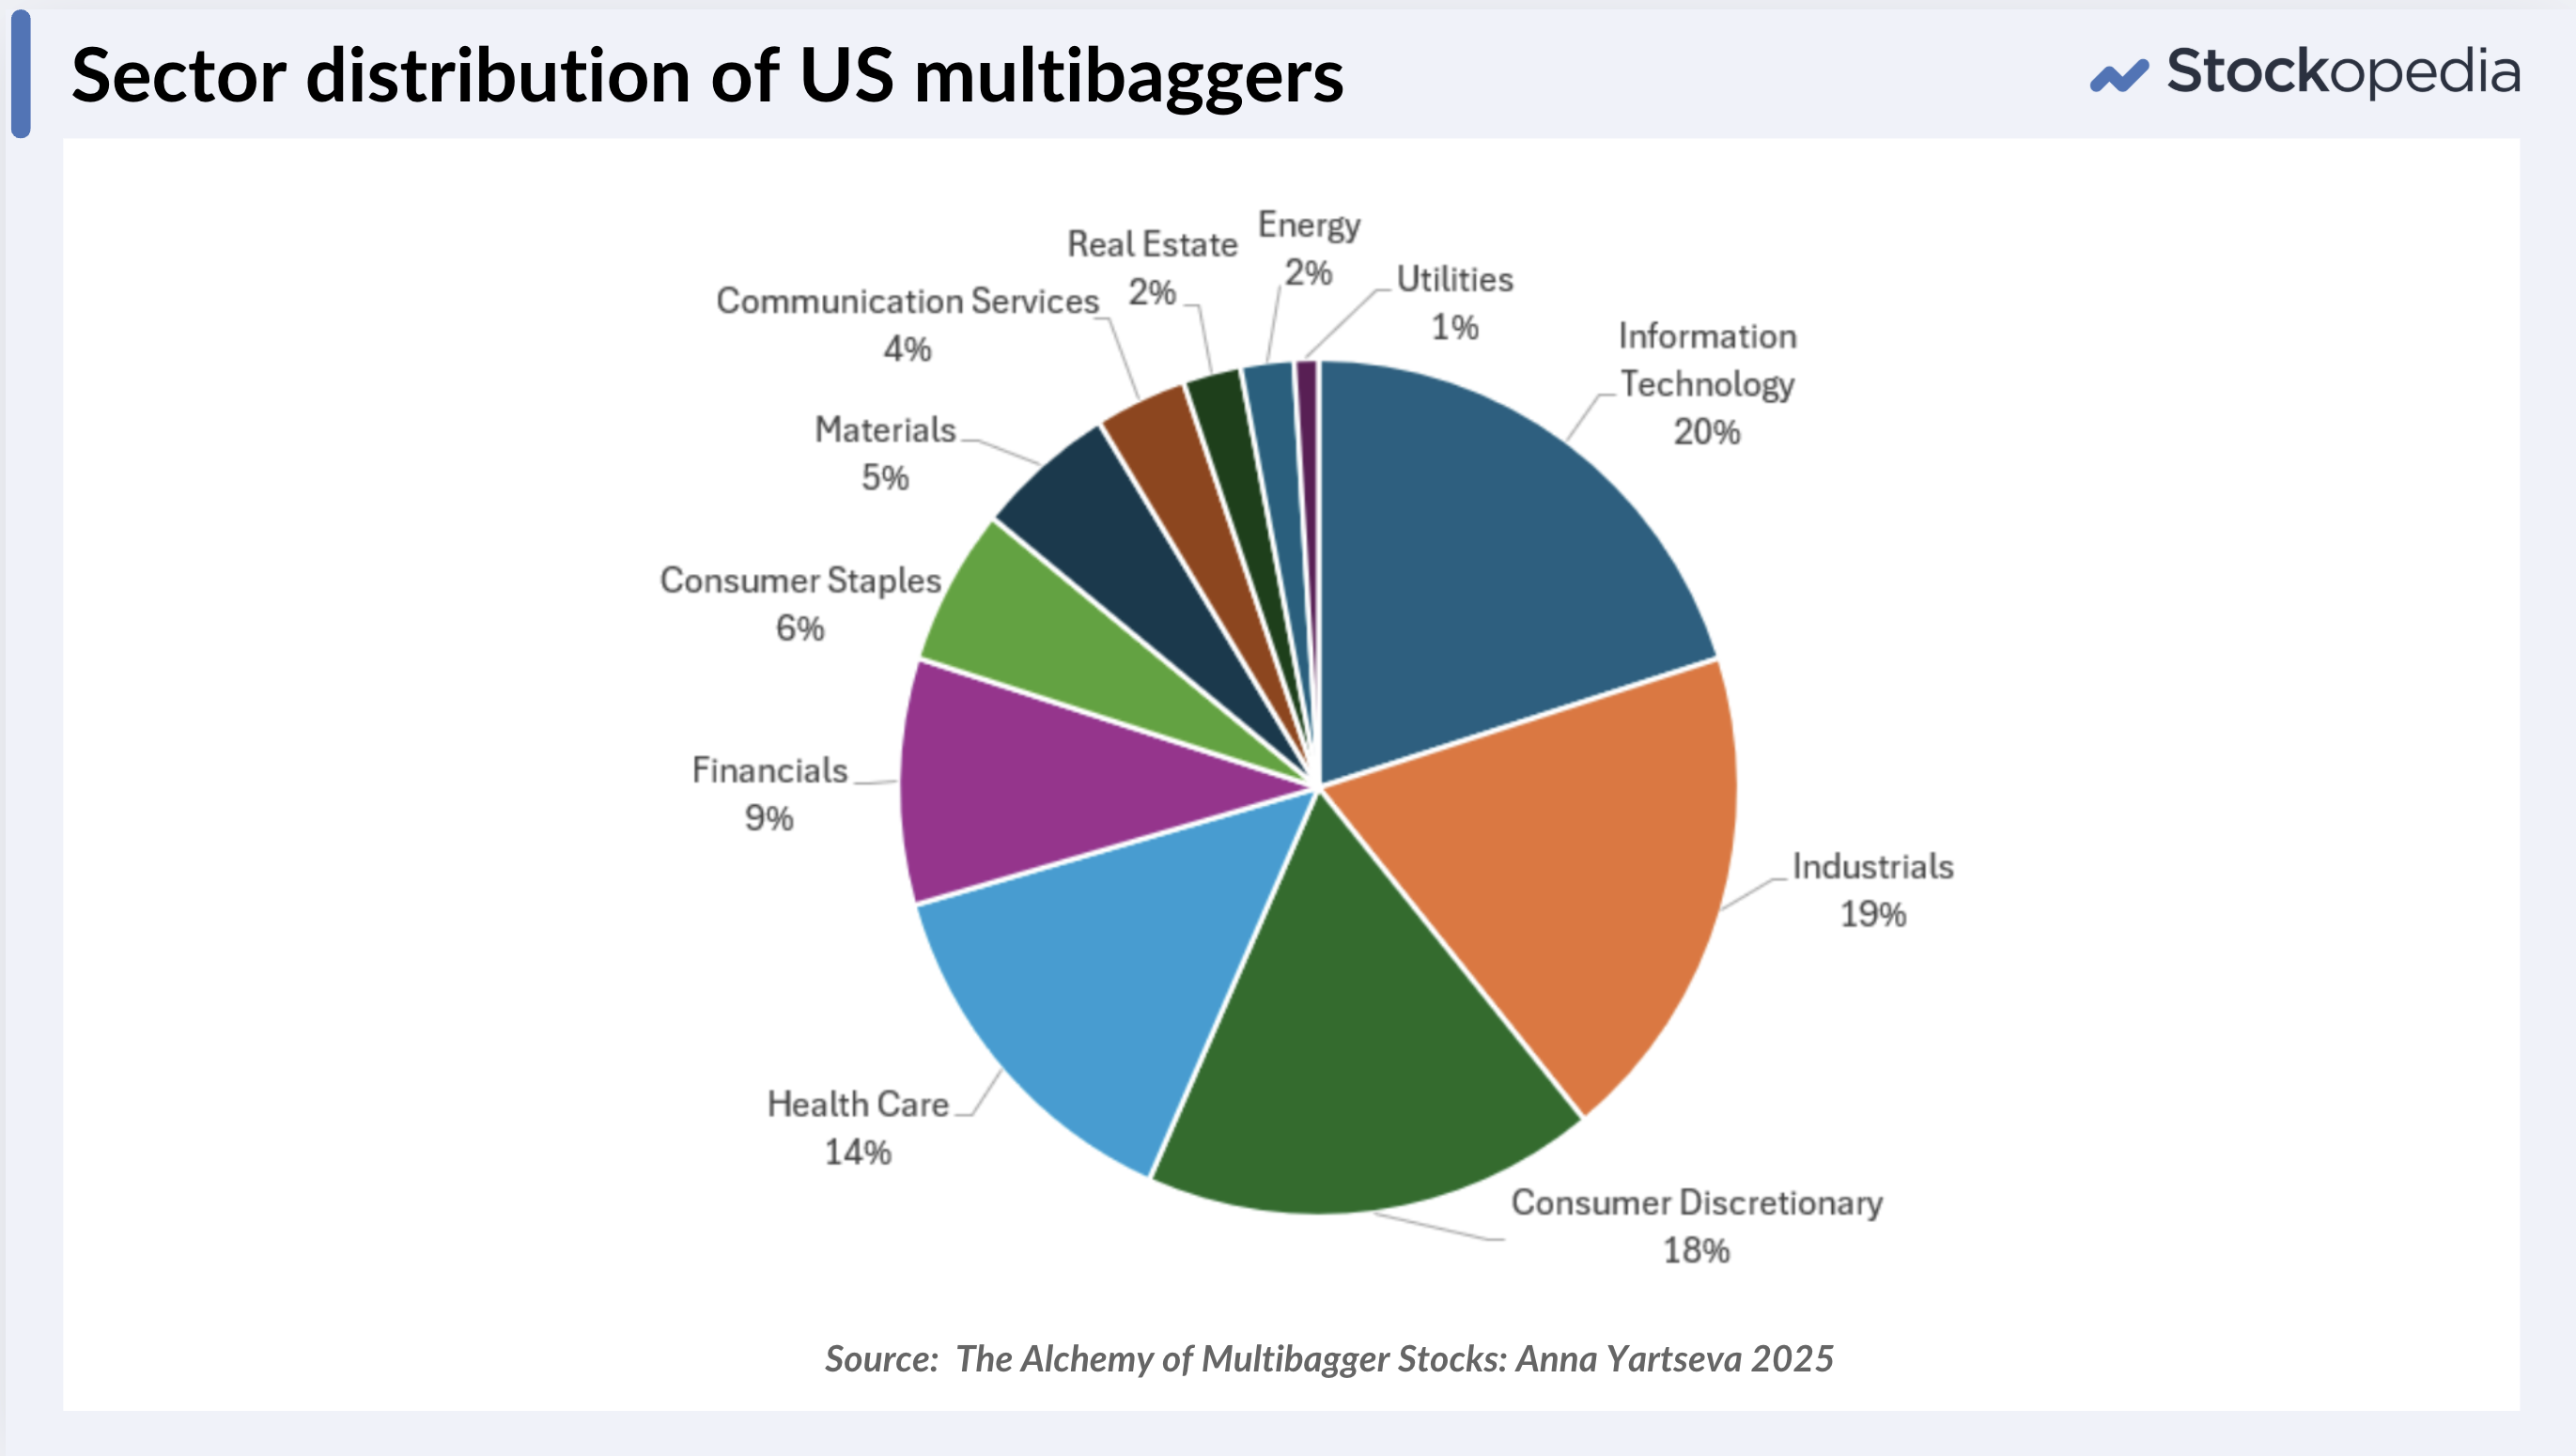
We also found that simple and sustainable business models were the best for finding top multibaggers. There were actually no technology stocks in the UK set at all. I was expecting to see a dominance of technology stocks in the US multibagger report, but this wasn’t the case. Only 20% of Yartseva’s 464 Multibaggers were in technology. Of course, the study began in 2009, and the industry dynamics have changed in the USA with cloud computing and AI having evolved since that date, so these industry dynamics can change.
What’s new?
A few useful points of note stood out:
- Aggressive capital investment showed up as a strong positive within US multibaggers. Yartseva found that higher asset growth paired with rising EBITDA growth was strongly aligned with outperformance. But there’s a caveat, if asset growth grew faster than EBITDA, forward returns dropped.
- In other words, companies should invest aggressively, if the profit engine can carry it. This is a strong counter to the general theme across academic finance that low investment (conservative) firms outperform high investment (aggressive) firms. Multibaggers really are the anomaly.
- In our UK case studies, we did discover that six out of ten of our multibaggers practiced disciplined bolt-on M&A, and reinvested the majority of their profits when cash generation was strong. This is the same principle through a different lens.
- Growth variables turned out to be less significant on a one-year view - using trailing measures of earnings growth, free cashflow growth appeared to be less significant for the next 12-month returns. This is counter-intuitive, as it’s often the first thing people screen for. Far more important was the investment growth rate as defined above, as long as it was higher than earnings growth.
- Be highly wary in increasing interest rate environments - Multibaggers tend to underperform dramatically in these periods, by as much as 8-10%.
An example - a recent real-world 20-bagger: Celestica
One of our members, Phil Hoffer, is going to be joining us for a webinar next month (invite link to follow soon). He has shared on the discussion boards a few times that he’s been holding the US stock Celestica, which has 20-bagged since January 2023, and is 200% up since it was mentioned in my November 2024 US clear trends article. I have to admit this kind of return rather puts the UK stock market to shame, as it took a full decade for our big winners to 10x on average!
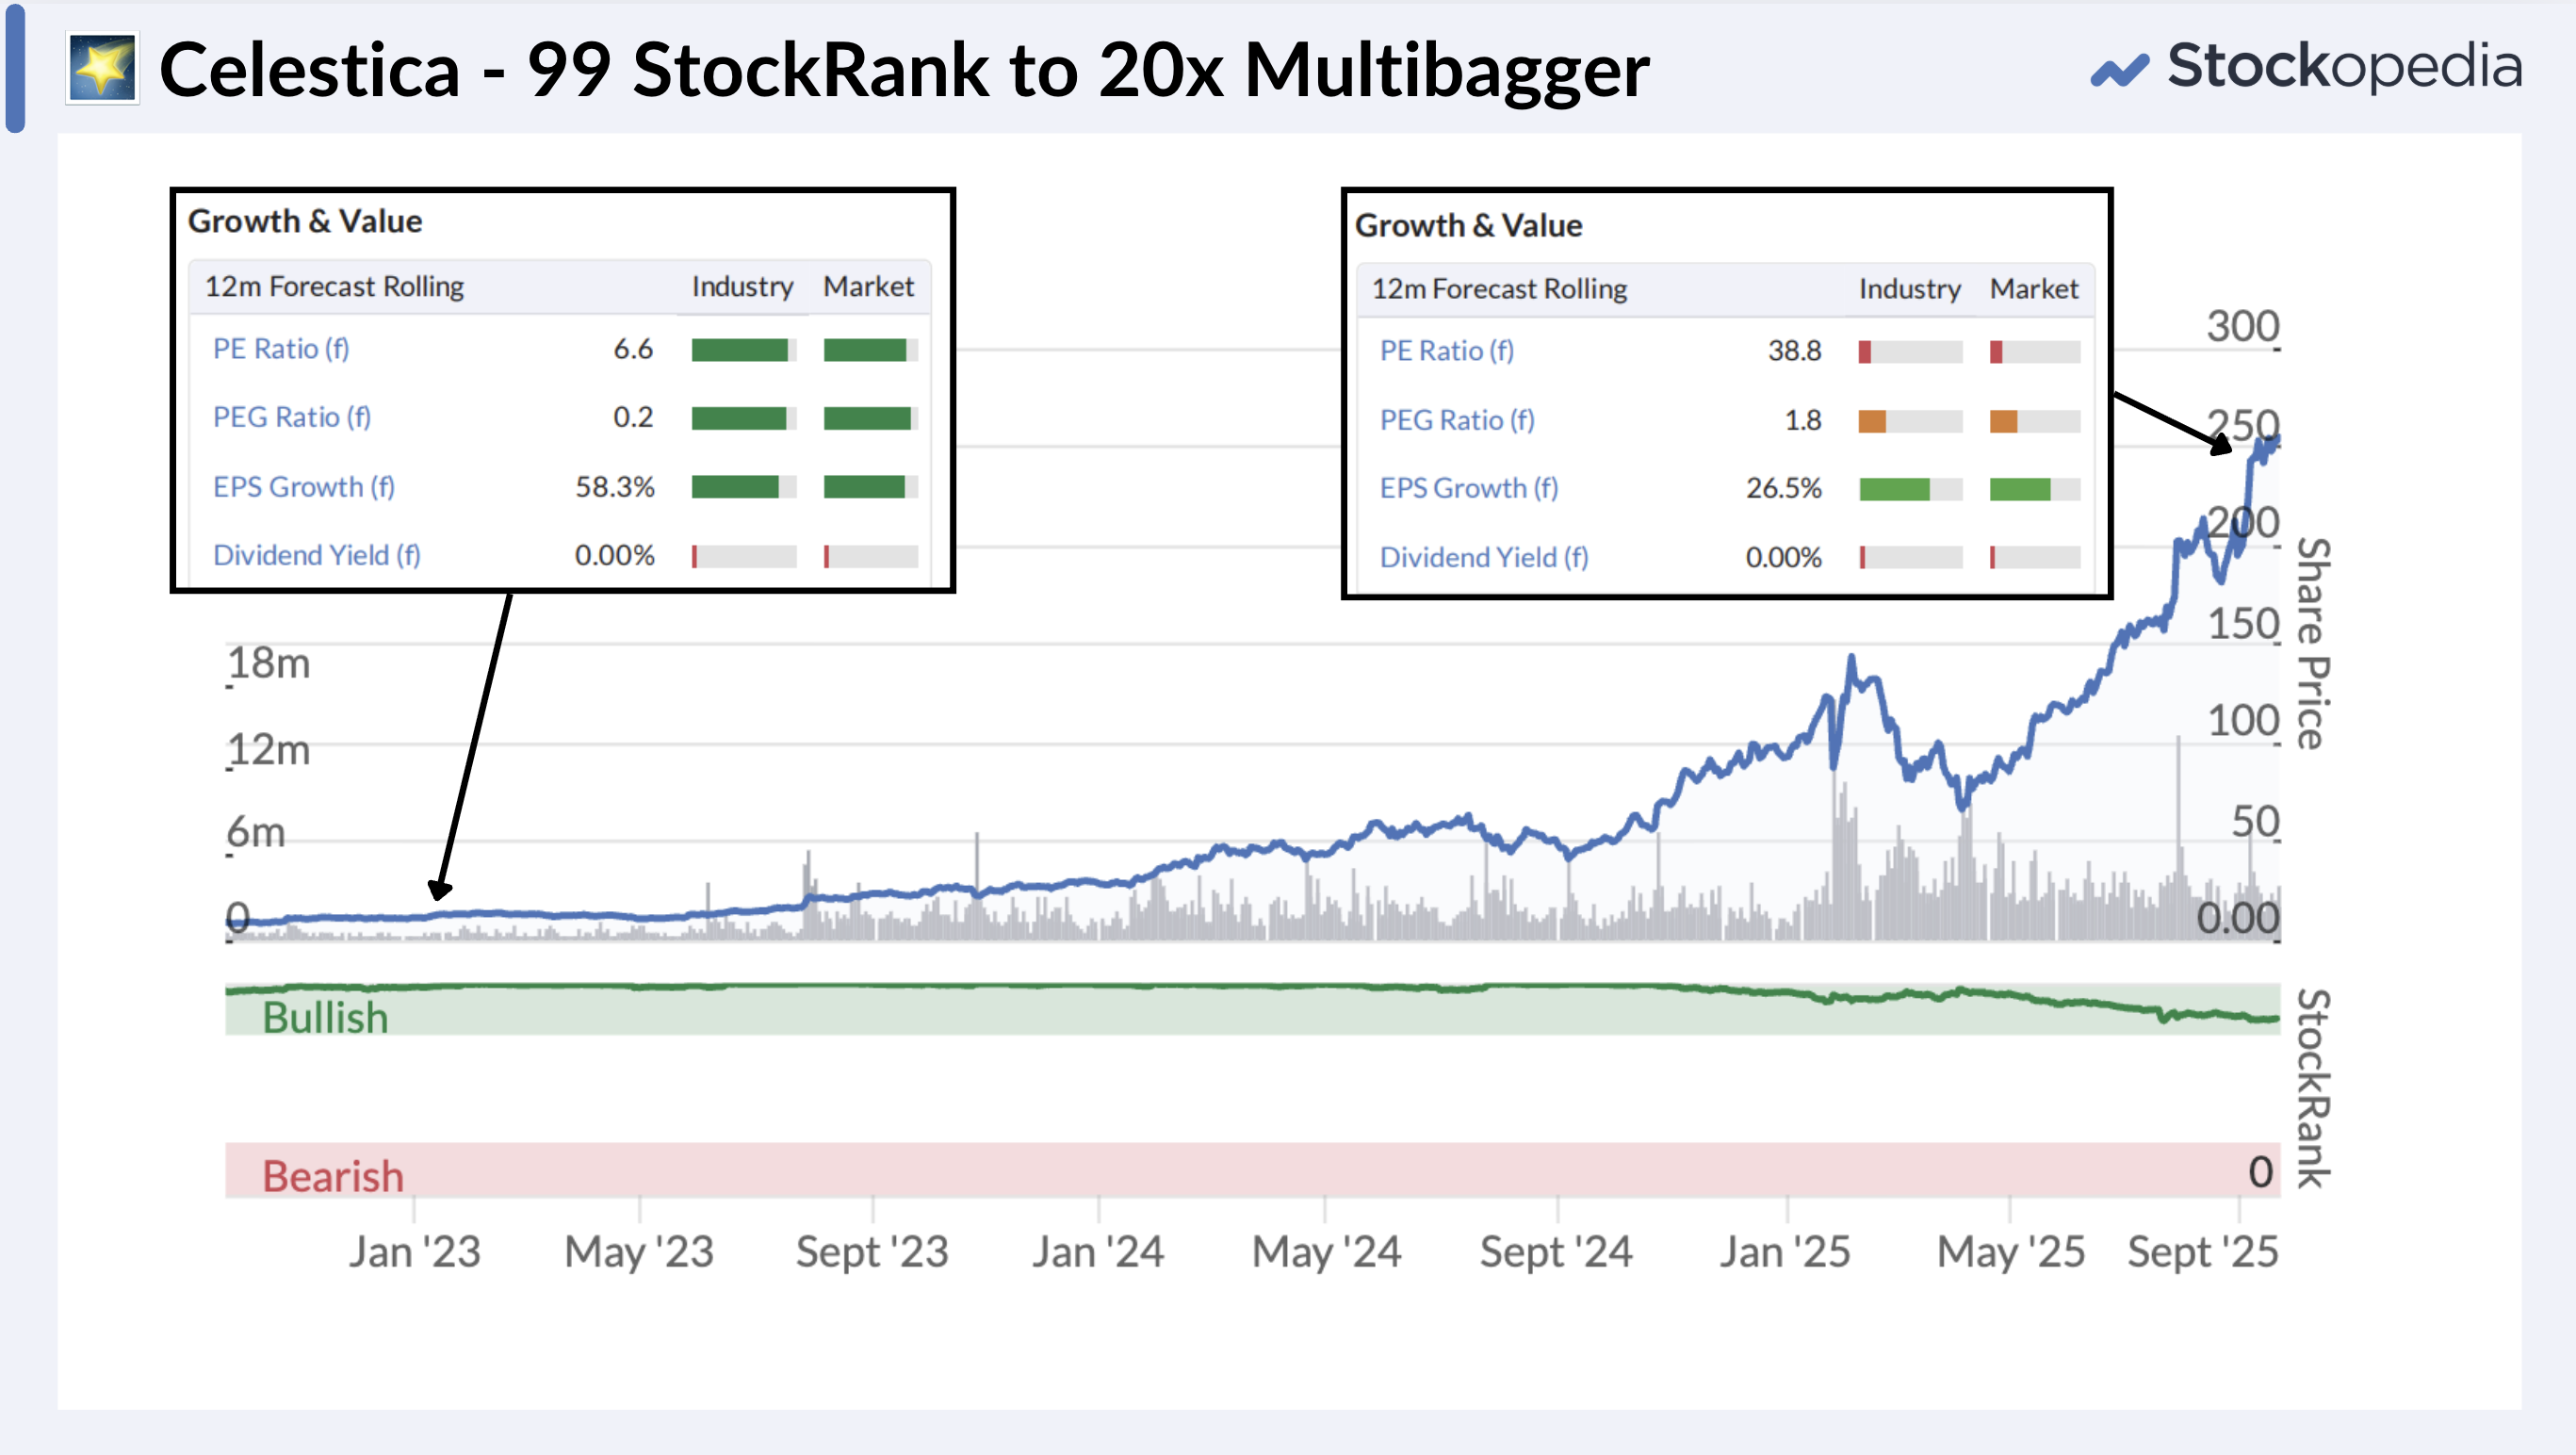
It’s a striking illustration of the same principles - when a low P/E multiple meets an accelerating sales growth runway and operating leverage, remarkable things happen. Celestica saw a powerful multiple expansion (from 6x to 39x) as the market caught up with the new economics.
It’s a great reminder, when both the financial engine kicks into gear and the narrative aligns with a theme, the multibagger mathematics can happen surprisingly fast!
Simple rules you can use
Let’s summarise with a recap of rules from this paper and our own research:
- Seek small/mid caps with lower starting valuations (for example a Price to Sales of less than 0.6, or a forecast P/E below 11 at the start), seek improving profitability, and companies that have opportunities for profitable investment.
- Prefer double-digit sales growth with operating margin expansion.
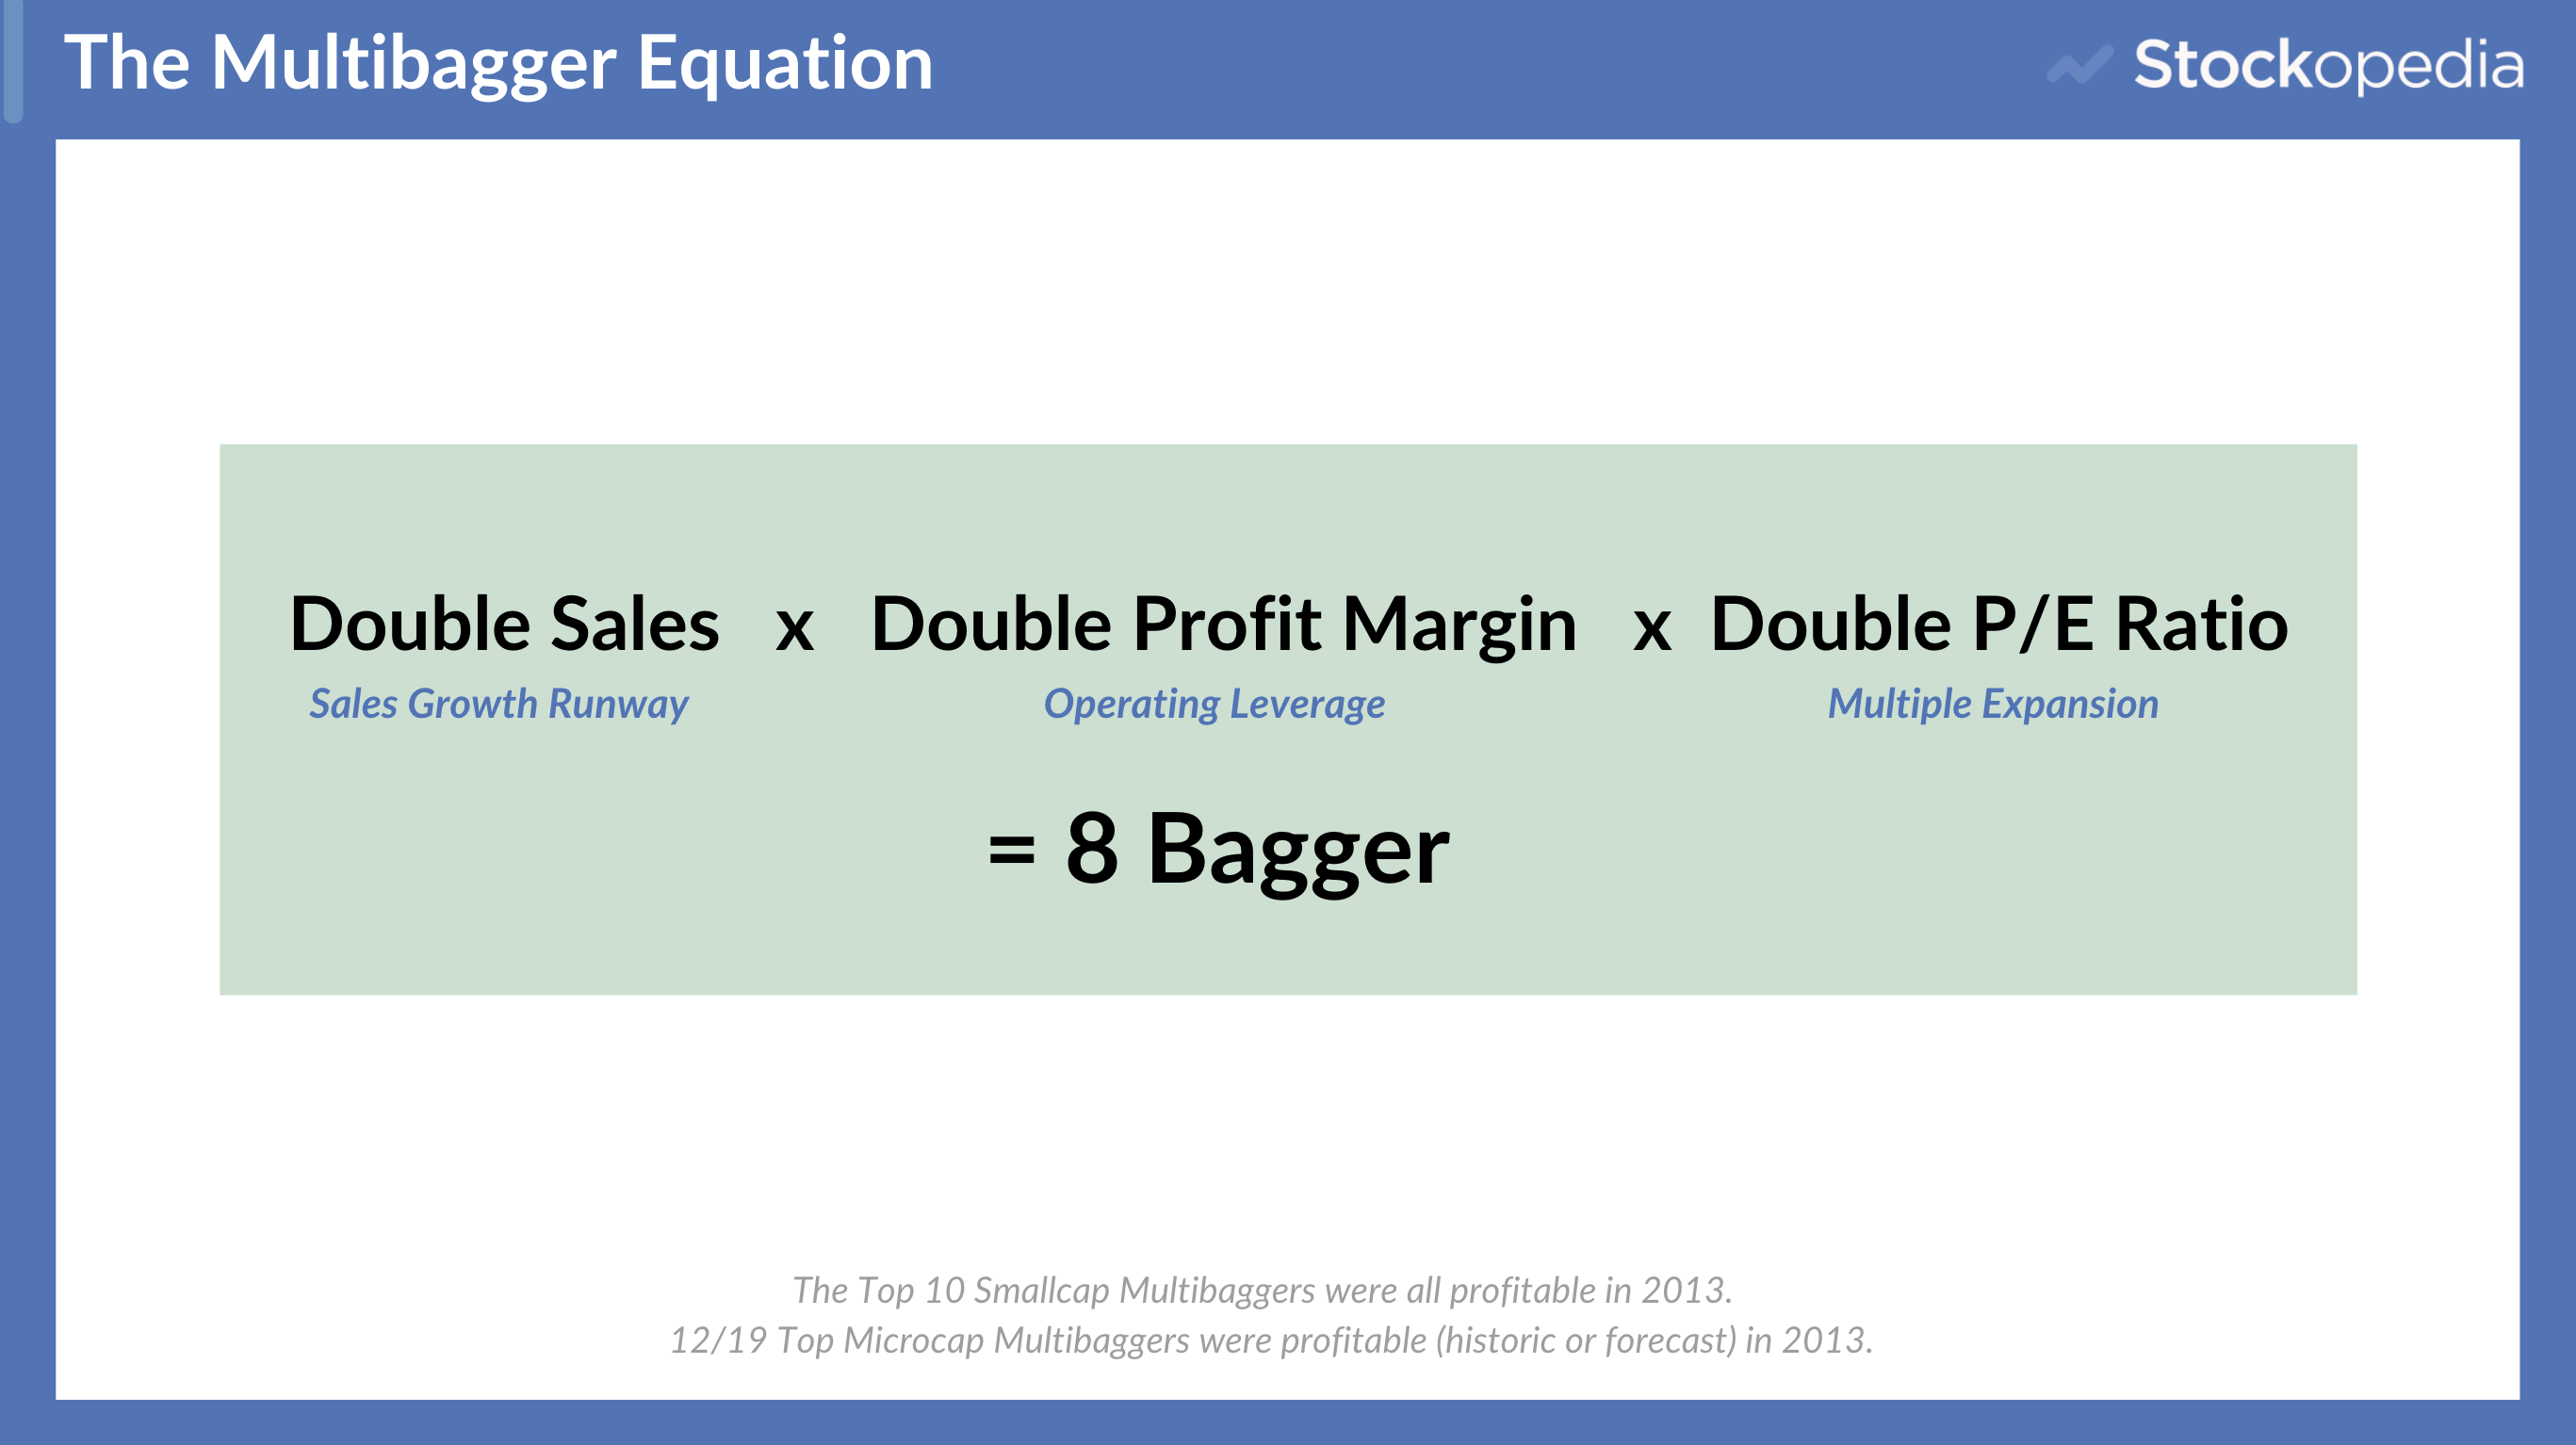
- Expect the best returns to come from a combination of EPS growth + multiple expansion - don’t rely on just one. And remember EPS growth is a function of both Sales Growth and Operating Leverage. This defines our Multibagger Equation:
Yartseva appears to be working on a checklist approach for finding Multibaggers - much like the Piotroski F-Score approach. I will be looking forward to seeing what she comes up with in her future research on this topic.
A reminder of our multibagger resources
We have a range of excellent resources for those wishing to learn more about multibaggers - an original webinar presentation of the research study, and then 3 half-hour masterclasses:
- Multibagger Webinar - 1 hour research study presentation.
- Masterclass: The Financial Engine of Multibaggers (sales runway, operating leverage, ROCE, cash conversion, multiple expansion) - includes the Games Workshop case study.
- Masterclass: Competitive Advantage & Capital Allocation (models, moats and managers; why tenure, founder-ownership and bolt-on M&A mattered in our UK ten).
- Screening for Multibaggers with Stockopedia (turning the rules into practical screens).
Please let us know which multibaggers you've discovered using these principles in the comments below !
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

28 comments
Hope its allowed to post this here - but found this discussion on the other side of the pond quite fascinating: https://podcasts.thecompoundne...
- with author Neeraj Khemlani of a "new book" The Coffee Can Investor - A Stock-Picker's Journey to Build Generational Wealth. I say new because there are other older books out there re the Coffee Can Investor idea.
+ Also back in the UK: GVC Holdings (now Entain) was a 100 / 200+ multibagger for a period of time - depending when you brought and sold ! As Google AI puts it: Between 2010 and 2021, the stock rose from roughly 100p to over 2,100p, representing a growth of more than 20x. However, since reaching those historical highs, the price has undergone a notable correction.
SanDisk (NSQ:SNDK) is up over 30x in less than 9 months, not seen any comments about it, on this site. Unfortunately it flew under my radar.
Micron Technology (NSQ:MU) is up 10x in just over a year, l did hold.
I do hold Celestica (NYQ:CLS) still. The US makes the UK multi baggers look pedestrian. They are not even small caps, look at NVIDIA (NSQ:NVDA).
Pan African Resources (LON:PAF) has been my best UK stock in the last few years. Far outperforming Serabi Gold (LON:SRB), which gets far more attention, on here.
Maybe this study needs redoing, as things have changed, in the last few years.
Nice article Ed, thanks.
I have held many multibaggers over the years, but usually sell too early or sell on bad news which is then followed by a breakthrough and re-rating. My latest attempt is Tekcapital (LON:TEK) , which on Stockopedia has gone from sucker Stock to Super stock, there is also much speculation about its next IPO of Guident, which appears to be in a hot sector which could do well on the NASDAQ. I live in hope, but would be interested to know what others here think.
I’ve been on Pan African Holdings (PAF) since 10p and it’s nearly 90p today, and in my judgement still got plenty of life. Not without its risks of course, with South African exposure, but:
Excellent management
Sound strategic diversification into Australia at a great price.
Avoids basketcase countries
Manages costs effectively
Profits a certain to continue to soar in 26 if gold price holds up anywhere near where it is at the moment
about to move from aim to main market introducing a whole new raft of potential investors
it has met many of the criteria set out in this excellent article, though of course has been supercharged by gold price rise
Do the maths
mmol - I agree with what you say about Pan African Resources (LON:PAF). I bought at 25p and will hold as there is so much more potential on offer.
You are not cheering me up this morning!! I bought Pan African Resources (LON:PAF) back in April 2006 at around 10p. There was a rights issue in Jan 2013 so I guess that is why the price chart shows the price around 5p back then (?). I took some profit at around 20p in Jan 2013 but sold out in April 2020 when the price was around 9.5p after a significant price slump. During my long holding period of 14 years the price fluctuated between c 5p and 20p (see Stocko chart) but never took off - until Jan 2024 when the rise from around 16.5p to the current level of 89p occured. I would have had to have the patience of a saint and the forecasting ability of Nostradamus to predict that if I had continued to hold the share for 20 years it would eventually come good! However, well done on riding the current wave of gold frenzy through holding onto Pan African Resources (LON:PAF).
Don't worry about it. We have all been there.
I have 7 multibaggers, 5 of which are British. Rolls Royce is my best performer with a gain of 1850 % , bought at an average of less than 60 p per share. Crowdstrike is my best American performer with a 700+% gain.
Hi Jenny, Great results. Do you have any nuggets to share as to why you purchased Rolls-Royce Holdings (LON:RR.) and Crowdstrike Holdings (NSQ:CRWD) or any of your 7, when you did?
I already had shares in Rolls-Royce Holdings (LON:RR.) when they offered new shares for 32p in Nov 2020 which seemed to be a no brainer, so I bought 980. Crowdstrike Holdings (NSQ:CRWD) was a recommendation in The Daily Telegraph and I went with my gut feeling and bought 120 at £47. I just wish I had bought more.
Thanks for the reply Jenny, love the feeling we all have far to frequently- just wish i had bought more !
Looked back today at a share i held for best part of a year 3 years ago. It had gone no where so I sold. Of course it has 3 bagged since
Patience is a virtue. I have a couple of shares I've held for some time, and like you, I often think that I should sell them, but never do. However, my BP (LON:BP.) shares were showing a small loss a few weeks ago, so I bought another 2000 at £3.56. I did the same with Scottish Mortgage Investment Trust (LON:SMT) when they dropped under £7, putting in £500 per month until it started to recover in 2024. Both of these have been profitable moves
Interesting. I have had the great fortune to buy and then hold Ideagen at 6.5p when it was listed on the Plus market before moving to AIM in 2013 and then sold to HG Capital at 368p in 2022, if I recall correctly ( I don't keep meticulous notes). Ideagen was, and is, a UK software company of real quality - so a tech play. I may have read this wrong, but it strikes me that it should have featured in multi bagger analysis somewhere.
My biggest recent winner (10 bagger +) doesn't really fit the rules I'm afraid to report. I bought Valeura Energy (TSE:VLE) at 0.55c because it was a net/net with no revenues & looking to use its cash pile for M & A. It pulled off two amazing deals offshore Thailand and it's rocketed since. I look for good mgt with a cash pile to deploy in M & A. Transformational may be an overused word in M & A but they really can happen, going from a standing start to flat out sprint in the blink of an eye.
Wow - congratulations Joe - that really is a terrific chart! What other high cash/good mgmt / potential m&a setups are you seeing?
Thanks Ed, luck played big part too as I didn't know Valeura's deals would be so good. I just really liked the risk/reward. Valeura's set up was quite unusual and it's hard to find similar scenarios. My favourite shares at moment are Tenaz Energy (TSE:TNZ). Canadian listed O & G co looking to buy mature assets on the cheap, exact same model as Valeura. I've been in it for a couple of years. I was hoping they would do another Valeura, and they have. Their mgt is exceptional, previously ran $bn O & G companies and they were looking to replicate that success and they're well on their way, still looking for further transformational deals. I like Cerrado Gold (CVE:CERT). It's my main gold holding. No debt & undervalued vs other gold co's. Main producing asset is gold mine in Argentina but has two further projects in Portugal & Canada with $bn's NPV that mkt gives no value to. I like ACG Metals (LON:ACG) in the UK and have held for a few months. Gold mine in Turkey that will transition to copper mine next year. CEO is ex deputy CEO Rusal so has contacts and big ambitions to roll up other copper mines and create multi billion value co, we'll see. Two other junior O & G co's I like are Jersey Oil and Gas (LON:JOG) & Challenger Energy (LON:CEG). None of these co's are net/net's as Valeura was. I like small cap commodity co's with potential to multi bag, mainly through good mgt deal making.
That's quite a move in Cerrado Gold. An EM fund manager friend of mine has Asante Gold (CNSX:ASE) as his highest conviction gold pick at the moment - told me 2 weeks ago and it's risen about 40% since - though I prefer gold juniors with a higher StockRank as it highlights the producers (able to self-finance exploration assets). There's an acceleration of capital reallocation to producing gold juniors at the moment which is rather exciting if you are long!
Celestica is a US listed stock (on the NYSE) but is a Canadian company (listed on the TSE). Celestica (TSE:CLS)
The key point was eps growth + multiple expansion.
However multiple expansion i.e. PER, should only occur if there is eps growth and/ or a reduction in risk. Given that company risk changes little, this formula really boils down to eps growth that is sustained long enough for the market to notice and accept that it is sustainable.
What i am saying is that the formula in practice means finding companies which have a highly profitable product, in a market that is expanding and who are able to build barriers to entry against potential competitors. This is basically Buffett's investment approach.
I am guessing that Buffet had a significant number of 10 and more baggers over his investing lifetime.
Interesting. Put the criteria thru ChapGPT and although no stock met the criteria a few were not far off. Time to do more work and hopefully catch a multi bagger.
Atalaya Mining Copper SA (LON:ATYM) ,Ramsdens Holdings (LON:RFX) ,M P Evans (LON:MPE) ,Caledonia Mining (LON:CMCL), Anglo-Eastern Plantations (LON:AEP)? (missing p/e forecast for some reason) qualify at the moment if strictly adhere to the equation, a few others if you loosen the criteria a tad (e.g Smith & Nephew (LON:SN.) ,Property Franchise (LON:TPFG) ), a fair few have 'Ahead' statements, all have decent charts. Great work
did those come up from the 'multibagger' screener?
I created a screen that has the parameters Ed outlined in his multibagger article but you have to export the results into a spreadsheet to get the most from it imo. You can look at the data from different perspectives that way
I’ve held (LON:AEP) since June and bought more in August, I’ve just finished putting it through the Multibaggers equation ( rough and ready ) and I’m pleased to see it’s passed the test. My only concern was if the recen price hike would make the current share buy back look expensive but I guess it’s only £8 million so probably nearly completed by now.
Property Franchise (LON:TPFG) has easily been my best performer since I first bought, at less than 150p , Belvoir which TPFG subsequently took over. The price is now 600p ish and I still have most of my original stake plus a very nice divi. I moved house in 2019 and got acquainted with a lot of estate agents most of whom were rubbish which made me think that the sector was ripe for change. Belvoir really impressed me and by a fluke I noticed they were listed and their business was doing really well. Goes to show that even having missed Gillette and Coca-Cola, keeping your eyes open for change pays.
Great article Ed.
The only multibagger I have had in US is Apple and the one i missed is Costco.
Elephants do gallop!