Multibaggers with 10 Bagger Potential - Carclo (CAR) Returning to Growth

Carlo - Returning to Growth
2nd July 2021.
Carclo (LON:CAR) hit a new low of 4p on the 18th of March 2020. ( Lowest buy price 5.1p, additional buys at 11p, 35p) - (I hold a long position).
Having just listened to the presentation, I found the CEO and CFO competent and conservative in their outlook.. They cover FY2021 in detail but were reluctant to elaborate on FY22 numbers. They did mention the 2 new contacts they have won will contribute to FY22 revenues and profits. The impression I got was they expect growth to be significant (>20%) but wanted to underpromise and potentially beat expectations. So my forecast has been upgraded slightly, but my expectations are this is likely to be upgraded as the year develops.
Sales Forecast
Sales forecast 2020 to 2025

Valuation
The evaluation model suggests 113-160p valuation for year-end 2021, and 2025 upper-end valuation of 570p . See the graph below

As Alway DYOR, don't trust bloggers and vloggers.
BSV
27th April 2021
Carclo (LON:CAR) hit a new low of 4p on the 18th of March 2020. ( Lowest buy price 5.1p, additional buys at 11p, 35p) - (I hold a long position). With the share price already rising 100%plus in 2021 I expect the best is still yet to come.
Carlo released a trading update, see link https://www.stockopedia.com/sh.....
Overall the second half was better than the first and the tool orders in 2021 suggest further growth to come 2022.
The results look ahead of my expectation hence I updated my model. (information provided below)
Sales Forecast
Sales forecast 2020 to 2025

Valuation
The evaluation model suggests 100-140p valuation for year-end 2021, and 2025 upper-end valuation of 440p . See the graph below.

As always DYOR
25th Aug 2020 - Has Carlo Turned a corner?
Carclo (LON:CAR) hit a new low of 4p on the 18th of March 2020. ( Lowest buy price 5.1p, additional buys at 11p) - (I hold a long position)
Carclo plc, a global manufacturer, principally of fine tolerance injection moulded plastic parts for the medical, electronics, optics, and automotive safety markets.
With plans in place for cost reduction, debt management, pension payment, and robust sales into medical health markets has this value trap turned a corner?
Having already remove significant cost from the operation and a focus on more stable revenues from the Medical and Aerospace market, this should throw off an additional £10M of free cash flow. The pension contribution is increased by £2M from £1.8M to £3.8M should be comfortable assuming no further deterioration in business. It could take 3 years to repair the balance sheet from free cash flows.
The Net Profits from the Technical Plastics and Aerospace business are better than from the LED Technologies business they just sold (which was loss-making).
Stockpedia suggests Operational Cashflows have actually improved £17M in FY2020 compared to FY19 as a result. See below;
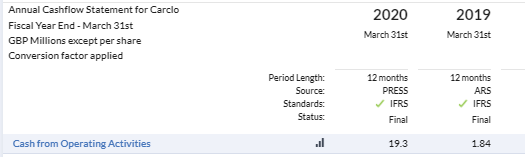
My estimate suggests FY2021 and beyond FCF will be north of £15M, so debt interest payments (£2.5M), and pension payments (£3.7M), are easily covered, and there is plenty of cash to pay down debt or add capacity.
From the market low, any improvement in pension liability will improve the company balance sheet.
The company may decide to raise more cash or improve its position by trading, only time will tell which it chooses. Either way, the investment case should improve as the balance sheet becomes stronger.
Updated with march 2020 results

I've updated the model to reflect the 2020 results. Topline revenue is provided above.
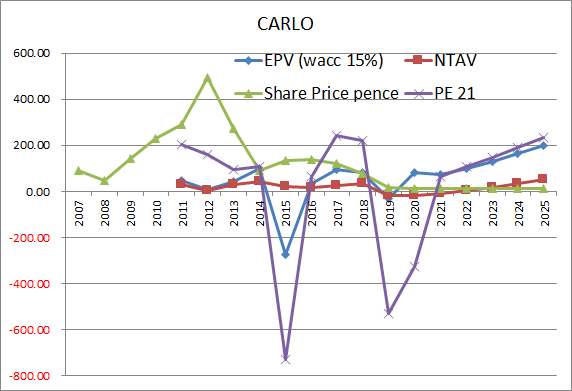
Evaluation model suggests 60-70p valuation for 2021, (160-180p for 2024). See the graph below.
DYOR
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
22 comments
A stomach-lurching plunge in price since the beginning of July has suddenly made Carclo even better value. I hope.
Well, I did not expect to see 35p again, and better value at this low price. Nice to pick up a few more at this price.
As always DYOR
BSV
Bloody well done! How remiss of me not to look at this post closely when it was originally posted! Not sure about getting in now but will keep an eye on the results. Cheers.
Hi Leebod,
I posted a new update in the main post. I would buy more today if it was not already the largest position in my portfolio. My rules prevent me from adding to a position once it reaches a certain % of the portfolio. I still there is significant upside from here.
As always DYOR
BSV
For anyone interested.
Carclo (LON:CAR) is holding a presentation at https://www.investormeetcompany.com on 2nd Jul 2021 at 11:45 am.
You will need to register.
BSV
What your thoughts on Renold
Hi Azhar,
Renold (LON:RNO), Has high debt but lacks the FCF and growth I would be looking for.
DYOR
BSV
I recently posted CAR as my stock suggestion on Mello. What investors need to look at is the new board led by Nick Sanders, he was right hand man to John Moulton (Apax Partners) at Better Capitial, turnaround specialists. Sanders left to run Gardner Aerospace where he did a fab job of turning the co around. He has brought in two non-execs, each immediately invested the equivalent of their fee approx into CAR shares. It's now a refreshed board. The co recently won a 10 year framework worth £10-£15m a year, so £100-£150m sales, this was to make the plastics for lateral flow test kits. Aerospace is a tiny part of the business now but with Sanders being ex-aerospace at Gardner he has the contacts to turn this part around too - there could be real value here in turning it around and selling it off to become a pure play specialist plastics business. Only a couple of years ago Consort Medical bid 116p a share for the co so that was real money telling you what they thought the co was worth imo.
Well worth keeping an eye on, I am long from 13p tho I did trade just prior from 7p to 11p.
All imo, dyor etc.
RebelChatRoom, hello. Always interested to hear you at Mello, including your views on Carclo (LON:CAR) . Know the people, brief but incisive reasons for buying. I am impressed by you and others at how clever you were to buy in at very low prices, but I and others like me would be interested to know if you would buy in at the current price, or alternatively at what SP you would buy in the n. Thanks for listening!
I'm struggling to understand how such tremendous growth is being caused. Is it just from "cost reduction, debt management, pension payment, and robust sales into medical health markets"?
Hi Paolosolani,
The main contribution to improving profitability is the sale of loss-making division LED Technologies in 2019, which accounts for most of the exceptional losses. Once this was sold Carclo (LON:CAR) looks very cash generative.
In addition, recently it has announced a number of new substantial contracts, like to contribute to the growth of the top line and profits from FY22 and onwards.
I hope this helps.
BSV
Thanks!
I have personally owned since 26p.
Hi Ed,
Surprised to read it.
What persuaded you to invest/to trade a position?
Hope you did DYOR.
BSV
@Bluesky Ventura
"What persuaded you to invest/to trade a position?"
Carclo fitted the bill for me for a certain speculation class that I find attractive in my discretionary investments - which I'd call "Deep Value & Momentum with Insider Buying". It's quite a simple approach. Deep Value comes with risk of course, especially when you have a balance sheet situation like Carclo does... but the change in management to bring in turnaround specialists, cluster director buying and trend reversal are positives. Very high StockRank of course.
I re-read "Super Stocks" by Jesse Stine last year - which is one of my all time favourite books on making money in stocks. This stock fit the bill.
I don't see this as a keeper... but I'll hold as long as the trend persists & the rankings stay elevated.
Thanks, Ed,
Appreciate the explanation.
After watching the following video reviewing the book: Insider Buy Superstock by Jesse Stine, I will read the book.
(I've posted the review for anyone interested.)
;ab_channel=FinancialWisdomBSV
Nice to see our Carclo bet paying off so well @blueskyventura ;-)
It has been an excellent run, 10 bagged from its low. Still believe it can ten-bagger again.
BSV
£car Any thoughts as to what has lit the fire under the share price in the past few days? (I hold so am not complaining.)
Hi James,
Hopefully, the company is being re-rated by investors. Fingers Cross this is the start of a longer-term move.
BSV
Hi Ed,
I believe that some refresh of the DDs area was on the cards, but the system you are using would really benefit from being able to scan for deep value and show net DDs for the last 3,6,12 months in the same search. We could really do with more detail too - at the moment if I look at the DDs for a stock I have to check the job title somewhere else. I also have to go offsite to find what their previous holding was (the % figure is really not much help for most directors). I'm afraid that the graphic showing DDs is invariably wrong in my experience. At the moment the only way to know (other than sitting on Investegate all day) if a big DD has happened is by going to another site which shows the previous day's DDs.
It's never going to be straight forward looking at DDs because sometimes they are meant to be deceptive, but I feel you have the data to make it somewhat easier.
A digression, but on the next tab down, you have the data for the funds which are invested in a company. It's a real shame that I can't find out, for example, which stocks T. Rowe Price has and be able to set up an alert when it buys into a listed stock.
Other than that, all fine!
All the best
@FunnyMoney