Multibaggers with 10 Bagger Potential - CARD FACTORY

Card Factory - Lowest cost Producer and Vertically integrated Retailer.
May 21st 2021 up-date
Card Factory (LON:CARD) (buy at 38p, and still hold at 73p)- The refinancing is completed, Card Factory shops are re-opened and return to level pre-covid sales level, and the equity fund raised in view. All three elements are in place for the business to return to good health. https://www.stockopedia.com/sh... link the new release.
To understand why this business is like to do well it important to understand the Free cash the company is able to generate. I've revised my model with the new equity raise at 60p and 40p below.
Sales Estimate FY21-FY26

Evaluation model at 60p fundraise (117m new share in issue)
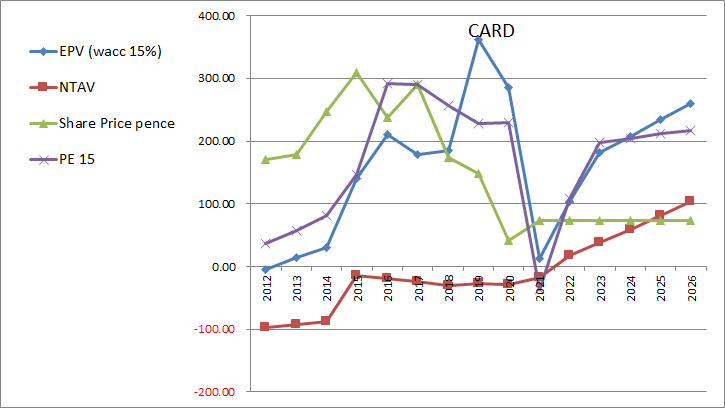
Evaluation model at 40p fundraise (175m new share in issue)
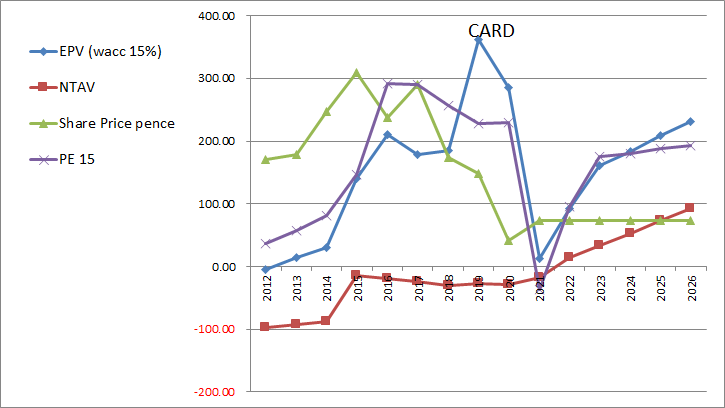
150p above share price looks very feasible regardless of the level of dilution. I hope retail shareholders get to participate in the fundraiser.
I am happy to continue to hold my position in the stock. I really must state please do your own research and evaluation of prospects here before making your own decision.
BSV
1 April 2021 UP-DATE
Card Factory (LON:CARD) (Hold at 73p)- banks continue to wavier debt pile, is a welcome piece of news. I still expect the company to want to raise funds and hopeful this will be done at a higher share price supporting the valuation below further.
https://www.stockopedia.com/sh...
DYOR
BSV
15 Jan 2021
Card Factory (LON:CARD) Had a year low of 25p during 2020 having declined 72% by year-end and looks good value at 38p today.
I was encouraged by the sales numbers (£284M FY 21) during the Covid-19 period and cash how cash has been conserved (probably due to government help ).
After 5 years of poor share price performance (Share price moving from 327p to 38p today) valuations look extremely cheap. With Covid-19 vaccines rollouts in the UK, a full recovery seems on the cards by year-end 2021. Add this with the growth engines of online sales and partner sales the future looks bright ex-covid 19. If free cash can return to previous levels this is a very profitable business.
Sales Estimate FY21-FY26

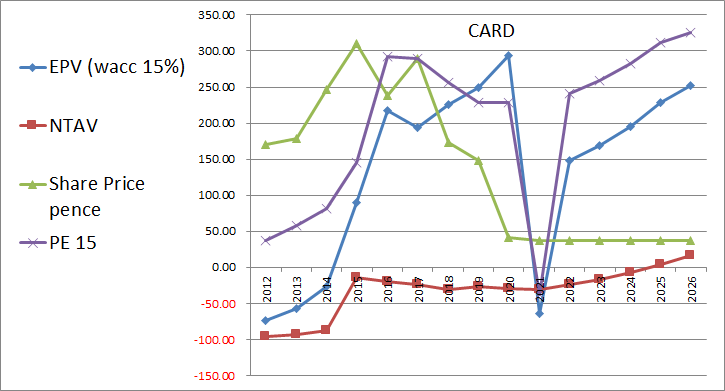
Evaluation model suggests 150p valuation for year-end 2022, (325p upper-end target for 2026). See the graph below
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
16 comments
I've just bought in here as I believe this is a deeply undervalued stock.
Hi Simmsc,
I hope the investment goes well for you. I am hoping for a 200p recovery in the share price, the stores look busy locally which should be good for cash flow.
As always DYOR and don't trust the posts on this and other media outlets.
BSV
Card Factory (LON:CARD)
Model up-date with potential new equity raise.
BSV
Card Factory (LON:CARD) first mentioned in Aug 2020 (see link: https://www.stockopedia.com/co...)
Issued a trading update https://www.stockopedia.com/po...
Essentially saying its trading above expectations and 'The Company has agreed headline terms for refinancing of the Group with its current syndicate of commercial lending banks and will issue a further update, over the coming weeks, once terms are documented.'
I expect the share price to make its way to fair value (150p) very soon. A day to fill my boots.
As Always DYOR and don't rely on blogs and vloggers like myself.
BSV
This person seems to enjoy trolling one of our SCVR writers, usually in the form of "Small Cap Dog Of The Day" discussions. Explains the contrary opinion to today's report, rather than any genuine conviction.
Hi brballs,
For the record, I posted Card Factory (LON:CARD) on the 15th of Jan 2021 originally, see link below.
https://www.stockopedia.com/co...
I believe Paul Scott decided to the company worthy of some coverage after my original post. We should not call it trolling when an SCVR writer expresses an opinion about an investment, just because some else already has and vis a verser.
I think you'll find you always be ignorant about my motives, that does not make you a troll either.
BSV.
No April fools. Just a £CARD valuation.
BSV
Hmmm what makes me wonder is :-
"Share price moving from 327p to 38p today" - its 74p today
Evaluation model suggests 150p valuation for year-end 2022- the graph clearly shows sub 50p
I'll stick with my initial assessment, thanks....
Hi PLSnve5t,
the green line is the share price on the 15 of Jan. The valuation is in red(NTAV), blue(EPV), purple(PE).
Hope this explains the graph better.
BSV
So why did you say "There was me think this could one for the Coffee can.
Selling is probably the wiser choice"
Seems to be contradictory.
Hi Herbie,
The coffee can comment was meant as a joke, I find it amusing investors think they are stock pick 100baggers and put them in an imagery coffee can.
I am not critical of anyone selling, the debt and the rolling liquidy has risk, and possibly it's a wiser choice than me still wanting to hold £CARD.
Card Factory (LON:CARD) The share price rise has taken me by surprise also, but I guess it is only a reflection of COVID-19 recovery playing out in real life and the stock market.
If and when the company is allowed to trade (12 April I think ) the free cashflow is substantial, (>£100M ), which can comfortably service and pay down the debt.
I am happy with the risk/reward and hope they do a fundraiser or pay down debt, I've model valuation for 20%,40%, 60%, 80% dilutions and still make a positive return. . Actually, I consider Card Factory (LON:CARD) market position as a vertically integrated cost leader as very strong and rate the company at a much higher value than the current share price.
As always DYOR,
BSV
I see. Well too much debt for me and they have opened too many shops recently. Also summer is their quite time of the year, they have missed Christmas and Valentines. If they survive until next year they maybe ok. Even before Covid growth has been sluggish. Cards also seem to be out of favour. A good share to hold about 7 years ago but I think too risky now.
A perfectly reasonable view.
BSV
do 'younger' folk do cards anymore?..not convinced about that
Hi Phil, well my younger generation do - They upload a photo, choose the style and wording and/or add their own and Mr Tinternet does the rest.
But you are right they don't plan enough ahead to have one in the house handy for Dad's birthday that the purchased in a physical specialist store (Or even the local supermarket)
Is this an April fool :-)