Multibaggers with 10 Bagger Potential - Creightons - 10 years of growth at an average of 14% is it time to rerate as a growth stock?

30th DEC 2022
Creightons -mitigation of Covid related hygiene Sales
Creightons (LON:CRL) released a half-year result today, demonstrating a return to its traditional growth profile. The company states 'Core sales have increased by GBP8.37m (40.2%) which has substantially replaced the Covid-19 related hygiene sales which were a once-off feature of the previous half-year. Like many company's it has invested in working capital to overcome supplier chain delays.
It is one of a few companies I'd be willing to pay up for the growth. a PE of 20-24 seems closer to fair value.
The company also successfully completed two acquisitions in the period - Emma Hardie and Brodie & Stone - which will further strengthen the underlying branded business and should add substantially to underlying profitability.
Anyway I have updated my forecast. (see below)
Sales Estimate 2022-2026

My valuation model suggests plenty of upsides. (see below)
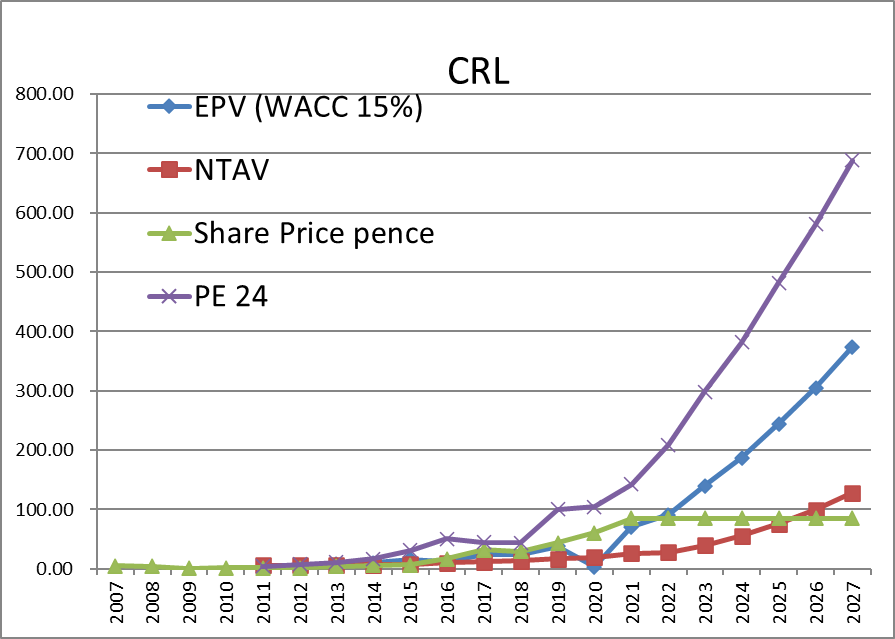
My fair valuation for year-end is close to 202p for year-end 2020 and could be as high as 661p by 2026
As always please DYOR and don't trust vlogs and blogs including this one.
BSV
6th Aug 2021
Creightons -Emma Hardie Acquisition.
Creightons (LON:CRL) released a video on the Emma Hardie acquisition. The link is provided below.
https://bit.ly/CRL_EmmaHardie_acquisition
The main takeaways I took is that,
- Emma Hardie, with cost and market synergies, should see sales of £5M with £1M EBITDA in the near term, with plenty of growth for the future also. It feels like a well-thought acquisition by a team that understands the market and opportunity very well.
- Significant confidence in reach £100M top-line revenue by 2024/25, £30M organic growth, £20M M&A, and margins to improve with top-line growth.
Without knowing the specifics of the Emma Hardie business it is difficult to know if a fair price is paid. I am assured, Creightons (LON:CRL) has brought a business with excellent growth, high margins, and access to new distributions channels, with Creightons (LON:CRL) have the resources to make the most of the opportunities available.
As always DYOR, watch the video and comes to your own conclusion.
BSV
21st JUL 2021
Creightons - 10 years of growth at an average of 14% is it time to rerate as a growth stock?
Creightons (LON:CRL) hit a year low of 29p in Mar 2020 can Creightons (LON:CRL) 10-bag again? (lowest buy 30p, additional buy 57p). (I hold a long position).
The Company release full-year results which made excellent reading, even with Covid-19 and Brexit related costs and impact. https://www.stockopedia.com/sh....
The Result highlights include.
- Revenue increased by 28.9% to £61.6m (2020: £47.8m).
- Operating profit increased by 43.7% to £5.4m (2020: £3.8m).
- Operating profit margin of 8.8% (2020: 7.9%).
The Company will present results on the 28th of July. To register for the presentation please follow the link: https://bit.ly/CRL_FY21_results_webinar28721
A significant part of the increase in growth was driven by Hygiene Related product delivered sales with sales of £14.6m. Some of this will not be repeatable for 2022. Expecting limited growth for 2022 and margins to improve as £1..6M covid costs are likely not to be repeated, I rate this as one of the best growth stocks in the market, deserving a much higher rating.
Sales Estimate 2022-2026

My valuation model suggests plenty of upsides. (see below)
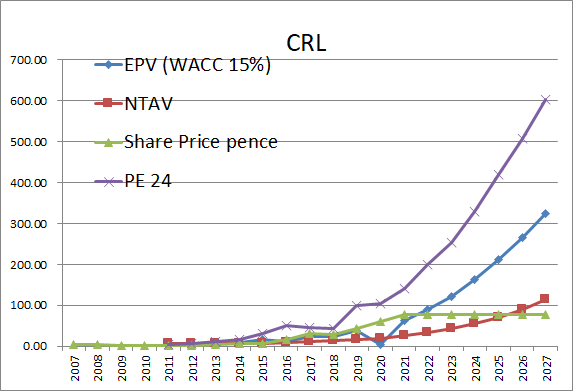
A PE ratio of 20-24 seems close to fair value for a company achieving consistent growth over 11 years.
My fair valuation for year-end is close to 140p for 2021 and could be as high as 570p by 2026
As always please DYOR and don't trust vlogs and blogs including this one.
BSV
4th Sept 2020
Creightons (LON:CRL) has already been a 10 bagger rising from 2p in 2013. After 10 years of continuous growth (14% Average), the company still appears attractive by a number of metrics.
Creightons (LON:CRL) hit a year low of 29p in Mar 2020 can Creightons (LON:CRL) 10-bag again? (lowest buy 30p, additional buy 57p). (I hold a long position).
After yesterday's results presentation, I am optimistic for growth to continue and the share to re-rate.
The reasons I continue to add to my position;
- I'm a big fan of Global Marketing Director/Deputy MD, Pippa Clark , and her knowledge of the market. She knows how to drive sales growth.
- I'm a big fan of Bernard Johnson and his concern for all stakeholders in the business
- Its a small company with a massive market opportunity
- response to covid-19 was excellent
- 10 years of 14% average growth
- margin expansion
- strong balance sheet
The company's long overdue a re-rating to a growth stock.
10 years of growth
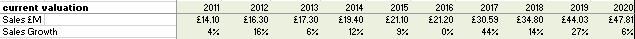
Sales Estimate 2021-2025

With 2021 PE at 10, and PEG of 0.3 my valuation model suggests plenty of upsides. (see below)
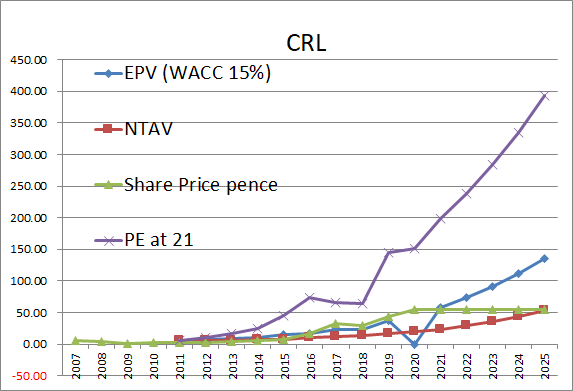
A PE ratio of 21 seems close to fair value for a company achieving consistent growth over 10 years.
My fair valuation for year-end is close to 150p for 2021 and could be as high as 440p by 2025
As always please DYOR. ( Remember I only post these as it benefits me socially and hopefully economically).
BSV
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
34 comments
I updated the forecast on half-year results
'Creightons -mitigation of Covid related hygiene Sales'
2022 fair value estimated at 202p.
As always DYOR.
BSV
I think there is a point to be made here about the EH acquisition….if I was the seller I’d be delighted at the metrics of the deal…as buyers Creightons (LON:CRL) are having to do some serious post purchase furniture rearranging to justify the price
I’d be inclined to give Creighton’s mgt the benefit of the doubt…but I’m more inclined to congratulate the vendors on doing a great deal without needing synergies to make it great for them
I’m an ex holder of Creightons (LON:CRL) & have a high regard for them BTW
Bernard Johnson feels that there is value in the acquisition, and that they have managed to outmanoeuvre their competitors in getting the deal done, and I am prepared to give him the benefit of the doubt, but there is a risk that the acquisition of Emma Hardie has set a precedent for the price that they are prepared to pay.
Eamon Murphy does to fill me with as much confidence tough. In the video on the previous day they set out their stall in terms of acquisition expectations, but then the following day they have completed a deal that is not in the valuation range that they outlined - surely he should have set the groundwork in the results presentation. To then justify the price based upon the expected integration benefits does not feel correct.
It will be interesting to see how long Barry Cook remains with Creightons (LON:CRL) I would expect him to leave in a couple of years once the earn out part of his deal is complete.
Hopefully the next acquisition that Creightons (LON:CRL) do will be at a better valuation.
Beermonster,
I think you are a bit harsh with your comments. I watched the initial presentation again AFTER the acqusition and I came away satisfied that they didn't mislead us. Bernard does state clearly that the 5x EBITDA max that they will pay for acqs can only be confirmed AFTER the synergies have been realised which I think is fair.
We will know within a year how well this acq has been and whether they did pay too high a price. I am confident that they have at least paid a good price for a good business.
@MGinvestor
The acquisition of Emma Hardie has certainly lit a fire under the share price. I don't know how the coming year will play out, but I have met Bernard Johnson and the management team who in my view are very capable and despite what appears to be the full price paid, I would not bet against them making a success of Emma Hardie.
I have been a holder of the shares for sometime and found the recent PIWorld presentation of the rationale behind the acquisition convincing. I need to crunch the numbers, but a forward PE of 15/16 looks more than reasonable for a company that is performing well, with competent management. To paraphrase Warren Buffet the return on retained earnings is an important factor in determining the the quality of a company's management. Having spent £5m of retained earnings, the team at Creightons have the opportunity to impress, fingers crossed they will do so.
released a video on the Emma Hardie acquisition. The link is provided below.
https://bit.ly/CRL_EmmaHardie_acquisition
The main takeaways I took is that,
As always DYOR, watch the video and comes to your own conclusion.
BSV
Creightons (LON:CRL) released a video on the Emma Hardie acquisition. The link is provided below.
https://bit.ly/CRL_EmmaHardie_acquisition
The main takeaways I took is that,
As always DYOR, watch the video and comes to your own conclusion.
BSV
Creightons (LON:CRL) released a video on the Emma Hardie acquisition. The link is provided below.
https://bit.ly/CRL_EmmaHardie_acquisition
The main takeaways I took is that,
As always DYOR, watch the video and comes to your own conclusion.
BSV
I was really impressed with the report in Creightons (LON:CRL) and the acquisition of Emma Hardie provided added interest as it is a business I am aware of. I have just watched the video on PI World about the acquisition.
Am I missing something? Creightons (LON:CRL) have paid £6.5m for a business that made a £40k net profit and £200k EBITDA. Their justification is what they may be able to do with it.
The deputy MD is their Sales and Marketing director. She chatted on with buzz word laden chat that was far from convincing.
My worry is market positioning. Creightons (LON:CRL) are a mass market company looking to buy their way in to the premium brand space. They believe they can expand Emma Hardie by using their existing sales network and also their in house manufacturing. Their is a big risk hear of damaging that 'premium' brand.
Emma Hardie simply has not performed. Yet Barry Cooke the MD has been kept on as MD. That doesn't really make much sense to me either.
To me it seems like they have paid well over the odds and the acquisition is high risk in terms of integration.
I like Creightons (LON:CRL) in terms of revenue growth, EPS growth and ROC.
However, this acquisition concerns me. Am I missing something?
Agree. I wasn’t impressed with Barry Cooke’s responses. He came across as someone who’s run out of ideas and didn’t know what to do next.
The other thing I didn’t like was him saying, constantly “we need a partner”. Newsflash Barry, Creightons aren’t a partner, they’re the boss, and you’re now an employee not an owner.
Certainly an acquisition that has a lot to prove and will be a benchmark for us to judge their growth and expansion plans against.
He's just sold his business for £6m, and received a decent stake in £CRL. respect to the man.
BSV
Price now 105p, possible I get to my 140p end of year price target.
BSV
Creightons (LON:CRL) released a video for its new acquisition. Link https://bit.ly/CRL_EmmaHardie_acquisition
The main takeaway I took is that;
As always DYOR, watch the video and comes to your own conclusion.
BSV
released a video on the Emma Hardie acquisition. The link is provided below.
https://bit.ly/CRL_EmmaHardie_acquisition
The main takeaways I took is that,
As always DYOR, watch the video and comes to your own conclusion.
Interesting acquisition announced. Anyone have thoughts good/bad/meh.
Personally I’m not sure there’s enough information for me to come to a firm conclusion. I’ve decided to trust the management who I think are excellent and done a cracking job over the last couple of years - this will be a good test of that faith.
Edit: looking at the Emma Hardie website, it’s certainly premium. Could be some very good gross margins and a decent addition to the bottom line if they’re able to grow this brand. More execution risk than I expected, they’re going to be out their comfort zone here for sure. Doesn’t mean they won’t rise to the challenge though.
As you say, not much info given. Not a huge bite in the context of the rest of the Creightons‘ business. At face value it looks earnings dilutive (paying £6.4m in cash and shares for about £50k PBIT) in the first instance so it depends what the business adds by way of product, markets and personnel as to whether it’s a good deal or not. Creightons (LON:CRL) have a pretty good acquisitions track record so happy to give them the benefit of the doubt.
https://www.investegate.co.uk/...
Gus.
It seems margins will drop straight to the bottom line. I guess this is the first of the £12M acquisition eluded to in the recent presentation. if this all leads to £100M revenues in 2024 as suggested by the presentation I hope for a great outcome for the share price.
I am pretty positive about the management team adding the right acquisitions to the £CRL.
BSV
It's a relatively low margin consumer defensive. I wish you well in your optimism of P/E 24. At 80p PE is 13.8, I see no reason why it shouldn't be 15 or 16, so I'm looking for a price in the next few weeks of 85 - 95p. I'd be delighted if they could get to a quid but, personally, I can't see that before the next interims, and maybe not after them as they've not got some pretty tough comparatives,. Having said that, the £6m cash in the bank goes a long way to supporting the £1 price target as that represents, I think, around 8p per share raw cash? (appreciate help on the maths with that, I'm an idiot and just did £6m / 73 million shares in issue - I'm sure sharper minds will tell me why this is wrong and I'm happy to be schooled :) )
What price are you basing your 10x on? My first purchase was 20p so I reckon I could be looking at a few years yet for a 10x with a P/E of 15.
Oh, off topic, I like your bio. One thing I would say though, physics says very little at the macro level about psychology :) Trying to see order in chaos leads to madness, but I guess if you treat it like weather forecasting there might be some patterns emerge one can rely on.
There is order in Chaos, so hopefully, no madness is expected. The share market is no more complicated than a random walk weighted up or down by economics and sentiment.
BSV
JM Keynes thought something similar at the start too :)
The 10 bagger comes from the share price moving from 30p (2020) to 300p (hopefully in 2024). I value the £CRLmuch high than the current share price personally and hope the market will catch up sooner rather than later.
The company in its Sept-2020 presentation, suggests it is targeting £100M sales by Mar-2025, in the same production footprint. So I expect continues top-line growth and margins to improve way past the companies own internal forecast. Presentation is provided below.
;ab_channel=PIWORLDMany views make a market.
BSV
I'm not doubting their growth, and I have a decent sized position myself. I just don't think your expectations for the earnings multiple of an unexciting stock is realistic. I do think we'll get to £3 here, but not in 2025.
At £100m sales, EPS is going to be around 12p I reckon. P/E of 15 looking at £1.80. Not to be sneezed at and would represent a 9x from my first purchase at 20p in March 2018. I presume that £100m is the core company organic sales growth without acquistions? Of course, as they throw off cash they might get acquisitive and actually achieve sales of £120m+. I think they have a really strong management team and significantly beating their expectations is definitely a possibility though that might involve dilution and start making their balance sheet harder to understand.
I have sold out once here at 60p and bought back below 50p, but that was a mistake and I got lucky with being able to get back in so cheaply. These are now in the "hold forever" category - way too much potential upside to risk missing out.
Hi IPJ,
It looks like your doing a linear extraction of the future.
We know the company is looking to automate production and grow the top line without adding additional production heads. So I expect gross and net margins to continue to improve. Historic numbers and trends look like they will continue.
2018 - Net margin 4.86%
2019 - net margins 6.52%
2020 net margins 7.43%
2021 net margins 8.39%.
As always DYOR.
BSV
Yeah, at some point margins will be maximised. 8% - 10% seems realistic in the medium term for a manufacturer of consumer defensives with limited brand power.
I think we're all agreed there's a lot to love, it'll be interesting to watch it play out :)
Well, typically consumer defensive has operating margins from 10%-38%. My expectation is that Creightons (LON:CRL) will get to net margins in the high teens at some point.
BSV
Yeah, sorry, should've been more clear. I was talking about gross margins. Anything over 10% would be a stellar performance.
I might be wrong here, as it's a while since I've watched any of the presentations, but I thought Creightons (LON:CRL) said they are aiming for £100m sales including the sales added from a 'small acquisition'.
I'm not yet convinced by their plan to buy a brand and build it up, as they appear to be much better at creating new own brand and contract products than they are at marketing them. IMO, their direct to consumer sales are unimpressive, and their website and social media presence are currently pretty dismal too. I initially had doubts about the planned merger with Innovaderma (LON:IDP) , as I thought IDP's accounting in their results was far too racy, although I warmed to the merger idea as Innovaderma (LON:IDP) appeared to be considerably better at marketing than Creightons (LON:CRL), and CRL's manufacturing facility should lower costs for IDP. However, Innovaderma (LON:IDP) rebuffed the approach anyway...
Despite my reservations expressed above about Creightons (LON:CRL) buying a brand and building it, the shares remain a long term conviction hold for me, as I'm impressed by the turnaround and subsequent long period of sales and earnings growth. I'm also impressed by Bernard Johnson and Pippa Clark, and the way in which the team have responded to Covid-19.
Marketing is a muscle that can be developed.
Pippa seems to understand the product market, getting her some support in reaching customers shouldn't be too difficult and I'm sure this part of the business will see investment going forward. I mean, who buys soap from the manufacturers website anyway