Multibagging gold miners: AAZ and Petropavlovsk

The gold price continues to look strong. Central banks have been gobbling up the yellow metal but all the while supply is dwindling.
In fact the World Gold Council reports that central banks have bought 374 tonnes of gold this year alone – a post-war record. Central bank demand is just one part of the puzzle though.
We explored other attractive gold price dynamics here but there is unfinished business. Somewhere out there is probably a well-placed, healthy, profitable gold miner offering material upside for shareholders. I want to find that stock.
It looks like it’s getting harder to find new reserves of the yellow metal just as demand has ramped up. Despite increases in exploration budgets, no major discoveries have been made in almost a decade.
This slide from a recent Barrick Gold presentation shows a marked decline in major gold discoveries:
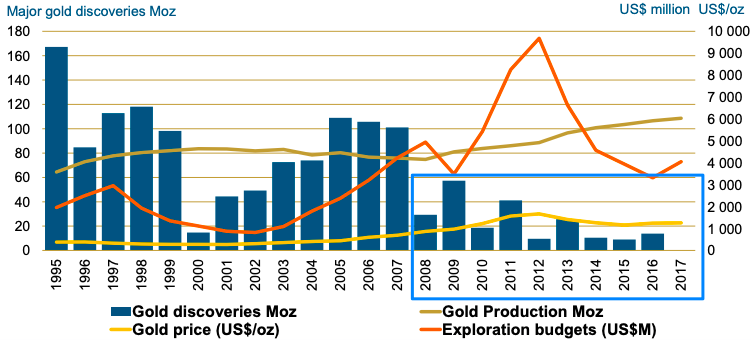
The world might strike gold once again, but the fact remains we have built up a decade or so of low supply. Another dynamic that points towards the price of gold rising.
Gold miners have been increasing production despite the dearth of discoveries, meaning that they are eating into their own reserves. Forecasts suggest supply is going to shrink substantially over the next decade - so those that can continue to produce are well placed to grow profits.
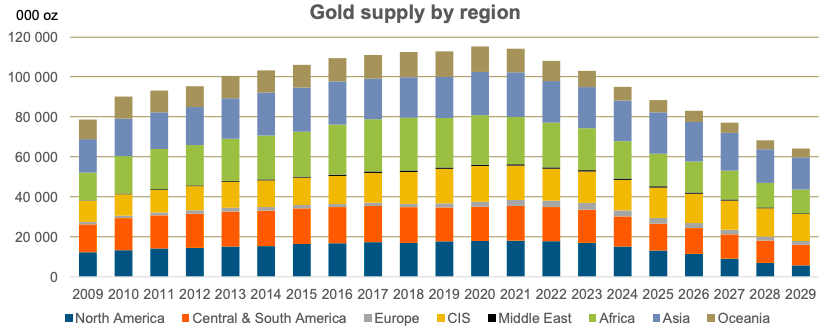
Below I take a look at two cheap gold miners that might fit this profile: Anglo Asian Mining (LON:AAZ) and Petropavlovsk (LON:POG) .
There’s a lot to cover, and I’ve still only just scratched the surface of what’s happening at Petropavlovsk in particular. There are other names to consider later, though, including:
- Highland Gold,
- Caledonia Mining, and
- Shanta Gold
There may be some I’ve missed off the list. If you think of any just say and I’ll make a note.
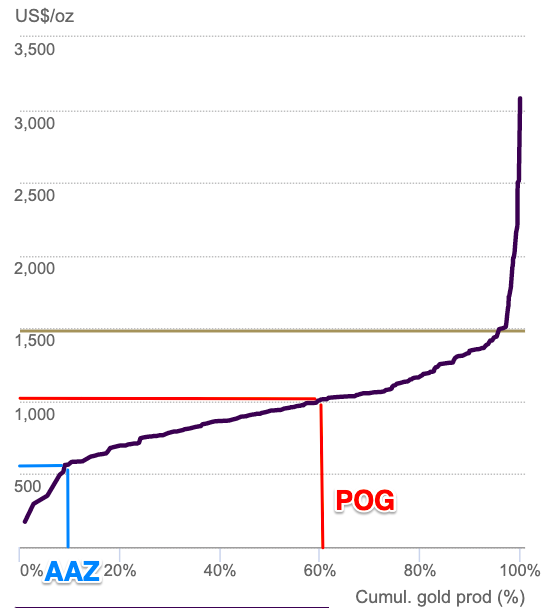
I’ll focus on AAZ and POG for now. This chart shows the all-in sustaining cost (AISC) curve of the global gold industry. I’ve pointed to where each miner figures (roughly) on that curve.
Note that the attractive part of POG has less to do with today’s AISC and more to do with future potential. AAZ, on the other hand, clearly has much more immediate economic attractions.
Anglo Asian Metals (LON:AAZ)
- Share price: 141.2p
- Market cap: £156m
- Forecast revenue: $106m / £86m
- Production ounces: 81,399
- All-in sustaining cost: $591
(I hold)
AAZ is a highly cash-generative gold miner with four mines in Azerbaijan. Here are the bull points:
- A low all-in sustaining cost makes for high levels of cash generation,
- This cash generation has allowed AAZ to build a strong, debt-free balance sheet,
- It is piling up cash and paying strong dividends,
- It is well placed for acquisitions or new discoveries at existing sites, and
- It appears to be cheap according to cash flow, earnings, and dividend metrics
As a relative gold novice, I hold AAZ because of its obviously attractive mining economics, safe balance sheet, dividend payments, and cash generation potential. It’s a fairly straightforward pitch.
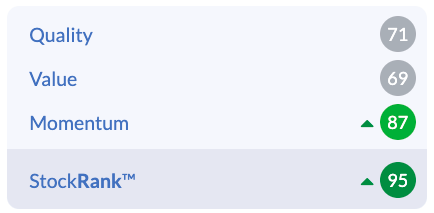
The Ranks love it as well, classing it as a Super Stock based on its attractive spread of Quality, Value and Momentum:
What AAZ needs is to prove more resources. The group is dutifully doing so and the body language is positive, but I will believe it once I see confirmation. Until then, possible disappointment on this front remains a risk.
Exploration opportunities at AAZ’s sites are ongoing and the signals are positive. The group’s recent updates suggest upgrades in the near future. On top of that, AAZ has five “fast-track” production targets at Gedabek and the Ordubad Contract Area.
There is always a risk these do not materialise, but the work sounds promising so far.
Regardless of what happens here, if gold prices hold steady, at its current valuation AAZ could rack up cumulative free cash flow in excess of its market cap in under a decade.
AISC, cash generation, and financial health
The group’s open pit mining sites place it firmly in the lowest-cost quartile, with an all-in sustaining cost of just $591, making for a highly cash generative miner. See the free cash flow yields below.
AAZ | 2014 | 2015 | 2016 | 2017 | 2018 | 2019 |
Operating cash flow per share | 13.3 | 20.5 | 26.3 | 26.3 | 41.3 | 25.9 |
Capex per share | 15.1 | 13.1 | 9.83 | 9.24 | 16 | 8.04 |
Free cash flow per share | -1.8 | 7.4 | 16.47 | 17.06 | 25.3 | 17.86 |
Share price | 137 | 137 | 137 | 137 | 137 | 137 |
Free cash flow yield | -1.31% | 5.40% | 12.02% | 12.45% | 18.47% | 13.04% |
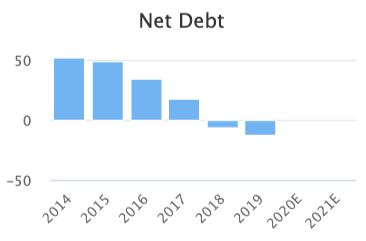
This has enabled AAZ to power its balance sheet from a net debt position of $52.4m in 2014 to a net cash position of $21.2m at end-December 2019. This will likely continue to grow even after dividend payments and capital expenditures over the next few years.
Trading and outlook
AAZ has quoted a combined mine life to at least 2024 - a bit close for comfort. The miner has already identified mineable extensions to existing sites though. This is how management sees that timetable over the next few years:
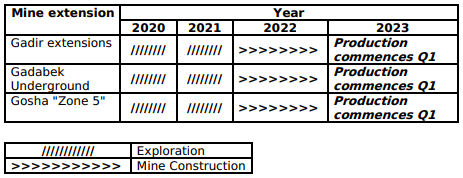
It sounds like the Gedabek and Ordubad Contract Areas have bigger “system” potential as well, although the scale of this has yet to be confirmed.
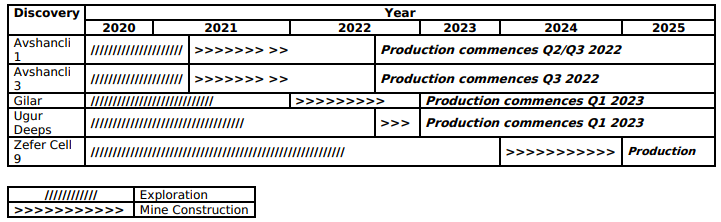
In addition, there are five fast track exploration targets:
- Avshancli 1 and Avshancli 3 (Gedabek Contract Area);
- Gilar – (Gedabek Contract Area);
- Zefer Cell 9 – (Gedabek); and
- Ugur Deeps – (Ugur open pit mine).
This fast-track plan sees Avshancli 1 and 3 potentially coming onstream in the second half of 2022 with the last one, Zefer, potentially onstream by the beginning of 2025.
Red flags
AAZ operates under a Production Sharing Agreement (PSA) with the government of Azerbaijan, which it periodically has to renegotiate. Similar contracts have been used in the development of Azerbaijan’s oil sector in cooperation with oil majors, such as BP.
Anglo Asian finances the operations and the government receives cash payments after certain expenses. AAZ is entitled to a maximum of 75% of sales proceeds. Thereafter, the remaining proceeds are allocated 51% to MENR and 49% to Anglo Asian. I think regulatory risk is a concern.
In the 2020 CEO Letter to Shareholders, it says:
...in August 2019 that the Government of Azerbaijan had announced it had appointed advisors with regard to a possible transaction with Anglo Asian Mining. There have been no significant subsequent events requiring further announcements by us. Nevertheless, I can assure shareholders that it is the Company's understanding that the Government of Azerbaijan has no intention to nationalise, purchase or otherwise take control of Anglo Asian Mining or its assets in Azerbaijan.
Everything I’ve read in trading updates and financial statements indicates AAZ has a strong relationship with the government, at least. Beyond that there’s not much I can add to the matter besides flagging it up for others to make a decision on.
As you might expect of a small cap Azerbaijani gold miner, the group’s Major Shareholders is populated by individual investors and slightly lacking in classy institutional names. Is this a corporate governance risk or an opportunity for nimble retail investors? I’d argue it’s a bit of both. Some shareholder churn at some point could act as a nice tailwind if there is institutional interest out there - perhaps in the event of confirmed new reserves.
But then of course, there is also the risk that new discoveries fail to materialise - in which case AAZ will be compelled to seek acquisitions.
A final point: AAZ qualifies for not one but two short screens:
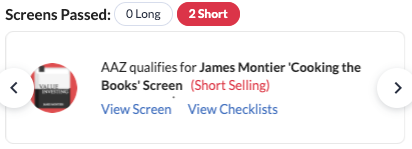
The most notable point flagged here that I can see is that receivables are increasing in proportion to sales. This is a fair comment - you can see the increasing receivables on AAZ’s balance sheet. It’s a big jump:
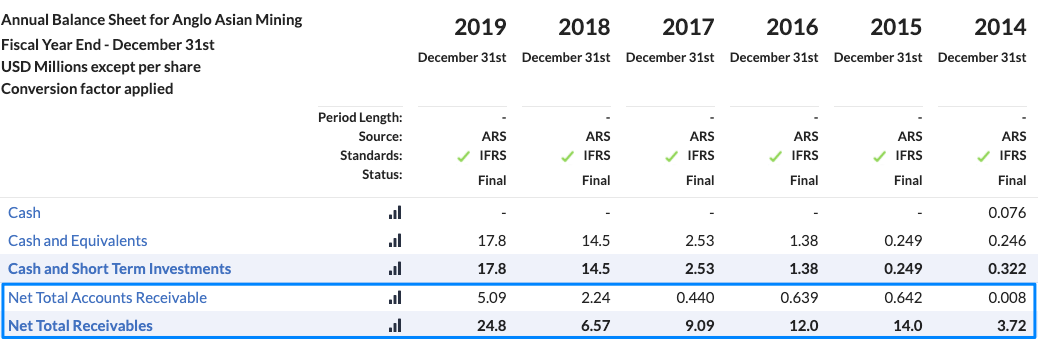
The bulk of this (c$18.5m) is gold held due to the government of Azerbaijan. An offsetting balance has been recorded under Trade Payables. I’d hope this unwinds, but again, another example of the government’s presence.
Conclusion and valuation
To recap the dangers, I see:
- Regulatory risk,
- Scope for mine exploration disappointment, and
- A recent increase in receivables as a proportion of revenue
… But I also think there is a reasonable margin of safety built into the share price at 7.4 times forecast earnings.
An AISC of $591/oz puts the company in the lowest quartile of the gold mining industry’s cost curve. At its present rate of cash generation, I reckon AAZ will generate its current enterprise value in free cash flow over the next 10 years (although this assumes successful mine life extensions).
What we know for sure is that AAZ has a strong balance sheet and highly cash generative operating characteristics.
While we wait for announcements, the company has committed to pay out 25% of free cash flow to shareholders. Brokers aren’t making forecast dividend per share estimates right now, so this income potential might not be priced in. The FY19 dividend was 8c (around 5%) so it’s a useful amount.
There’s compelling valuation and margin of safety here in my view - the only question is if there’s an even better deal out there somewhere.
Petropavlovsk (LON:POG)
- Share price: 25.19p
- Market cap: £831.5m
- Forecast revenue: $706m
- Production ounces: 514,000
- All-in sustaining cost: $1,020
Perhaps Petropavlovsk is that opportunity?
If you look beyond the name and read up on what it’s been building, Petropavlovsk looks like less of an old world miner and more of a high tech innovator well placed to serve the wider mining community with a key infrastructure asset...
Whereas AAZ’s share price has gone nowhere for a while, POG has been on an absolute tear recently. Here it is against a basket of other gold stocks over the past two years.
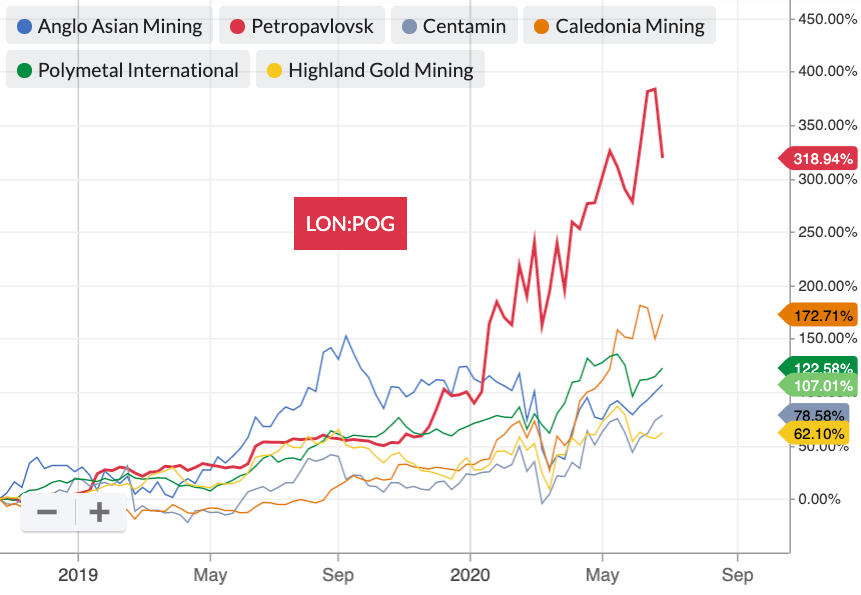
I’m approaching this company anew and there are a few moving parts. I can’t cover it all in one pass but there is a clear company-specific share price catalyst worth focusing on: the group’s POX Hub. This is a high tech, potentially transformational new plant.
That certainly seems to be what Uzhuralzoloto Group of Companies ("UGC") seems to think. UGC is a leading privately-owned Russian gold producer with a bevy of mining and development assets across the region. It has taken a c25% stake in POG and the group’s CFO has joined the board. Clearly UGC sees strategic value here.
The world’s largest sovereign wealth fund, Norges Bank, has also taken a c4% stake.
The POX opportunity
POG’s flagship asset - the Pressure Oxidation (POX) Hub - enables the processing of refractory reserves and resources. Ground ore is passed through a flotation circuit and out the other end comes high-grade concentrate.
Pressure oxidation technology is the most efficient way of processing refractory gold ore - and now POG has one of only two of these centres in Russia. This means that it can unlock value in not just its own c.5.31 million ounces of refractory reserves, but it can also take on 3rd party refractory material as well.
The group has four autoclave vessels operational with another two that can be brought onstream. I don’t really know what autoclave vessels are, but I take this to mean POG can expand the plant’s capacity by 50% at relatively short notice.
In FY19 alone, POX contributed 35% of total gold production. In 2020, the POX Hub is expected to produce 370-430koz of gold - nearly as much as its three main mines combined. Processing costs are expected to be below the level of 2019 too, due to higher throughput and operational improvements.
In Q1 of this financial year POG reported a 73% increase in gold produced to 186.2koz (Q1 2019: 107.7koz), of which 115.4koz (62%) came from the POX Hub - so it looks on course to hit the upper end or even exceed this target this year.
Trading and outlook
That aside, there is a lot of newsflow, major holdings announcements, and share price action at POG. It’s a hot stock with a lot going on. Is that a good or a bad thing? I don’t know yet.
The group’s shares were down 19% yesterday - I need to be quite sure of my reasoning (or quite small in my position sizing) if I am to handle that type of volatility.
Its recent FY19 results give a sense of strong operational progress obscured by legacy issues. Group revenue was up some 48% to $741.6m and underlying EBITDA jumped up 45% to $264.8m.
If that underlying figure can be trusted, that puts POG on an historic EV/EBITDA of just 5.6x even after recent strength.
The group’s Financial Summary gives a good sense of its evolving operating profile. There’s a lot happening between the revenue and profit lines - but when that’s the case it can be hard to calculate true underlying value, which creates opportunities.
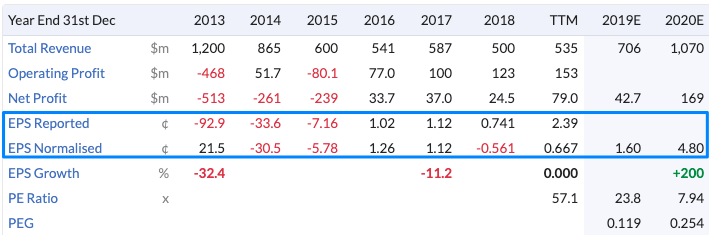
It’s messy, but underneath it all gold production is up, gold sales are up, the gold price is up, all-in sustaining costs are down, and POX offers substantial potential.
Still, a gold miner headquartered in Russia with complicated accounts that is part way through a turnaround is presumably not everyone’s cup of tea.
POX is a clear catalyst
The below table is a very rough first pass at running some numbers. The direction is more important than the detail. I still don’t know POG that well and there are all manner of items left out, so if you’d like to raise any points, be my guest.
What’s most important to me is getting a sense of scale in terms of how much a ramped up POX might change POG’s financials (in conjunction with a strong gold price). I’m aiming for “approximately right and precisely wrong” here.
My assumptions:
- Gold produced for FY20 uses the lower end of the company’s own guidance in its FY19 annual report,
- The FY19 gold price assumes the average gold price for 2019 ($1,392),
- The FY20 gold price assumes the current spot price ($1,771),
- All-in costs remain constant for each mine, with figures sourced from FY19 accounts, and
- POX generates a 10% margin in FY19 and FY20 - this is a shot in the dark but hopefully conservative. The company itself says costs should come down and margins will improve this year.
FY19 | FY20(e) | |
POX | ||
Gold produced (OZ) | 179,500 | 370,000 |
POX Profit (10% margin) | $24,986,400 | $65,527,000 |
Pioneer | ||
Gold produced (OZ) | 120400 | 130000 |
Pioneer profit | -$13,364,400 | $34,840,000 |
Albyn | ||
Gold produced (OZ) | 170900 | 145000 |
Albyn profit | $111,597,700 | $149,640,000 |
Malomir | ||
Gold produced (OZ) | 180300 | 155000 |
Malomir profit | $55,352,100 | $106,330,000 |
Underlying profit | $178,571,800 | $356,337,000 |
If I’m even in the right ballpark then this does look like a substantial long term opportunity given the region’s substantial refractory reserves. I’m not attaching a great deal of weight to the precision of these figures at present, but directionally it’s enough to pique my interest.
Conclusion and valuation
Two gold miners but two very different investment propositions.
With AAZ we have a proven profitable miner that needs to extend its mine life. It is exploring, the prospects are good, and in the meantime it is a cash-generative dividend-payer with a cash-backed balance sheet and a cheap share price.
POG, on the other hand, is much more a case of what might be. This might be its defining year, with POX ramping up to something like full production.
A significant rerating is underway. Is there more to come? I think it’s certainly worth further investigation. The group is targeting between 620koz and 720koz of gold production for FY20 - that’s at least 20% more year-on-year, with an increase in margins quite possible.
Meanwhile, Russia’s significant refractory resource base accounts for approximately 40% of total resources, so POX is a substantial opportunity for many years to come.
The company is still working through financial instruments it put in place years ago when conditions were harder, including forward sales, hedges, convertible notes and a $500m bond. If it can pull off reducing capex and greater production, with the gold price as it is, POG could strengthen its balance sheet in the years ahead in much the same way AAZ has done in the past. That can be a powerful share price driver.
That’s me for now, but there’s more out there. Caledonia Mining, Highland Gold, and Shanta Gold to name a few. I like AAZ, and POG sounds exciting - but perhaps the best opportunity is in that final three?
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

48 comments
looks interesting
Anglo Asian Mining plc / Ticker: AAZ / Index: AIM / Sector: Mining
21 July 2020
Anglo Asian Mining PLC
Formation of a Joint Venture with Conroy Gold and Natural Resources PLC
to acquire up to a 55 per cent. interest in the Longford Down Massif gold project in Ireland
Initial 17.5 per cent. interest to be earned by Anglo Asian investing €2 million in further exploration, with its interest increasing progressively to 55 per cent., by developing
the Clontibret gold deposit to mine construction-ready status
Anglo Asian awarded warrants over 325,000 Ordinary Shares in Conroy Gold and Natural Resources PLC, with an additional 1,625,000 warrants to be awarded on completion of the Joint Venture Agreement
Anglo Asian Mining PLC ("Anglo Asian" or the "Company"), the AIM listed gold, copper and silver producer focused in Azerbaijan, is pleased to announce that it has entered into a non-binding Heads of Terms Agreement ("HoT") with Conroy Gold and Natural Resources PLC ("Conroy Gold") for a proposed joint venture. Anglo Asian will acquire, by way of the joint venture, up to a 55 per cent. interest in the Longford Down Massif gold project (the "Project") in Ireland currently wholly-owned by Conroy Gold in exchange for committing to meet certain expenditures.
Anglo Asian has also been awarded warrants to acquire 325,000 Ordinary Shares in Conroy Gold which are exercisable immediately. Anglo Asian will be awarded an additional 1,625,000 warrants to acquire Ordinary Shares in Conroy Gold upon completion of the joint venture agreement. The additional warrants will become exercisable at certain milestones as Anglo Asian invests funds into the joint venture as set out below. The total of 1,950,000 warrants represent 7.44 per cent. of the current issued share capital of Conroy Gold.
Note that all references to "$" are to United States dollars, "£" and "pence" are references to the United Kingdom pound sterling and "€" are references to the Euro.
Excellent write up, the all-in cost of $591/oz and strength of gold price makes Anglo Asian AAZ very attractive.
Gold is set to continue its strength as the economic situation deteriorates and more fiscal stimulus is needed.
Very true Elias Jones: "Gold is set to continue its strength as the economic situation deteriorates and more fiscal stimulus is needed."
Moreover I should add that if we have to revert back to a pre-1971 system (AKA The Gold Standard) then gold remonitised would be around $32,392 /toz [i.e. circa 18 times its current spot price! Source: https://www.usdebtclock.org/gold-precious-metals.html]
Dachsis Capital (Robin), for some reason, on a separate thread, a poster suggested the LF Ruffer Gold Fund. I point this out as an investor in Pan African Resources (LON:PAF). As the chart below shows, it now holds around 6% of Pan African’s equity. But the point I’m making is that it does seem to have its finger on the pulse, at least as far as Pan African is concerned. And its Q1 2020 figures are impressive - outpacing the FTSE Gold Mines Total Return Index.
Frankly, I prefer to invest directly in Gold miners and so I hold no position in the fund but it's certainly an interesting proposition.
Not Gold but Nickel...........
Micro Cap Pick and in my view has a great potential for rewarding returns with the SP sitting at a very low level.
Amur Minerals (AMC) - Nickel Mining Exploration Company with the licence to mine one of the world's largest Nickel deposits, 1.5 Million Tonne of Nickel @ approx 13,000 USD per Tonne)
There is a huge post Covid 19 move away from traditional fueled Vehicles to EV.
Some further information regards the growing demand for EV.
https://seekingalpha.com/article/4269216-battery-shortages-already-problem-electric-car-waiting-lists-becoming-norm?app=1&isDirectRoadblock=true
This has cased a huge increase in demand for Nickel.....
This has caused an ever increasing Nickel price, breaching the 13,000USD per tonne mark and a Chart with looks encouraging for further rise.
See below article for more background behind this share and it's ever growing potential.
Amur Minerals - (LON:AMC) - The Start of the Final Rise! (Nickel Mining)
https://www.stockopedia.com/content/amur-minerals-lon-amc-the-start-of-the-final-rise-nickel-mining-zak-mir-update-631283?order=createdAt&sort=desc&mode=threaded
There are a few more before this latest one if interested....
Again DYOR and GLA
Gold and Alchemy can do wild things to men’s minds and share prices. Gold was discovered in 1849 in California and Amur regions of Russia. First gave rise to the Wild West and the last to Wild East. POX is likened to High Technology Alchemy.
English and Directors have had many Board room problems and made some interesting financial decisions including a 19.7 for 1 rights issue.
Scaling a graph of the wild price action is near impossible hence the table below to give an idea of the wild gyrations. (table created using new courier type face for spacing)
Year___Open______High_________Low______Close_____¦__Avg Volume__Median Price
‘
2008___1,300.00___1,541.00___160.00______404.00__¦_____996,965______1,162.00
2009_____394.00___1,343.00___345.00____1,110.00__¦_____968,661________635.00
2010___1,054.00___1,370.00___834.00____1,081.00__¦___1,306,297______1,106.00
2011___1,143.00___1,170.00___538.00______678.50__¦___1,282,717________786.25
2012_____629.50_____826.50___317.10______368.90__¦_____577,653________436.50
2013_____369.70_____417.40____54.00_______72.75__¦_____631,212________104.13
2014______77.75______98.25_____6.00_______13.00__¦_____339,886_________40.25
2015______13.25______18.50_____4.21________5.48__¦__54,639,226__________6.09
2016_______6.30______15.12_____5.92________6.91__¦_128,523,344__________7.25
2017_______6.98_______9.05_____5.80________8.26__¦___9,320,772__________7.40
2018_______7.70_______8.75_____5.15________6.86__¦___9,320,772__________6.90
2019_______6.75______13.40_____6.61_______12.80__¦__13,577,613__________9.62
2020______12.30______34.55____12.30_______30.90__¦___2,843,310_________21.73
‘
Company traded from 2002 my tracking is from 2006. 2020 ended last weekend in June.
Wild East of Russia encompasses enough action to embarrass Hollywood
Correction to avg volume column in table
Gold is sitting steady above $1800/toz today...the December price is $1840/toz. All very bullish for the precious metal miners!!!
This is a great article Ben, or in fact, a great series of articles!
I am really looking forward to your write up on Highland Gold (HGM), as I currently hold, and am considering topping up but am in the process of doubling down on my research.
A second stock that I like is AAU, I have held this for a few years. It is a micro cap, but I have always been impressed with how the managemet reapeatedly over acheive and under promise on their updates. This was especially so during the early plant development phases. They have a faor bit of debt, which I think may be the reason why their stock rank is being dragged down.
I'd be interested to hear your thoughts on AAU if you havethe time to add a cheeky micro cap into your analysis?
Thanks, but it's Jack actually - Ben sends his regards though ;)
I've definitely seen a few voices put forward Highland by now. Serabi and PAF too, although I did take a quick look at PAF in a previous article.
Pure Gold has been put forward. Its StockReport looks dire, but the momentum is strong, so clearly something's up. Requires more reading.
Shanta Gold and Hummingbird too... Plenty to be getting on with! I'll aim for another article next week
Hi Jack. Brilliant, as a Highland Gold Mining (LON:HGM) owner, I too look forward to next weeks article!
Pure Gold Mining is my biggest portfolio position, followed by Ross Beaty's Equinox Gold. I think both have UK listings. Pure Gold mining looks like a potentially very exciting situation and Ross Beatty of Equinox Gold is a reliable multi company mining entrepreneur. CRUX Investor just published an interview with the CEO of PUR on YouTube and a week or so ago with Ross Beatty. If you can't get access to the CEO of mid sized gold companies, or don't understand the geology, the NYSE listed royalty and streaming companies are the safest bet. I agree with the comments below that the risk of the Russian market are overstated and I am happy to allocate money to Russian mining companies.
Several miners mentioned by posters are based in Russia. Comments about these companies are often prefaced by a warning (Understandably). The warning relates to jurisdictional risk. So I thought it might be useful to put it into perspective.
In 2020, the World Bank published a survey examining the ease of doing business. It covered some 190 countries and placed Russia in the 28th position. For sure, it may be easier doing business in the UK or Singapore. But Russia scored higher than the Netherlands, Spain or France. From what I can understand, the Russian Government has not expressed any interest in nationalising its Gold mining assets. And the type of cronyism that has beset its oil and gas industry does not seem to be present to the same degree in Gold mining. It’s simply a different animal.
More subjective but very important. Russia does not seem to be beset with the type of anarchy that bedevils miners across the world. Its mines are often in remote and sparsely populated areas where there is little scope for friction with “Community groups”. Contrary to popular mythology, it appears to provide the stability required when making major capex commitments.
Good comment. Also I would like to add that the Russian government has very low levels of debt compared to just about every other country. Unlike the UK they have been 'repairing the roof while the sun was shining'. Moreover their central bank have been accumulating a lot of gold (just like the Chinese in fact) over the last decade. Still lots of deep value to be had in Russia as per its low CAPE ratios.
Has anybody looked at NQ Minerals ( NQMI) that seems to be flying under the radar?They just announced that the purchase of Beaconsfield Gold Mine and that production at their Hellyer mine was up 44% last month. Market cap is just under £30mn so on the surface it looks cheap.
I was disappointed to see the AAZ portion of this article c&p onto the ADVFN thread. That’s very poor form ‘gold finger 1’ whoever you are. I’m sure you are enthusiastic about AAZ and just trying to be helpful but subscribers pay for the privilege of these articles and Stockopedia use them as part of their marketing strategy. You should edit your post on ADVFN and remove all but a ‘fair use’ line or two.
Greatland Gold (LON:GGP) might disagree about no major gold discoveries. This has soared since finding gold in Australia and people are waiting for what many see as the inevitable takeover although I am a little unconvinced about the prices being suggested. Currently about 12p. I have a long history with this having once bought at 0.09p many years ago. No I don't still hold from then....unfortunately....but I did buy at 2.95p in the March lows. Of course this is not a producer yet.
Also a word about a very risky and highly speculative small cap Katoro Gold KAT. https://twitter.com/KatoroGoldplc management are currently on site as the photos from today show. News on a JV may lead to a strong rerate but this is def punting money only imo.
I like the look of PAF; the momentum is strong and they seem to be over their labour troubles.
Centamin (LON:CEY) is my gold stock. StockRank 96. Undramatic company though my investment in it is up over 100%. Productive mine in Egypt with stable relationship with Egyptian government. Interesting exploration licences in Burkana Faso and Cote d'Ivoire.
I think £tsg are worth a look. Low cost russian miner. Pays divi. However some simiar risks re resource life but early reports are v promising. Also operating in a fledgling mining area so opps for growth through acquisition of licences in future.
Agreed. Trans-Siberian Trans-siberian Gold (LON:TSG) is one of my favorite gold miners. They had great success on their exploration front last year when they found a new vein that could be twice the size of the original orebody at Asacha. They’ve spent money this year focusing on drilling it for the new orezone. Also the Rodnikova development project is looking superb.
This is a good article, but one thing to note is that if you think Gold is in/entering a bull market that its actually better to be investing in companies which have HIGHER all in costs....
This may seem counter-intuitive, but consider the following examples gold stocks:-
Stock A: All-in-costs of $500/oz
Stock B: All-in-costs of $1000/oz
Stock C: All-in-costs of $1500/oz
Start price for Gold = $1750
End price for Gold = $2500 (which i think is very achievable in 12-18 months)
Stock A: Profit growth will be 60%
Stock B: Profit growth will be 100%
Stock C: Profit growth will be 300%
So assuming PE's are maintained you'd expect the share price of Stock C to rise 5 times that of Stock A.
Of course if you were expecting a bear market for gold then the opposite would be true and you'd dump Stocks B & C and head for Stock A (if you felt you had to own a Gold stock)
Hi MartinC, which particular Gold miners do you favour in the 'gold bull market' scenario ?
A really useful article - thank you. In terms of others you may look out I would appreciate your views on Serabi please.
Many thanks
POG one of the reasons this is doing well is it currently getting rid of underperforming assets, but how many boardroom disruptions have there been ?
mmol, simply adding to your comments on Pan African Resources (LON:PAF). Yesterday, the company announced an ADR programme for the Over-The-Counter market in the US. That should broaden its shareholder base. As the chart below demonstrates, it’s also worth pointing out that its share price fell sharply from late 2017. As a result, the company was relegated from the MSCI Global Small Cap Index. And so lost its place in some Index tracking funds. Presumably, a rising share price will propel it back into more indices.
In my view, its recovery started when it commissioned its Elikhulu tailings retreatment plant in September 2018. This is low-risk and predictable Gold production. And, of course, low-cost (AISC of US$708 per oz). It was even able to operate during the lockdown (Its surface operations operated at around 70% of normal production during the lockdown).
As you pointed out, it’s based in South Africa so it’s not without risk. However, it does have considerable development opportunities within its current assets. That includes the Egoli project - 1 million oz of Gold measured and inferred. With the prospect of extracting 90,000 oz per annum for ten years. It’s now examining non-dilutive ways of funding the project.
Great article Jack, for those that are interested Edison released a really good report recently about the fundamentals of gold, see here.
I've bought into 4 gold funds in recent months as I really think diversity is important when buying a company that effectively pulls anything out of the ground and I often think fund managers have the inside track rather than us lonely private investors. Funds are split 50/50 with two targeting big boy producers kicking out decent cashflow with little debt and the other two targeting the junior market who are within 1-2 years of production and ripe for M&A activity. I expect I might rotate more towards the juniors in the coming 1/2 years as their share prices are massively lagging current producers.
Even if gold takes a big hit these companies should be kicking out good profits and theres a prospect of the big boys paying income as well with a lot of funds struggling to park cash anywhere at the moment as the usual div players reduce yields.
Phil
Maybe you can help Phil with the names of the 4 gold funds? I am new to sector and as a small cap specialist never felt necessity to be in gold until recently. Been playing it via physical gold ETF so far but am keen to expose myself to income streams from it. I own a few AAZ given the yield prospects but given this article and comments mention 20 different companies that I should be looking at ! the fund route looks attractive. Your further help would be appreciated. I have dipped my toe into BRWM given it owns Barrick and Newmont.
my name is Robin btw
Thanks for another great article Ben. Could I just ask where Trade Payables is shown? I don't see that under the Stock Report anywhere.
Great article. Thanks. I hold three gold mining companies - in order of holding size: Anglo Asian Mining (LON:AAZ), Shanta Gold (LON:SHG) and £HUM
You are down to look at Shanta Gold (LON:SHG), please could you add Hummingbird Resources (LON:HUM) to the list!
Thanks again.
I am wondering if there might be some takeover activity involving the gold minnows.
Amur Minerals (AMC)
Not gold but Nickel mining and in my view a no brainer multi bagger....
See below article
Amur Minerals - (LON:AMC) - The Start of the Final Rise! (Nickel Mining)
https://www.stockopedia.com/content/amur-minerals-lon-amc-the-start-of-the-final-rise-nickel-mining-628718?order=createdAt&sort=desc&mode=threaded
There are a few more before this latest one if interested....
Again DYOR and GLA.
Worth adding: Sprott (SII) are one of the main gold/silver royalty companies so great for gold exposure with lower risks than the miners. They pay a dividend too.
Thank you for turning your laser on AA Z and POG. I have held these in the past but do much better in these other current holdings: Fiore (F), Great Bear Resources (GBR), Franco - Nevada (FNV), ans SSR mining (SSRM).
However my largest gold mining holding is in Sylvania Platinum (SLP) and I cannot understand why this profitable, debt free, dividend paying miner's stock is so undervalued. Can anyone tell me what I am missing, please?
Platinum is correlated to the good times. The "money metals" (Silver & Gold) do well when the proverbial is likely to hit the fan (AKA the bad times).
Here’s a link to the Hardman note https://www.hardmanandco.com/wp-content/uploads/2020/06/Hardman-Research-Anglo-Asian-June-2020.pdf
The other point worth mentioning is that AAZ only has 114m shares in issue. There has been no significant dilution since IPO and at the low point, the CEO lent the company money rather than raise funds in the market. Management ownership accounts for around 40% overall.
My fave has been Ariana (aau) as I believe it has a very strong board and an increasingly good track record. As gold as a sector heats up good board behaviour is going to be increasingly important to us private investors
The Fed is printing money like nobody's business creating a crazy bubble in US stocks. The global impact of corona virus is slowly becoming apparent but the consensus is that it's going to be massive. Back home England has the highest number of covid deaths in Europe and the same government that brought you that is just about to take us into Brexit. Gold is looking increasingly like a safe haven.
My personal favourites are Serabi Gold (LON:SRB) and Trans-siberian Gold (LON:TSG) .
The elephant in the room is of course, covid which I imagine could severely impact the production from a gold mine.
Another fine article Jack, although I am overweight Anglo Asian Mining (LON:AAZ) and therefore, heavily biased. I have a couple of comments.
1. Hardman are forecasting a 10.5c dividend for FY20 which is 6%+ yield depending on fx movements of cable.
2. I really do not see any problems with life of mine. I have read all the mine reports including those from the airborne geological survey which yielded 30+ prospects in the Gedabek contract area - not to mention probable extensions to existing mines. Everything that the company does is JORC compliant, so while the official LoM is relatively short, there really is a lot of gold/copper within the Gedabek contract area. And as for Ordubad, the company anticipate 20-50k gold equivalent ounces to be mined from 2023 onwards. As you have pointed out there is every chance that AAZ are sitting on two major (technical term used by Hardman was giant) systems. There is a very high probability that AAZ will be mining these resources for many years to come, at least until the end of the PSAs (2032+).
3. Personally I believe regulatory risk with the current GoA is low. For example, the government provided the helicopter for the airborne survey. They have also partnered with AAZ to develop the infrastructure around the Gedabek contract area. Plus, the government are focused on attracting external investment into Azerbaijan not scaring it away. I would cite the biggest risk in this area to be regime change which also seems unlikely at this juncture. A bigger risk would be a natural disaster such as an earthquake or mine closure via a local outbreak of Covid-19.
Thanks again for another solid article.
Cheers
Simon
Thanks for that Simon, some great colour on AAZ. I do rate its prospects and think you are likely right wrt LoM, so I'm happy to sit tight and hold. Good to hear your thoughts on regulatory risk too.
I remember that Hardman note being fairly comprehensive - c40 pages long actually. I must track it down again.
Pan African Resources (PAF) is the one I like but, as you've noted, several should bounce substantially on the back of higher gold prices
POG worries me because of the Russian connection - but I can see that Southern Africa (PAF) will concern many investors. Nevertheless PAF looks very well managed and the accounts are clear. Governance also appears good, and there is also a strong focus on local community issues which I take as a positive.
I've tried to do the same profit forecasting calculations re POG as you, Jack - the annual production numbers (oz) and costs are all there in the published data, as well as (importantly) the hedging contracts - which run out half way through this year and will lead to a sharp increase in revenue earned per ounce. The CEO points out in his latest report the "importance" of this point which I took as a clue to how revenues should increase sharply once the hedges expire. Cash generation looks tremendous. On this basis the June 20 year end 2020 profits should be sharply up on the previous year, with considerably more in 2021 when the hedges have run out. And any further increases in the gold price and production levels will only help things further.
I started buying at 10p earlier this year and the shares are now c.18p, so that's a bumper return. But based on the ratios (very, very low PE and PEG), there should be a lot more to go.
.
You should add PAF to your list of other gold stocks to consider. I'm interested in AAZ though not invested in it. I found your write up on very useful.
Main market ALTN is also interesting. The issue that has been holding this company back has been the management's attitude towards small investors and its relatively small production, but the attitude and news flow seems to have changed for the better in the last few months. You might find it an interesting one to research because it has a large resource (not sure how much of it is inferred) and a long mine life. The primary concerns are (1) their ability to increase production over the next few years - they have been buying new plant and equipment to do this and (2) improving management effectiveness and investor communication along the lines we've seen recently. They are in Kazakhstan which might be a concern to some.
Petropavlovsk shares have now risen by close to 300 per cent since January but the management structure is super unstable (multiple board coups!). Their board has been voted out by new major shareholder UGC ... There is better value out there I feel.
I would love to read Jack's appraisal of both CMCL & HGM as I have been monitoring these two shares recently. CMCL has had a turbulent few days so am more cautious but HGM looks more stable. POG & AAZ could both have political questions and maybe another EVZ?
Also, Shanta Gold (Shanta Gold (LON:SHG)), they are a cash flow machine.Trans Siberian Gold (Trans-siberian Gold (LON:TSG)) too.
Anglo Pacific (LON:APF) have an interesting royalty model with some Gold exposure. Worth looking at too.
Hi Ray,
I've looked at £CMCL. assuming gold price stay above $1600 and Caledonia Mining (LON:CMCL) production forecast increase is correct (an increase from 53 Koz to 80 Koz) then valuations should rise. See model below.
DYOR
BSV