My biggest mistakes of 2025

As we approach the end of the calendar year, it is a natural time to take stock; to reflect on things that have gone well and events we wish had turned out differently. For many investors, this introspection will take the form of a portfolio review. When it comes to these, I find myself in a strange conundrum. I enjoy reading other investors' reviews. I often learn a lot from seeing the investment process of others or commentary on individual stocks. However, when it comes to my own portfolio, I always baulk at the idea of writing an annual review.
The problem with portfolio reviews
There are a few reasons why I pull away from doing a full portfolio review. The first is that public disclosure tends to act as a form of commitment bias. If I publicly say these are my best ideas, then it makes it a lot harder to sell them if things go wrong. Of course, Stockopedia writers always disclose when we write about something we hold, but for me, that could vary anywhere between a small short-term special situation and a significant long-term position. The second is that by focusing on short-term results, I may become excessively pessimistic in the bad years and suffer from hubris in the good years. My own performance in 2025 has been nothing to write home about; I’m slightly lagging the FTSE All-Share, which is what I typically benchmark myself against. However, I consider that not too bad a result given my small cap and value focus (see my article earlier this week to learn how UK small caps have fared in 2025). It does feel like I’ve gone 12 punishing rounds with Mr Market in 2025, and come away with a draw at best!
We all tend to “only sing when we are winning”, and annual portfolio reviews can certainly be subject to selection bias, both in the events that investors choose to write about and whether they write one at all. The average portfolio review is certainly not representative of the performance of the average investor in any given period. Investors should keep this in mind when reading reviews during this period.
Hubris is a particularly bad thing for investors; it leads us to take on too much risk after a period of good results, often leading to investors giving back much of their short-term gains. Anyone who has been investing for a while will remember investors who were particularly active on social media during a couple of good years of performance, only to disappear completely when things turned south.
Focusing on mistakes
My own answer to this conundrum is to look for the mistakes I made during the year. If my chief reason for writing a review is to improve my own investment performance, then focusing on my mistakes is a way of achieving this aim without the risk of hubris. There is the possibility that dwelling on the negatives may lead to undue pessimism. However, like most investors (and despite my natural cynicism towards overly-promotional companies), I tend towards optimism, so this is unlikely to be an issue for me.
When it comes to investing, a big question remains: what is a mistake? It is tempting to think that any investment where we lost money is a mistake. However, as I’ve written about in the past, luck plays a significant role in short-term investment outcomes. Investors can do great research and spot an underpriced opportunity, yet an unpredictable disaster can blow a hole in the investment case.
Likewise, not every portfolio winner will represent an investment success. In extremis, it is not unknown for high-risk potential frauds to receive takeover offers. (If a management team can mislead investors, they may be able to fool acquirers, too.) Investors who had a high-risk investment saved by a takeover probably shouldn’t conclude that a portfolio full of high-risk, potential frauds is the way to go!
The key is to separate process from outcome, as the following table from Michael Mauboussin makes clear:
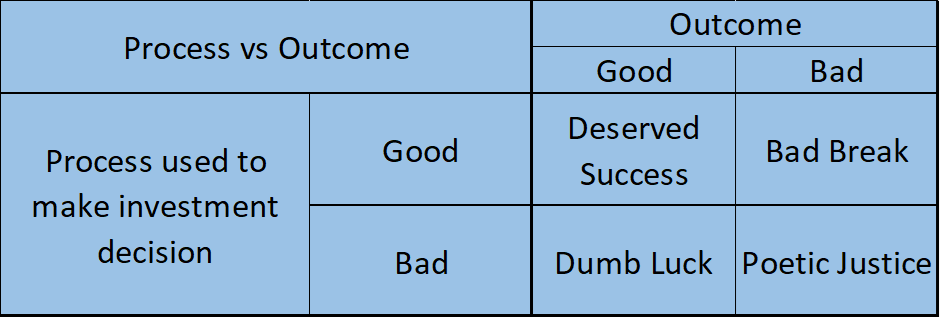
The reality is, it’s actually quite hard to learn from dumb luck, where my process was bad but I came out ahead. So, in terms of spotting my own mistakes, I look for cases of Poetic Justice. For these, I rely on two sources. The first is stocks that I bought during the year, which went down. The second set of events to review is stocks that I sold that subsequently went up.
2025 Mistakes:
Mistake #1 – Ignoring a declining Momentum Rank
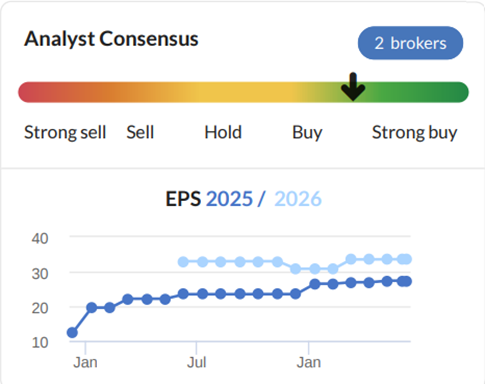
Thankfully, my buying record this year doesn’t look too bad. There are only a few stocks that I bought or added to which have faced significant declines. The first is System1 (LON:SYS1), which I initially bought at around £4.
The broker trend at the time was actually quite encouraging:
However, the declining Momentum Rank should have been a warning sign:
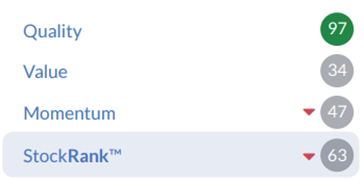
My thesis was that a conservative management that had a habit of beating expectations would make the shares look very cheap on a forward basis. However, weak advertising markets, and the high operational gearing that helped with the upside went into reverse, leading to a big profits warning. In this case, the lack of support from other Value metrics made the fall precipitous.
Billington Holdings (LON:BILN) is another company with excellent management and typically conservative guidance, where beating expectations is the norm. But not this year, where my top-up at around £4.50 in April looks ill-timed, with hindsight. Again, a great-looking broker consensus gave me false comfort:
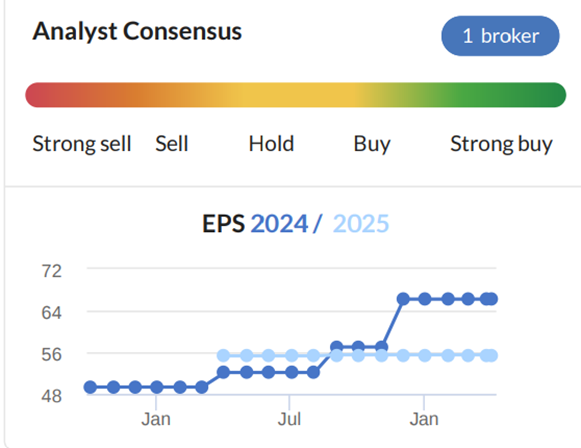
But a declining Momentum Rank at the time should have made me pause:
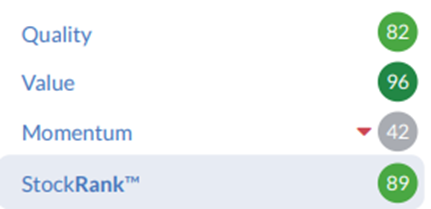
[One major loss in 2025, but I’m not sure if it should be considered a mistake or not, was to own shares in Jarvis Securities. The FCA has often been described as a chocolate teapot, given that many investors view that it regularly fails to prevent serious harm to investors from bad actors. In this case, it appeared more like a chocolate teapot full of poison, as it forced the sale of a brokerage that generated around £5m FCF/pa for £10m to a competitor. I don’t know what went on behind the scenes, but on the surface, they both damaged Jarvis shareholders and competition for all investors. It highlights that investment is about calculated exposure to risk, and sometimes those risks bite, even if they come from a strange source.]
Mistake #2 – The trend was not my friend
The trend I refer to here is not the share price chart, but the fundamental performance of the business. This year, I have been too early buy into businesses that faced further headwinds, and I was too early to take profits on those that performed well:
Capital (LON:CAPD)
I sold out of one of my long-term holdings in 2025. I was used to describing Capital as cheap to investors when it was on a P/E of around 7, and an EV/EBITDA of less than 3. However, a series of downgrades in 2024 and at the start of this year meant the shares no longer trade anywhere near these levels of cheapness:
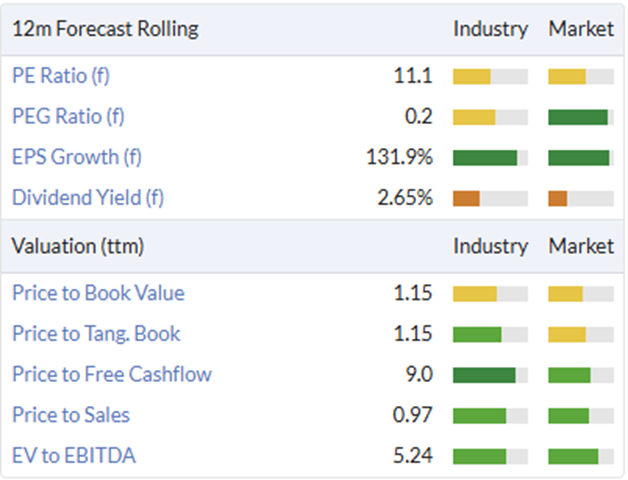
However, that trend has been recovering recently:
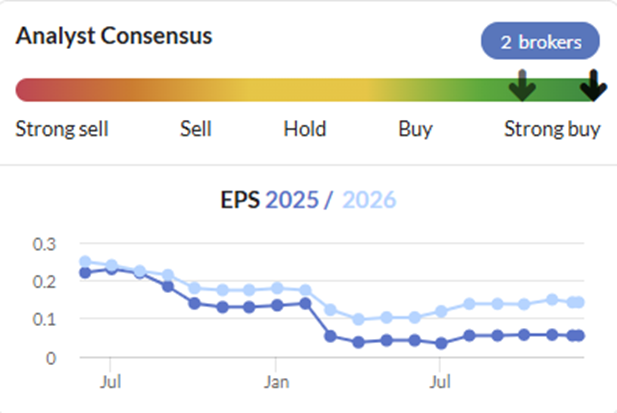
It is these small upgrades, plus their exposure to gold mining, that mean that investors are suddenly excited about the opportunity here. Other aspects of their business, such as their holdings in some gold explorers, have gone from a reason to avoid the company to a reason to buy for many investors. This shows the incredible power that sentiment has in the price investors are willing to pay for a stock, and I’m not sure the moves here have been totally logical. However, there is no doubt that by being focused on the absolute valuation (the share price is 50% higher than when 2026 EPS estimates were last at today’s level), and ignoring the direction of travel, means that I have left money on the table:
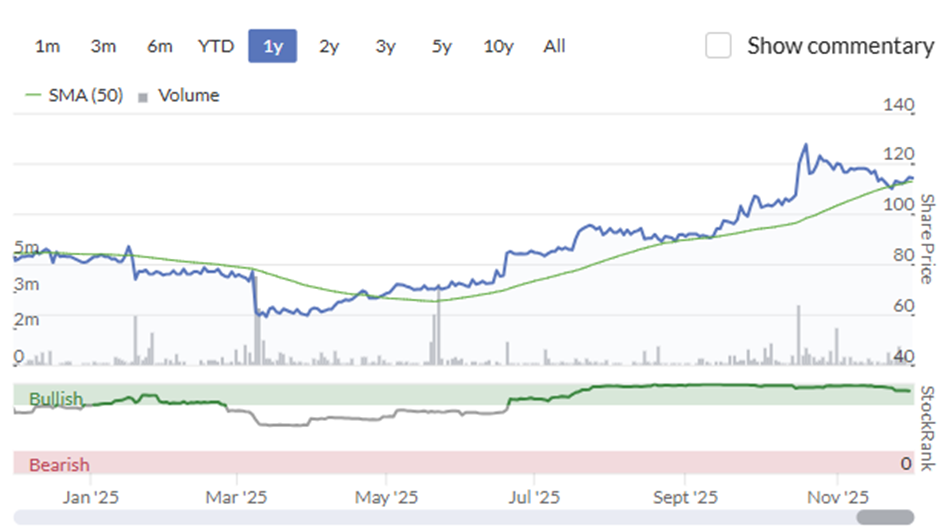
Ramsdens Holdings (LON:RFX)
This is another stock that has benefited from exposure to the gold price, although indirectly through its gold-buying arm, and the improved security of its loan book. I correctly called that this under-promise, over-deliver management would hold something on reserve in this sort of environment, as the series of EPS upgrades confirms:
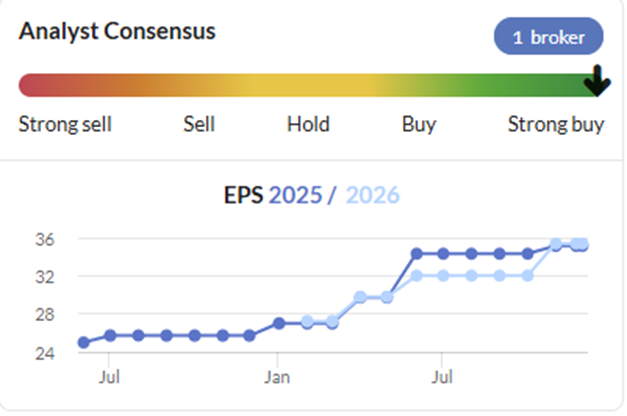
While I didn't predict the incredible run gold has been on this year, I started top slicing around £2.50 when the shares started to rise above their typical earnings multiple range. However, I should have taken note of the very strong and rising Momentum Rank at the time:
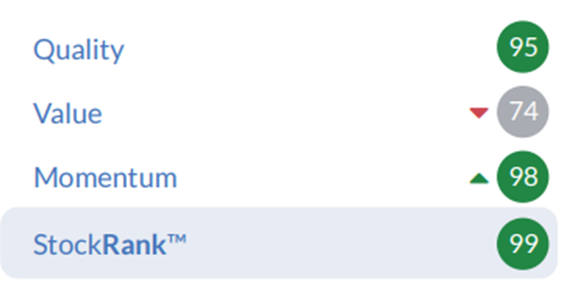
And while the Value Rank was falling at the time, this was far from just a Momentum-driven High Flyer.
Brave Bison (LON:BBSN)
I bought in here, having originally spoken to management at the Mello investment conference a year ago. The scale of the ambition of the Green brothers was clear, and they used their cash generation to acquire multiple businesses during the subsequent period, leading to modest upgrades in EPS:
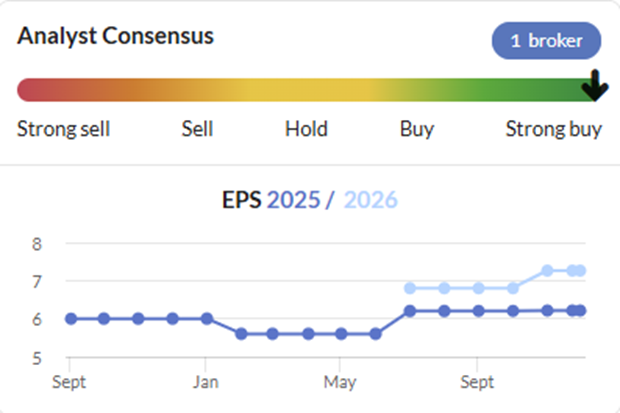
For a time, I thought I’d made a wise decision, as the placing that accompanied the deal was at a discount to the level I sold at. However, it was only after the company presented at Mello again in May, that investors really started to re-rate the company, especially as the impact of the deal was integrated into broker forecasts.
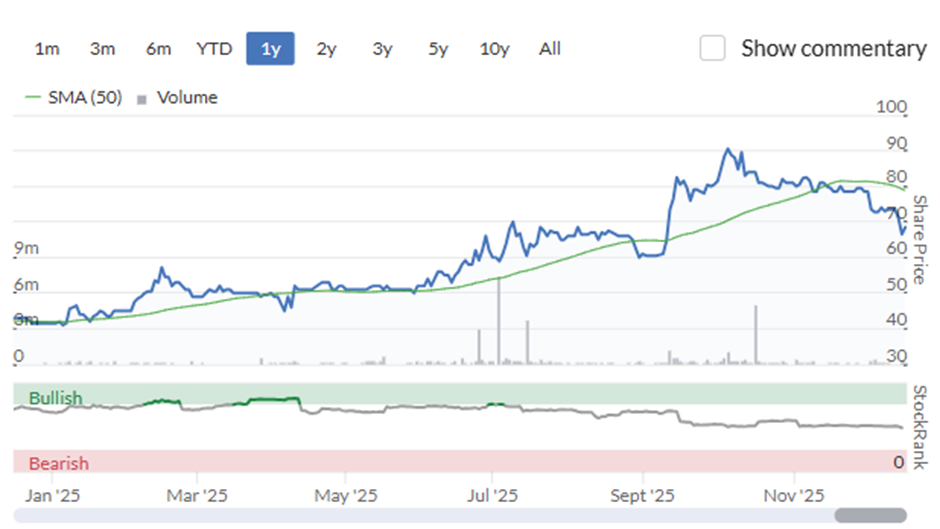
A rising Momentum rank perhaps should have meant that I was willing to hang on for a further re-rating:
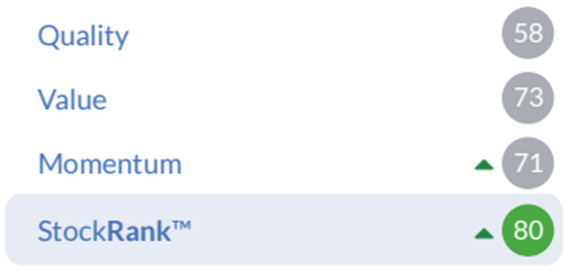
Mistake #3 Selling due to boredom
Centaur Media (LON:CAU)
Centaur was a company that I had held in the past, and while I knew that the company was likely to be undervalued on a Sum-of-the-Parts basis. Indeed, it was the seller of the Mini-MBA that excited Brave Bison shareholders. However, it had profit-warned, and the shares had traded sideways for a long time. It was only when I heard Christopher Mills describe it as his best pick at Mello in May that I thought there may be enough near-term news flow to consider holding again. However, with very little sign of anything brewing regarding the sale of their biggest asset, The Lawyer, I had got bored by the mid-Summer and ditched my holding. A month or so later, the company announced that The Lawyer had been sold, and the proceeds were to be returned to shareholders:
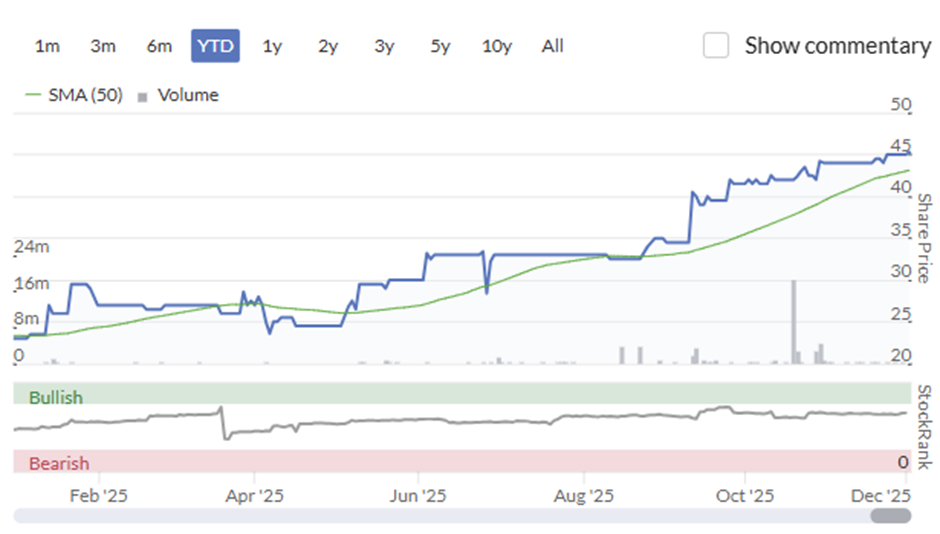
Treatt (LON:TET)
This was another company that I bought well, having got a good price following one of the company’s recent profits warnings.
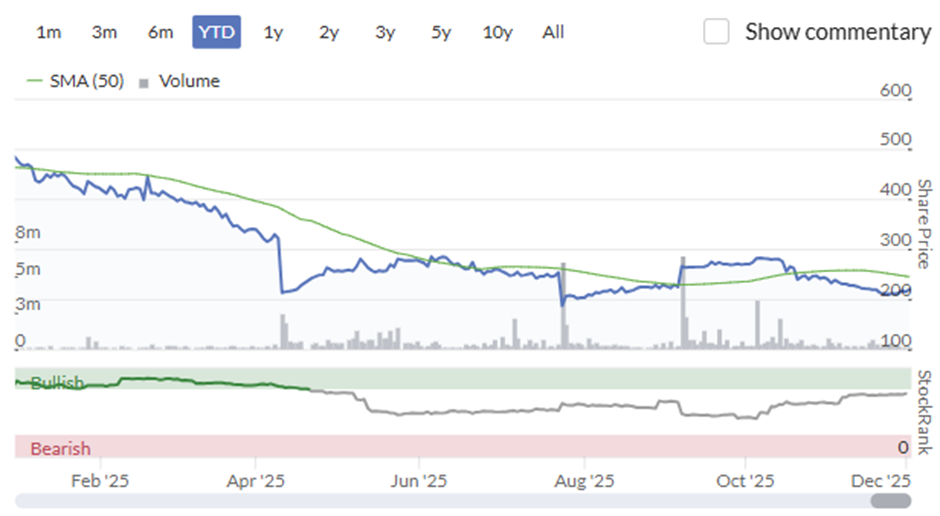
The attraction was a discount to Tangible Book value:
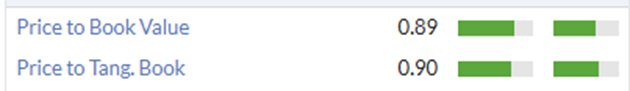
While I knew that this could make the shares a takeover candidate, the lack of near-term earnings led me to take modest profits shortly before the offer came in. This didn’t turn out to be disastrous, as the bid was blocked and the shares now trade back below book value, potentially giving me another bite of the cherry. However, with no other bidders arriving during the recent offer period, and blocking shareholder Dohler unable to mount their own bid (if they indeed want to) for six months, I am in no rush to buy back in.
Mistakes retrospective
Overall, none of these mistakes have been disastrous, mainly because I appear to have mostly avoided the mistakes I reported on for 2024 which were:
Mistake 1 – Ignoring my own rules
Mistake 2 – Under-estimating how poor sentiment can get
Mistake 3 – Poor selling
Mistake 4 – Missed opportunities
I don’t feel I have been over-exposed in financially weak companies. I think I have been more cautious in deciding when to buy during this period of continuous weakness for many smaller companies. However, I think my selling could probably do with some work, as my “The trend was not my friend” mistake from 2025 above shows. I have undoubtedly missed opportunities, but no significant ones come to mind. So, despite rather mediocre returns for the year, if my aim is to only make new mistakes, I have mostly achieved this.
Finally, I won’t be alone in making mistakes in 2025. It may be difficult to focus on the errors, but it is also strangely cathartic. I’d love to hear from subscribers in the comments if any particular mistakes stood out to them, and perhaps more importantly, what they learnt and how they are going to avoid this mistake in the future. I’m sure they will make fascinating reading.
[Disclosure: Mark owns shares in Billington Holdings (LON:BILN) ]
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.

64 comments
On stop losses. I think it is worth adding that there may be some stocks that are so illiquid that having a stop is counter-productive, especially at times like these where UK markets suffer from low-liquidity, and we enter a period where this is likely to be even lower. Having a notional stop where, if the stock closes below a certain level, you re-assess the position can be very useful. However, investors who try to automate this process and put in stop loss orders with their broker can often lead to some very nasty shocks. What happens is that a few sales, say someone doing a bit of year-end tidying of an insignificant position, leads to a fall below the level of the stop which then leads to the broker executing a market best order for the whole position, which then may execute significantly below the intended stop. What was intended to protect against a 20% drop on bad news ended up crystallising a loss at 30%+ down on no news. And, of course, once the order has been executed the price often bounces back.
I think I've seen this over that last month. Some rapid drops in illiquid stocks that quickly bounce back. If investors are willing to be liquidity providers and take advantage of those who have foolishly placed stops they will do much better than being the stop-lossers over the long-term IMO.
This doesn't mean that stop losses, especially if one is smart about where they are placed, is a good strategy to avoid loss aversion for more liquid positions. (The same effect can happen, e.g. with algorithmic "flash-crashes", but these are much rarer.) Just that I think there is a level of illiquidity where investors have to accept that they won't be able to trade at the price they want on any given day. They either need to not invest in these types of stocks or accept that they won't be able to have a stop loss on this sort of position.
Mr Simpson
I do not understand the statement. I do not make mistakes. I only have have wins, some very very big wins and intend to continue doing so for years to come.
D Trump
I use the base of the Ichimoku Cloud as my notional stop loss. In normal circumstances I'd exit on a close below the cloud. The challenge is if a stock has an aggressive runup then it is a long drop to the base of the cloud. I can tolerate those larger drawdowns but many can't ...
YouGov (LON:YOU) was mine...
Thank you Mark, educational as usual. We lost heavily on Jarvis too for the same reasons. We still hold Capital and half our original holding in Ramsdens, the sale was close to its current price several months ago. Billington remains on a possible buy list. 2026 promises to be interesting. I've read an FT article this morning on Apollo positioning for market turbulence, good luck to everyone on Stockopedia.
My greatest success Serabi Gold (LON:SRB) , my greatest regret Serabi Gold (LON:SRB) . It dropped 20%, so I sold, but then went back on a climb, so lost an additional 30%. How do I fight my auto 20% rule against a share with a high stock rank?
Were you using a trailing stop loss? It really is a difficult one.I think for stop losses, you have to take the natural volatility of the share into account. But even then, it doesn't necessarily help if you've got a big winner like Serabi Gold - corrections can get quite significant as you go deeper into the run.
I actually did sell half of my Serabi Gold in the recent correction, and I was quite comfortable taking some risk off, at the time. Of course, it's popped up and now looks like it's going to break out again. So I might increase the position size once more - But there are so many other good gold stocks too that some more diversity makes sense.
Regarding stop losses, I'll share a graphic I did some time ago, which I do use as a rule of thumb for some of my investments. The key lesson here is that more volatile shares need to be given wider stop losses. Maybe that's something that could be helpful.
Thanks Ed
Where do I find the 1year volatility?
Sorry if it's a dumb question
We aren't publishing the volatility on stock reports, but you can add it as a column in any table view. I don't tend to look at the exact volatility myself. I prefer to just scan the risk ratings.
You just have to have a bit of a mental model of the ranges that their volatilities are in. The above graphic helps with that.
Thanks
I'll take a look over the holidays
Van Tharp used to advocate for a multiple of the average true range (ATR). Brief overview of it here (along with lots of alternative methods), covered more fully in his books.
Van Tharp 7 - Stops and Exits - 7 Circles
Van Tharp is a total legend - it was a great loss to see him pass away a few years back. I actually have a copy of his position-sizing book which is really terrific if you are into R multiples and that kind of thing..
One of my favourite comments of his is the idea that "If you don't have rules, everything you do is a mistake."
I love that quote Ed!
I know, I can't get it out of my head. It's one to live by!
don't think position sizing has ever been mentioned on the site, presume this is because it requires a stop loss. Would be interesting to back test the NAPS with position sizing and a hard stop loss at 3xATR for comparison. Personally, found the ATR method caused me to be overweight in conservative stocks and underweight in the more adventurous leading to underperformance. Wide spreads also make hard stops impractical.
That's the nature of any volatility-based position sizing scheme. It's a reason I don't really like it.
I don't mind using volatility levels for stop losses, but I find that it's often slightly more speculative/volatile securities in high stock rank sets which drive a lot of the outperformance in bullish markets. So if you underweight the position, you suffer in the upswings.
A case in point is the junior gold stocks this year - there are two positions in the NAPs this year which have returned more than 180%. Using a volatility-weighted position size would have very significantly underweighted those positions.
One of the great benefits of rebalancing positions after a set period of time is that you cut down sizes when they get excessive as a routine - this does lock in quite a lot of gains from more volatile securities - they can have excess upside volatility as well as downside volatility. But because returns are positively skewed ( you might lose 50% but you might also triple a position) - you get a positive return distribution.
This Stop Loss Levels checklist has been very useful throughout the year. Thanks.
I think that any investing rules need to be backed by statistical evidence. Maybe I'm being a bit unfair, but reading this article I felt like I was listening to someone leaving a casino penniless, cursing the fact that they hadn't listened to their gut and put everything on red.
I certainly didn't come to that conclusion from reading the article. He even included the whole process vs. outcome table and discussed it. Mark is one of the most evidence-based investors that I know, which is probably one reason he sticks so firmly to his value strategy (the evidence suggests it is one of the few factors that really work over the long term).
Really enjoyed this, Mark, and it was lovely meeting and spending time with you at Mello recently
Sorry the message got truncated!
I especially like the idea that progress shows up as making new mistakes rather than repeating old ones.
Reading it through that lens, it feels like you’ve clearly addressed Mistake 1 (ignoring your own rules) and Mistake 2 (under-estimating how poor sentiment can get). Simply avoiding weak balance sheets and being more selective about entry points during prolonged small-cap weakness has probably done more to preserve capital than is obvious from headline returns.
Where I most recognised my own experience this year was around selling. Like your “trend was not my friend” example, I found that the hardest calls weren’t forced by bad news, but by a gradual erosion of the original thesis.
Those are uncomfortable decisions because nothing demands action — yet in hindsight they’re often the most important. A few of my exits are still down year-to-date, which has reinforced that lesson rather than undermined it.
On missed opportunities, I’ve become more relaxed about not owning everything that works, and more focused on avoiding positions I can’t confidently explain several years out.
In that sense, 2025 hasn’t felt like a year of disastrous mistakes — more a year where process quietly improved. And as you say, that’s often the most valuable kind.
My examples where I got out were Synectics (LON:SNX) , SThree (LON:STEM), and Transense Technologies (LON:TRT) btw.
Mark
Thanks for your write-up, which is thought provoking as usual.
I totally agree with you that “ loss-making investment equals mistake” is incorrect logic. Whatever process you have, you are going to have losers - you are going to be buying not at the bottom and sell not at the top. I try to focus on four items in reviewing my annual performance:
1) Look at major contributors (positive and negatives in absolute and percentage terms). Think about position sizing On my winning trades, why did I not have a bigger position? How confident was I in the trade at the time? Similarly on losing trades was illiquidity (particularly a risk in small and nano caps) a significant factor in the size of the loss? End-year is a good time to recalibrate the criteria for deciding the illiquidity threshold below which I should not go
2). Were there situations where I did not follow my process? Either sloppiness, laziness, FOMO etc. Why did I do that? We naturally focus on those that cost us money - but probably more interesting are those that turned into profitable investments. What do I learn from those? If I repeatedly don’t follow my process - should I change the formal process?
3). Is my process still appropriate for the current market conditions? Is it still reasonable to expect my process (and universe of investments I look at) will throw up enough opportunities in the upcoming years. Talking to other investors are their aspects of their process I feel I am intellectually and emotionally capable of incorporating?
4). How much do I enjoy the investment process? Are there things I can do to make it more enjoyable (and therefore more sustainable long-term).
I think my biggest mistake of this year, and most years, is changing my approach too quickly. I read a new book or article and get swept up with a new approach such as momentum investing, but then get impatient and dont follow it long enough to reap the rewards (only to look back and see those stocks do very well in the medium term)
Look forward to continuing to do the same in 2026!
For me, there are two main mistakes that are related to each other.
First, the way I handled the March-April drawdown. I sold a lot of my holdings half-way down the decline: the MSCI World Index lost 17.5% as Trump came out with some truly mad tariff proposals (remember his big board of tariff rates?!). But then he chickened out (TACO!) when he saw how severe the market reaction was becoming. Well I had a smaller drawdown, but was too late to re-engage in the market, so I lost out on a lot of gains and took much longer to get back to starting value, overall.
As an aside, I actually sold Google in early May, during this recovery, because of concerns that its >90% market share in search will be significantly eroded by AI LLMs, like CoPilot. Well, Google has doubled since then! I'm actually not sure this is a mistake, as Mark mentions, because I still believe that thesis will prove to be true, and the AI landscape is very narrative driven right now, in terms of the excitement around Gemini.
Anyway, my second class of mistake is simply selling on short-term troughs and buying on short-term peaks. Yes, stocks are often very momentum driven nowadays, but an individual stock is also very volatile (you can add the vol figures as a column in your portfolio table), and all I'm really doing is reacting to that randomness and acting against the "but low, sell high" principle. I'm going to try and buy on dips and sell on troughs, over the next year.
*sell on peaks, I mean! (can't edit the post in Android)
Thanks for your writeup and honesty Mark. I've done a personal investment review every year and it's helped me to take a 'step back' and refine my method.
Coincidentally I've also become more focused on my momentum blind spot this year. There were a couple of stocks I had quite big hits on and in most of those cases I bought 'too early' or they have possibly turned out to be value traps e.g. Card Factory, Ultimate Products, Impax Asset Management (apologies but I can't get the @ symbol to work). I'd argue the first two aren't very high quality businesses which should have also given me cause for caution, but perhaps buying when there was better momentum would have made more sense.
Impax hasn't showed any meaningful turnaround in net fund flows - really I should have waited until there was clearer evidence of a turnaround happening; why rush in? The good thing with fund managers is most report quarterly, and some you can even track monthly, so why dive in too quickly?
There are obviously a number of investors who seem to do quite well with momentum e.g. Cockney Rebel and Phil Hoffer (I enjoyed his Stockopedia webinar earlier this year). So it's definitely something I want to pay greater attention from now on.
I have a lot of sympathy with JohnDoe2378's comment that he should have invested in a US based index fund. It's quite humbling to look at my portfolio's performance versus NASDAQ or S&P500. While the tech giants are dominating, the historic performance for the S&P has been good. Maybe time to allocate at least a proportion of my portfolio to the US.
I do a personal investment review every Friday/Saturday and have no surprises at years' end. I read the DSCR every weekday too.
Biggest mistake for me this year was a Boredom Sale. I had held Smiths News (LON:SNWS) for 3 years and finally the inertia got to me at 55p this year just before it made a leap to 71p which, when allied to the 10% divi, would have made it a solid winner. Now I see it every day at the top of my VM Screen and it makes me chunter. Ho hum.
Centaur Media (LON:CAU) for myself. But hey! I put the cash on Pan African Resources (LON:PAF) .
They say that the biggest error investors make is:
1. Not cutting losses soon enough.
2. Not running profits long enough.
I am guilty of both (especially number 1), but i am working on this.
Thanks Mark - really helpful and honest review.
I bought £40k of PAF shares in 2015 at 8p per share and thought I'd done well selling them at 16p in 2023 after years of going sideways.......today's closing share price £1.15p!!
Glad I'm not the only one that sometimes makes the mistake of getting bored and selling too early.
My biggest mistakes: not selling BAE Systems (LON:BA.) when its value score fell below 20; not selling 3i (LON:III) when its PBV was significantly above 1.
My lesson for 2025 is to accept the loss and sell before a 20% loss becomes a 40% loss
Where there'd been a profit warning I think that's true (read Stockopedia's profit warning research). The risk with other stocks is you might miss out on some big gains. Just look at the NASDAQ index this year!
Very honest and educational bad momentum needs more respect
Impatience which leads to selling a stock far too early or not adding additional funds when running a winner are my mistakes from 2025.
Unfortunately I fell in love with SNX and was way too confident of this company moving forward.This is my biggest holding by far and made the mistake of not listening to my gut back in August. Knew I should have sold around £3 due to lack of news - obviously didn't and now find myself 30% down and still invested.
Synectics (LON:SNX) I sold this stock back in August back clung on by my finger nails when everything in my personal opinion meant sell. And going back to not running my winners the funds saved from selling SNX should have been spent topping up a winner. It stares me in the face but I still make the mistake! Must do better in 2026.
Just sell it
Over the last 3 years I have learnt not to hold losers. I cut if losses hit 15%. This was emotionally difficult at first but it is now a mechanical action.
Hi SCI20, just a quick question on your 15% cut off point.
If you buy in several tranches do you sell if/when each tranche hits the 15% stop loss or if/when the overall position does?
I'm just intrigued as to what way people who use stops like that work it. I appreciate no system is correct 100% of the time, apart from hindsight and it's no way to invest.
I sell when the overall position hits a 15% loss. I buy in no more than 3 tranches with an average of 2. The 15% sell rule is not overly scientific but it has removed confirmation bias which has previously seen me hold on to losing positions sometimes exceeding 50%.
Thanks for the reply. I was just intrigued as to what method you used.
I agree on the need for a cut off/stop loss. I'm sure most people on here have held onto shares far too long and watched gains evaporate or losses compound. All part of the ongoing learning process.
Cheers
I often sell too early, especially when I hold a losing share that is on the rebound and has started to show reasonable gains. The momentum ranking seems to lag a bit and the worry is that it will just drop back again.
Thanks for this Mark. I'm interested that you mention Broker Consensus on a number of occasions as an influence on your decisions, but most of charts you use have only one, sometimes 2, brokers.
It's easy to reach a consensus when only one party is involved
The lesson I draw from this is to be wary of placing weight on a Broker Consensus when only one or two Brokers are involved. Obviously this metric will apply more often to smaller companies than large ones, exactly the companies where the insights of a broker are helpful. But hey, nobody said this game was going to be easy
I think the broker concensus trend can still be useful even where there is only 1 broker as you can see whether that broker thinks the picture is improving or not. However, there was an example on DSMR yesterday where Roland pointed out that a broker estimate on Synectics hadn't been updated since Feb due to a house broker change and looked as though it was out of date - so caution is definitely needed as this can give a misleading picture of the expectations and PEG metrics etc.
Impatience and over trading were my biggest enemies and I they'll still be tough to overcome in 2026.
Mark, Oh well at least you did not have IG Design (LON:IGR), which l think one of your Christmas share picks. On that subject, only 2 out of the 12 are in profit. IG Design (LON:IGR) is the worst down 69%. Serabi Gold (LON:SRB) is the top performer up 129%.
A bit harsh on the lad, he is bearing all!
It was not just him, it was several Stockopedia staff.
Stocko staff are not tipsters, but provide ideas for investors to consider and DYO research. Personally I found the 12 stocks for Christmas selection very supportive when I carried out a NAPS selection using Ed's principles at the start of the year.
Out of the 12 stocks for Christmas list I purchased 2 stocks in January which were also on my NAPS selection: - International Personal Finance and Serabi Gold. The former is up 70% and the latter >100%. I also bought CMC Markets off Graham's Top 10 list. This is currently up ~15%.
Having said that I did get suckered in to buying Impax Asset Management in July when I thought it was just too cheap, only to realise it could go cheaper still. This is currently down ~30%.
I use the stock ideas from the Stocko staff and carry out own research thereafter to decide whether to invest or not. Accordingly, I very much hope the Stocko staff will once again provide some interesting stock ideas for 2026 from which I can consider and cherry pick one or two ideas from.
Yes, I thank them for that and International Personal Finance (LON:IPF) treated me kindly too
Ah Serabi Gold (LON:SRB) the stock I placed on a watchlist which alerted me when the price was 72p a share which I then took no action….why follow my own plan?? The rest is history.
I did own IG Design (LON:IGR) when it was one of my 12 Stocks of Christmas, and I thought about writing about it here, but didn't for brevity.
I think it is actually a good example of why we have to seperate the process from the outcome when identifying investing mistakes. It may well be a mistake to own it at the start of last year, but going down on a profits warning isn't the only criteria for judging that.
Firstly, when I wrote about it, it didn't have an amazing Momentum Rank, but it was rising:
And with a very high SuperStock ranking, we often use this as an example fo why investors should own a basket of SuperStocks, not just pick 5 or 10.
At the time, the brokers' consensus was recovering:
Meaning that this actually looks a lot like Capital (LON:CAPD) does now, and one of my mistakes was to sell that too early, by focussing on the absolute value not the direction of travel.
At the time, I thought that the would hit the numbers, mainly becasue management gave some very specific and credible reasons why the business was recovering strongly. They were either deluded or wrong.
So we could say it was a mistake to speak to management of companies we invest in, but then I know many of us gain great insight from doing so, so I am not convinced talking to management is a mistake per se.
Also you could say that investing in any company that could profit warn is a mistake. But then there are plenty of counter-examples. One recent one that springs to mind is Tpximpact Holdings (LON:TPX) , where a market seemed to be expecting a miss, and a simple in-line statement caused a 40% rise in the stock on the day.
The reason I picked IG Design (LON:IGR) as my Value pick of the 12 days of Christmas, was that it traded on around half book value, and I expected that those assets would be made productive eventually. When the share price fell on the profit warning, by around 60% IIRC, the case for a TBV play actually got stronger and I bought more shares.
I eventually sold when the market reacted positively to them selling the DG Americas business for a nominal amount, (but removing potential liabilities). At the time I thought there could be a bit more value left but with no pro-forma accounts for just DG International, I had no idea what the real situation was, and I got out. Overall, for a profit, but this again is not a good test as to whether I made mistakes here or not.
As it happens, we finally have accounts for just DG International. They do show a discount to TBV again:
Mainly because the price has fallen back down. I am not tempted to buy back in yet as the new management guidance and brokers' forecasts show that there is almst no chance that these assets can be made productive agian in the next few years. However, if that changed, I'd conside investing again.
--------------------------------------------------
Overall, I think the performance of our combined 12 Stocks of Christmas wasn't great, but I believe there is more analysis to come on that one, so keep your eyes peeled for this year's festive treats.
No information from the company, and none expected before the new year. But my time is up with Warpaint Warpaint London (LON:W7L) -so this si MY commentary, ie it may differ from others.
I have just sold my final tranche of W7L for £2.
My much larger tranche of W7L I sold for £5.09 in January.
Subsequently, I wrongly bought back some in the meantime at much lower prices than my January sale price with the hope of picking up some trading profit as the brand recovered. I was mistaken.
Why did I hold on for so long to my latest holding is a good question.
The answer is complex because I believed in part that some of the issues at the Interims in Sept were a one off. However, the inexorable fall in SP continuing since then together with a detailed review of the market possibilities in key markets (US potential), UK (£W7L’s significant market from the first), and EU (often forgotten that it is the £W7L’s largest in terms of total sales) have changed my mind. When we get more RNS information from the trading updates in the New Year, I believe that we may find that Warpaint London (LON:W7L) is overpriced at £2, and predictions for H2 may fall significantly short of that.
Evidence? As far as that open to us as private investors, there really is only Amazon.co.uk which as we know from the past is a large and profitable element for £W7L. I follow that closely, and the evidence shows that there is significant discounting going on across the board, especially for the W7 brand, right now in this key period leading up to Xmas.. There are widespread offers of 32% and 26% available across the range. Surprisingly, there is less on the second and lesser brand, Technic but this is less important. Also usefully on Amazon, there are extra figures for the numbers of a line sold in the last month etc for many lines. These have been less than I would have expected for some Warpaint London (LON:W7L) lines, especially in gifting, very important at this time of year for presents.
Clearly, the Trump tariff situation has been unkind to Warpaint London (LON:W7L) which was pinning much hope on the expansion possibilities in the much bigger market of the US, at least 10 x the size of the UK. After expanding their personnel investment in the US, that has now been cut back and in the second half, there is only one store group taking more lines. Gone are the expansion dreams of moving up out of the deep discounters and getting the aspirational back-wall permanent fixture in the likes of Walmart. Sad but true.
You will note that I have not included any impact of the recent acquisition made by £W7L. If you look on amazon.co,uk the company has made a brave push to get the products into the limelight. There is no indication of sales effect, and therefore financial effect for the company. Anything I say would be a stab in the dark, so I am taking a neutral stance there with some positive effect on revenue in due course.
Probably, the most important consideration in my deeper analysis has been the revelations I have found in examining the US company e.l.f. (standing for eyes, lips and mouth, for those who didn’t already know.) If you want to see what e.l.f. sales on Amazon in the US have been recently, go to amazon.com and you will be surprised. On the other hand, this is a company and a brand which has recently paid $1 BILLION (my capitals!) for Hailey Bieber’s skincare brand, rhode. In other words, this is a huge company ………and, in my view, it is eating W7L’s dinner, and that of probably quite a few other UK brands too.No mention of soft consumer sales from e.l.f, and they are already poised for growth in key European markets, including the |UK, regardless.
Why its impact on Warpaint London (LON:W7L) could be disproportionate is that its pricing is closer to £W7l’s …..and it wants more. In 2024, it claims it was growing at 10 x the growth in the UK market. And it has already been in Superdrug since 2017 and Boots from 2019. I mention these in particular because £W7l mention these are significant support elements in its expectations for H2 this year; expansion in Superdrug, and some limited gifting opportunity in some Boots stores.
As for the EU, again key support elements for £W7l in H2, this was the position of e.l.s. in key store groups there.
In e l.f.’s plans for 2025, there are major moves in Germany, Belgium and the Nordics. Germany is considered the largest cosmetics market in Europe, and e.l.f have launched its products in 1,600 ROSSMANN locations nationwide, marking its largest international retail launch to date. Notably, no action from W7L in this apparently very large market.
In the Netherlands, as well as Etos, which is claimed as one of the new ‘wins’ for W7L in H2. the e.l.s. brand further expanded into Kruidvat and Trekpleister stores in May 2025.
In the Nordic region, e.l.f. partnered with SÆTHER as the exclusive distributor for the Nordic region, with launches anticipated in retailers such as H&M, Matas, Kicks, Vita, Sokos and Lyko. No mention of W7L there.
If you get the impression of a huge e.l.f. bulldozer working through western Europe, including the UK, you may.share my opinion too.
Of course, there will always be space for smaller companies, managing their resources well as W7L have done in the past. However, the profitable growth path which many of us have enjoyed with W7L over the last few years may no longer be there and the effect on the bottom line and ultimately the SP may be very significant going forward. Additionally, smaller companies may well also be operating with smaller discounters….like one of the UK companies which took Warpaint London (LON:W7L) by surprise going into administration in W7L’s Q1. This had been a long time trader with W7L for decades, and has left W7L with somewhe3re near a£1m loss in total when the total effect is eventually totted up totted up.
It is a sad situation, because it feels like I am losing am old friend - and I may be wrong. of course.
If you have got this far, congratulations and I hope this research in depth will help you make up your own minds too.
Good thoughts on recent trading, especially as you've had your ear to the ground in a way many of us will not have been on top of. It can be very hard to sell something much lower than it has been trading in the past, so congratulations on being able to trade what you see the current outlook is rather than hanging on to past price action, it is a rare skill.
Honestly, my biggest mistake was stockpicking rather than invest in a US based index fund. Simples.
Excellent and honest review. Yet to undertake my annual year-end review (why year-end and not say 23 Feb or some other random date?) and yet I know already that some of the findings will include:
Never love a share (to paraphrase Joan Collins, never love anything that can't love you),
Being too optimistic on the likely outcomes of decisions (selling too early cos its made its expected return, only to see it keep climbing; holding on because my decision was right and the entire Market doesn't see what I see),
Being too exposed to the UK and, by definition, underexposed elsewhere,
Suffering from FOMO.
Thanks.
Never love a share (to paraphrase Joan Collins, never love anything that can't love you),
Yes, I never understand investors that make a particular share their handle. If you call yourself XYZInvestor, how can you ever sell XYZ? And while XYZ may be good now, yesterday's never-sells are today's lost 90%s!
It's tricky, though. If you've made a bunch of dough on something then you figure you might have a 10-bagger on your hand and want to hodl. We've all sold shares that were "high enough" only to see them go on to go on to multi-bag. Very painful.
I think there are many ways to "play" the stock market. You have to kind of know what game you're playing and what the rules to that particular game are.
I'm more into safe, quality steady compounders. If you buy at a reasonable price I think you avoid a lot of big drawdowns. You should still make mistakes, but the losers shouldn't take big chunks out of your portfolio. You're playing the "losers game", as it were.
Contrariwise, one should probably think about lightening up when prices become too daft, whatever you think "too" is (but the "too" much should probably be higher than you're comfortable with).
So, often people like me or others come up with share recommendations, and other people shoot them down with counterarguments. It's not that others are wrong, it's just that you can't find the perfect investment. As Howard Marks points out, it's the fear and uncertainty that keep prices low. As he puts it, "When it's time to buy, you won't want to."
It's difficult to know what being "wrong" means. Take Apple. From 1981 to 2019 it generated $1.64t of wealth. BUT. It had a 74% drawdown form May-Aug 1983 during infighting leading to the departure of Jobs. It has an 80% drawdown between Feb 1992 and Dec 1997, being outcompeted by PCs and the rise of Windows. It had a 79% drawdown from Mar 2000 to Mar 2003 due to the tech crash.
Amazon had a 91% drawdown in the Sep 2001 tech crash. Imagine that!
It's hard. Very hard.
It's probably time to sell when you start feeling smug, and thinking how well you're doing. I've been there more than once. The market has a way of bringing you back down to earth with a bump!
Totally agree. I often find if I am checking my portfolio much more often than usual because I think I'm doing well it is a bad sign!
"It's probably time to sell when you start feeling smug, and thinking how well you're doing. I've been there more than once. The market has a way of bringing you back down to earth with a bump!"
Trouble is the price can keep going up long after one is feeling smug about one's profit. When something does eventually cause the music to stop, the reversal tends to be swift and calamitous - a case of damned if you do, damned if you don't.