My Market Musings 20/06/20: Pausing for Breath

Pausing for Breath?
Key macro/market trends to watch:
- Economic data can only get better: For now
- A pause in stock market uptrends: Stock markets have not yet exceeded their early June highs
- Commodities: Central bank liquidity should also help commodities
- Leading regions: Russia, China A-Shares
- Leading themes: Videogames and eSports, Cloud Computing, Biotech
- Risks: Worries over a 2nd wave of infections: Particularly in the US
The data is (obviously) looking better
This should be obvious – after all, we have just suffered what the UK Chancellor of the Exchequer Rishi Sunak called “the greatest recession in 300 years”!
After an economic collapse of such epic proportions and in record time, the end of lockdowns were always sure to herald very sharp rebounds in economic data readings from the depths of depression.
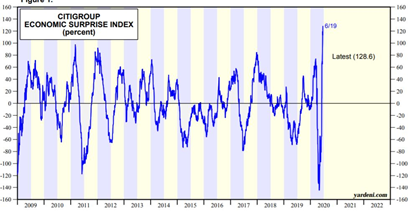
And that is exactly what we are starting to see, judging by the enormous rebound in the US economic surprise index (Chart 1):
Chart 1: A historic rebound in US economic data follows a historic collapse
This should not surprise anyone, given the speed and scale of the response by both governments and central banks to the sudden stop in the global economy since March. They are throwing all manner of economy-boosting policies in an effort to shock the global economy back into life.
The real question now is simply: how long are they going to continue this massive stimulus effort? My guess is for quite a while longer, until they are certain that their economies are back to growth and they see unemployment falling to more acceptable levels once again. This is pretty much what the US Federal Reserve chairman Jerome Powell has committed to do – to continue to help the US economy until unemployment and inflation are back to more “normalised” levels.
Ultimately, it is this gargantuan effort that is pumping liquidity into world financial markets, lifting all assets including government and corporate bonds, and of course stocks too.
And yet, stock markets are not making new highs
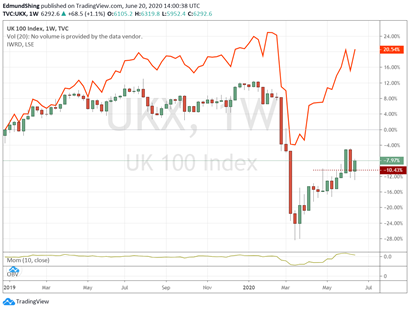
This last week has been one of a rebound, but really a continued pause for breath after the rally from the March lows. Despite the strength of the US stock market, the MSCI World index remains 6% down from its start-2020 level (in US dollars). Nevertheless, the FTSE continues to trail far behind global stocks, held back by its over-exposure to Oil and Mining, and its under-exposure to Technology.
Chart 2: FTSE 100, MSCI World indices bounce but no new highs
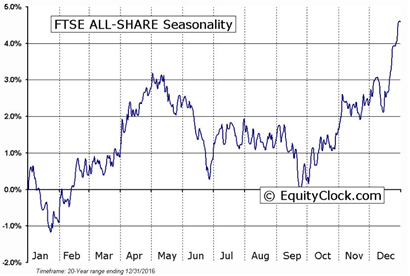
We should bear in mind that this is a generally unfavourable period of the year for stocks, particularly for European stocks which tend to post lower returns in summer, and stronger returns in winter…
Chart 3: FTSE seasonality is strong, and unfavourable right now
Spare a thought for unloved commodities
I have gone on here a number of times about precious metals and gold in particular before; I will just mention that for me, the $1750/oz level is a big one for gold, and we are coming up on it again now. The gold price has been consolidating sideways since mid-April (Chart 4).
Chart 4: Gold challenging the top of a 2-month trading range
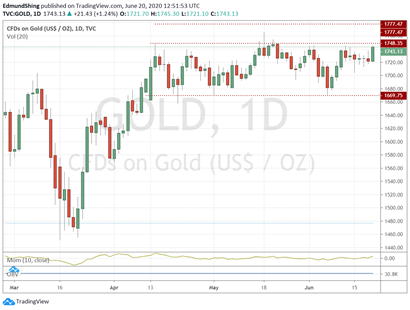
If we can break above this $1750 level and hold there, then I believe that the 2011 high of over $1900/oz will then be the next objective, driven in large part by the ongoing liquidity flooding into the global financial system.
For now, this gives me confidence to hold on to my over-sized position in gold mining shares and ETFs (like GDX and GDXJ), as they have operational gearing to the gold price and long-term catch-up potential to the gold price itself.
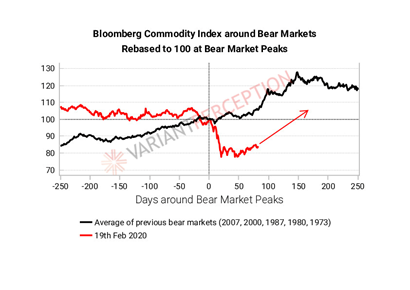
More broadly, commodities should benefit from this emergence from global recession and bear market, as indicated by Variant Perception’s chart below:
Chart 5: Excess liquidity should also boost commodity prices
Crude oil prices have certainly bounced from the lows, with Brent crude hovering just under $42/barrel at present. But I am more interested in industrial metals such as copper and nickel, which I have mentioned before, as they are not only geared to economic recovery (particularly in China), but are also exposed to a structural growth trend in hybrid and electric car demand.
Chart 6: Copper price back to pre-COVID levels
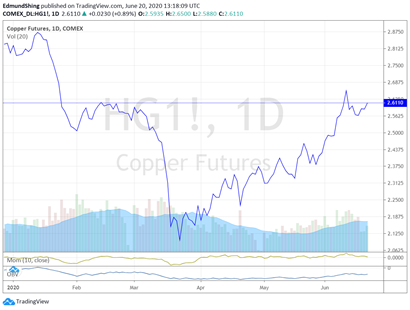
Mining mega-caps like Rio Tinto have already performed very well, but a further rally in industrial metals could give mining laggards like Glencore a helping hand.
Favoured Regions: Russia
A natural country to look at when discussing commodities is Russia, with heavy exposure to oil & gas, nickel and other commodities in their stock market.
The Russian ruble has been performing well against the US dollar of late, reflecting perhaps the recovery in oil price and thus in oil revenues for the Russian economy, despite the quota reductions in oil production volumes.
Chart 7: Ruble continues to recover against the USD

This has been reflected in the stronger performance of the JPMorgan Russia investment trust (JRS) of late:
Chart 8: JPMorgan Russia rallies further
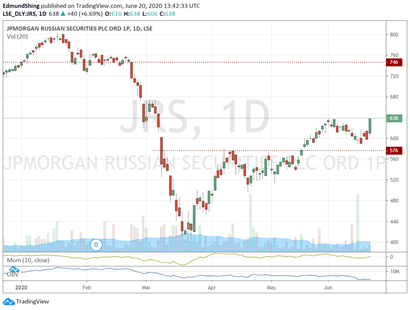
But there is still a fair way to go before JRS returns to its pre-COVID level of around 750p.
Leading Themes: Videogames/eSports, Cloud Computing, Biotech
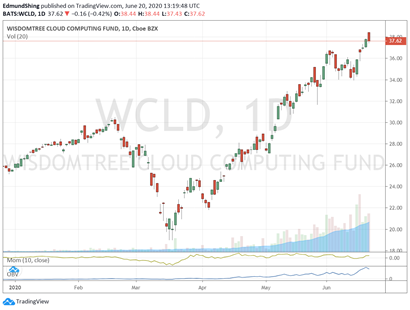
In leading themes for this week, technology still features heavily in the form of two evident COVID lockdown winners – Videogames & eSports, and Cloud Computing. The Wisdomtree Cloud Computing ETF (WCLD) is very US-centric, holding companies such as Zoom Video Comms, Shopify and Cloudflare amongst others.
Chart 9: Cloud Computing remains in vogue
In the Health care space that has been so strong all throughout this year, Biotech is now shining in particular, with the Biotech Growth Trust (BIOG) a good example:
Chart 10: Biotech Growth Trust at highs
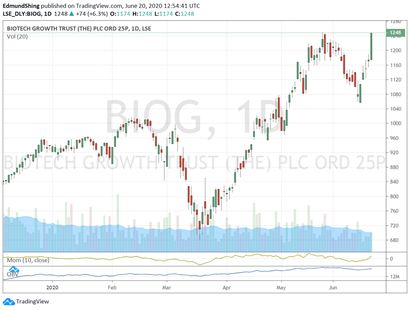
Companies such as Regeneron (REGN) are leading the way here, as they begin testing a Coronavirus antibody cocktail therapy, a combination of two different antibodies.
In contrast, the Banks sector remains in the doghouse despite all the central bank liquidity, as worries remain over the level of bad debts they will suffer from failing companies, not to mention the lack of dividends as they are banned by regulators from paying any until next year.
Have a good week,
Edmund
Disclaimer
This is not financial advice. Our content is intended to be used and must be used for information and education purposes only. Please read our disclaimer and terms and conditions to understand our obligations.
4 comments
Hi Edmund
A useful piece, thanks.
Perhaps a companion piece from Howard Marks of Oaktree Capital examining the Feb to Jun market fall and rise. Quite a long read but useful reflection on the past weeks.
https://www.oaktreecapital.com/docs/default-source/memos/the-anatomy-of-a-rally.pdf
Regards
Howard
Thanks Howard. A useful piece by Howard Marks. My takeaway on it is that people like Stan Druckenmiller and David Tepper see the S&P 500 as grossly overvalued because we're in a time of irrational exuberance and many investors seem to think prices will keep going up forever. Comparisons have been drawn with the markets of 1999. Might be wise to keep some of the portfolio in cash to benefit from the next inevitable correction.
Thank you Howard.
I want to bump this article too:
"Perhaps a companion piece from Howard Marks of Oaktree Capital examining the Feb to Jun market fall and rise. Quite a long read but useful reflection on the past weeks."
https://www.oaktreecapital.com/docs/default-source/memos/the-anatomy-of-a-rally.pdf
Its terrifying in its implications.
Excellent as always, Edmund. Many thanks.